
 Europe Built-In Coffee Machine Market | 2026-2036
Europe Built-In Coffee Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Built-In Coffee Machine Market Foresight
Market Context
Specialist kitchen retail channels is rewriting how built-in coffee machines reach European consumers, with showroom-based specification replacing traditional appliance retail. Jura Elektroapparate AG leverages its Swiss engineering heritage to dominate premium residential installations. Franke GmbH anchors the commercial and hospitality segment through its professional-grade integrated systems. De'Longhi S.p.A. competes across multiple price tiers with flexible product architectures suited to both retrofit and new-build kitchen projects.
Technical Definition and Segment Structure
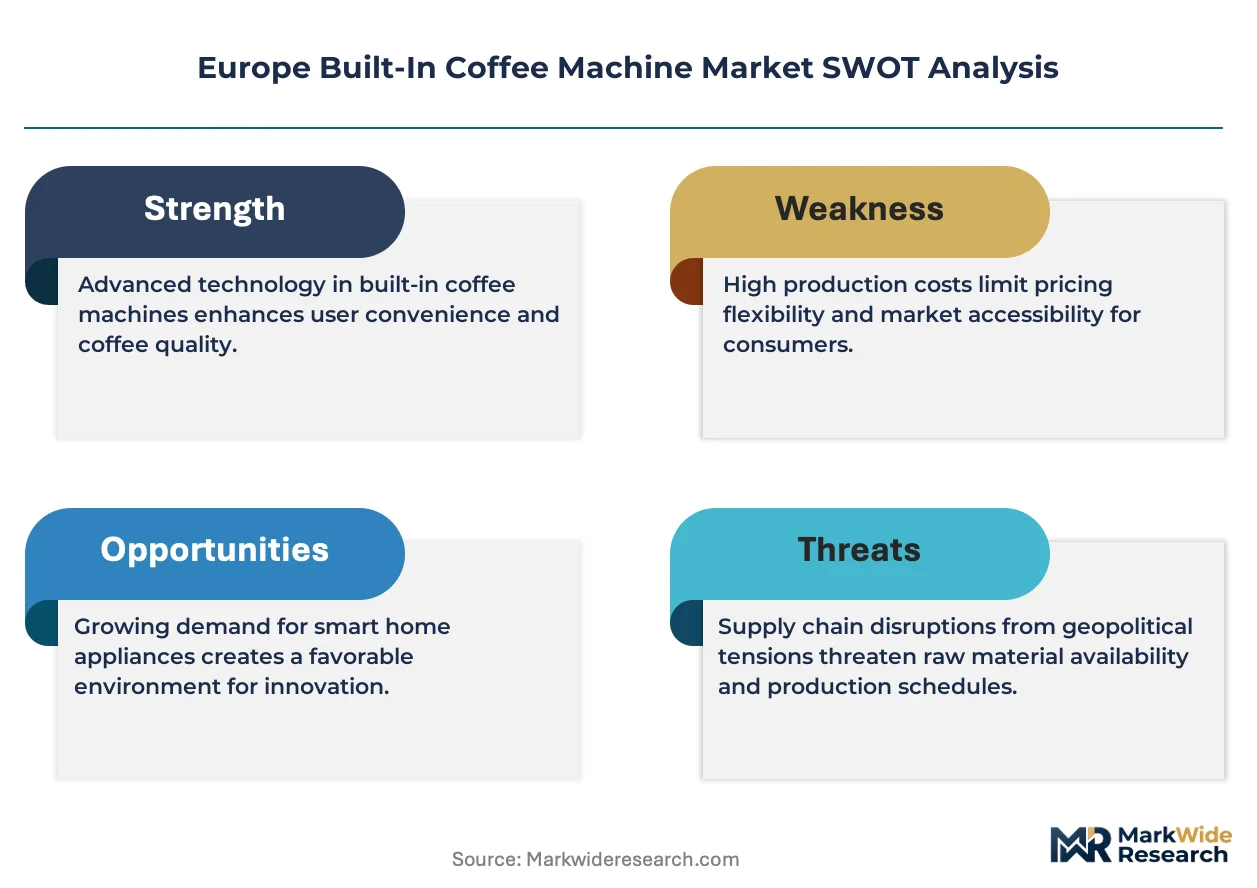
Built-in coffee machines are permanently installed appliances designed to integrate seamlessly into kitchen cabinetry, typically operating at 220-240V with pump pressures of 15-19 bar for espresso extraction and incorporating conical burr grinders with steel or ceramic mechanisms. These systems serve residential and commercial environments where space optimization and aesthetic continuity with surrounding cabinetry represent primary design constraints. Espresso machines and fully automatic control mechanisms command the dominant share of value, reflecting European consumer preference for bean-to-cup freshness and one-touch operation. Multi-function coffee centers represent the fastest-expanding product type as households consolidate multiple beverage preparation devices into single integrated units. Smart control mechanisms, though currently nascent, concentrate emerging margin pools through app connectivity and predictive maintenance subscription models.
Regulatory Framework and Outlook
The EU Ecodesign Directive and CE marking requirements shape product development trajectories, mandating standby power limits and material recyclability thresholds that filter non-compliant manufacturers from continental distribution. Germany's KBA-adjacent energy efficiency frameworks and France's AGEC anti-waste law extend these obligations toward extended producer responsibility and repairability indexing. REACH compliance constrains material selection for internal brewing components, particularly affecting sealants and heating element coatings. Stakeholders must monitor evolving EU appliance repairability scoring and the F-Gas Regulation's potential extension to small refrigeration circuits in milk cooling systems.
Market Dynamics
The EU Ecodesign Directive is compressing manufacturer margins while accelerating consolidation toward energy-efficient platforms, forcing redesign of heating systems and standby power architectures across European production lines.
Growth Catalysts
- Germany's premium housing sector:New-build kitchen specifications increasingly mandate integrated coffee systems as standard fittings in luxury residential developments, creating specification lock-in for appliance manufacturers.
- REACH compliance evolution:Tightening chemical safety standards for sealants and heating element coatings are filtering non-compliant suppliers from continental distribution, opening shelf space for certified incumbents.
- Bean-to-cup freshness preference:European consumer demand for one-touch operation with conical burr grinder integration is pulling upgrade cycles from manual espresso toward fully automatic built-in platforms.
Market Restraints
- Steel and ceramic grinder mechanism costs:Volatility in precision-machined component pricing constrains margin flexibility for mid-tier product lines.
- Technical limitation in milk cooling miniaturization:F-Gas Regulation coverage uncertainty for small refrigeration circuits complicates R&D roadmaps for multi-function coffee centers with integrated milk systems.
- Substitution from countertop premium machines:Jura Elektroapparate AG's freestanding Swiss-engineered units retain upgrade appeal in retrofit kitchen projects where cabinetry modification costs prove prohibitive.
Strategic Opportunities
- France's AGEC anti-waste law:Extended producer responsibility mandates and repairability indexing create first-mover advantage for manufacturers designing modular, field-serviceable brewing platforms.
- Smart control convergence:App connectivity layered with predictive maintenance subscriptions is digitizing aftermarket revenue streams beyond hardware margins.
- Italy's design-led kitchen renovation wave:Aesthetic continuity demands in Milan and Rome luxury residential clusters favor fully integrated cabinetry solutions over visible appliances.
Industry Challenges
- CE marking timeline compression:Evolving standby power limit testing protocols extend certification cycles, delaying product launches across multiple national approval bodies.
- Integration complexity with legacy 220-240V electrical:Retrofit installations in older European housing stock require costly electrical upgrades, limiting addressable market in renovation segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Built-In Coffee Machine Market |
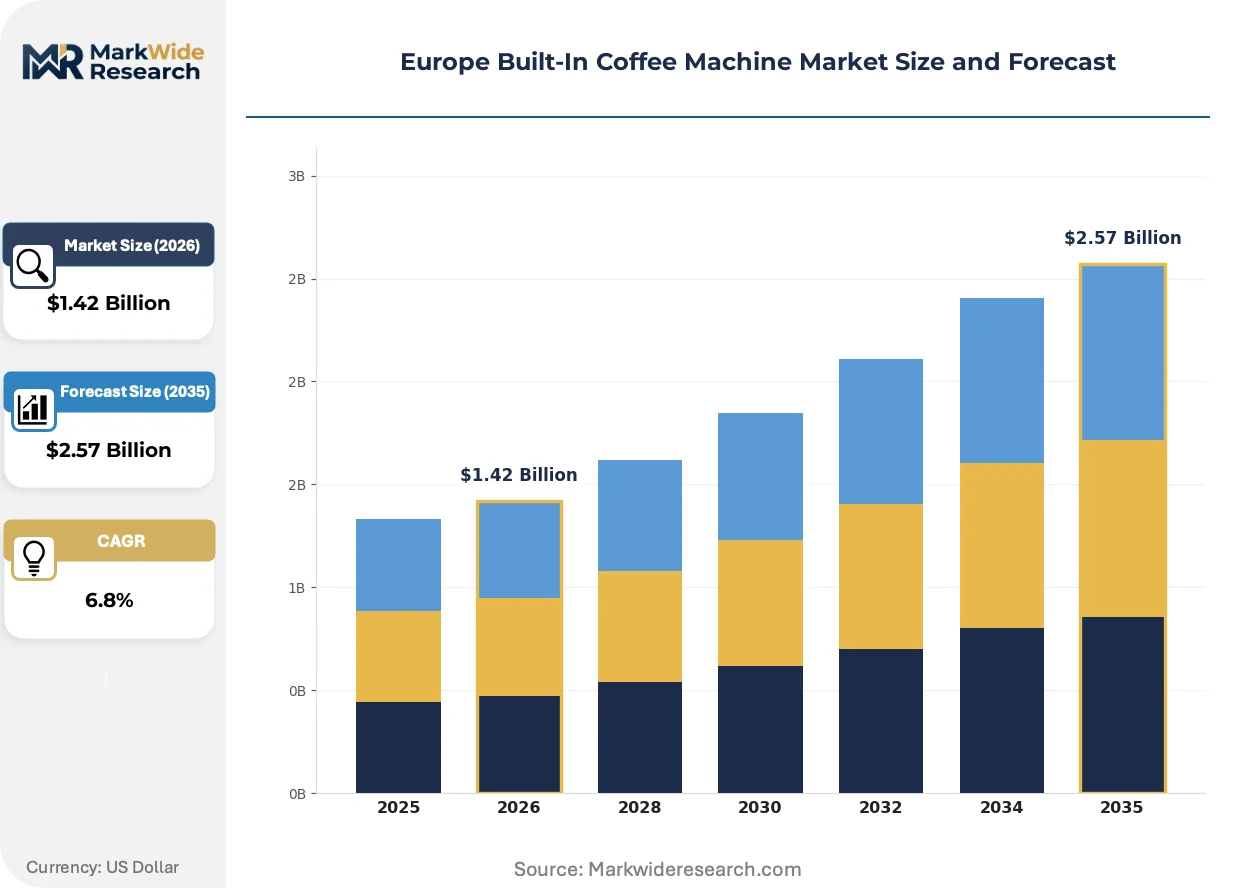
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Espresso Machines, Drip Coffee Makers, Cappuccino Machines, Multi-Function Coffee Centers Installation Type: Wall-Mounted, Under-Counter, Countertop, Integrated Control Mechanism: Manual, Semi-Automatic, Fully Automatic, Smart End User: Residential, Commercial, Hospitality, Offices |
| Companies Covered | Jura Elektroapparate AG, Franke GmbH, De'Longhi S.p.A., Nestlé Nespresso SA, Koninklijke Philips N.V., Miele & Cie. KG, WMF Group GmbH, LaCimbali S.p.A., BSH Hausgeräte GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Built-In Coffee Machine Market Shifts & Advancements
Kitchen specification practices are shifting from retail-driven selection toward architect-and-developer-controlled procurement, compressing traditional appliance distribution channels and elevating showroom-based technical consultation.
Touchscreen interface technology with programmable user profiles is digitizing the brewing experience, allowing households to store personalized extraction parameters. High-end residential developers in Hamburg and Munich are specifying these interfaces as standard in smart-home-integrated kitchen packages. The technology is digitizing competitive differentiation away from mechanical reliability toward software ecosystem stickiness and updateable feature roadmaps.
The EU F-Gas Regulation's potential extension to small refrigeration circuits is forcing redesign of milk cooling subsystems in multi-function coffee centers. Manufacturers must evaluate alternative cooling technologies or risk product line obsolescence. Germany's KBA-adjacent energy efficiency frameworks are most affected, with domestic producers accelerating R&D partnerships with industrial refrigeration specialists.
Architects and interior designers now control built-in coffee machine specification for luxury residential projects, displacing end-consumer retail choice. Specialist kitchen studios in Paris and Frankfurt are capturing this influence through exclusive distribution partnerships with premium manufacturers. This channel concentration is most visible in Germany's premium housing sector, where developer bulk procurement now exceeds individual retail volume for integrated kitchen packages.
Europe Built-In Coffee Machine Market Segmentation
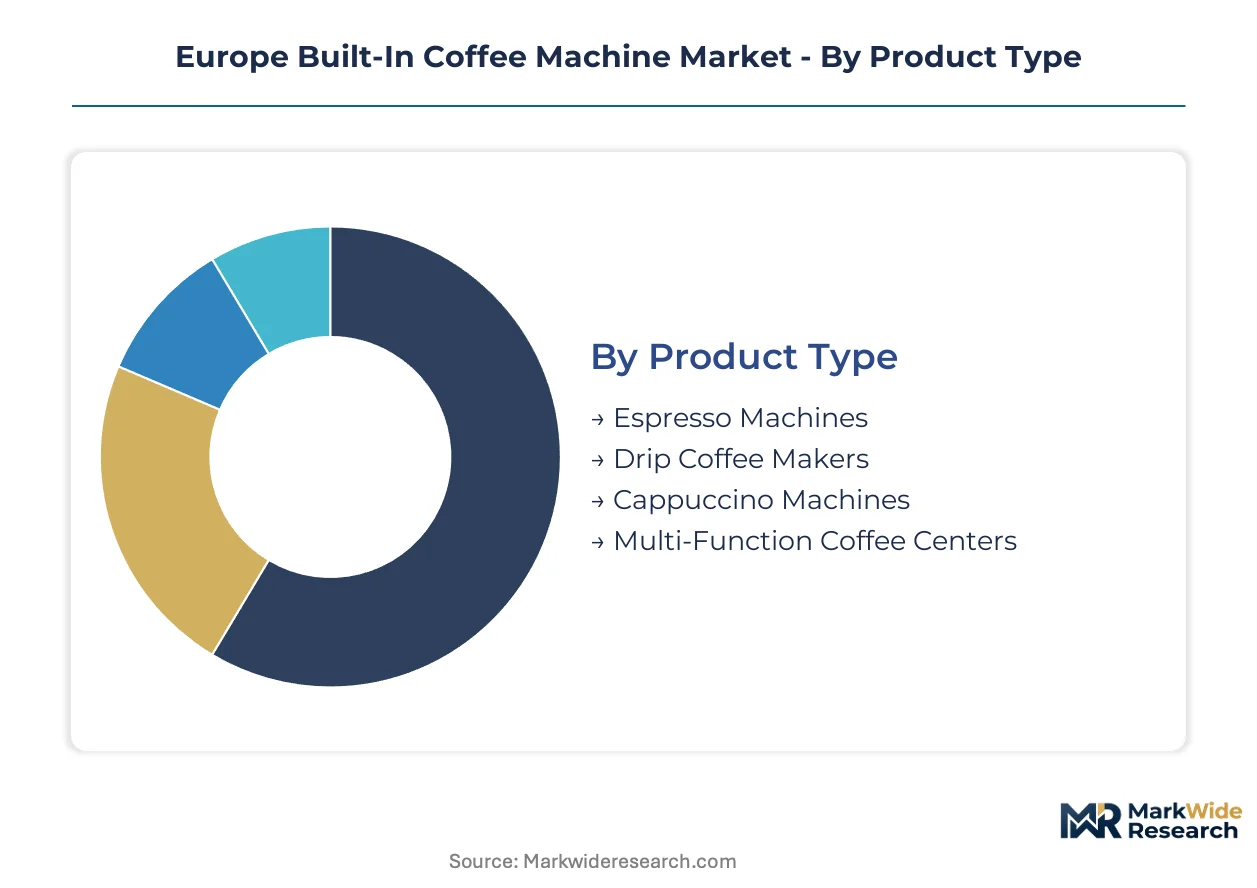
Built-in coffee machine segmentation reveals how technical specifications and installation constraints reshape procurement patterns across European residential and commercial channels. Product architecture decisions cascade through control mechanism selection and end-user requirements, creating distinct margin pools for manufacturers.
Product Type:
Cost tier differentiation separates premium extraction systems from volume-oriented brewing platforms, with grinder mechanism quality and pressure architecture defining price positioning.
- Espresso Machines:These systems operate at 15-19 bar pump pressure with conical burr grinders in steel or ceramic configurations. Demand concentrates in Germany's premium housing sector where developer specifications mandate integrated espresso platforms for luxury kitchen packages.
- Multi-Function Coffee Centers:Consolidating multiple beverage preparation devices into single cabinetry-integrated units, these systems incorporate milk cooling subsystems and programmable extraction profiles. Milan and Rome luxury residential clusters are rotating toward these platforms as households seek to reduce countertop appliance clutter.
- Drip Coffee Makers:Simpler brewing architectures targeting volume-oriented residential users and office break rooms across France and Benelux markets.
- Cappuccino Machines:Specialized milk-frothing systems with dedicated steam wands, finding niche adoption in hospitality environments requiring theatrical beverage preparation.
Espresso machines hold installed capacity. Multi-function coffee centers are rotating up the share rankings.
Installation Type:
Application context determines physical integration constraints, with new-build versus retrofit project economics driving specification divergence.
- Integrated:Seamless cabinetry embedding with flush panel alignment and shared ventilation systems. Hamburg and Munich developers specify these as standard in smart-home kitchen packages, creating specification lock-in for appliance manufacturers serving Germany's premium housing sector.
- Under-Counter:Compact chassis designs fitting standard European base cabinet dimensions, appealing to Paris and Frankfurt kitchen studios managing renovation projects with existing cabinetry constraints.
- Wall-Mounted:Vertical installation architectures for space-constrained urban apartments, gaining traction in Milan residential clusters.
- Countertop:Semi-permanent placement with dedicated power and water connections, serving retrofit segments where full cabinetry modification proves cost-prohibitive.
Integrated systems hold installed capacity. Under-counter configurations are rotating up the share rankings.
Control Mechanism:
Customer type sophistication spans from enthusiast-operated manual systems to unattended smart-connected platforms, with margin structure inverting toward digital subscription models.
- Fully Automatic:One-touch bean-to-cup operation with integrated grinding, tamping, and extraction sequencing. Residential demand across Italy and France favors these platforms as upgrade cycles shift from manual espresso toward convenience-oriented automation.
- Smart:App connectivity with programmable user profiles, predictive maintenance alerts, and over-the-air feature updates. High-end developers in Germany are specifying these interfaces as standard, digitizing competitive differentiation toward software ecosystem stickiness.
- Semi-Automatic:User-controlled extraction timing with automated pressure delivery, retaining enthusiast appeal in specialty coffee segments.
- Manual:Lever-operated or direct-pressure systems for purist users, occupying niche premium positioning in design-led kitchen renovations.
Fully automatic systems hold installed capacity. Smart control mechanisms are rotating up the share rankings.
End User:
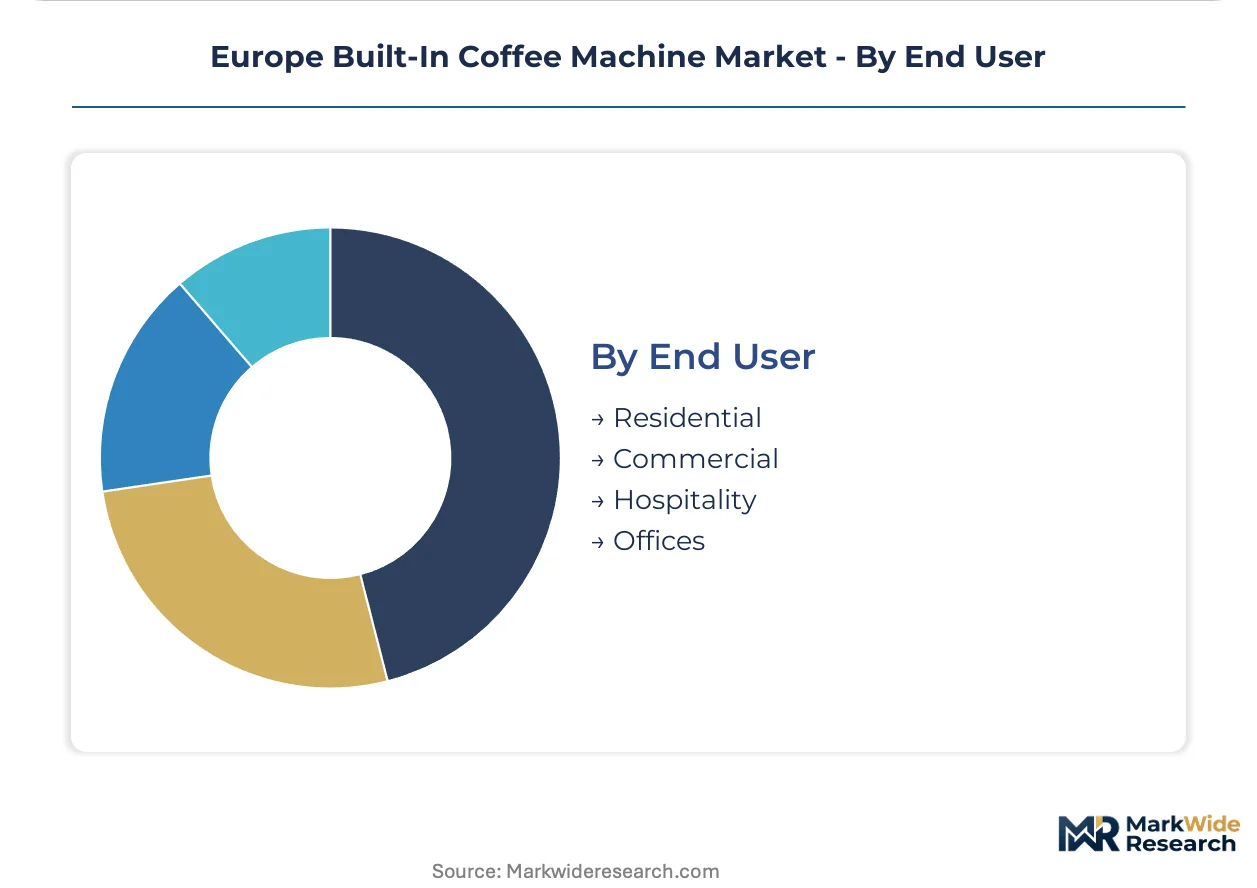
Volume concentration and procurement authority diverge sharply between residential specification channels and commercial hospitality procurement.
- Residential:Individual household installations through kitchen retail studios or developer bulk procurement. Germany's premium housing sector now sees developer bulk procurement exceeding individual retail volume for integrated kitchen packages.
- Hospitality:Hotels, restaurants, and cafés requiring professional-grade durability and rapid throughput. Franke GmbH anchors this segment through professional-grade integrated systems designed for continuous operation.
- Commercial:Non-hospitality business environments including retail and service establishments with moderate utilization requirements.
- Offices:Corporate break rooms and meeting facilities prioritizing unattended operation and low maintenance overhead.
Residential applications hold installed capacity. Hospitality procurement is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA-adjacent energy efficiency frameworks anchor Germany's regulatory environment for built-in coffee machines, establishing compliance baselines that cascade across neighboring markets. The EU Ecodesign Directive harmonizes standby power limits and material recyclability thresholds across the continent, though national implementations vary in enforcement intensity.
Germany
Hamburg and Munich developers specify integrated coffee systems as standard in smart-home kitchen packages, creating specification lock-in for appliance manufacturers. The KBA-adjacent frameworks mandate stringent standby power thresholds that filter non-compliant suppliers from domestic distribution. Bavaria's premium housing clusters concentrate developer bulk procurement exceeding individual retail volume for integrated kitchen packages.
France
Paris kitchen studios capture specification influence through exclusive distribution partnerships with premium manufacturers, displacing traditional retail channels. The AGEC anti-waste law imposes extended producer responsibility mandates and repairability indexing that favor modular, field-serviceable brewing platforms. Île-de-France luxury residential developments rotate toward multi-function coffee centers as households seek to reduce countertop appliance clutter.
Italy
Milan and Rome luxury residential clusters demand aesthetic continuity favoring fully integrated cabinetry solutions over visible appliances. REACH compliance evolution tightens chemical safety standards for sealants and heating element coatings, opening shelf space for certified incumbents. Lombardy's design-led kitchen renovation wave pulls upgrade cycles from manual espresso toward fully automatic built-in platforms.
Switzerland
Swiss engineering heritage commands premium positioning in residential installations across Alpine markets. Swissmedic-adjacent quality frameworks influence CE marking preparation for manufacturers targeting continental distribution. Zurich and Geneva high-end housing specifications increasingly mandate integrated coffee systems with conical burr grinder mechanisms.
United Kingdom
London and Southeast England kitchen retail channels shift toward architect-and-developer-controlled procurement, compressing traditional appliance distribution. The UK's post-EU regulatory alignment maintains Ecodesign Directive standby power limits through retained EU law mechanisms. Midlands renovation projects face integration complexity with legacy electrical infrastructure, limiting addressable market in retrofit segments.
Europe Built-In Coffee Machine Market Competitive Landscape
Swiss-engineered specialists and Italian design-led fabricators split the market along premium convenience versus aesthetic integration vectors. The vendor base concentrates around three strategic archetypes: heritage engineering houses leveraging technical reputation for developer specification lock-in, diversified appliance conglomerates spanning multiple price tiers through flexible product architectures, and professional-grade systems specialists anchoring hospitality procurement channels. Dominant competitive moves include exclusive distribution partnerships with specialist kitchen studios and R&D alliances with industrial refrigeration specialists addressing F-Gas Regulation uncertainty.
Within the heritage engineering tier, Jura Elektroapparate AG exemplifies Swiss precision positioning that dominates premium residential installations through showroom-based technical consultation. Franke GmbH occupies the professional-grade anchor position, representing the hospitality segment specialization visible in continuous-operation system design. De'Longhi S.p.A. sits within the diversified tier, exemplifying flexible product architectures suited to both retrofit and new-build kitchen projects across multiple European price bands.
| Leading Market Players |
|---|
| Jura Elektroapparate AG |
| Franke GmbH |
| De'Longhi S.p.A. |
| Nestlé Nespresso SA |
| Koninklijke Philips N.V. |
| Miele & Cie. KG |
| WMF Group GmbH |
| LaCimbali S.p.A. |
| BSH Hausgeräte GmbH |
| Others |
Supply & Pricing Matrix
German precision-machined component suppliers for conical burr grinder mechanisms anchor upstream margin capture, concentrating pricing power with steel and ceramic mechanism specialists who feed tier-one appliance assemblers across Alpine and Mediterranean manufacturing zones.
Pricing Analysis
Swiss-engineered units command premium positioning against Italian and German competitors, with price spreads widening based on grinder mechanism certification grade and smart connectivity bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies around conical burr material quality and pressure architecture sophistication. Cost compression in mid-tier product lines intensifies because steel grinder mechanism volatility constrains margin flexibility. Developer bulk procurement in Germany's premium housing sector shows least price sensitivity, while Paris kitchen studio renovation clients exhibit highest elasticity to cabinetry modification costs.
Supply Chain Analysis
Extended payment terms from German appliance OEMs to Swiss and Italian component suppliers characterize upstream financing structures, compressing working capital cycles for precision-machined grinder mechanism specialists. Manufacturing concentrates in Germany, Switzerland, and Italy, with conical burr grinders, heating element coatings, and pump pressure systems drawing from specialized regional metalworking clusters. Single-source vulnerability around REACH-compliant sealant formulations threatens production continuity as chemical safety standards tighten. Distribution runs through specialist kitchen studios and developer procurement channels, displacing traditional appliance retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscription layers expand faster than hardware sales as smart-connected platforms digitize aftermarket revenue, transforming built-in coffee machines from capital goods into service-attach opportunities with recurring telemetry-based income streams.
For Market Incumbents: Entrench specification lock-in through exclusive distribution partnerships with Hamburg and Munich developers, while accelerating backward integration into conical burr grinder mechanism production to offset steel and ceramic cost volatility. Counter Jura Elektroapparate AG's freestanding substitution threat by embedding predictive maintenance APIs that create switching costs for smart-home-integrated installations. For New Entrants and Emerging Players: Pursue under-counter retrofit configurations in Paris and Frankfurt kitchen studios, where legacy cabinetry constraints exclude integrated system incumbents. White-space concentrates in France's AGEC repairability-mandated modular platforms, with field-serviceable brewing architectures offering first-mover positioning against sealed-unit heritage brands. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diversified appliance conglomerates lacking smart connectivity roadmaps, presenting carve-out opportunities for industrial IoT specialists. Five-to-ten-year viability hinges on F-Gas Regulation resolution for milk cooling miniaturization. Watch CE marking timeline compression as inflection indicator for certification-constrained product launch delays.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Transforms hardware margins into recurring revenue through telemetry-enabled service tiers. |
| REACH-Compliant Sealant Backward Integration | Captures margin pool while filtering non-compliant competitors from continental distribution. |
| Smart-Home Platform Integration Partnership | Locks in developer specifications through Hamburg and Munich smart-kitchen package mandates. |
| Modular Field-Serviceable Architecture Development | Aligns product roadmaps with France's AGEC repairability indexing requirements. |
| Industrial Refrigeration R&D Alliance | Addresses F-Gas Regulation uncertainty for multi-function coffee center milk cooling systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with appliance R&D directors, kitchen studio procurement managers, developer specification leads, and regulatory compliance officers; and secondary validation through EU Ecodesign Directive filings, CE marking databases, KBA energy efficiency reports, and specialist kitchen retail audit data. Bottom-up unit economics triangulated against top-down market sizing across product type, installation configuration, control mechanism, and end-user segmentation dimensions.
Forecast inputs considered pump pressure architecture evolution, smart connectivity adoption curves, and developer bulk procurement penetration across the projection horizon. Segment-level CAGRs derived from installation type rotation rates, control mechanism upgrade cycles, and regulatory compliance cost pass-through assumptions. Modeling incorporated REACH chemical safety timeline impacts, F-Gas Regulation coverage uncertainty for small refrigeration circuits, and AGEC repairability mandate implementation schedules.
Sensitivities concentrate around CE marking protocol evolution, steel and ceramic grinder mechanism cost trajectories, and smart-home platform standardization outcomes. Forecasts reflect documented assumptions on regulatory enforcement intensity and developer specification persistence. Macroeconomic contraction in Germany's premium housing sector, accelerated F-Gas Regulation extension, or breakthrough countertop machine performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
Household Kitchen Appliances Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Russia Household Electric Grill Market