
 Range Cooker Market | 2026-2036
Range Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Range Cooker Market Outlook
Multi-source component procurement is hardening across the range cooker supply chain as manufacturers buffer against semiconductor and steel price volatility. GE Appliances leverages its captive logistics network to sustain North American distribution density. SAMSUNG anchors its position through R&D intensity in smart-kitchen connectivity modules. VIKING RANGE, LLC specializes in professional-grade configurations that dominate the premium segment through dealer-channel control.
A range cooker is a freestanding or built-in cooking appliance combining one or more ovens with a stovetop surface, typically fabricated from stainless steel or enamel-coated steel with burner outputs ranging from 15,000 to 23,000 BTU on gas configurations. The unit serves residential and commercial kitchens requiring simultaneous multi-zone cooking capacity with integrated oven functionality. Induction and dual fuel product types command expanding margin pools as energy efficiency standards tighten across major markets. The 36-inch and 48-inch size segments lead volume while custom-size installations capture the highest per-unit profitability in hospitality and luxury residential end-user categories.
The US Department of Energy appliance efficiency standards and the EU Ecodesign Directive shape product development trajectories by mandating reduced standby power consumption and improved combustion efficiency. The EPA ENERGY STAR certification and CE marking requirements filter market access for imported units across North America and Europe. Stakeholders must monitor evolving refrigerant and insulation material restrictions under REACH and state-level California energy codes that cascade into national design specifications.
Market Dynamics
Energy efficiency mandates across Germany and the United Kingdom are compressing product development cycles while induction technology captures preference share from conventional gas configurations. Manufacturers face simultaneous pressure to reduce standby power consumption and maintain burner output performance.
Growth Catalysts
- EU Ecodesign Directive:Mandates for reduced standby power consumption force technology upgrades that differentiate compliant products in retail channels.
- Residential kitchen renovation spending:Metropolitan households in North American and Western European markets prioritize professional-grade cooking appliances with dual-fuel flexibility.
- Induction technology:Superior thermal efficiency and precision control accelerate replacement cycles in energy-conscious consumer segments.
Market Restraints
- Semiconductor and steel price volatility:Multi-source component procurement hardens as manufacturers buffer against input cost swings.
- REACH compliance costs:Evolving restrictions on refrigerants and insulation materials cascade into design specification revisions.
- Induction cooktop infrastructure requirements:Electrical panel upgrades in older residential stock limit addressable market penetration.
Strategic Opportunities
- Smart-kitchen connectivity modules:Integration of IoT-enabled diagnostics and remote control functions opens premium pricing tiers.
- Custom-size hospitality installations:Non-standard dimensions for commercial kitchens command highest per-unit profitability.
- EPA ENERGY STAR certification:Voluntary efficiency benchmarks create retail differentiation and utility rebate eligibility pathways.
Industry Challenges
- Skilled technician shortage:Installation and service of dual-fuel and induction systems requires specialized electrical and gas certification.
- CE marking timeline compression:Conformity assessment procedures for imported units extend time-to-market for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Range Cooker Market |
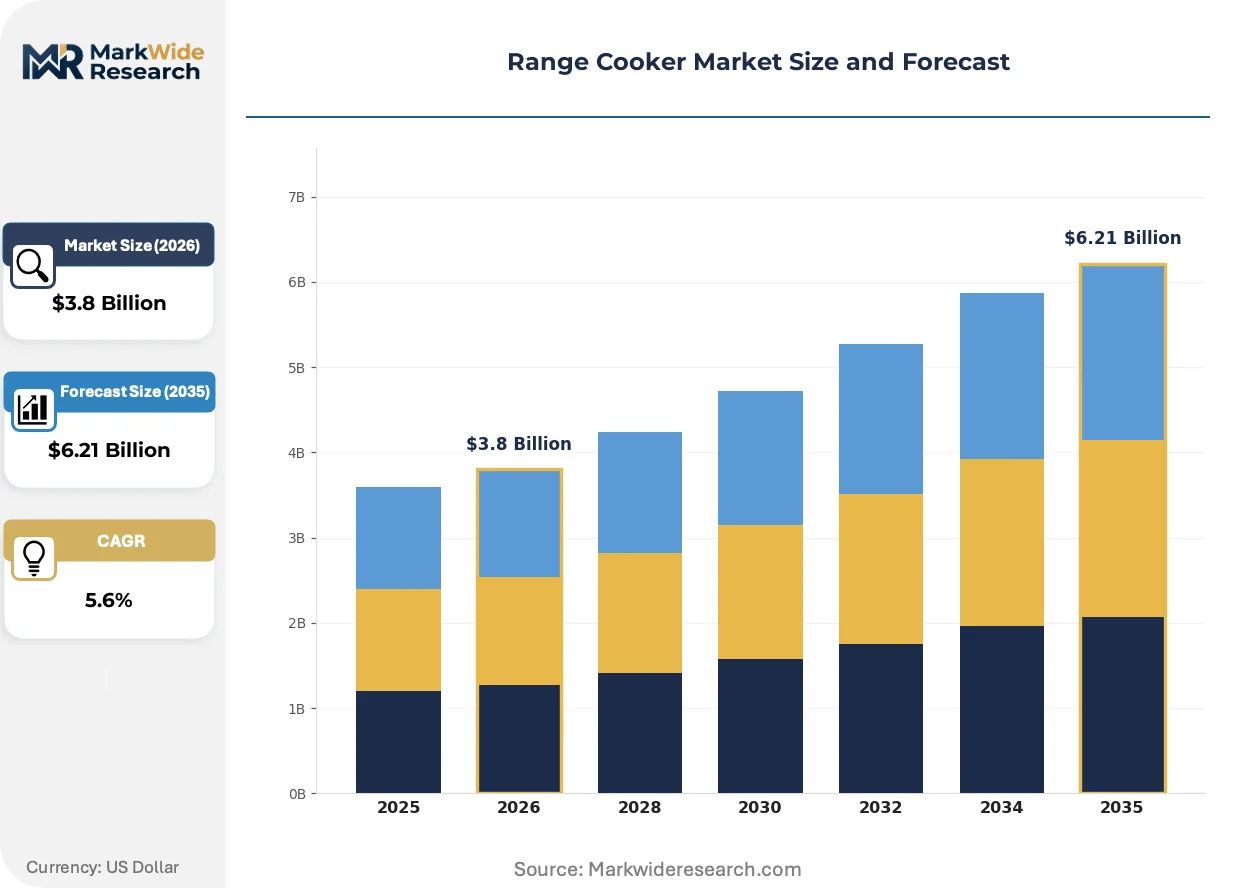
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas, Electric, Dual Fuel, Induction Size: 36-inch, 48-inch, 60-inch, Custom Size Installation Type: Freestanding, Built-in, Slide-in, Portable End User: Residential, Commercial, Hospitality, Culinary Schools |
| Companies Covered | GE Appliances, SAMSUNG, Amana, Whirlpool, LG Electronics, Frigidaire, VIKING RANGE, LLC, THERMADOR, Dacor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Range Cooker Market Strategic Shifts
Connectivity integration and precision thermal management are redefining competitive differentiation in professional-grade cooking appliances. Manufacturers invest in sensor arrays and algorithmic control systems that transform user interaction models.
Precision temperature sensing arrays are automating burner modulation across multiple cooking zones simultaneously. High-end residential buyers and hospitality operators adopt these configurations to reduce supervision requirements during complex meal preparation. The technology is automating skill transfer from professional chefs to home cooks.
California energy codes are cascading into national design specifications through manufacturer preference for unified product platforms. State-level mandates on combustion efficiency and insulation performance exceed federal minimums. Premium product lines absorb these requirements first, creating compliance templates for standard-tier releases.
Dealer-channel control is consolidating around experience-centric showrooms that bundle installation and extended service contracts. Independent appliance retailers cede ground to manufacturer-direct and builder-partnered distribution in new construction segments. This shift concentrates most visibly in Texas and Florida metropolitan markets where premium home construction sustains 48-inch and 60-inch model uptake.
Range Cooker Market Segmentation
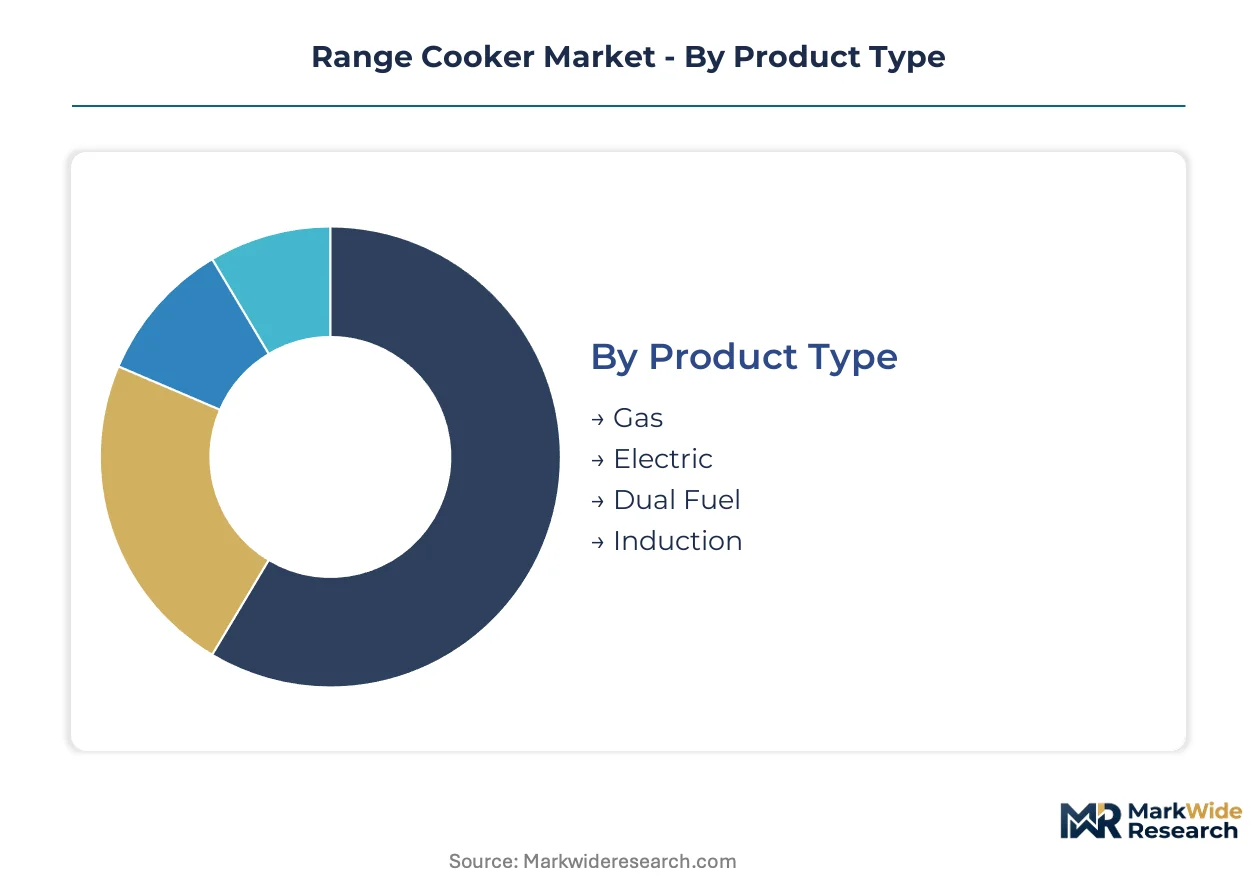
Range cooker purchasing decisions cascade from energy infrastructure constraints, spatial requirements, and end-use intensity. Buyers prioritize fuel compatibility with existing electrical panels or gas lines before evaluating feature sophistication. Segmentation reveals how professional-grade specifications migrate from commercial kitchens into luxury residential installations.
Product Type:
Energy efficiency mandates and retrofit compatibility dominate buyer evaluation sequences.
- Gas:Burner outputs spanning 15,000 to 23,000 BTU deliver immediate thermal response for searing and wok cooking. Demand concentrates in Texas and Florida metropolitan markets where premium home construction sustains uptake of professional-grade configurations. Natural gas infrastructure availability limits addressable penetration in older urban residential stock.
- Induction:Electromagnetic coil systems achieve superior thermal efficiency with precision control across multiple zones. Metropolitan households in Germany and the United Kingdom prioritize these configurations under tightening EU Ecodesign Directive mandates for reduced standby power consumption. Electrical panel upgrade requirements constrain replacement cycles in pre-1990 housing.
- Electric:Resistive coil or smooth-top radiant elements serve budget-conscious replacement cycles and rental property specifications.
- Dual Fuel:Combines gas burner responsiveness with electric oven thermal stability for hybrid cooking workflows.
Gas leads on scale; Induction leads on momentum.
Size:
Spatial planning and meal preparation volume determine dimensional selection hierarchies.
- 48-inch:Six-burner configurations with dual oven compartments accommodate simultaneous multi-zone cooking for entertainment-focused households. Hospitality operators and luxury residential end-users in North American metropolitan markets specify these dimensions for chef-style kitchen layouts. Custom cabinetry integration requirements elevate total installed cost premiums.
- 36-inch:Standard-width footprint balances burner density with kitchen spatial constraints in renovated urban residences. Builder-partnered distribution channels in Texas and Florida metropolitan markets specify these units for new premium construction. Volume manufacturing achieves cost efficiency that cascades into competitive retail positioning.
- 60-inch:Commercial-grade width supports griddle, grill, and auxiliary burner modules for professional kitchen specifications.
- Custom Size:Non-standard dimensions command highest per-unit profitability in hospitality and luxury residential end-user categories.
36-inch configurations anchor volume throughput; Custom dimensions capture margin concentration.
Installation Type:
Construction phase and renovation scope dictate installation methodology selection.
- Freestanding:Self-contained units with finished side panels enable flexible positioning without cabinetry modification. Residential renovation spending in Western European metropolitan markets favors these configurations for retrofit compatibility. Finished aesthetics on all sides permit island or peninsula placement without adjacent cabinet runs.
- Built-in:Flush integration with surrounding cabinetry delivers streamlined visual continuity for architect-specified kitchens. Premium home construction segments in Germany and the United Kingdom specify these installations for ENERGY STAR certification alignment. Precision dimensional tolerances require skilled technician coordination between appliance and millwork trades.
- Slide-in:Overlapping cooktop edges create seamless counter transitions with controlled side clearances.
- Portable:Castor-mounted or lightweight units serve temporary culinary school training stations and event catering operations.
Freestanding dominates replacement demand; Built-in gains share fastest in new construction.
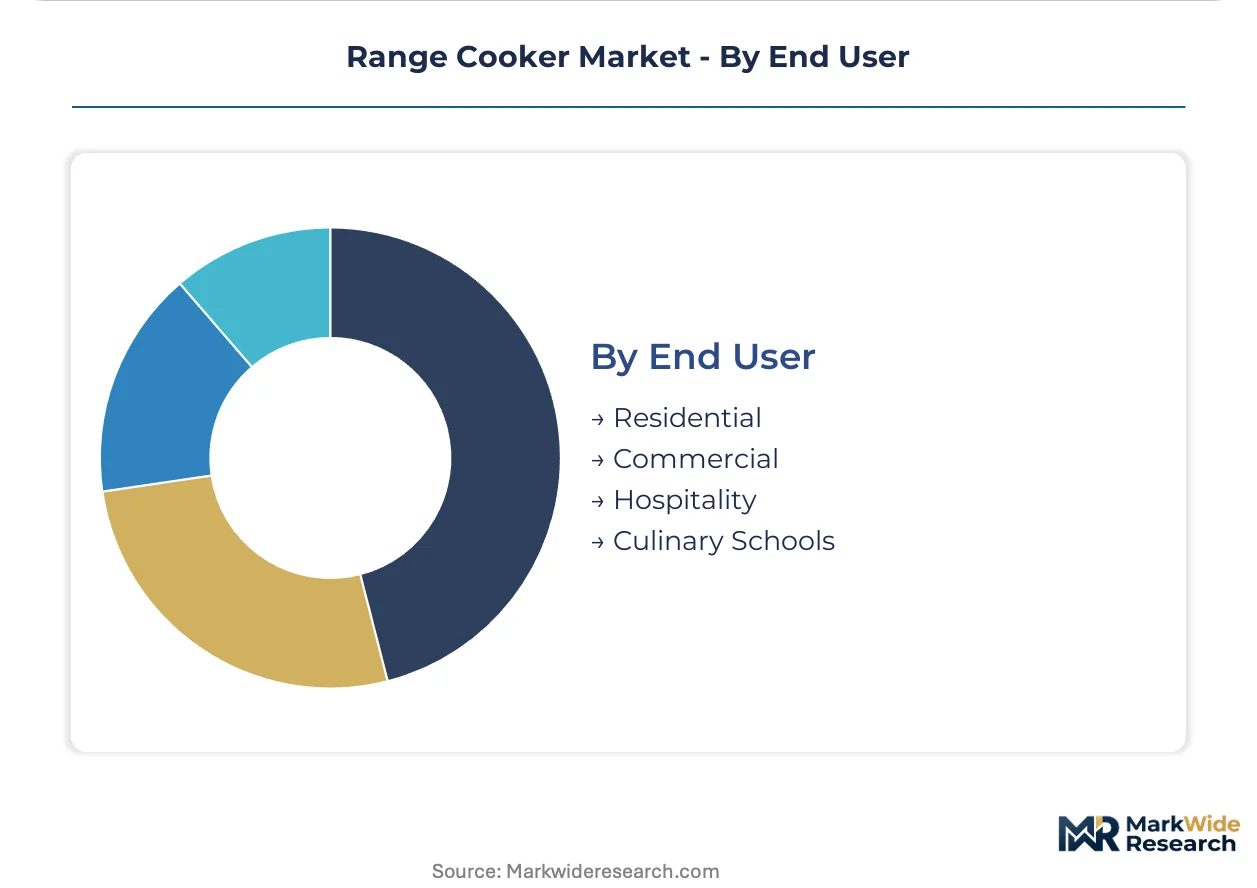
End User:
Intensity of use and performance durability requirements segment demand across institutional and private applications.
- Residential:Metropolitan households prioritize professional-grade aesthetics with connectivity-enabled diagnostics for remote monitoring. Kitchen renovation spending concentrates in North American and Western European markets where dual-fuel flexibility commands premium positioning. Smart-kitchen integration modules differentiate product tiers for tech-adopter segments.
- Hospitality:Hotels and resorts specify custom-size installations with precision temperature sensing arrays for consistent batch preparation. Non-standard dimensions and extended service contract bundling command highest per-unit profitability across all end-user categories. California energy code compliance cascades into national specifications for unified product platforms.
- Commercial:Independent restaurants and foodservice operations require certified combustion efficiency under EPA and CE marking requirements.
- Culinary Schools:Training institutions demand durable, standardized configurations for skill transfer replication across student cohorts.
Residential anchors volume scale; Hospitality leads on per-unit margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas metropolitan corridor anchors premium range cooker demand through sustained luxury home construction and professional-grade kitchen specifications. Residential renovation spending concentrates in Germany and the United Kingdom where EU Ecodesign Directive mandates accelerate induction technology replacement cycles.
United States
Texas and Florida metropolitan markets sustain 48-inch and 60-inch model uptake through premium home construction pipelines. The EPA ENERGY STAR certification filters retail channel access while creating utility rebate eligibility for compliant units. Builder-partnered distribution channels in Dallas-Fort Worth and Houston specify dual-fuel configurations for new luxury residential developments.
Germany
Metropolitan households in Berlin and Munich prioritize induction technology under tightening EU Ecodesign Directive standby power consumption mandates. The country's national energy regulator enforces reduced combustion efficiency thresholds that compress product development cycles. Baden-Württemberg industrial clusters host precision thermal management component fabrication for smart-kitchen connectivity modules.
United Kingdom
London and Southeast England residential renovation spending channels toward professional-grade cooking appliances with dual-fuel flexibility. CE marking requirements for imported units extend conformity assessment timelines for new product introductions. Manchester and Birmingham metropolitan areas concentrate dealer-channel showrooms bundling installation with extended service contracts.
Canada
Ontario and British Columbia markets align with California energy code specifications that cascade into national design requirements through unified product platforms. Health Canada's national appliance efficiency program mandates reduced standby power consumption matching US Department of Energy standards. Toronto and Vancouver metropolitan construction segments specify built-in installations for architect-designed luxury kitchens.
France
Île-de-France and Auvergne-Rhône-Alpes regions exhibit accelerating induction cooktop preference among energy-conscious consumer segments. The country's national environmental regulator enforces REACH compliance restrictions on insulation materials that cascade into design specification revisions. Lyon and Marseille hospitality operators specify custom-size installations with precision temperature sensing arrays for consistent batch preparation.
Range Cooker Market Competitive Environment
Global majors compete with regional champions across distribution density and smart-kitchen technology integration. The vendor base stratifies into three tiers: diversified appliance conglomerates with captive logistics networks, premium specialists controlling dealer-channel relationships, and mid-scale fabricators serving renovation replacement cycles. Strategic archetypes include scale-driven platform players, connectivity-technology integrators, and professional-grade configuration specialists. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers buffer semiconductor and steel input volatility.
Within the diversified conglomerate tier, GE Appliances and SAMSUNG exemplify scale-driven platform strategies with captive supply chain infrastructure and R&D intensity in smart-kitchen modules. VIKING RANGE, LLC occupies a position representing the professional-grade specialist archetype through dealer-channel control and premium segment focus. These three anchors illustrate how competitive positioning diverges across logistics integration, technology licensing, and channel specialization vectors.
| Leading Market Players |
|---|
| GE Appliances |
| SAMSUNG |
| Amana |
| Whirlpool |
| LG Electronics |
| Frigidaire |
| VIKING RANGE, LLC |
| THERMADOR |
| Dacor, Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-tier bifurcation between ENERGY STAR-compliant premium configurations and baseline electric units manifests in both pricing power and sourcing complexity across the range cooker market. The EU Ecodesign Directive and California energy codes create compliance ladders that concentrate margin extraction in certified product lines while forcing multi-source procurement strategies for semiconductor and steel inputs.
Pricing Analysis
Input-cost pass-through from semiconductor and steel price volatility compresses margins most acutely in standard-tier electric configurations. Three-tier pricing structure across premium, standard, and economy levels separates dual-fuel professional-grade units from basic gas models, with ENERGY STAR certification and smart-kitchen connectivity modules commanding measurable premiums. Pricing pressure stems from REACH compliance costs cascading into insulation material revisions. Builder-partnered distribution channels exhibit lowest price sensitivity due to bundled installation contracts, while independent appliance retailers face highest margin compression.
Supply Chain Analysis
Direct-to-builder channels handle hyperscale demand from Texas and Florida metropolitan construction pipelines, while dealer-showroom networks service renovation replacement cycles in Germany and the United Kingdom. Component fabrication concentrates in China, South Korea, and Germany, with electromagnetic coil systems and precision thermal sensors drawing from specialized industrial clusters. Steel sheet and semiconductor inventories rest on volatile commodity pricing. Single-source vulnerability in smart-kitchen connectivity modules creates exposure to logistics chokepoints. Distribution runs through manufacturer-direct partnerships for new construction and independent retailer networks for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The range cooker market functions as a regulatory compounder where EU Ecodesign Directive mandates for standby power consumption and combustion efficiency create sustained technology upgrade demand across replacement cycles.
For Market Incumbents: Hedge against semiconductor price volatility through captive logistics network expansion and multi-source component procurement hardening. Prioritize backward integration into precision thermal management component fabrication in Baden-Württemberg industrial clusters. Defend dealer-channel relationships against manufacturer-direct encroachment by bundling extended service contracts with ENERGY STAR-certified installations. For New Entrants and Emerging Players: The 36-inch to 48-inch price-point gap between premium dual-fuel configurations and standard gas units offers white-space entry in metropolitan renovation segments. Target electrical panel upgrade constraints in pre-1990 housing stock with retrofit-compatible induction modules. Pursue hospitality custom-size specifications where non-standard dimensions command highest per-unit profitability. Lead with IoT-enabled diagnostics as a differentiated go-to-market angle for tech-adopter residential segments. For Investors and Strategic Acquirers: Consolidation pressure builds where regional mid-scale fabricators lack R&D intensity for smart-kitchen connectivity modules and face REACH compliance cost burdens. Long-term viability favors platforms with unified product architectures spanning multiple regulatory jurisdictions. Acquisition target archetype: professional-grade specialists with dealer-channel control but underinvestment in induction technology transition. Watch induction cooktop infrastructure penetration rates in older metropolitan housing stock as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Kitchen Connectivity Module Development | IoT-enabled diagnostics open premium pricing tiers in residential segments seeking remote monitoring capabilities. |
| Multi-Source Component Procurement Hardening | Buffering against semiconductor and steel volatility protects margin stability across product development cycles. |
| Dealer-Channel Experience Showroom Expansion | Bundled installation and service contracts defend against manufacturer-direct encroachment in premium construction segments. |
| Custom-Size Hospitality Installation Capability | Non-standard dimensions for commercial kitchens command highest per-unit profitability across all end-user categories. |
| EU Ecodesign Directive Compliance Investment | Reduced standby power certification filters retail access and creates utility rebate eligibility pathways in European markets. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with appliance manufacturer product managers, dealer-channel showroom operators, hospitality procurement directors, residential kitchen renovation contractors, and regulatory compliance officers with secondary validation. Secondary sources included EPA ENERGY STAR certification databases, EU Ecodesign Directive implementation reports, SEC 10-K filings from diversified appliance conglomerates, customs and trade data on steel and semiconductor imports, and California Energy Commission appliance efficiency standards. Bottom-up unit shipment modeling and top-down market value estimation triangulated to produce segmentation outputs.
Comparable historical reference periods anchored the forecast window to pre-pandemic baseline demand patterns and post-efficiency-mandate replacement cycle acceleration. Segmentation dimensions modeled include product type, size configuration, installation methodology, and end-user intensity across residential, hospitality, commercial, and culinary school categories. CAGRs derived from regression analysis against kitchen renovation spending indices, premium home construction permits in Texas and Florida metropolitan markets, and EU regulatory compliance timeline assumptions. Forecast inputs incorporated electrical panel upgrade penetration rates in pre-1990 housing and smart-kitchen module adoption curves.
Caveats apply where semiconductor supply chain disruptions, REACH material restriction expansions, or California energy code cascade effects into national specifications could materially shift the outlook. Forecasts reflect assumptions about continued metropolitan household prioritization of professional-grade cooking appliances and sustained premium home construction pipelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Popcorn Makers Market
Kitchen Appliances
Smart Kettle Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
Sweden Kitchen Appliances Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Russia Kitchen Appliances Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
Europe Major Home Appliances Market