
 Cake Pans Market | 2026-2036
Cake Pans Market Size, Share, and Industry Trends Forecast 2026-2036
Cake Pans Market Analytics
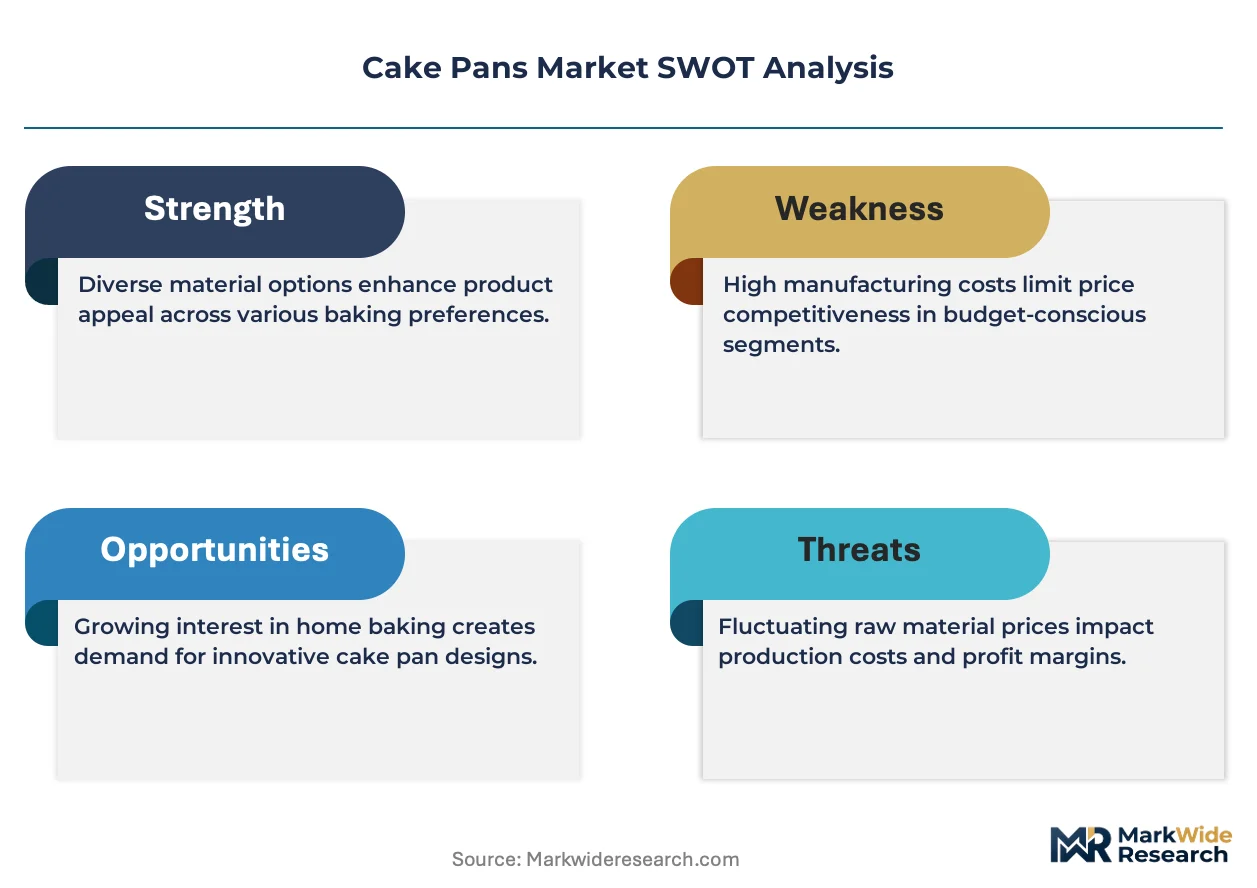
Silicone-based bakeware is recalibrating cost-performance tradeoffs across the cake pans category, displacing conventional aluminum in price-sensitive tiers while forcing premium metal producers to defend differentiation through thickness specifications and thermal conductivity claims. Nordic Ware sustains its position through die-cast aluminum specialization and Made-in-USA sourcing narratives. Wilton Brands anchors the mass-market channel through craft-store distribution and licensed character molds. USA Pan competes on commercial-grade aluminized steel construction targeting professional bakers and institutional buyers.
Cake pans are rigid or flexible containers engineered from aluminum, steel, silicone, or composite substrates with defined wall thickness, diameter tolerance, and heat distribution coefficients to shape batter during thermal processing in residential or commercial ovens. The aluminum segment dominates unit volumes due to thermal efficiency and cost structure, while silicone represents the fastest-growing material category driven by microwave compatibility and demolding convenience. Professional bakers and catering services command premium pricing tiers where durability certifications and NSF compliance separate margin pools from commoditized home-use alternatives.
The FDA governs indirect food-contact substances under 21 CFR 175.300, while the EU EFSA enforces migration limits on heavy metals and perfluorinated compounds in non-stick coatings, compelling manufacturers to reformulate surface treatments or risk market exclusion. BIS certification requirements in India and GB standards compliance in China create additional testing burdens for exporters seeking access to emerging volume markets. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as coating chemistry decisions made today will determine product eligibility in tomorrow's regulatory environment.
Market Dynamics
Social media baking content is compressing purchase cycles and fragmenting buyer loyalty across the cake pans category. Instagram and TikTok tutorials drive impulse trial of novel shapes and materials, while algorithmic discovery erodes traditional brand stickiness established through retail shelf placement.
Growth Catalysts
- Perfluorinated compound restrictions:EFSA migration limits on traditional non-stick coatings force manufacturers toward ceramic and silicone alternatives, accelerating material innovation cycles.
- Home baking resurgence:Post-pandemic retention of baking hobbies sustains replacement demand for specialized pans among residential consumers seeking professional results.
- Aluminum thermal efficiency:Commercial bakeries prioritize heat conductivity specifications in heavy-gauge aluminum, insulating this segment from silicone displacement.
Market Restraints
- Raw aluminum price volatility:Energy-intensive smelting costs squeeze margin structures for die-cast producers unable to pass through input fluctuations.
- Coating chemistry lock-in:PFAS reformulation timelines create inventory obsolescence risk for distributors holding legacy-treated stock across multiple jurisdictions.
- Silicone durability ceiling:Temperature tolerance limitations and structural deformation under sustained heat constrain adoption in commercial ovens exceeding standard residential specifications.
Strategic Opportunities
- India BIS certification pathway:Formal compliance with Bureau of Indian Standards unlocks access to emerging middle-class households upgrading from improvised baking vessels.
- Licensed entertainment IP convergence:Character-shaped molds tied to streaming content releases capture gift-market occasions and social media shareability.
- Direct-to-consumer subscription models:Curated seasonal pan collections bypass craft-store margin structures and build recurring revenue streams.
Industry Challenges
- Multi-jurisdiction coating compliance:Divergent PFAS phase-out schedules across FDA, EFSA, and state-level US regulations fragment product line rationalization.
- Legacy oven compatibility testing:Silicone and ceramic-coated variants require validation across non-standard residential oven cavity dimensions and heating element configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cake Pans Market |
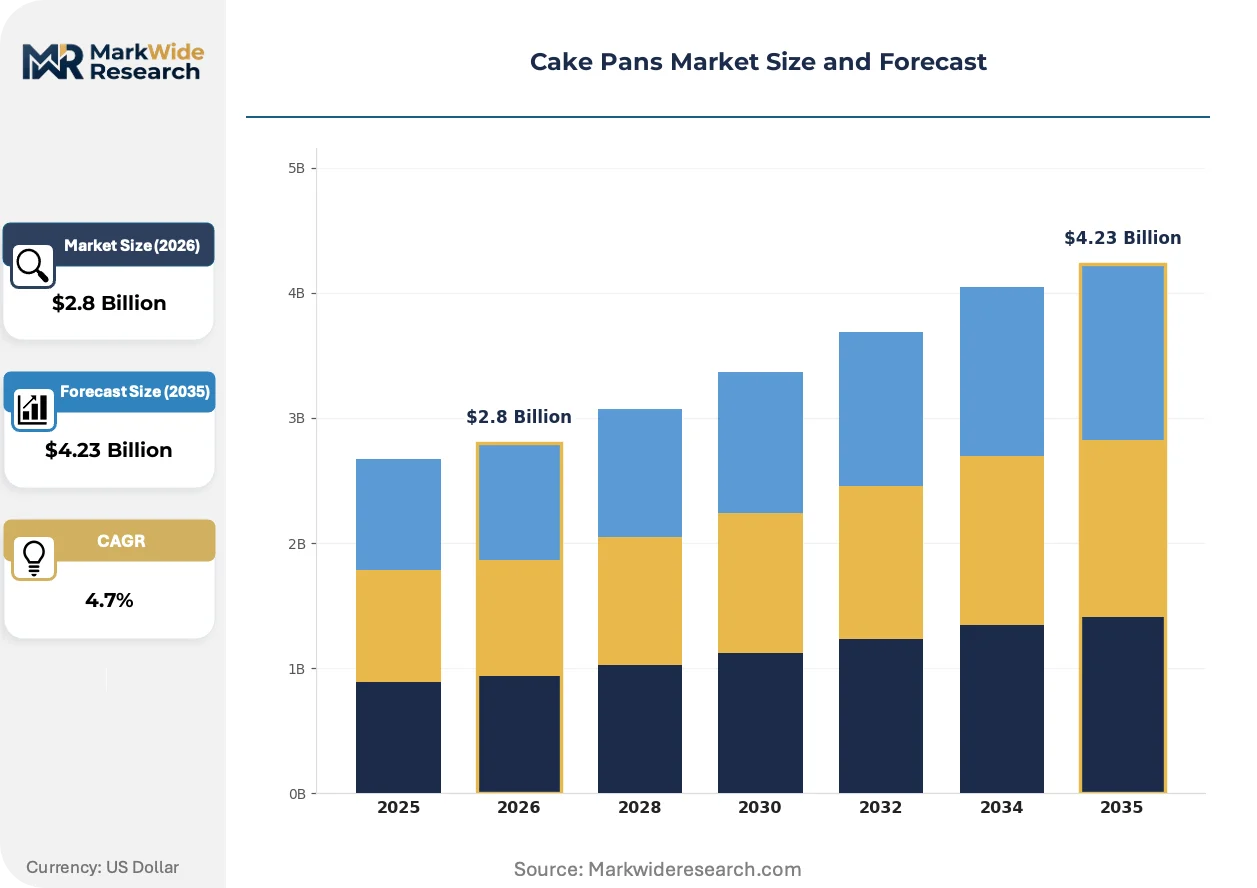
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Stainless Steel, Silicone, Non-Stick Shape: Round, Square, Rectangular, Specialty Size: Mini, Standard, Large, Jumbo End User: Home Bakers, Professional Bakers, Restaurants, Catering Services |
| Companies Covered | Wilton Brands, Nordic Ware, USA Pan, Le Creuset, Calphalon, Cuisinart, Pyrex, Farberware, Anolon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cake Pans Market Evolving Landscape
Material science advances and regulatory chemistry constraints are bifurcating product development roadmaps. Manufacturers now optimize simultaneously for thermal performance and coating safety, with divergent solutions emerging for commercial versus residential use cases.
Ceramic-reinforced silicone hybrid formulations are consolidating the mid-market tier between commodity aluminum and premium die-cast alternatives. Home bakers seeking microwave-to-oven versatility drive adoption of these composites, which offer structural rigidity without thermal conductivity tradeoffs. The technology is consolidating price-performance expectations around demolding convenience rather than heat distribution metrics.
REACH restrictions on per- and polyfluoroalkyl substances are compelling coating suppliers to accelerate fluoropolymer-free formulations. Manufacturers serving EU markets face reformulation deadlines that outpace FDA review timelines, creating regulatory arbitrage opportunities for early movers. Professional-grade product lines bear the highest compliance burden, as NSF certification requirements layer atop substance restrictions.
Baking content creators now function as de facto distribution channels, with affiliate-linked pan recommendations displacing traditional craft-store discovery. Hobbyist buyers purchase directly from manufacturer storefronts after platform algorithm exposure, compressing the path from awareness to transaction. This behavioral shift concentrates in the United States and Germany, where creator economy monetization infrastructure matures fastest.
Cake Pans Market Segmentation
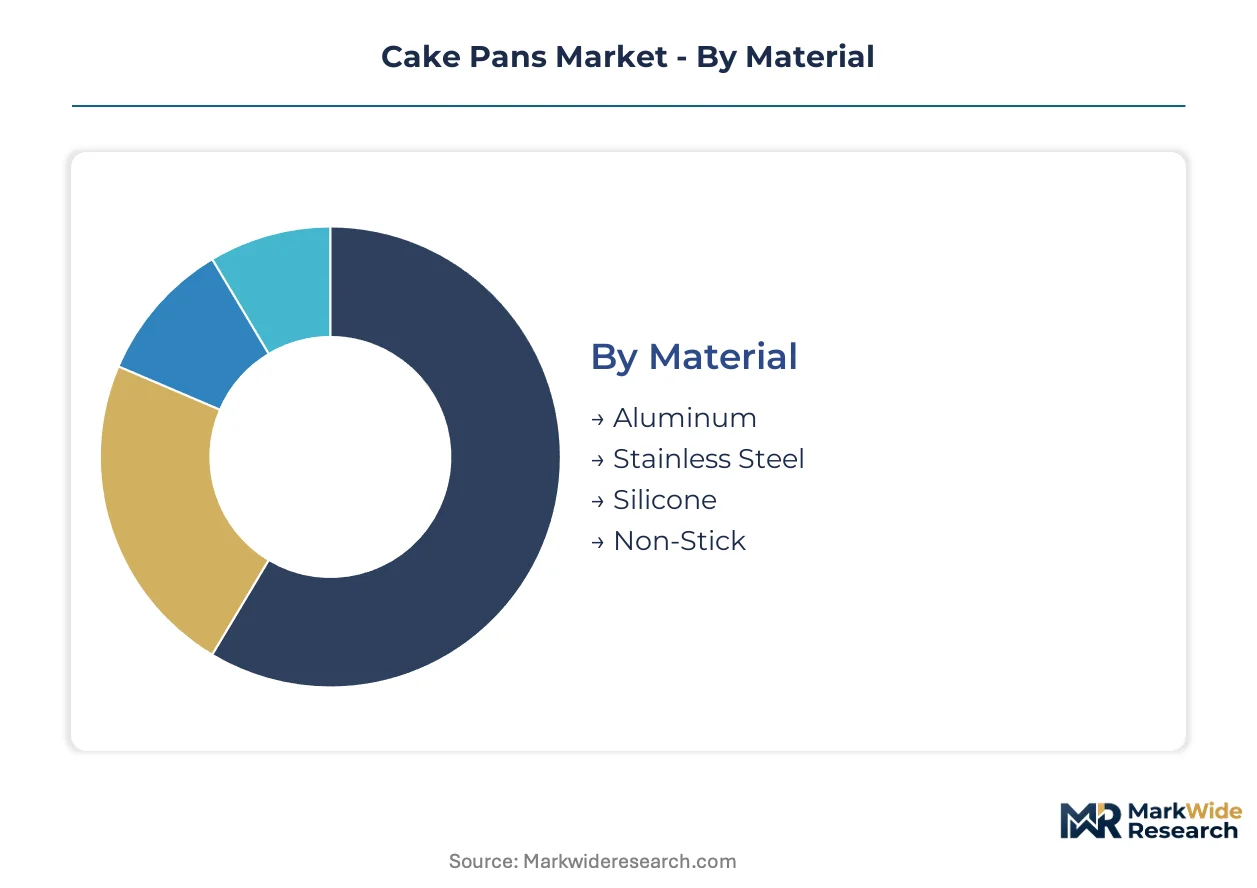
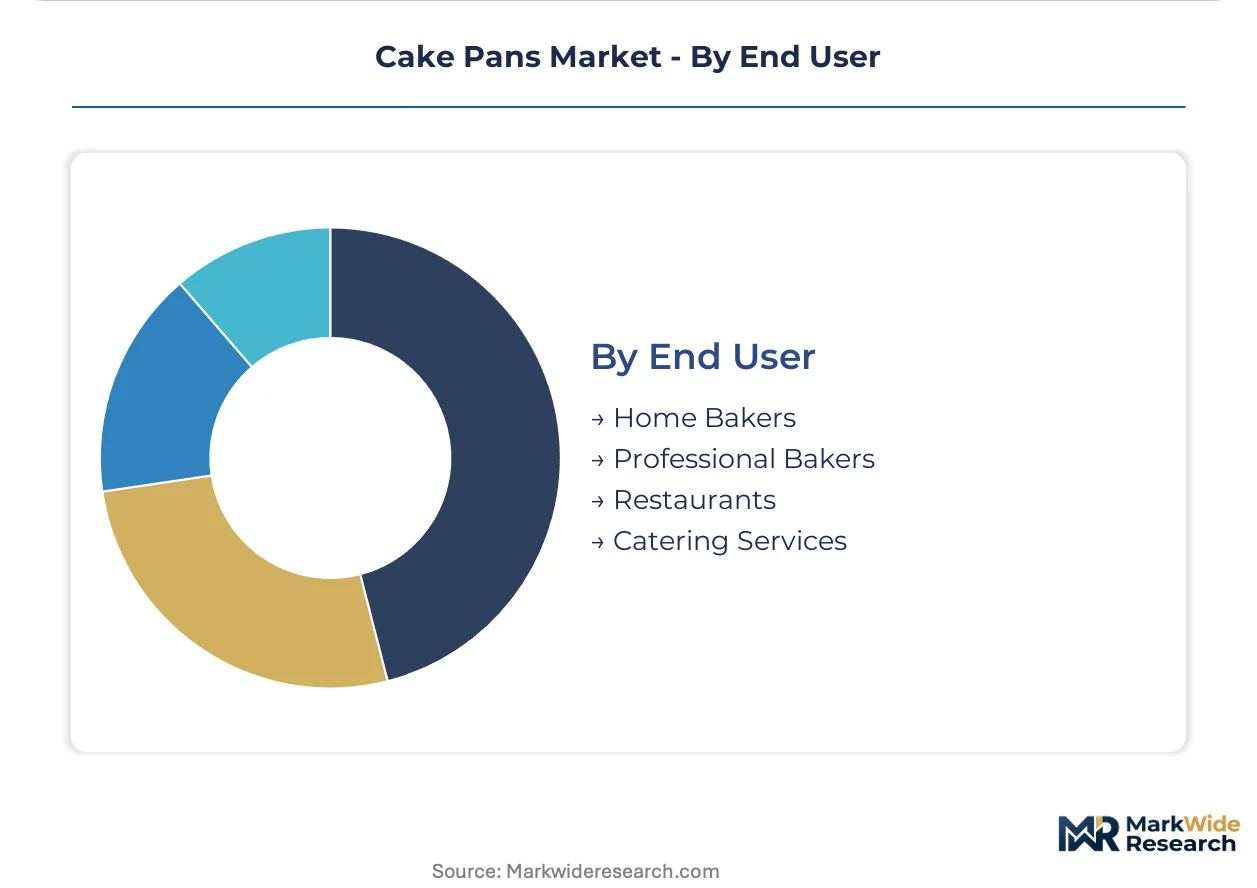
Cake pans segment across four functional dimensions that determine thermal performance, use-case fit, and margin capture. Material chemistry and end-user application exert the strongest influence on pricing architecture and distribution channel selection.
Material:
Buyers differentiate primarily by thermal conductivity requirements and coating safety preferences rather than upfront cost alone.
- Aluminum:Die-cast or stamped construction delivers superior heat distribution coefficients for uniform browning. Demand concentrates among commercial bakeries in the United States and Germany where thermal efficiency specifications outweigh coating transition risks.
- Silicone:Platinum-cured or tin-cured elastomer formulations enable microwave-to-oven versatility and rapid demolding. Home bakers in Japan and the United States drive fastest expansion as social media content amplifies convenience-oriented trial.
- Stainless Steel:18/8 or 18/10 chromium-nickel alloys resist corrosion without surface coating dependencies. Professional kitchens prioritize durability certifications over thermal conductivity metrics.
- Non-Stick:Ceramic or fluoropolymer surface treatments reduce fat requirements and simplify cleaning. Regulatory pressure from EFSA and FDA migration limits is forcing rapid chemistry reformulation.
Volume sits with aluminum; growth tilts toward silicone.
Shape:
Geometric configuration determines batter distribution physics and decorative finish possibilities across residential and commercial ovens.
- Round:Concentric wall construction optimizes heat circulation for layer cakes and tortes. Standard diameters dominate replacement cycles in established baking households.
- Square:Right-angle corners maximize yield from rectangular oven cavities and simplify portioning for brownies and sheet cakes. Commercial kitchens favor these for efficiency.
- Rectangular:Extended surface area supports sheet cakes and bar cookies with consistent edge-to-center baking. Institutional buyers specify these for volume production.
- Specialty:Bundt, tube, and character molds deliver aesthetic differentiation for gift occasions and content creation. Licensed entertainment IP convergence accelerates demand in the United States.
Round and rectangular formats command volume; specialty shapes capture the steepest expansion trajectory through social media discoverability.
Size:
Capacity scaling aligns with batch economics and oven cavity constraints rather than household demographics alone.
- Standard:8-inch to 9-inch diameters or equivalent volume serve nuclear family occasions and recipe standardization. These anchor mass-market retail assortment.
- Mini:Individual-portion formats support tasting menus, portion control, and high-yield production for catering. Restaurants specify these for plating flexibility.
- Large:10-inch plus diameters accommodate celebration cakes and institutional volume requirements. Professional bakers prioritize these for wedding and event contracts.
- Jumbo:Commercial-scale dimensions exceed standard residential oven specifications. Catering services and central kitchens drive thin but high-margin demand.
Standard sizing dominates unit economics; mini formats gain share fastest through restaurant plating trends.
End User:
Buyer sophistication and performance requirements separate certification-driven procurement from impulse-driven retail selection.
- Home Bakers:Hobbyist buyers prioritize convenience features and aesthetic outcomes over durability metrics. Social media algorithm exposure compresses purchase cycles and fragments brand loyalty.
- Professional Bakers:Artisan and production operations demand NSF compliance, thermal conductivity specifications, and multi-year durability. These buyers insulate aluminum segments from silicone displacement.
- Restaurants:Kitchen operations balance speed of service with presentation requirements. Mini and specialty formats support dessert menu differentiation.
- Catering Services:High-volume event production requires jumbo formats and rapid turnaround compatibility. Commercial-grade construction justifies premium pricing tiers.
Professional bakers anchor margin pools; home bakers deliver volume expansion through post-pandemic hobby retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shenzhen and bonded logistics parks in Hamburg concentrate die-cast aluminum sourcing for bakeware exporters serving premium retail channels in the United States and Germany.
United States
Home baking hobby retention and social media content creator affiliate networks drive silicone and specialty-shaped pan demand. FDA migration limits under 21 CFR 175.300 constrain coating chemistry choices for non-stick formulations. Minneapolis-St. Paul anchors Nordic Ware's die-cast aluminum production, while Wilton Brands maintains distribution headquarters near Chicago's craft-store corridor.
Germany
Professional bakery equipment procurement and thermal efficiency specifications sustain heavy-gauge aluminum demand among artisan producers. EFSA perfluorinated compound restrictions accelerate ceramic coating reformulation timelines faster than FDA review cycles. Solingen's metalworking cluster supplies precision-stamped bakeware to EU institutional buyers, while Nuremberg hosts annual baking trade fairs that set regional assortment standards.
Japan
Microwave-to-oven versatility and compact kitchen footprints favor platinum-cured silicone formats in Tokyo and Osaka metropolitan households. METI product safety standards govern elastomer migration testing for food-contact applications. Kansai region manufacturers specialize in mini-format pans aligned with bento culture and individual portion dessert trends.
India
Emerging middle-class household upgrading from improvised vessels creates replacement demand for standardized round and rectangular formats. BIS certification requirements under IS 9873 create compliance barriers for unorganized sector imports. Maharashtra's Thane-Belapur industrial belt hosts contract manufacturers serving domestic modern trade and export preprocessing to Gulf markets.
China
Export contract manufacturing and domestic e-commerce direct-to-consumer channels bifurcate production between OEM scale and branded silicone innovation. GB standards compliance for food-contact materials and SAMR product quality supervision shape coating substance approvals. Yangtze River Delta factories in Zhejiang and Jiangsu provinces supply character-mold capacity for licensed entertainment IP releases targeting North American gift markets.
Cake Pans Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium die-cast aluminum concentrated among heritage US producers and silicone innovation dispersing across Asian supply bases. The vendor base organizes into three tiers: mass-market licensors with craft-store distribution, commercial-grade fabricators with NSF certification, and direct-to-consumer specialists with content-creator affiliate networks. Consolidation pressure concentrates in the mid-market where ceramic-silicone hybrid formulations erode traditional aluminum positioning. Strategic moves center on coating chemistry reformulation partnerships and direct-to-consumer subscription model launches that bypass retail margin structures.
Within the heritage US manufacturer tier, Nordic Ware and Wilton Brands exemplify divergent specialization strategies. Nordic Ware occupies a position anchored in die-cast aluminum craftsmanship and Made-in-USA sourcing narratives, while Wilton Brands exemplifies mass-market channel dominance through licensed character mold portfolios and craft-store distribution density. USA Pan represents the commercial-grade vector, targeting professional bakers and institutional buyers with aluminized steel construction claims. These three entities collectively illustrate how thermal performance specifications, distribution channel control, and regulatory compliance positioning separate margin pools from commoditized alternatives.
| Leading Market Players |
|---|
| Wilton Brands |
| Nordic Ware |
| USA Pan |
| Le Creuset |
| Calphalon |
| Cuisinart |
| Pyrex |
| Farberware |
| Anolon |
| Others |
Value Network & Pricing Analysis
London Metal Exchange aluminum pricing volatility cascades through die-cast fabrication costs into three distinct buyer tiers, with energy-intensive smelting premiums compressing margins for stamped-sheet producers unable to hedge input exposure.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to NSF-certified commercial-grade orders from professional bakeries, while spot inventory of standard aluminum rounds trades at contracted discounts. Pricing stratifies across premium die-cast, standard stamped, and economy imported tiers, with certification grade and thermal conductivity specifications driving differentiation. Cost compression in the economy tier is intensifying because Chinese contract manufacturers absorb currency fluctuation to maintain export share. Home bakers exhibit highest price sensitivity, while catering services prioritize durability claims over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta die-casting capacity for premium aluminum formats, where Zhejiang and Jiangsu provinces concentrate OEM fabrication for North American brands. Raw material draws from Australian bauxite, Chinese alumina refining, and German tooling equipment. Tariff exposure on finished bakeware imports into the United States creates inventory positioning risk for distributors holding bonded warehouse stock. Distribution runs through craft-store retail clusters, direct-to-consumer manufacturer storefronts, and restaurant supply wholesalers serving institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone and ceramic-hybrid technologies are displacing legacy aluminum in residential segments, creating a material-transition phase where coating chemistry compliance separates viable competitors from stranded inventory.
For Market Incumbents: Acquire ceramic-coating formulation IP to accelerate fluoropolymer-free product line transitions ahead of EFSA deadline divergence. Secure backward integration into platinum-cured silicone compounding to defend margin position against Asian contract manufacturer cost structures. NSF certification maintenance insulates commercial-grade aluminum from displacement.
For New Entrants and Emerging Players: Begin with direct-to-consumer subscription models targeting home bakers through content-creator affiliate networks, bypassing craft-store margin structures. India BIS certification compliance unlocks modern trade access for standardized round and rectangular formats. Licensed entertainment IP convergence captures gift-market occasions with character-mold differentiation.
For Investors and Strategic Acquirers: The window for entry favors ceramic-silicone hybrid specialists with established EU regulatory compliance and content-creator distribution partnerships. Long-term viability hinges on coating chemistry reformulation capabilities rather than scale economies alone. Watch EFSA-FDA regulatory divergence timelines as inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Reformulation | EFSA perfluorinated compound restrictions force fluoropolymer-free surface treatment transitions ahead of FDA review cycles. |
| Direct-to-Consumer Subscription Launch | Curated seasonal pan collections bypass craft-store margin structures and build recurring revenue from algorithm-discovered buyers. |
| BIS Certification Investment | Formal compliance with Bureau of Indian Standards unlocks modern trade access to emerging middle-class households upgrading from improvised vessels. |
| Licensed Entertainment IP Partnership | Character-shaped molds tied to streaming content releases capture gift-market occasions and social media shareability in the United States. |
| Platinum-Cured Silicone Compounding | In-house elastomer formulation control defends margin structure against Yangtze River Delta contract manufacturer cost competition. |
Research Methodology
Independent corroboration across primary interviews with commercial bakery procurement managers, coating chemistry suppliers, craft-store category buyers, and content-creator affiliate network operators underwrites the qualitative findings. Secondary validation draws from FDA 21 CFR filings, EFSA migration limit documentation, London Metal Exchange aluminum price data, and customs import records. Bottom-up demand modeling from end-user segments triangulates against top-down market sizing from production capacity assessments.
Comparable-period anchoring to pre-pandemic baseline volumes establishes the forecast window trajectory across the analysis window. The analytical framework models material chemistry, end-user application, shape configuration, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth rate blending weighted by volume contribution. Forecast inputs include social media content creator reach metrics and home baking hobby retention surveys.
Underlying measurement precision varies by segment; silicone growth rates carry tighter precision than specialty shape demand projections. Forecasts reflect assumptions on regulatory phase-out timelines and coating reformulation success rates. Deviation in EFSA-FDA regulatory divergence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Global Stainless Woks Market
Kitchen Appliances
Asia Pacific Induction Hobs Market
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Europe Household Appliances Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Russia Kitchen Appliances Market