
 Ceramic Coated Cookware Market | 2026-2036
Ceramic Coated Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Coated Cookware Market Insights
Market Context
China is narrowing the cost gap with European ceramic coating suppliers through expanded sol-gel manufacturing clusters in Zhejiang and Guangdong provinces. GreenPan leverages proprietary Thermolon technology to sustain premium positioning across North American and European markets. Caraway specializes in direct-to-consumer channel control, while Zwilling J.A. Henckels anchors professional-grade credibility through German engineering heritage.
Technical Definition and Segment Structure
Ceramic coated cookware comprises metal substrates—typically aluminum, stainless steel, or cast iron—covered with inorganic silica-based sol-gel coatings that cure at temperatures between 400°C and 450°C to create a hydrophobic, non-reactive cooking surface free of polytetrafluoroethylene. The coating's primary commercial purpose is to eliminate per- and polyfluoroalkyl substance release during high-heat cooking while maintaining release performance competitive with traditional non-stick systems. Aluminum substrate frying pans occupy the largest volume position due to thermal conductivity advantages and cost accessibility, though stainless steel cookware sets command margin premiums through durability positioning and compatibility with induction cooktops. Online retail distribution is accelerating fastest as brands bypass wholesale markups and capture first-party consumer data.
Regulatory Environment
REACH in Europe and FDA food-contact substance regulations in the United States are progressively restricting legacy fluoropolymer coatings, directly expanding addressable demand for ceramic alternatives that demonstrate compliance through migration testing protocols. ECHA's PFAS restriction proposals and state-level legislation in California and New York are creating fragmented but directional compliance pressure across major demand centers. Stakeholders must monitor evolving testing standards and raw material qualification timelines to secure coating chemistry approvals before regulatory deadlines crystallize procurement requirements.
Market Dynamics
REACH and FDA food-contact restrictions on fluoropolymer chemistries are redirecting procurement toward sol-gel ceramic systems, compressing qualification timelines and rewiring supplier relationships across cookware supply chains.
Growth Catalysts
- REACH PFAS Restrictions:ECHA's proposed broad PFAS limitations eliminate legacy non-stick options from European retail shelves, forcing brand owners to certify ceramic alternatives ahead of enforcement deadlines.
- Induction Cooktop Penetration:Stainless steel substrate demand is accelerating in residential kitchens as electromagnetic heating adoption spreads through German and Japanese appliance markets.
- Sol-Gel Manufacturing Clusters:Expanded production capacity in Zhejiang and Guangdong provinces is shortening lead times and reducing coating cost differentials versus European supply.
Market Restraints
- Silica Nanoparticle Supply Concentration:Precursor chemical production clusters heavily in eastern China, exposing coating formulators to single-source disruption risk and freight volatility.
- Thermal Durability Ceiling:Ceramic surfaces degrade faster than fluoropolymer systems above 450°C, limiting professional kitchen adoption where high-heat searing is routine.
- Substitution from Cast Iron:Unseasoned and enameled cast iron cookware retains toxin-free positioning without coating complexity, capturing price-sensitive health-conscious buyers.
Strategic Opportunities
- India Urban Middle-Class Expansion:FSSAI tightening on food-contact materials creates first-mover advantage for ceramic-coated imports and local assembly partnerships in Mumbai and Bangalore.
- Recyclable Substrate Integration:Aluminum recycling mandates in the EU Green Deal push brands toward closed-loop material sourcing paired with ceramic surface renewal services.
- Direct-to-Consumer Data Capture:First-party e-commerce channels enable predictive inventory and personalized product development bypassing wholesale margin extraction.
Industry Challenges
- Migration Testing Bottlenecks:FDA and ECHA protocol divergence forces dual-track laboratory validation, extending new coating chemistry approval cycles by 8-14 months.
- Sol-Gel Application Skill Scarcity:Thin-film ceramic deposition requires precision control absent from conventional PTFE coating workforces, constraining production scaling.
Report Scope
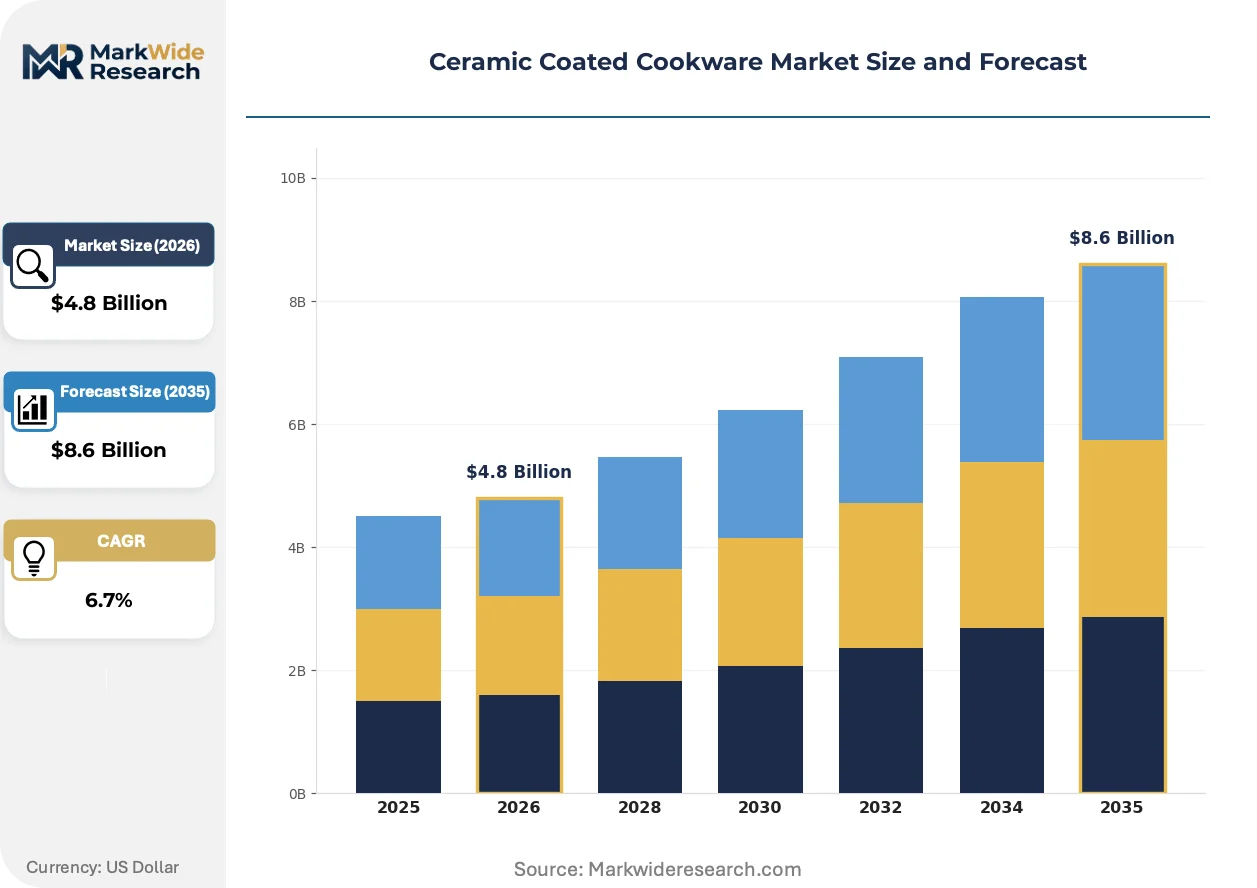
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Coated Cookware Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frying Pans, Sauce Pans, Bakeware, Cookware Sets Material: Aluminum, Stainless Steel, Copper, Cast Iron Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Residential, Commercial, Culinary Schools, Food Service |
| Companies Covered | Tramontina USA, GreenPan, Cuisinart, Calphalon, Tefal, Our Place, Williams-Sonoma Inc., Zwilling J.A. Henckels, Caraway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Coated Cookware Market Trends and Innovations
Active coating formulation, regulatory chemistry restrictions, and channel restructuring are simultaneously compressing product lifecycles and opening new margin pools across ceramic cookware supply chains.
Multi-layer sol-gel systems incorporating titanium dioxide and reinforced silica matrices are collapsing the performance gap between ceramic and legacy fluoropolymer release characteristics. Premium residential buyers in Germany and the United States are accepting 15-20% price premiums for these advanced formulations. The technology is collapsing aftermarket re-coating service economics by extending usable product lifespans beyond traditional warranty periods.
California's AB 1200 and New York's pending PFAS disclosure mandates are accelerating state-level fragmentation ahead of federal harmonization. Brand owners must now maintain parallel inventory SKUs and labeling systems to serve restricted versus unrestricted state markets. The regulatory patchwork is concentrating compliance investment among mid-scale manufacturers lacking dedicated regulatory affairs functions.
First-party digital channels are displacing wholesale and big-box retail as the primary customer acquisition path for ceramic cookware brands. Direct-to-consumer platforms in the United States and United Kingdom capture behavioral data enabling predictive replenishment and accessory bundling. This channel shift is most visible among millennial and Gen Z household formation cohorts prioritizing transparency and sustainability certifications over in-store tactile evaluation.
Ceramic Coated Cookware Market Segmentation
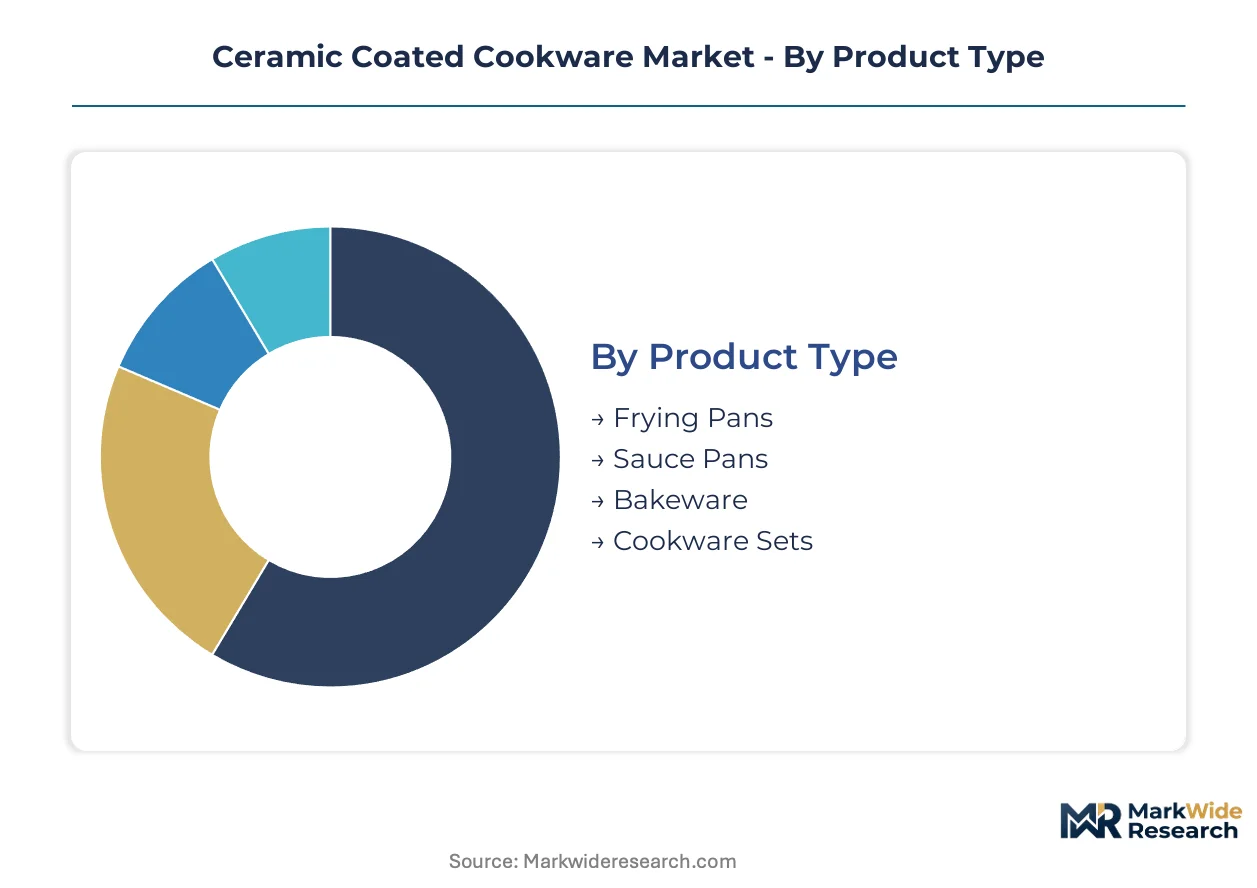
Ceramic coated cookware segmentation reveals how substrate choices, channel strategies, and end-use requirements fragment procurement patterns across residential and professional kitchens. Understanding these divisions exposes where coating formulators must adapt sol-gel specifications and where brands capture margin through material positioning.
Product Type:
Mature categories dominate household penetration while emerging formats reshape professional kitchen equipment specifications.
- Frying Pans:Single-piece aluminum substrates with 2.5-3.5mm gauge thickness concentrate the highest shipment volumes through mass-market retail. North American residential buyers prioritize 10-inch and 12-inch diameters for stovetop versatility, with ECHA's PFAS restrictions accelerating ceramic conversion in German and French households.
- Cookware Sets:Coordinated 7-12 piece collections bundling fry pans, sauce pans, and Dutch ovens command premium positioning through direct-to-consumer channels. California's AB 1200 disclosure mandates force set manufacturers to maintain parallel SKUs for restricted versus unrestricted state markets, complicating inventory planning.
- Sauce Pans:Medium-gauge vessels with tempered glass lids serve simmering and reduction tasks in residential kitchens.
- Bakeware:Rectangular and loaf configurations with reinforced rim construction target oven-specific applications.
Frying pans retain volume leadership; cookware sets hold the steepest expansion curve.
Material:
Cost tiers separate thermal performance positioning from induction compatibility requirements across substrate selections.
- Aluminum:3003 and 3004 alloy substrates with hard-anodized pre-treatment deliver superior thermal conductivity at accessible price points. Zhejiang and Guangdong manufacturing clusters supply rolled aluminum sheet to coating facilities, shortening lead times for European and North American brands.
- Stainless Steel:18/10 chromium-nickel compositions with magnetic 430-grade bases enable induction cooktop compatibility. German and Japanese appliance markets drive residential demand as electromagnetic heating penetration accelerates.
- Copper:2.5mm gauge substrates with tin or ceramic lining serve professional kitchen thermal responsiveness requirements.
- Cast Iron:Enameled and bare substrates compete with ceramic coatings on toxin-free positioning without sol-gel complexity.
Aluminum dominates unit economics; stainless steel gains share fastest on induction compatibility.
Distribution Channel:
Customer type fragmentation between convenience-seeking mass buyers and transparency-demanding direct purchasers rewires margin capture.
- Online Retail:First-party e-commerce platforms and marketplace storefronts capture behavioral data enabling predictive replenishment. Millennial and Gen Z household formation cohorts in the United States and United Kingdom prioritize sustainability certifications over in-store tactile evaluation.
- Supermarkets:Mass-market retail placement drives impulse purchases of single-piece fry pans through high-frequency traffic.
- Specialty Stores:Sur La Table and Williams Sonoma locations enable hands-on evaluation for premium cookware sets.
- Direct Sales:Brand-owned showrooms and pop-up experiences control full margin stack for established ceramic coating labels.
Supermarkets retain transaction volume; online retail climbs the fastest on data-enabled bundling.
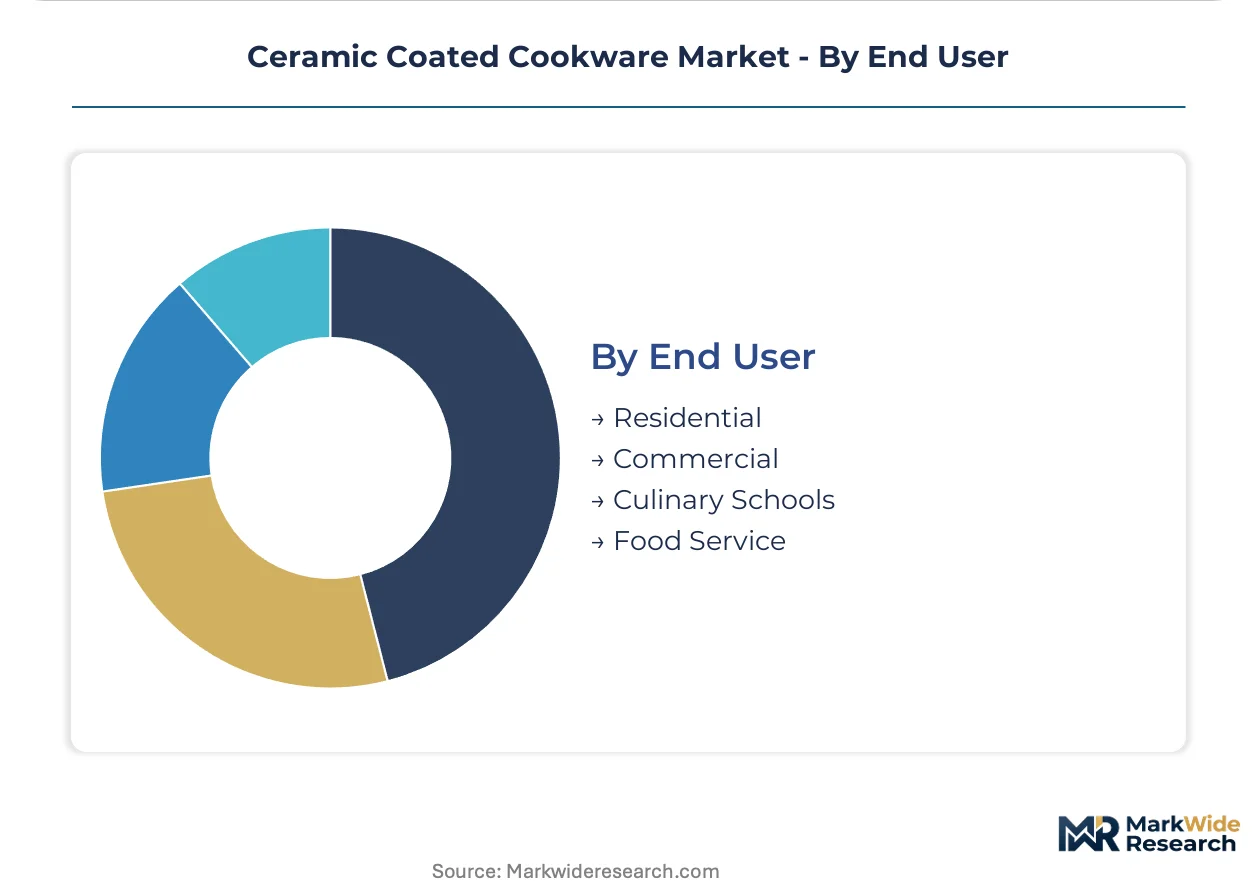
End User:
Application requirements separate temperature tolerance needs from regulatory compliance burdens across kitchen environments.
- Residential:Health-conscious households seeking PTFE-free alternatives drive the core addressable market. FDA food-contact substance regulations and state-level PFAS disclosure mandates in California and New York redirect procurement toward ceramic systems with migration testing documentation.
- Commercial:Restaurant and hotel kitchens demand thermal durability above 450°C where ceramic surfaces degrade faster than fluoropolymer alternatives.
- Culinary Schools:Training institutions require standardized equipment for instruction consistency across student cohorts.
- Food Service:Institutional cafeterias and catering operations prioritize cost efficiency over coating longevity in high-volume settings.
Residential commands revenue concentration; commercial faces adoption ceilings on thermal performance constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sol-gel coating production clusters heavily in eastern China, exposing European and North American brands to freight volatility and qualification bottlenecks. German and Japanese appliance markets are accelerating stainless steel substrate demand through induction cooktop penetration. Regulatory fragmentation between ECHA's REACH proposals and California's AB 1200 disclosure mandates forces parallel inventory systems across major demand centers.
United States
Residential buyers in California and New York face AB 1200 and pending PFAS disclosure laws that redirect procurement toward ceramic systems with migration documentation. FDA food-contact substance regulations tighten scrutiny on legacy fluoropolymer alternatives. Direct-to-consumer brands headquartered in New York and Los Angeles capture first-party data through e-commerce platforms, enabling predictive replenishment models.
Germany
ECHA's proposed broad PFAS limitations under REACH eliminate legacy non-stick options from retail shelves, forcing brand owners to certify ceramic alternatives ahead of enforcement deadlines. Induction cooktop penetration in German households accelerates stainless steel substrate demand. Manufacturing clusters in North Rhine-Westphalia and Bavaria house coating application facilities serving pan-European distribution networks.
China
Zhejiang and Guangdong provinces have expanded sol-gel manufacturing capacity, shortening lead times and reducing cost differentials versus European supply. MIIT standards and dual carbon goals push domestic brands toward closed-loop aluminum recycling paired with ceramic surface renewal. Shanghai and Shenzhen serve as export consolidation points for North American and European brand owners.
India
FSSAI tightening on food-contact materials creates first-mover advantage for ceramic-coated imports and local assembly partnerships. Mumbai and Bangalore anchor demand from urban middle-class households seeking PTFE-free alternatives. Gujarat and Tamil Nadu host emerging coating application facilities supplying domestic brands and export markets.
Japan
METI efficiency standards and residential kitchen renovation cycles sustain premium positioning for ceramic-coated stainless steel cookware. Osaka and Nagoya manufacturing clusters specialize in precision sol-gel deposition for induction-compatible substrates. JIS standards for food-contact materials align with ECHA testing protocols, simplifying dual-market qualification.
Ceramic Coated Cookware Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in coating formulation and substrate fabrication. The vendor base separates into three tiers: multinational housewares conglomerates with diversified kitchen portfolios, direct-to-consumer brands controlling full margin stacks through owned channels, and private-label manufacturers supplying retail banners. Consolidation pressure concentrates among mid-scale manufacturers lacking dedicated regulatory affairs functions. Competitive moves center on geographic expansion into India and Southeast Asia, plus technology licensing of multi-layer sol-gel systems.
Among premium-tier specialists, GreenPan and Caraway exemplify divergent channel strategies—GreenPan leverages proprietary coating technology across wholesale and retail partnerships, while Caraway anchors direct-to-consumer positioning with first-party data capture. Zwilling J.A. Henckels occupies professional-grade credibility through German engineering heritage. These three represent the archetype spectrum from technology-licensing platform to channel-native brand to heritage manufacturer.
| Leading Market Players |
|---|
| Tramontina USA |
| GreenPan |
| Cuisinart |
| Calphalon |
| Tefal |
| Our Place |
| Williams-Sonoma Inc. |
| Zwilling J.A. Henckels |
| Caraway |
| Others |
Pricing and Supply Chain Analysis
Silica nanoparticle supply concentration in eastern China determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic configuration of coating application facilities serving North American and European brands. REACH and FDA compliance timelines compress procurement cycles while freight volatility from Zhejiang and Guangdong ports feeds directly into landed cost spreads across distribution tiers.
Pricing Analysis
REACH PFAS restrictions dictate the pricing tier structure by forcing dual-track certification investments that separate premium ceramic formulations from standard sol-gel alternatives. Price differentiation rests on migration testing documentation depth and induction compatibility certification, with German and Japanese appliance markets absorbing the steepest premiums for stainless steel substrates. Cost compression in mass-market aluminum fry pans is intensifying because Zhejiang manufacturing clusters narrowed European coating cost differentials. Residential buyers in California and New York show lowest price sensitivity due to AB 1200 disclosure mandates eliminating legacy options.
Supply Chain Analysis
Extended payment terms from Zhejiang coating facilities to European brand owners compress working capital cycles and concentrate supplier financing risk in eastern China. Raw material dependencies draw from silica precursor chemicals, 3003 aluminum alloy sheet, and magnetic 430-grade stainless steel substrates. Single-source vulnerability sits with sol-gel formulation clusters in Guangdong province exposed to MIIT environmental enforcement cycles. Distribution runs through direct-to-consumer platforms capturing first-party data alongside wholesale retail partnerships for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where ECHA and FDA compliance documentation creates switching costs that lock in certified suppliers ahead of enforcement deadlines. Network effects concentrate among coating formulators with pre-qualified chemistry libraries serving multiple brand owners.
For Market Incumbents: Insulate market position by deepening backward integration into sol-gel precursor production within North Rhine-Westphalia coating clusters, offsetting silica nanoparticle supply concentration risk. Accelerate multi-layer titanium dioxide formulation R&D to extend thermal durability ceilings above 450°C, neutralizing cast iron substitution threats in professional kitchen segments.
For New Entrants and Emerging Players: Build out local assembly partnerships in Gujarat and Tamil Nadu to capture FSSAI tightening tailwinds in Mumbai and Bangalore urban middle-class expansion. Target direct-to-consumer channel control with predictive replenishment models, exploiting millennial household formation cohorts prioritizing transparency certifications over tactile retail evaluation.
For Investors and Strategic Acquirers: ECHA's broad PFAS restriction proposals reshape the acquisition landscape by concentrating value in coating formulators with validated migration testing protocols and established European brand relationships. Mid-scale manufacturers lacking dedicated regulatory affairs functions face consolidation pressure, creating rollup opportunities for platform integrators. Watch for FDA-ECHA protocol convergence signals as inflection indicators for qualification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Sol-Gel Licensing | Titanium dioxide formulations collapse performance gaps versus fluoropolymer systems in German premium residential markets. |
| Direct-to-Consumer Channel Expansion | First-party data capture enables predictive replenishment bypassing wholesale margin extraction in United States and United Kingdom. |
| Induction Compatibility Certification | Magnetic 430-grade stainless steel substrates capture share from aluminum as electromagnetic heating penetrates Japanese households. |
| Closed-Loop Aluminum Recycling | EU Green Deal mandates push brands toward surface renewal services paired with recycled substrate integration. |
| India Local Assembly Partnerships | FSSAI tightening creates first-mover advantage for ceramic-coated imports in Mumbai and Bangalore demand centers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with coating formulators, brand procurement directors, and specialty retail category managers; and secondary validation through ECHA restriction proposal documentation, FDA food-contact substance filings, and customs trade records from Zhejiang and Guangdong export consolidation points. Bottom-up shipment modeling triangulated against top-down consumer expenditure patterns across residential and commercial end-use segments.
Forecast inputs incorporated substrate material splits, distribution channel migration rates, and regulatory compliance timeline assumptions across the projection horizon. Segmentation dimensions modeled include product type, substrate material grade, channel structure, and end-use application intensity. CAGRs derived from unit shipment trajectories weighted by average selling price evolution through premium formulation penetration and channel mix shifts.
Sensitivities concentrate around ECHA PFAS enforcement timeline acceleration, silica precursor supply disruption from MIIT environmental inspections, and induction cooktop penetration rates in German and Japanese residential markets. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Smart Induction Cooktop Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
US Induction Cookware Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
Colombia Kitchen Appliances Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Warming Drawer Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
Cake Pans Market