
 Electric Pressure Cooker Market | 2026-2036
Electric Pressure Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Pressure Cooker Market Insights
The direct-to-consumer channel is narrowing as specialty retailers and mass-market chains consolidate shelf space for small kitchen appliances. Instant Pot leverages its brand recognition to sustain premium positioning across North American big-box stores. Ninja Kitchen competes through aggressive bundling with complementary cookware lines. Chef iQ differentiates via app-connected recipe programming that anchors its digital ecosystem strategy.
An electric pressure cooker is a sealed countertop appliance that uses internal steam pressure at temperatures exceeding 100°C to reduce cooking times for grains, proteins, and stews by 50-70% compared to conventional methods. Stainless steel construction dominates commercial-grade units due to durability and heat distribution properties, while non-stick coatings prevail in entry-level consumer segments. Digital and programmable models are capturing the fastest growth trajectory as consumers prioritize preset functions and Wi-Fi connectivity. The six-quart capacity bracket occupies the largest installed base, though eight-quart variants are expanding among multi-person households and meal-prep users.
UL certification requirements in the United States and CE marking obligations under EU appliance directives enforce baseline electrical safety and pressure-release standards that shape design costs and market entry timelines. China's GB standards and NMPA-equivalent quality supervision protocols govern domestic manufacturing output that supplies both local consumption and export channels. Stakeholders must monitor evolving energy-labeling thresholds and right-to-repair legislation that could alter component modularity requirements and aftermarket service economics.
Market Dynamics
Energy-efficiency mandates under the EU Ecodesign Directive and comparable U.S. appliance standards are compressing product development cycles and forcing redesigns of heating elements and insulation systems across the electric pressure cooker supply base.
Growth Catalysts
- EU Ecodesign Directive:Mandatory energy-labeling thresholds accelerate replacement cycles for aging stovetop pressure cookers in European households.
- Stainless steel construction:Commercial-grade durability specifications expand adoption among restaurant kitchens and institutional foodservice operators seeking equipment longevity.
- China's middle-class kitchen upgrades:Domestic manufacturing clusters in Guangdong and Zhejiang provinces enable rapid scaling of multi-function digital models for urban households.
Market Restraints
- Aluminum input cost volatility:Fluctuations in base metal pricing squeeze margin structures for entry-level non-stick coated units.
- Supply concentration in Guangdong:Heavy reliance on a single provincial manufacturing cluster creates vulnerability to regional logistics disruptions and labor availability constraints.
- Induction cooktop substitution:Faster heating alternatives in modern kitchen renovations displace countertop appliance demand in premium residential segments.
Strategic Opportunities
- India's underpenetrated urban markets:Rising electrification rates and nuclear family formations create whitespace for compact digital pressure cookers in tier-2 and tier-3 cities.
- Wi-Fi and app connectivity convergence:Integration of voice-assistant compatibility and recipe programming opens subscription revenue streams for consumables and guided cooking content.
- U.S. right-to-repair legislation momentum:Emerging state-level mandates for component modularity favor manufacturers with modular pressure-valve and heating-element architectures.
Industry Challenges
- Embedded software certification timelines:UL 1026 and IEC 60335-2-15 testing protocols for programmable safety systems extend new product introduction schedules by 4-6 months.
- Multi-material bonding expertise:Shortage of technicians skilled in stainless steel-to-plastic interface engineering constrains scaling of premium digital models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Pressure Cooker Market |
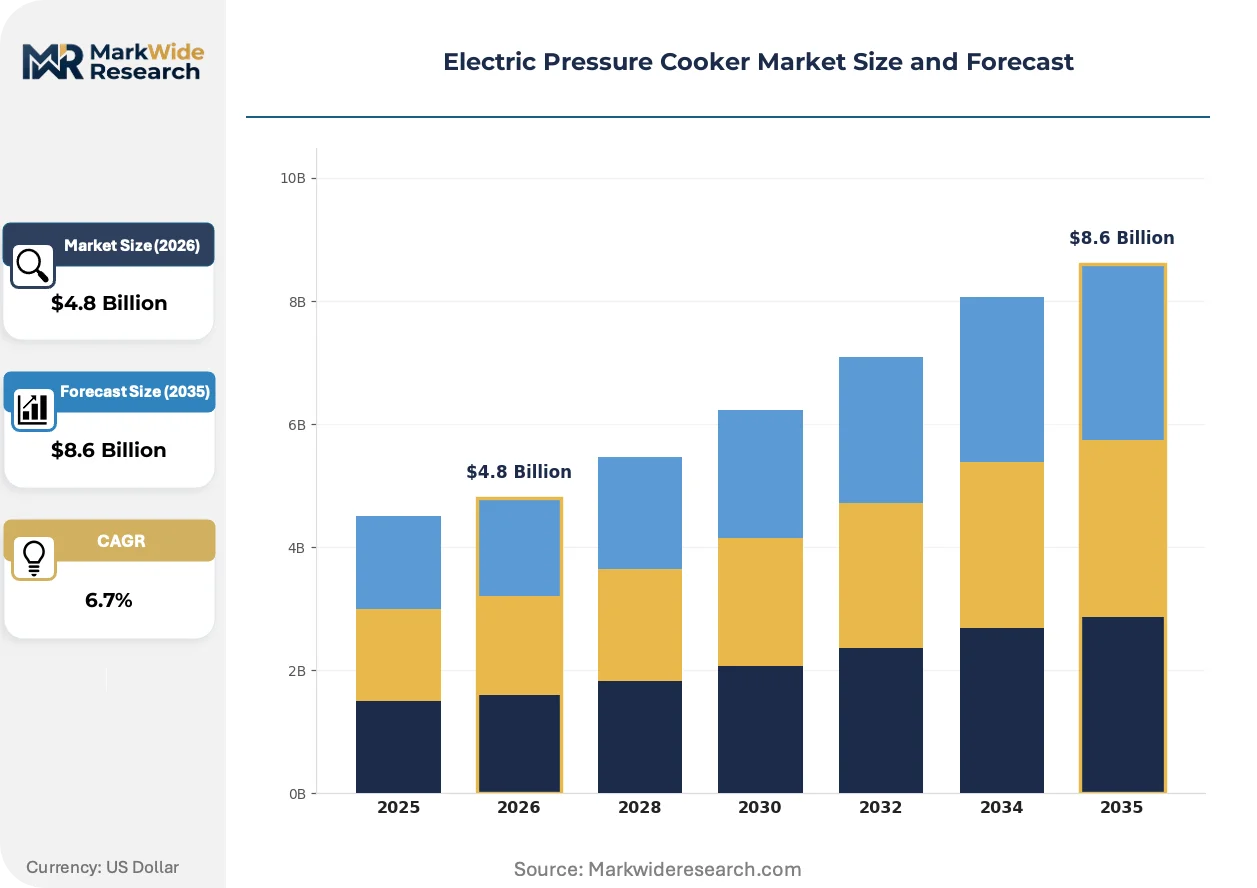
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Manual, Digital, Multi-Function, Programmable Capacity: 3 Quarts, 6 Quarts, 8 Quarts, 10 Quarts Material: Stainless Steel, Aluminum, Non-Stick, Ceramic Power Rating: 600 Watts, 800 Watts, 1000 Watts, 1200 Watts |
| Companies Covered | Our Place, Chef iQ, Instant Pot, COMFEE', Zavor, Ninja Kitchen, T-fal, Blue Diamond, Breville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Pressure Cooker Market Trends and Innovations
Sensor-enabled cooking automation and connected-kitchen ecosystems are displacing manual valve-control interfaces and reshaping how manufacturers monetize hardware through ongoing software engagement.
Precision temperature sensors paired with microprocessor-controlled pressure regulation are digitizing the cooking process for grains and proteins. Urban households in North America and Asia-Pacific adopt these systems fastest, with preset-function models capturing disproportionate growth. The technology is digitizing recipe execution into programmable sequences that reduce user intervention and enable remote monitoring through mobile applications.
The EU Ecodesign Directive's expanding scope now covers standby power consumption and heating efficiency metrics for countertop cooking appliances. Manufacturers must redesign thermal insulation layers and heating coil geometries to meet tiered energy-label thresholds. European-market SKUs face the steepest compliance cost inflation, with redesign cycles compressing from 36 months to 18 months for flagship product lines.
Meal-preparation users and multi-person households are consolidating appliance purchases around larger-capacity units with batch-cooking functionality. Specialty retailers and mass-market chains capture this demand shift through bundled accessory offerings and extended warranty programs. China and the United States exhibit the most pronounced migration toward eight-quart variants, with six-quart models losing share among households cooking for four or more individuals.
Electric Pressure Cooker Market Segmentation
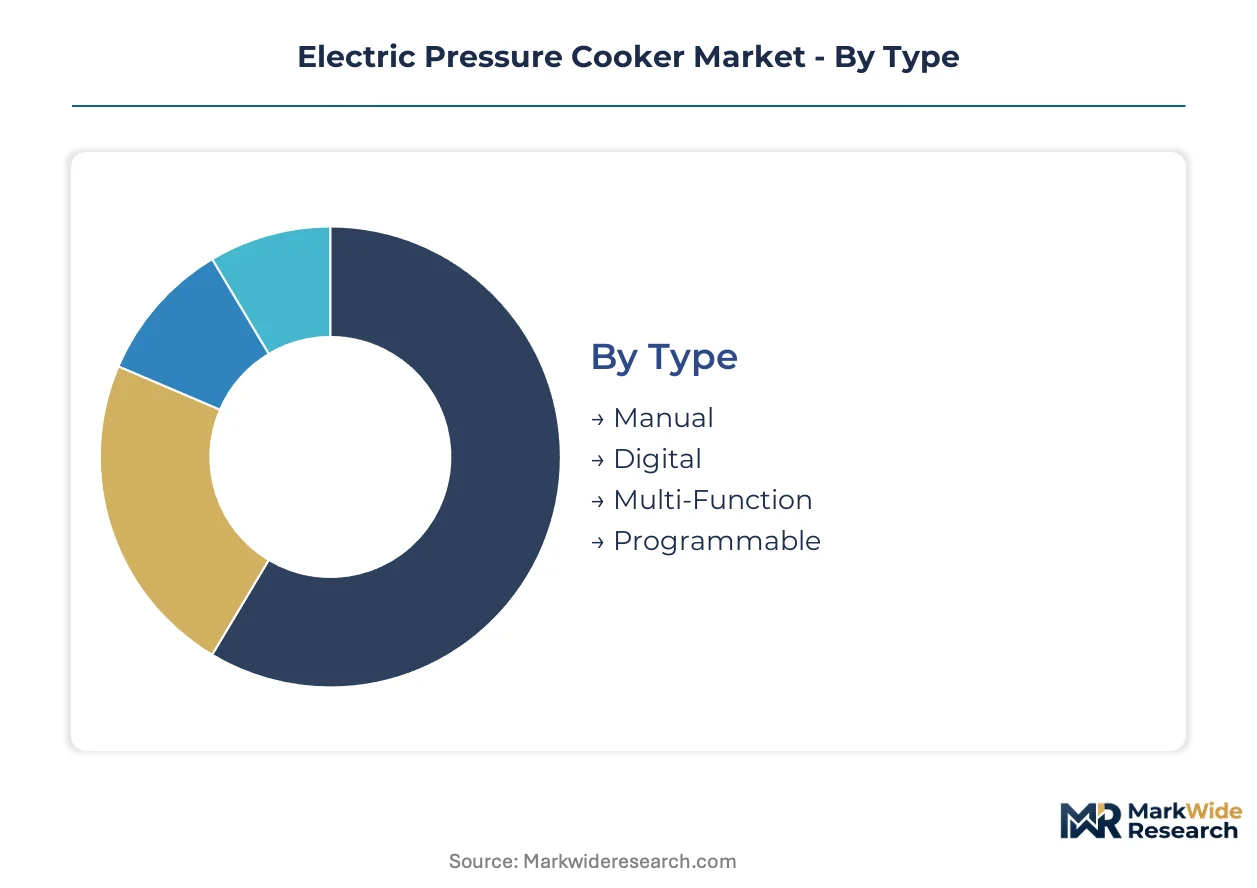
Segmentation in the electric pressure cooker market determines warranty exposure, spare parts forecasting, and service technician training intensity. Digital and programmable variants demand software update infrastructure and connectivity troubleshooting that manual units never require. Capacity and material selections further stratify failure modes and replacement part economics.
Type:
After-sales-service intensity varies dramatically across type segments, with connected models requiring ongoing firmware support and cloud-based recipe platform maintenance.
- Digital:Microprocessor-controlled interfaces with LCD displays and preset cooking programs dominate urban household purchases in China and the United States. Demand concentrates among time-constrained professionals seeking one-touch operation for grains and proteins, though embedded software certification under UL 1026 extends replacement timelines when control boards fail.
- Programmable:Wi-Fi-enabled units with app-based recipe synchronization and voice-assistant compatibility anchor manufacturer ecosystem strategies. North American consumers adopt these fastest, with subscription revenue potential for guided cooking content creating ongoing service relationships beyond the hardware sale.
- Manual:Mechanical valve-control systems with limited electronic components minimize field service requirements and appeal to price-sensitive rural markets.
- Multi-Function:Hybrid appliances combining pressure cooking with air frying, slow cooking, and sous vide capabilities expand use-case density per countertop unit.
By volume, Digital leads. By growth pace, Programmable is ahead.
Capacity:
Cost tier stratification in capacity segments reveals inverse relationships between unit margin and absolute price point, with mid-size variants optimizing manufacturing scale.
- 6 Quarts:The installed base standard for three-to-four-person households balances cooking surface area with countertop footprint. Chinese manufacturing clusters in Guangdong province achieve maximum production efficiency at this scale, driving procurement concentration among mass-market retailers.
- 8 Quarts:Batch-cooking functionality for meal-prep users and multi-generational households commands premium positioning. United States demand shows pronounced migration toward this bracket as household consolidation and weekend preparation habits reshape purchase patterns.
- 3 Quarts:Compact footprint targets single-person urban apartments and secondary vacation homes with limited kitchen space.
- 10 Quarts:Commercial-grade specifications serve institutional foodservice operators and restaurant kitchens requiring volume protein preparation.
By volume, 6 Quarts leads. By expansion trajectory, 8 Quarts is climbing the fastest.
Material:
Application durability requirements separate material segments, with thermal cycling resistance and cleaning protocol compatibility driving specification divergence.
- Stainless Steel:304-grade and 316-grade alloys deliver commercial-grade longevity and even heat distribution for restaurant kitchens. European foodservice operators under EU Ecodesign Directive efficiency mandates specify these for equipment replacement cycles, accepting higher upfront cost for total cost of ownership reduction.
- Non-Stick:PTFE and ceramic-reinforced coatings dominate entry-level consumer segments where easy cleanup outweighs durability concerns. China's domestic market shows heavy concentration here, with Guangdong and Zhejiang province manufacturers optimizing coating application throughput.
- Aluminum:Lightweight thermal conductivity supports budget-tier units, though base metal price volatility squeezes margin structures.
- Ceramic:Natural mineral-based surfaces appeal to health-conscious segments avoiding synthetic coatings, with limited scale due to brittleness constraints.
By volume, Stainless Steel leads. By share gain rate, Non-Stick is ahead.
Power Rating:
Customer type separation in power segments reflects kitchen infrastructure constraints and cooking speed priorities across residential versus commercial settings.
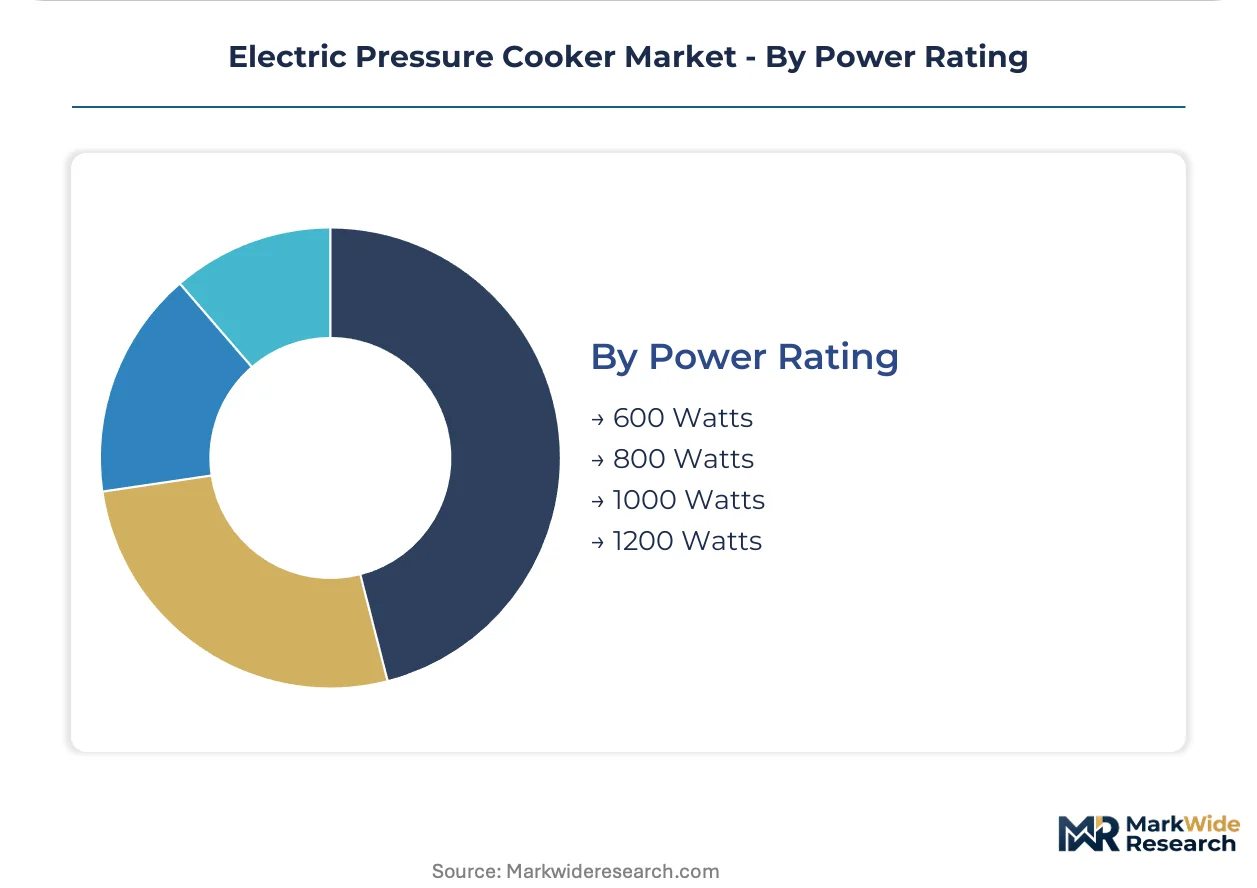
- 1000 Watts:The performance sweet spot for North American 120V residential circuits delivers rapid pressure buildup without dedicated wiring. Urban households in the United States and Canada concentrate purchases here, with heating element redesigns under efficiency mandates compressing development cycles.
- 1200 Watts:High-output configurations for commercial 240V installations and European 230V residential circuits reduce protein cooking times further. Professional kitchens and meal-prep operations adopt these for throughput maximization, accepting higher energy draw for labor time savings.
- 600 Watts:Low-power dormitory and RV-compatible units operate on restricted circuits with extended heating phases.
- 800 Watts:Entry-tier residential specification common in price-sensitive Asian markets with 220V infrastructure.
By volume, 1000 Watts leads. By growth pace, 1200 Watts is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy-efficiency mandates and right-to-repair legislation are reshaping procurement patterns across major national markets. Urban electrification rates and kitchen renovation cycles drive replacement demand in distinct regional configurations.
United States
Mass-market retailers consolidate shelf space around Wi-Fi-enabled programmable models as household penetration exceeds saturation thresholds in coastal metros. The Department of Energy appliance standards compress heating element redesign cycles for manufacturers serving the 120V residential circuit base. Chicago and Dallas distribution hubs channel inventory toward suburban big-box consolidation.
China
Domestic manufacturing clusters in Guangdong and Zhejiang provinces achieve maximum throughput efficiency for six-quart digital variants targeting urban middle-class kitchen upgrades. GB standards and NMPA-equivalent quality supervision protocols govern export-channel certification timelines. Shenzhen and Foshan industrial zones anchor global supply concentration for multi-function hybrid appliances.
Germany
EU Ecodesign Directive tiered energy-labeling thresholds accelerate replacement cycles for aging stovetop pressure cookers in efficiency-conscious households. CE marking obligations under EU appliance directives enforce baseline electrical safety standards that extend new product introduction schedules. Bavarian engineering consultancies specialize in thermal insulation layer redesign for European-market SKUs.
India
Rising electrification rates in tier-2 and tier-3 cities create whitespace for compact digital pressure cookers targeting nuclear family formations. BIS certification requirements for small kitchen appliances shape import-channel compliance costs for foreign manufacturers. Maharashtra and Karnataka urban corridors concentrate early adoption of programmable models among tech-sector professionals.
Japan
Space-constrained Tokyo and Osaka apartments drive demand for three-quart compact variants with precision temperature control. METI energy-efficiency labeling programs influence consumer preference toward low standby-power consumption designs. Nagoya-area component suppliers specialize in microprocessor-controlled pressure regulation systems for premium digital models.
Electric Pressure Cooker Market Competitive Landscape
On the supply side, the industry is consolidating around brand-recognition moats and ecosystem lock-in strategies. Specialty retailers and mass-market chains narrow direct-to-consumer channel access as shelf-space allocation tightens. Three archetypes dominate: ecosystem-platform builders, bundling-focused appliance families, and component-modularity specialists. Competitive moves center on strategic partnerships with recipe-content platforms and backward integration into heating-element manufacturing.
Within the ecosystem-platform tier, Chef iQ and Instant Pot exemplify divergent approaches to digital engagement. Chef iQ anchors app-connected recipe programming that manufacturers seek to replicate. Instant Pot occupies a position as the category-defining reference brand in North American retail. Among European-heritage fabricators, Breville sits within the premium-tier specialization vector.
| Leading Market Players |
|---|
| Our Place |
| Chef iQ |
| Instant Pot |
| COMFEE' |
| Zavor |
| Ninja Kitchen |
| T-fal |
| Blue Diamond |
| Breville |
| Others |
Pricing and Supply Chain Analysis
The Shenzhen-Long Beach maritime corridor's container cost dynamics compress margin structures for Guangdong-based manufacturers while amplifying price differentiation between CE-certified European SKUs and entry-level units bound for price-sensitive Asian markets.
Pricing Analysis
Certification level (UL 1026 versus GB standards) creates the primary spread between premium programmable models and manual entry-tier units. Three-tier pricing structure across premium, standard, and economy levels dominates, with Wi-Fi-enabled variants commanding positioning premiums over mechanical valve-control systems. Cost compression in the aluminum-clad entry tier is intensifying because base metal price volatility squeezes coating-application margins. Rural households in India's tier-3 cities exhibit highest price sensitivity, while European foodservice operators under EU Ecodesign Directive mandates show lowest elasticity due to total cost-of-ownership calculations.
Supply Chain Analysis
Stainless steel feedstock from Indonesia and nickel alloys from the Philippines feed Guangdong and Zhejiang province manufacturing clusters. Heating element assemblies draw from Japanese microprocessor suppliers and domestic Chinese coil fabricators. Single-source vulnerability concentrates in the Foshan industrial zone's pressure-valve component ecosystem. Distribution runs through Chicago and Dallas regional hubs for North American big-box retail allocation, with direct-container shipments serving European specialty appliance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where ecosystem lock-in through app-connected recipe platforms generates switching costs that protect incumbent positions against hardware commoditization.
For Market Incumbents: Pre-empt induction cooktop substitution by embedding voice-assistant compatibility and guided-cooking subscription tiers that deepen digital engagement. Backward integration into heating-element manufacturing in Guangdong secures cost control against aluminum volatility. Channel control through exclusive big-box shelf-space agreements limits emerging brand visibility. For New Entrants and Emerging Players: India's underpenetrated tier-2 urban corridors offer whitespace where rising electrification and nuclear family formations outpace established brand presence. Compact three-quart digital variants targeting space-constrained apartments bypass incumbent dominance in six-quart mass-market brackets. Direct-to-consumer launch via recipe-content platform partnerships sidesteps consolidated retail gatekeepers. For Investors and Strategic Acquirers: Component-modularity specialists with UL 1026 pre-certified pressure-valve architectures present acquisition targets as right-to-repair legislation spreads across U.S. statehouses. Long-term viability hinges on software-update infrastructure monetization rather than hardware replacement cycles. Watch for BIS certification timeline accelerations in India as signal of regulatory environment favoring import-channel entrants.| Strategic Initiative | Industry Significance |
|---|---|
| App Ecosystem Integration | Voice-assistant compatibility with Alexa and Google Home anchors recurring revenue streams beyond hardware sales. |
| Heating Element Backward Integration | In-house production of microprocessor-controlled coils reduces exposure to Japanese supplier lead time volatility. |
| Right-to-Repair Modular Design | Swappable pressure-valve architectures align with emerging state-level U.S. repair mandates. |
| EU Ecodesign Compliance Redesign | Thermal insulation layer investments preserve market access under tightening standby-power thresholds. |
| India Direct-to-Consumer Launch | Recipe-content platform partnerships bypass consolidated mass-market retail shelf-space constraints. |
Research Methodology
Cross-validation between appliance industry supply chain interviews and customs trade data anchors the qualitative findings in observable procurement patterns. Primary fieldwork engaged product development executives at multi-function appliance manufacturers, category buyers at North American big-box retailers, aftermarket service technicians, and thermal insulation engineering consultancies. Secondary sources included UL certification filing databases, EU Ecodesign Directive implementation reports, China customs export records, and BIS small appliance registration filings. Bottom-up SKU-level production estimates triangulate against top-down regional consumption models.
Calibration against historical replacement cycle data and efficiency-mandate acceleration patterns shapes the analytical framework across the analysis window. Segmentation dimensions encompass type tier (manual, digital, programmable, multi-function), capacity bracket, material specification, and power rating, crossed with regional regulatory cluster. CAGRs derive from installed base turnover velocity and urban household formation projections. Input assumptions include GB standards certification timeline compressions and EU energy-label threshold escalations.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem-platform investments by appliance-family conglomerates or sudden aluminum price spikes would shift outcomes. Cross-checking against NPD Group retail audit data and China Association of Small Household Appliance Manufacturers production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Smart Cooktop Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
On-The-Go Pots Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
Smart Induction Cooktop Market
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Electric Hobs Market