
 Digital BBQ Tongs and Thermometer Market | 2026-2036
Digital BBQ Tongs and Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital BBQ Tongs and Thermometer Market Outlook
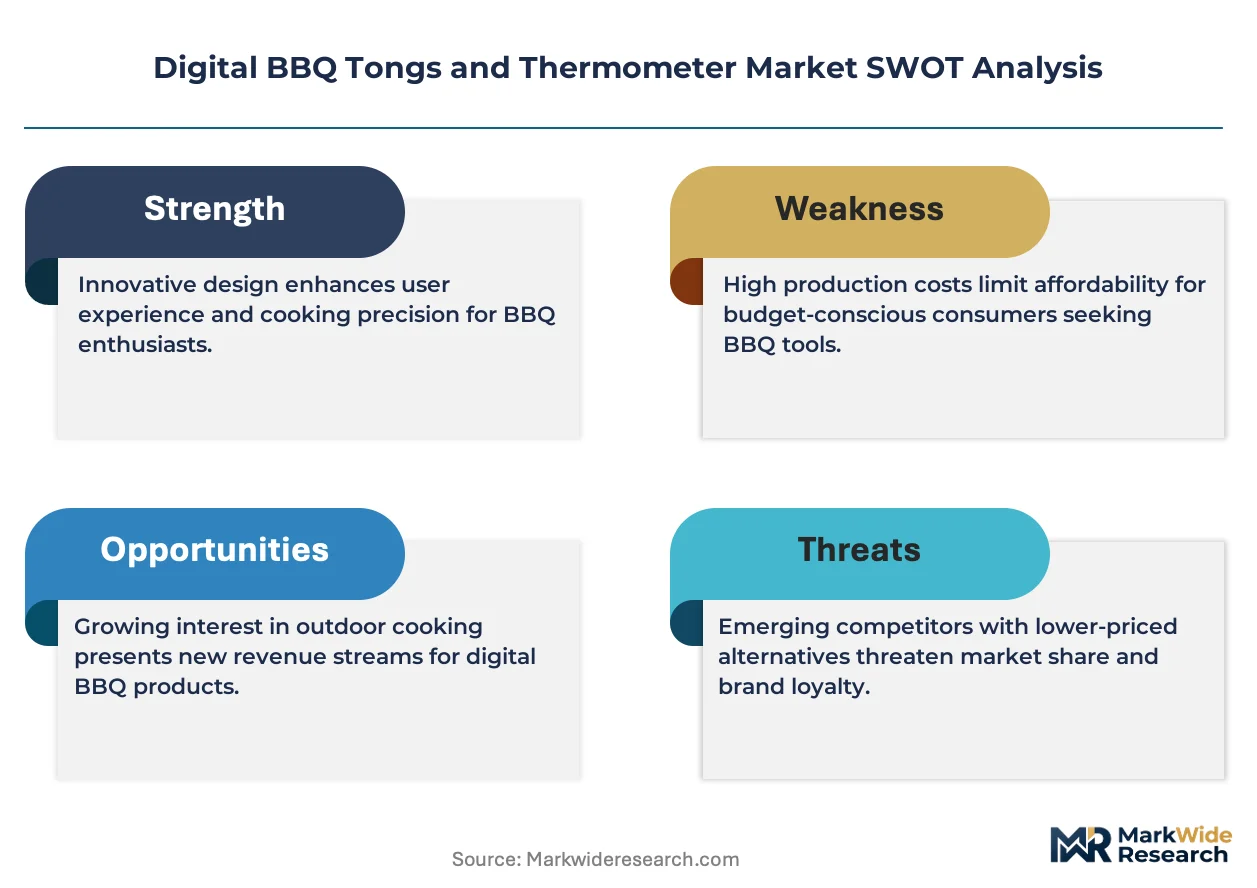
E-commerce direct-to-consumer channels are reshaping how digital BBQ tools reach end users, bypassing traditional big-box retail gatekeepers. ThermoWorks leverages its calibration laboratory reputation to sustain premium pricing across professional and enthusiast segments. Weber-Stephen Products anchors its position through bundled ecosystem sales with connected grills and proprietary app infrastructure. MEATER competes on true wireless design, eliminating probe cables that frustrate rotisserie and smoker users.
Digital BBQ tongs and thermometers comprise handheld or probe-based temperature measurement instruments integrated with electronic displays, wireless transmitters, and food-safe metallic alloys, typically achieving accuracy within one degree Fahrenheit and transmitting data via Bluetooth or Wi-Fi protocols to smartphone interfaces for real-time monitoring. Their primary commercial purpose centers on eliminating guesswork from protein doneness, reducing foodborne illness risk, and enabling remote supervision of extended smoking or roasting processes. The technology dimension shows Bluetooth-enabled probes leading volume while Wi-Fi configurations capture the highest margins through whole-home range and cloud logging capabilities. Stainless steel dominates material selection for probe shafts and tong bodies due to thermal resilience and regulatory acceptance, though silicone grips are gaining share for heat insulation and color-coded allergen management in catering environments.
The FDA governs food-contact material safety for probe coatings and tong surfaces under 21 CFR standards, while the FCC regulates radio frequency emissions from Bluetooth and Wi-Fi transmitters, creating dual compliance pathways that favor established manufacturers with dedicated certification teams. The EU's REACH framework and RoHS directives restrict hazardous substances in electronics sold across member states, pushing vendors toward lead-free solder and phthalate-free polymer components. Stakeholders must monitor evolving cybersecurity labeling requirements for IoT-connected kitchen devices, as consumer protection agencies in multiple jurisdictions draft baseline standards for data transmission and firmware update practices.
Market Dynamics
Wireless protocol standardization is compressing hardware margins while expanding software monetization potential across connected outdoor cooking ecosystems. Bluetooth Low Energy and Wi-Fi 6 chipsets now dominate bill of materials, forcing manufacturers to differentiate through firmware rather than sensor hardware.
Growth Catalysts
- FCC Part 15 Certification Streamlining:The FCC's modular approval pathway for radio frequency devices accelerates time-to-market for Bluetooth-enabled probe manufacturers. US-based vendors leverage pre-certified radio modules to reduce compliance timelines.
- Rotisserie and Smoker Enthusiast Expansion:Cable-free probe designs address the fastest-growing buyer segment in backyard grilling communities. True wireless architectures eliminate cable management failures during extended smoking sessions.
- REACH Compliance as Market Access Tool:EU RoHS and REACH directives on lead-free solder and phthalate-free polymers create competitive moats for compliant manufacturers. German precision-engineered tool vendors command premium positioning through documented substance safety.
Market Restraints
- Stainless Steel Price Volatility:Probe shaft and tong body production faces input cost pressure from nickel and chromium alloy markets. Thermal resilience requirements prevent material substitution to lower-grade metals.
- Probe Calibration Drift:Thermocouple accuracy degradation over repeated thermal cycling creates warranty liability and replacement cost burdens. Foodservice operators demand annual recertification protocols that increase total cost of ownership.
- Smartphone Dependency:Bluetooth-only configurations require continuous app connectivity, alienating users in remote outdoor locations without cellular coverage. Wi-Fi infrastructure requirements exclude rural and campground cooking environments.
Strategic Opportunities
- Catering and Commercial Kitchen Expansion:Color-coded silicone grips for allergen management address untapped institutional demand. Food-safe material documentation opens procurement channels with contract foodservice operators.
- Cloud Logging and Recipe Integration:Convergence of temperature telemetry with machine learning-driven doneness prediction creates subscription revenue potential. Whole-home Wi-Fi range enables data aggregation across multiple probe deployments.
- Cybersecurity Labeling Pre-emption:Early compliance with emerging IoT device security standards in consumer protection jurisdictions builds brand trust. Firmware update transparency protocols differentiate vendors ahead of mandatory labeling requirements.
Industry Challenges
- Embedded Systems Engineering Talent Scarcity:Firmware development for low-power wireless stacks requires specialized expertise concentrated in semiconductor hubs. Smaller manufacturers struggle to recruit RF engineers against consumer electronics compensation benchmarks.
- Dual Certification Timeline Compression:Simultaneous FDA food-contact material review and FCC radio frequency approval creates sequential bottlenecks. Documentation requirements for 21 CFR compliance and Part 15 testing extend product development cycles.
- Legacy Grill Integration Complexity:Proprietary app ecosystems from connected grill manufacturers fragment the interoperability landscape. Independent probe vendors face API access restrictions and firmware lockout from dominant platform owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital BBQ Tongs and Thermometer Market |
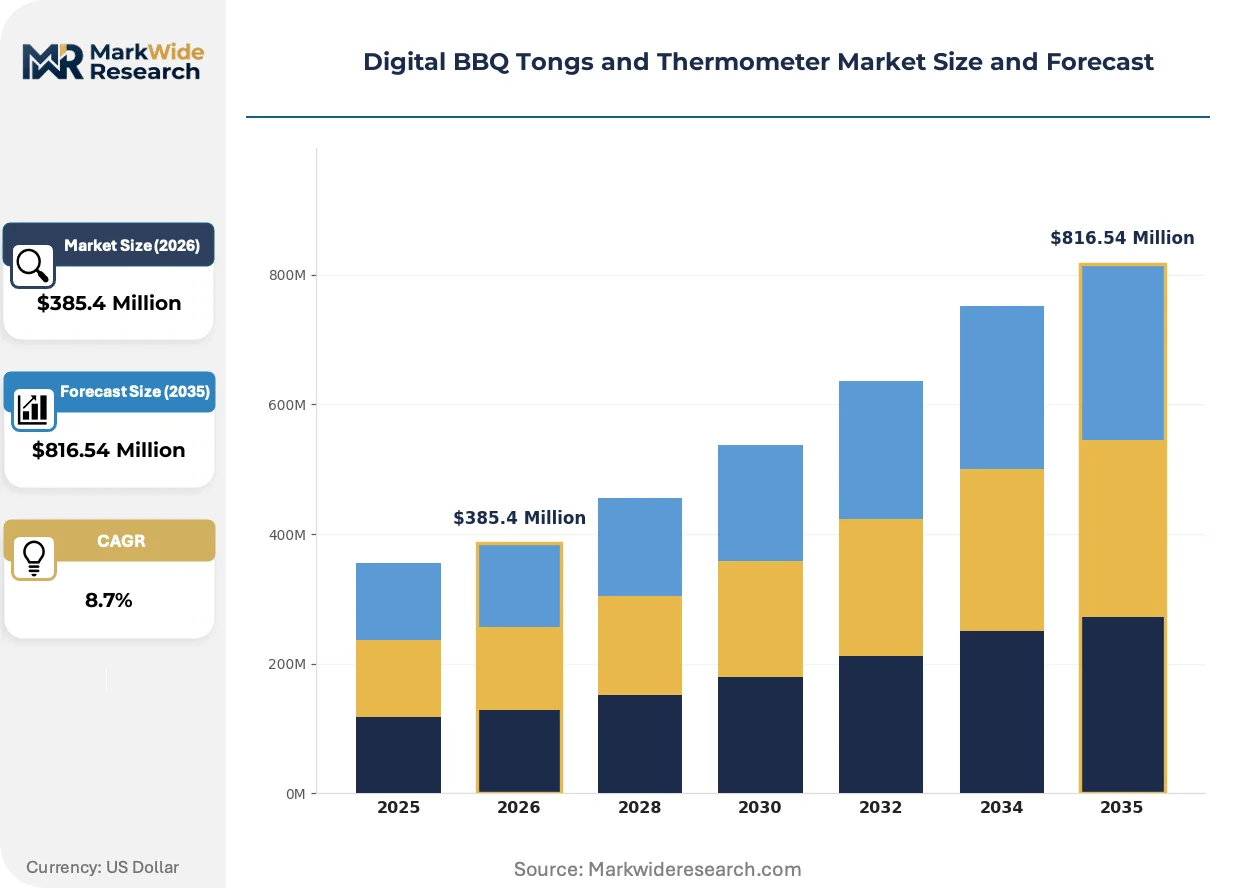
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tongs, Thermometer, Multi-tool, Grill Brush Technology: Digital, Analog, Bluetooth, Wi-Fi End User: Home Cooks, Professional Chefs, Catering Services, BBQ Enthusiasts Material: Stainless Steel, Plastic, Silicone, Wood |
| Companies Covered | ThermoWorks, Weber-Stephen Products, Char-Broil, Taylor Precision Products, MEATER, Alpha Grillers, ThermoPro, Inkbird, MAN LAW Australasia Pty Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital BBQ Tongs and Thermometer Market Strategic Shifts
Sensor miniaturization and edge computing architectures are redistributing functionality between probe hardware and smartphone software layers. Manufacturers now compete on algorithmic doneness prediction rather than raw temperature accuracy.
Multi-sensor probe arrays combining ambient pit temperature with internal protein readings are rendering obsolete single-point measurement devices. Competition barbecue teams and smoking enthusiasts adopt these configurations fastest, compressing demand for basic instant-read thermometers. The technology is rendering obsolete the standalone timer-and-probe category that dominated the 2010s.
REACH substance restrictions and RoHS hazardous substance limits are tightening material specifications for electronics sold across EU member states. Vendors face reformulation costs for solder alloys and polymer housing compounds. German and Austrian retailers now require full material disclosure documentation as a listing prerequisite.
Direct-to-consumer channel expansion is displacing traditional big-box retail gatekeepers for premium digital BBQ tools. E-commerce platforms enable calibration laboratory brands to sustain premium positioning without wholesale margin compression. This pattern concentrates most visibly in US backyard grilling communities, where enthusiast buyers research specifications independently before purchase.
Digital BBQ Tongs and Thermometer Market Segmentation
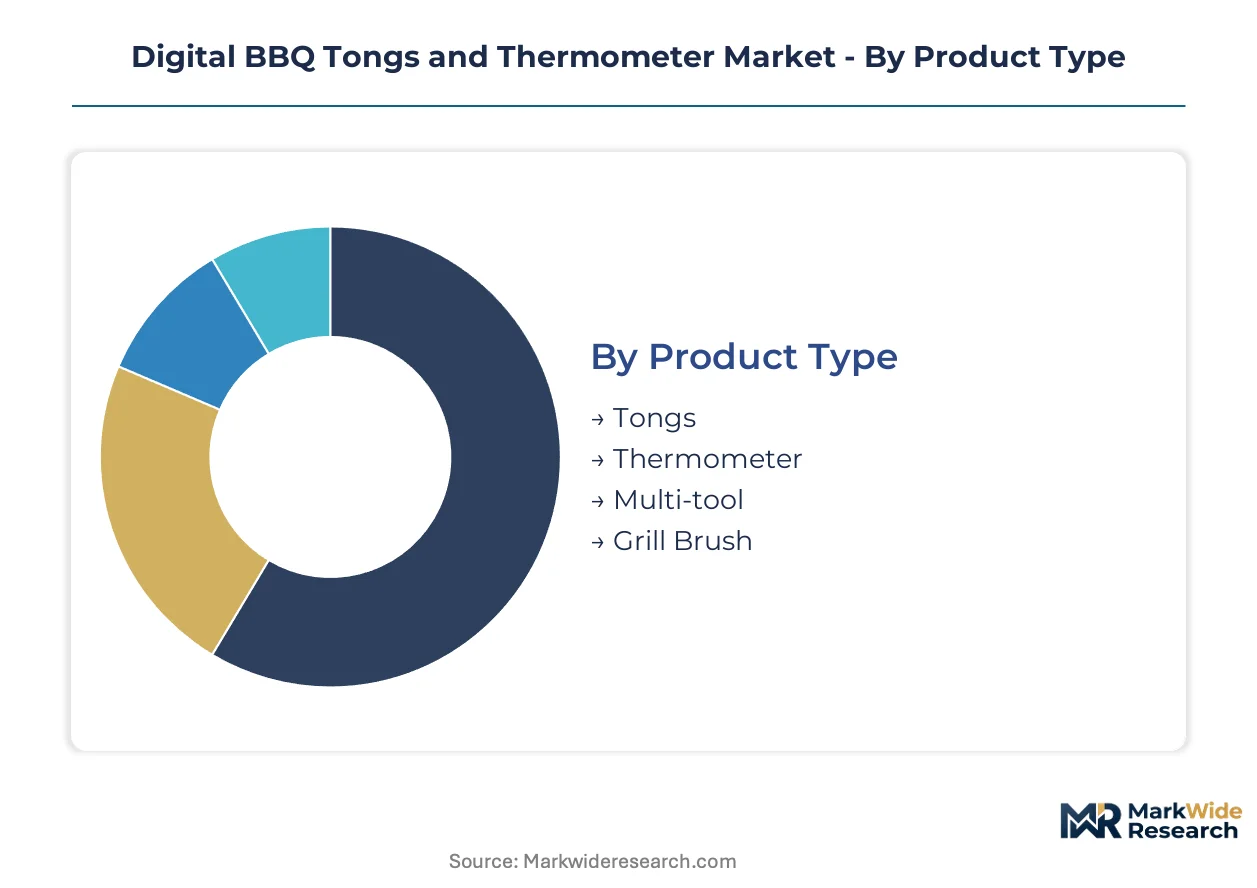
Segmentation in digital BBQ tools determines warranty exposure, calibration service frequency, and replacement part logistics. Manufacturers structure after-sales programs around technology tier and end-use intensity, with commercial kitchens demanding annual recertification while home users follow event-driven replacement cycles.
Product Type:
After-sales intensity varies sharply across product categories, with probe-based instruments requiring calibration support that tongs and brushes rarely need.
- Thermometer:Probe-based temperature instruments with thermocouple sensors achieve accuracy within one degree Fahrenheit. Demand concentrates among US backyard grilling communities where wireless connectivity eliminates guesswork from protein doneness. FDA food-contact material compliance and FCC radio certification create dual documentation burdens for manufacturers.
- Tongs:Handheld gripping tools with integrated digital displays or passive temperature indicators use stainless steel bodies with silicone grips for heat insulation. German precision-engineered variants command premium positioning through documented REACH substance safety and material traceability.
- Multi-tool:Hybrid instruments combining temperature sensing with gripping or basting functions. These address space-constrained outdoor kitchens and RV cooking environments.
- Grill Brush:Cleaning implements with minimal electronics integration, primarily analog bristle configurations with occasional scraper attachments. Replacement cycles follow wear patterns rather than technology obsolescence.
Thermometers hold the largest share; momentum sits with multi-tool configurations that reduce equipment clutter.
Technology:
Component sourcing strategies diverge across connectivity tiers, with Wi-Fi chipsets demanding more complex RF engineering talent than basic digital displays.
- Bluetooth:Low-energy radio protocols enable smartphone connectivity for real-time temperature monitoring. FCC Part 15 modular approval accelerates time-to-market for vendors using pre-certified radio modules. Backyard smoker enthusiasts drive adoption for cable-free probe designs that eliminate rotisserie cable management failures.
- Wi-Fi:Whole-home range protocols transmit data to cloud logging platforms and enable machine learning-driven doneness prediction. These configurations capture the highest margins through subscription revenue potential and multi-probe data aggregation.
- Digital:Standalone electronic displays without wireless connectivity, using button-cell batteries and LCD readouts. These serve price-sensitive segments and remote locations lacking smartphone dependency.
- Analog:Mechanical bimetallic strip or liquid-filled thermometer designs with no power requirements. Catering operators in institutional settings favor these for reliability in high-volume environments.
Bluetooth configurations hold the largest share; Wi-Fi is expanding most quickly through cloud-enabled ecosystem sales.
End User:
Procurement authority and specification complexity separate consumer from commercial segments, with foodservice operators demanding material documentation that home buyers rarely request.
- BBQ Enthusiasts:Backyard grilling communities with high engagement in smoking, rotisserie, and competition barbecue. True wireless probe architectures eliminate cable frustrations during extended cooking sessions. This segment researches specifications independently through direct-to-consumer channels.
- Catering Services:Contract foodservice operators requiring color-coded silicone grips for allergen management and annual probe recertification protocols. FDA 21 CFR compliance documentation opens procurement channels with institutional buyers.
- Professional Chefs:Restaurant kitchen staff prioritizing instant-read speed and durability under commercial use conditions. Calibration drift creates warranty liability concerns that increase total cost of ownership.
- Home Cooks:Occasional grilling households with seasonal equipment usage and lower price sensitivity to premium features. Smartphone dependency in Bluetooth-only configurations alienates users at rural properties.
BBQ Enthusiasts hold the largest share; Catering Services show the steepest expansion trajectory through institutional procurement standardization.
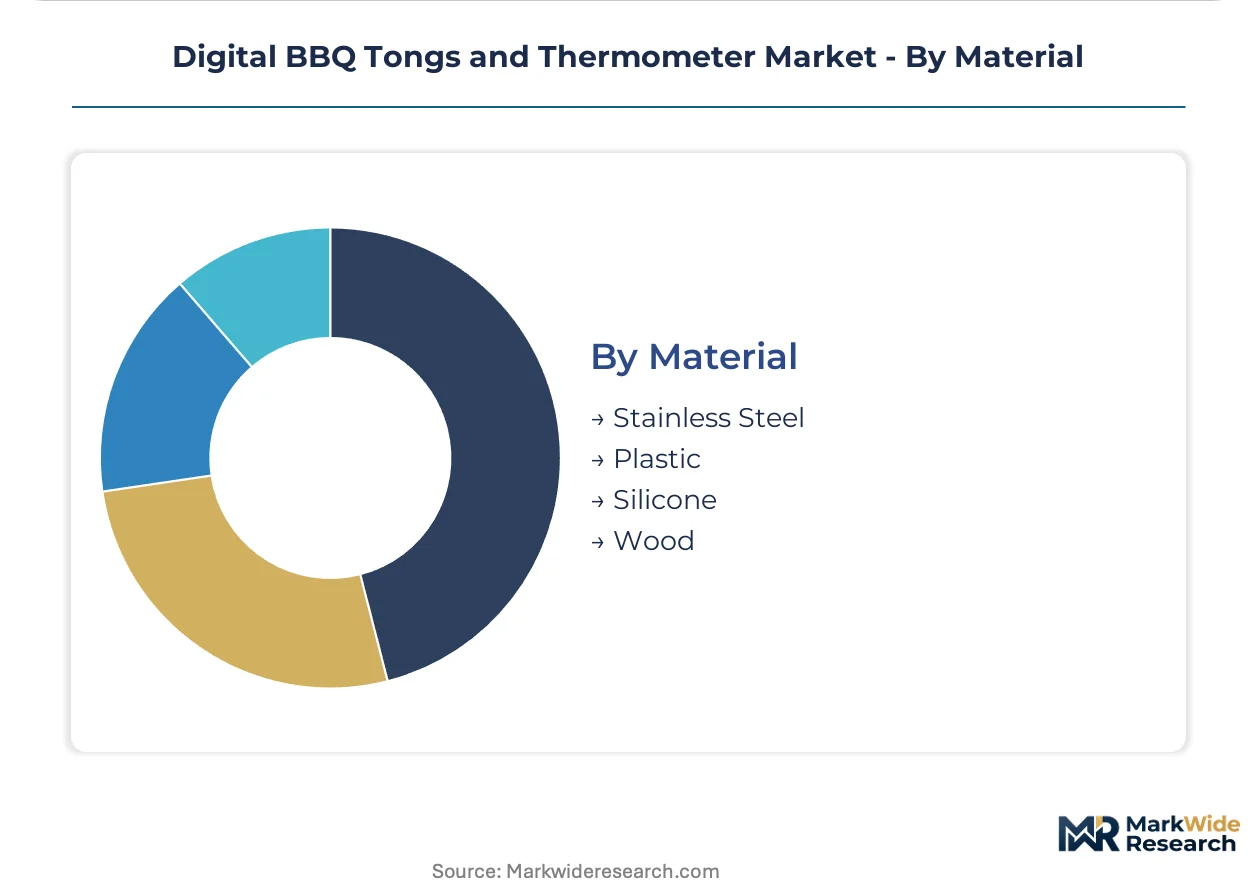
Material:
REACH substance restrictions and RoHS hazardous substance limits tighten specifications for electronics sold across EU member states, forcing reformulation of solder alloys and polymer compounds.
- Stainless Steel:Probe shafts and tong bodies use nickel-chromium alloys for thermal resilience and regulatory acceptance. Price volatility in alloy markets creates input cost pressure that prevents substitution to lower-grade metals.
- Silicone:Heat-insulating grip materials enable color-coded allergen management in catering environments. Phthalate-free formulations satisfy REACH compliance requirements for EU market access.
- Plastic:Polymer housing components for display units and battery compartments. Lead-free solder requirements under RoHS directives increase manufacturing complexity.
- Wood:Traditional handle materials with minimal electronics integration, primarily in analog thermometer variants. Thermal cycling limits restrict use in high-temperature probe applications.
Stainless Steel holds the largest share; Silicone is gaining share fastest through institutional allergen management requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC certification requirements for Bluetooth-enabled devices anchor the United States as the dominant geography, where backyard grilling communities drive wireless protocol standardization. FDA food-contact material standards under 21 CFR create compliance templates that manufacturers export to secondary markets.
United States
Backyard smoker enthusiasts and rotisserie hobbyists generate concentrated demand for cable-free probe architectures. FCC Part 15 modular approval pathways accelerate time-to-market for radio-frequency devices. Austin and Kansas City metropolitan areas host competition barbecue circuits that pressure-test wireless temperature telemetry under tournament conditions.
Germany
Precision-engineered grilling tools command premium positioning among enthusiast consumers demanding documented material traceability. REACH substance restrictions and RoHS hazardous substance limits enforce lead-free solder and phthalate-free polymer formulations. Stuttgart and Solingen industrial clusters specialize in stainless steel alloy processing for probe shafts and tong bodies.
China
Consumer electronics manufacturing ecosystems supply Bluetooth Low Energy and Wi-Fi 6 chipsets at compressed hardware margins. MIIT radio transmission regulations and GB standards for electronic products create dual certification workflows. Shenzhen and Dongguan metropolitan areas concentrate firmware development talent for low-power wireless stacks.
United Kingdom
Direct-to-consumer channel expansion through e-commerce platforms displaces traditional retail gatekeepers for premium digital BBQ tools. CE marking requirements and impending cybersecurity labeling standards for IoT devices shape compliance roadmaps. London and Birmingham urban grilling communities research specifications independently before purchase.
Australia
Outdoor cooking cultures in suburban and rural properties sustain demand for smartphone-independent digital displays. TGA-equivalent consumer product safety frameworks and ACMA radio communications standards regulate device imports. Melbourne and Sydney metropolitan areas host barbecue equipment retailers that curate Wi-Fi-enabled ecosystem products.
Digital BBQ Tongs and Thermometer Market Competitive Environment
Calibration-laboratory specialists and connected-grill ecosystem bundlers split the market between premium precision positioning and mass-market platform integration. Market structure shows moderate consolidation around established manufacturers with dedicated certification teams. Three strategic archetypes dominate: laboratory-grade calibration brands, bundled ecosystem providers, and true wireless design specialists. Competitive moves concentrate on firmware differentiation and strategic partnerships with connected appliance platforms.
Among laboratory-grade specialists, ThermoWorks anchors premium positioning through documented calibration protocols. Weber-Stephen Products exemplifies the ecosystem-bundler archetype with proprietary app infrastructure. MEATER occupies the true wireless design tier, eliminating probe cables that frustrate rotisserie and smoker users.
| Leading Market Players |
|---|
| ThermoWorks |
| Weber-Stephen Products |
| Char-Broil |
| Taylor Precision Products |
| MEATER |
| Alpha Grillers |
| ThermoPro |
| Inkbird |
| MAN LAW Australasia Pty Limited |
| Others |
Value Chain & Pricing Dynamics
Shenzhen-based chipset manufacturing clusters supply Bluetooth Low Energy and Wi-Fi 6 modules at compressed margins, concentrating value capture downstream in firmware development and cloud subscription tiers. This upstream concentration funnels margin pools toward vendors with proprietary algorithmic doneness prediction and multi-probe data aggregation capabilities.
Pricing Analysis
German precision-engineered variants command 40-60% premiums over mass-market alternatives through documented REACH substance safety and material traceability. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales calibration bundling. Cost compression in Bluetooth-only configurations is intensifying because pre-certified radio modules eliminate hardware differentiation. Home Cooks exhibit highest price sensitivity, while Catering Services accept premium positioning for allergen-compliant silicone grips and annual recertification protocols.
Supply Chain Analysis
Nickel-chromium alloy feedstock markets in Indonesia, South Africa, and Russia create input cost volatility for stainless steel probe shafts and tong bodies. Component sourcing draws from Chinese semiconductor fabs for wireless chipsets, German industrial clusters for precision alloy processing, and Malaysian polymer compounders for phthalate-free silicone formulations. Single-source vulnerability concentrates in FCC-certified radio module suppliers. Distribution runs through direct-to-consumer e-commerce platforms that bypass traditional big-box retail gatekeepers for premium digital BBQ tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless protocol standardization in outdoor cooking equipment signals early-cycle expansion, with cable-free probe architectures penetrating backyard grilling communities at accelerating rates.
For Market Incumbents: Pre-empt firmware commoditization by deepening proprietary app ecosystem integration and cloud logging subscription revenue. Threat from true wireless specialists demands backward integration into thermocouple sensor calibration laboratories. Certification investment in emerging cybersecurity labeling standards builds defensive moats ahead of mandatory IoT device requirements. For New Entrants and Emerging Players: Pursue untapped institutional procurement channels with color-coded silicone grip configurations for allergen management. Catering Services represent the most penetrable segment through FDA 21 CFR compliance documentation. Go-to-market angle should emphasize annual recertification service bundling that increases total cost of ownership stickiness. For Investors and Strategic Acquirers: Capital is best deployed toward laboratory-grade calibration brands with documented metrology protocols and established FCC certification teams. Long-term viability over a multi-year horizon favors vendors with hybrid hardware-software revenue models. Signal to watch: API access restrictions from connected grill manufacturers fragmenting interoperability and triggering consolidation pressure on independent probe vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Logging Platform Launch | Enables subscription revenue from MEATER and ThermoWorks enthusiast segments through machine learning doneness prediction. |
| REACH Compliance Certification | Opens German retail channels requiring full material disclosure documentation for lead-free solder and phthalate-free polymers. |
| Direct-to-Consumer Channel Expansion | Bypasses wholesale margin compression for calibration laboratory brands targeting US backyard grilling communities. |
| Multi-Sensor Probe Array Development | Addresses competition barbecue team demand for simultaneous ambient pit and internal protein temperature monitoring. |
| Cybersecurity Labeling Pre-emption | Differentiates vendors ahead of mandatory IoT device standards in consumer protection jurisdictions. |
Study Parameters
Cross-validation between primary interviews with product managers at wireless probe manufacturers and secondary analysis of FCC equipment authorization databases anchors the qualitative findings. Conversations with calibration laboratory directors, e-commerce category managers, and contract foodservice procurement officers informed demand segmentation. Secondary sources include FDA 21 CFR guidance documents, REACH substance restriction databases, and Bluetooth SIG certification listings. Bottom-up unit economics and top-down category spend estimates were triangulated for market sizing.
Calibration against historical adoption curves in connected kitchen devices refined the analytical framework across the modeling period. Segmentation dimensions include connectivity protocol, end-use intensity, material compliance tier, and regional regulatory cluster. CAGRs were derived from slope analysis of technology diffusion patterns and substitution effects against analog thermometer baselines. Forecast inputs incorporate FCC Part 15 certification timeline data and stainless steel alloy price indices.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending and nickel alloy commodity prices would shift the trajectory. Forecasts reflect assumptions about wireless protocol standardization velocity and regulatory compliance cost pass-through. Cross-checking against NPD Group retail audit data for outdoor cooking equipment is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Outdoor Cooking Equipment Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Sweden Kitchen Appliances Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Smart Induction Cooktop Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market