
 Global Smart Ovens Market | 2026-2036
Global Smart Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Ovens Market Outlook
Wi-Fi-enabled thermal precision is reorganizing how manufacturers tier their product portfolios. Samsung Electronics leverages its semiconductor supply chain to integrate proprietary chipsets that govern temperature algorithms. Whirlpool Corporation anchors its position through backward integration into sensor calibration facilities in the Midwest. LG Electronics differentiates via display-technology crossover from its television division.
Smart ovens are electric cooking appliances embedding microprocessor-controlled heating elements, IoT communication modules, and sensor arrays that enable remote monitoring, automated recipe execution, and energy-optimized thermal cycling. Built-in ovens command the highest margin pools among product types due to kitchen-renovation tie-ins and cabinetry integration requirements. Wi-Fi connectivity leads technology adoption as the backbone of whole-home automation platforms, while voice control captures the fastest expansion among residential users seeking hands-free operation during meal preparation.
FCC certification governs radio-frequency emissions for US-bound units, while CE marking and EU Ecodesign Directive compliance shape thermal-efficiency thresholds and standby-power limits for European market access. China's GB standards and MIIT radio-type approval create parallel certification tracks that fragment testing protocols for multinational suppliers. Stakeholders must decide whether to pursue modular platform architectures that accommodate regional regulatory divergence or accept higher compliance costs for unified global product lines.
Market Dynamics
The EU Ecodesign Directive is forcing manufacturers to redesign thermal systems and connectivity modules, while FCC certification and China's GB standards create divergent compliance tracks that reshape platform architecture decisions.
Growth Catalysts
- Urban condominium densification:Residential users in compact city dwellings seek space-efficient connected kitchen ecosystems that consolidate multiple cooking functions into single appliances.
- REACH substance restrictions:European chemical safety mandates accelerate material substitutions in heating-element coatings and insulation, creating upgrade cycles for compliant component sourcing.
- Voice interface maturation:Hands-free operation during meal preparation captures residential users seeking seamless integration with whole-home automation platforms.
Market Restraints
- Semiconductor supply concentration:Proprietary chipsets for temperature algorithms depend on concentrated East Asian foundry capacity, exposing manufacturers to input volatility.
- Copper and rare-earth magnet costs:Heating-element and motor assemblies face raw-material price swings that compress margin pools in mid-tier product lines.
- Legacy kitchen infrastructure:Existing cabinetry dimensions and electrical routing in renovated homes constrain built-in oven retrofit compatibility.
Strategic Opportunities
- India's premium appliance penetration:Underdeveloped smart-home penetration in urban Indian households creates first-mover positioning for Wi-Fi-enabled thermal precision systems.
- CE marking harmonization:Unified European compliance pathways reduce testing redundancy for manufacturers pursuing modular platform architectures.
- Display-technology convergence:Crossover from television-grade panel production enables touchscreen recipe visualization and streaming content integration.
Industry Challenges
- Firmware-engineering talent scarcity:Embedded systems development for real-time thermal cycling algorithms outpaces available skilled labor pools in Midwest manufacturing clusters.
- Multi-certification timeline compression:Parallel FCC, CE marking, and MIIT radio-type approval tracks extend product-launch cycles for unified global product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Ovens Market |
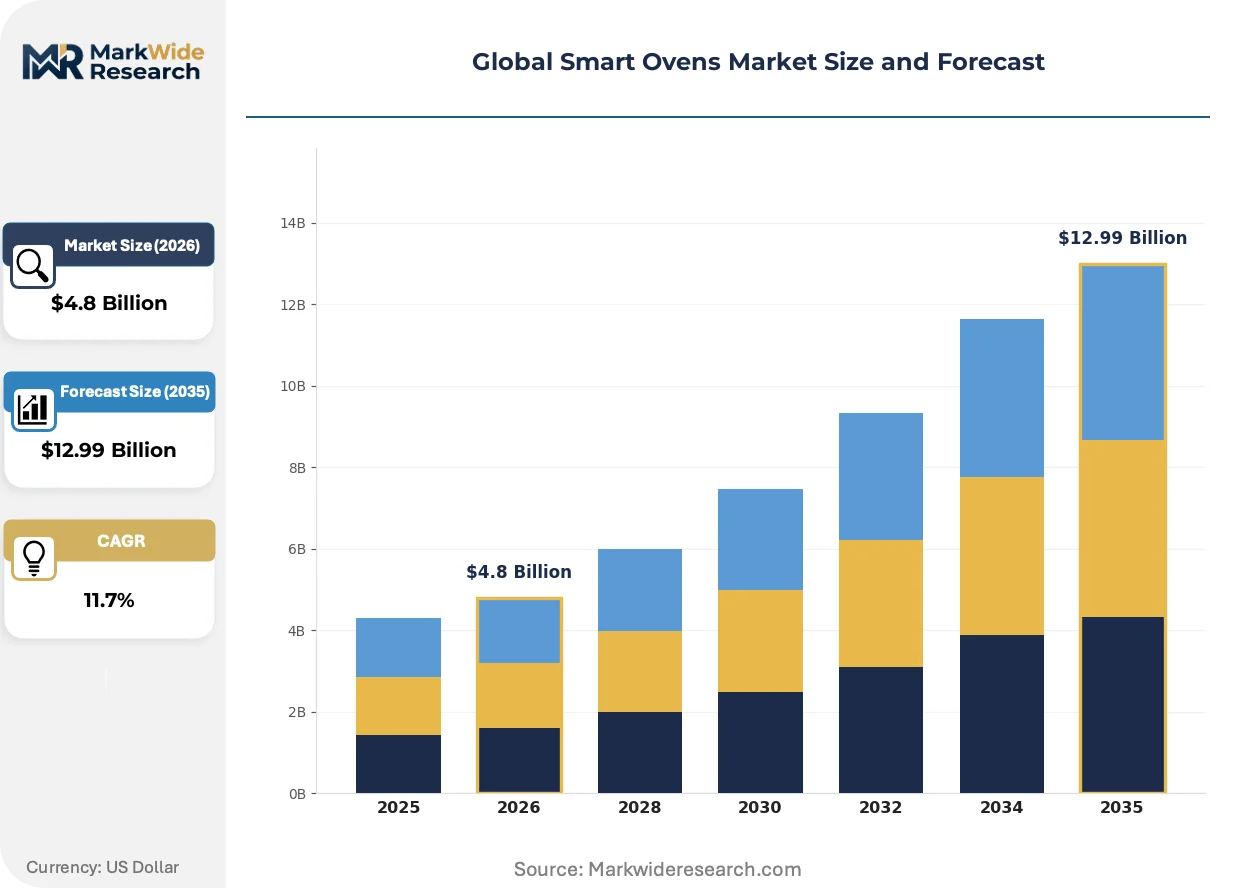
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in Ovens, Countertop Ovens, Range Ovens, Microwave Ovens Technology: Wi-Fi Connectivity, Bluetooth Connectivity, Voice Control, Touchscreen Interface End User: Residential Users, Commercial Users, Culinary Schools, Restaurants Feature: Self-Cleaning, Smart Diagnostics, Recipe Management, Multi-Cooking Modes |
| Companies Covered | Samsung Electronics, Whirlpool Corporation, LG Electronics, Bosch Group, Haier Group, Electrolux, Breville Group, Panasonic Corporation, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Ovens Market Strategic Shifts
Wi-Fi-enabled thermal precision is reorganizing competitive positioning as semiconductor integration, regulatory divergence, and residential automation preferences reshape product development priorities.
Sensor-array technology is fragmenting traditional temperature-control architectures. Multi-point thermal probes and infrared surface monitors enable real-time heat distribution mapping. Residential users in premium kitchen renovations adopt these systems for precision cooking of temperature-sensitive proteins. This capability is fragmenting the legacy single-probe standard into tiered accuracy specifications that separate professional-grade from mass-market offerings.
The EU Ecodesign Directive mandates standby-power limits and thermal-efficiency thresholds for European market access. Manufacturers must redesign heating-element insulation and power-management circuits to comply. Built-in ovens face the steepest redesign burden due to their higher energy ratings and longer replacement cycles, forcing suppliers to prioritize European-bound SKUs in engineering roadmaps.
Subscription-based recipe libraries are displacing static pre-programmed cycles as the primary software monetization path. Appliance brands now bundle cloud-connected culinary content with hardware sales. Urban condominium dwellers in the United States and Germany demonstrate highest attachment rates to these recurring-revenue models. This shift compresses the traditional five-year replacement cycle by creating ongoing service relationships that drive earlier trade-in decisions.
Global Smart Ovens Market Segmentation
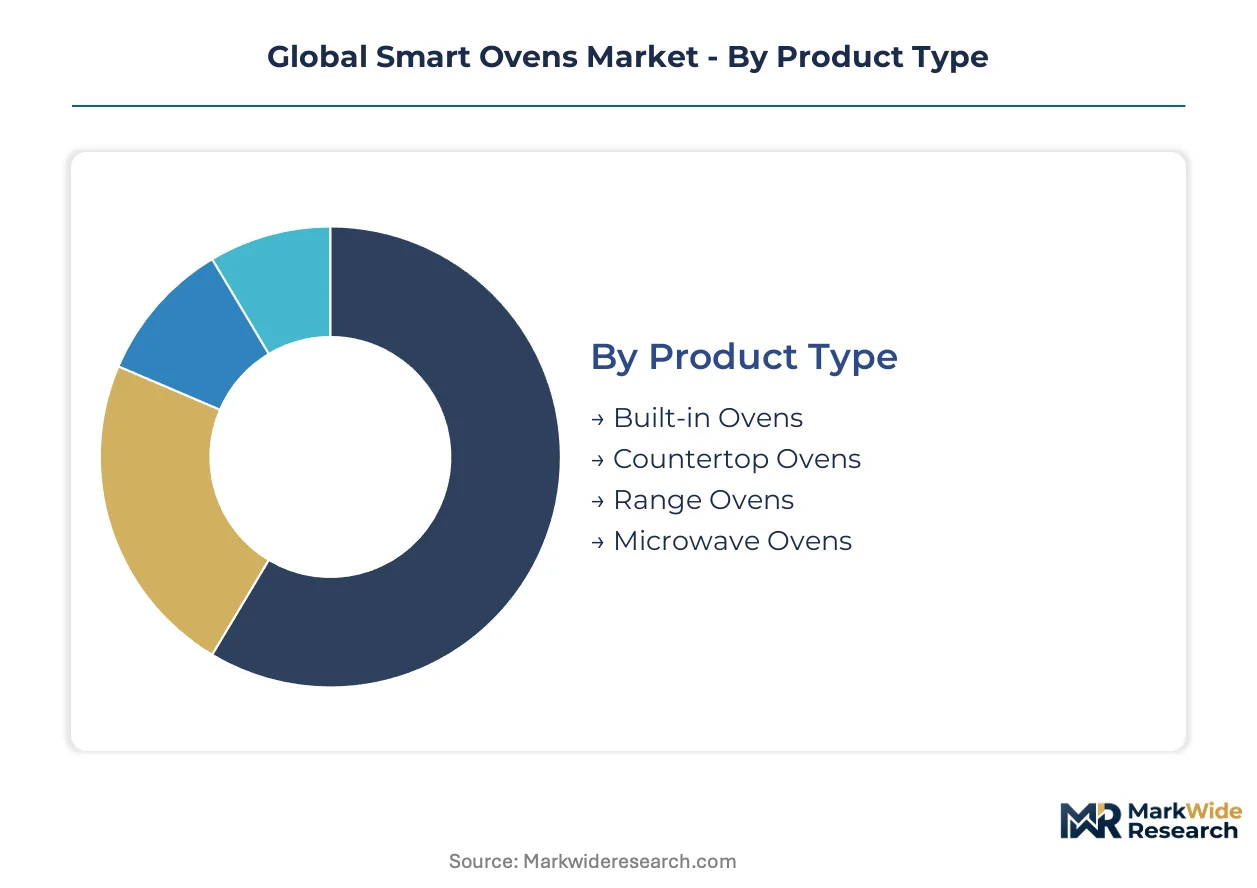
Smart oven segmentation reveals how hardware form factors, connectivity protocols, and user workflows fragment procurement decisions across residential renovations, commercial kitchens, and institutional training environments. Manufacturers must align thermal engineering investments with the distinct certification, durability, and software integration demands of each slice.
Product Type:
Built-in and range ovens dominate export-led demand from German and Chinese manufacturing hubs, while countertop variants serve primarily domestic North American and European markets through local assembly partnerships.
- Built-in Ovens:Cabinetry-integrated units with custom fascia panels and hardwired electrical connections. Demand concentrates in United States and Germany where premium kitchen renovations drive replacement cycles tied to whole-home automation upgrades.
- Countertop Ovens:Plug-in compact units with ventilated enclosures for open-surface operation. Urban condominium dwellers in Tokyo and New York adopt these for space-constrained cooking without cabinetry modifications.
- Range Ovens:Combined cooktop-oven assemblies requiring dedicated 240V circuits. These serve suburban residential retrofits in Australia and Canada where full-appliance replacement outpaces modular upgrades.
- Microwave Ovens:Magnetron-based units with added sensor arrays and IoT modules for remote monitoring. Commercial break-room installations in United Kingdom and South Korea represent the primary volume channel.
Built-in ovens command the established base. The steepest expansion runs through countertop ovens.
Technology:
Connectivity module selection directly determines certification burden and margin structure, with Wi-Fi and voice control requiring FCC, CE marking, and MIIT radio-type approvals that Bluetooth and basic touchscreen interfaces avoid.
- Wi-Fi Connectivity:IEEE 802.11 protocol stacks enabling cloud recipe synchronization and remote thermal monitoring. Whole-home automation platforms in United States and China mandate this capability as a baseline integration requirement.
- Bluetooth Connectivity:Short-range pairing for smartphone-based control without internet dependency. European markets with stricter data-localization requirements favor these lower-complexity implementations.
- Voice Control:Natural-language processing integration with Alexa, Google Assistant, and domestic Chinese alternatives. Residential users in Germany and Japan demonstrate highest attachment rates for hands-free operation during meal preparation.
- Touchscreen Interface:Capacitive or resistive panels for local recipe visualization and cycle programming. Culinary schools in France and Italy specify these for training environments where tactile feedback aids instruction.
Wi-Fi connectivity anchors the installed base. Voice control gains share fastest among premium residential specifications.
End User:
Residential procurement flows through retail and direct-to-consumer channels with 5-7 year replacement horizons, while commercial and institutional buyers operate on 10-15 year capital cycles with stricter NSF and HACCP compliance requirements.
- Residential Users:Individual households purchasing through appliance retailers or builder channels. Urban condominium densification in Shanghai and Mumbai drives demand for space-efficient connected kitchen ecosystems.
- Commercial Users:Corporate cafeterias, hotels, and catering operations requiring NSF-certified construction and multi-shift durability. These buyers prioritize remote diagnostics to minimize downtime across distributed kitchen portfolios.
- Culinary Schools:Accredited training institutions specifying equipment with precise temperature logging for curriculum standardization. Le Cordon Bleu campuses and equivalent programs in Switzerland and Japan represent concentrated demand nodes.
- Restaurants:Independent and chain operators seeking consistency across locations through cloud-based recipe deployment. Fast-casual concepts in United States and quick-service chains in South Korea lead adoption of networked thermal management.
Residential users represent the volume foundation. Restaurants show the steepest adoption trajectory for connected fleet management.
Feature:
Feature bundling stratifies pricing tiers, with self-cleaning pyrolytic cycles and smart diagnostics commanding premium positioning while multi-cooking modes and recipe management increasingly standardize across mid-tier offerings.
- Self-Cleaning:Pyrolytic or catalytic liner systems reducing manual maintenance. German and Austrian buyers treat this as non-negotiable in built-in specifications, driving regional SKU prioritization.
- Smart Diagnostics:Sensor-driven fault detection with predictive maintenance alerts. Commercial operators in United States and United Kingdom attach highest value to uptime protection and service-cost reduction.
- Recipe Management:Cloud libraries with automated thermal cycle programming. Subscription monetization models in North America and Western Europe convert these features into recurring revenue streams.
- Multi-Cooking Modes:Convection, steam, air-fry, and combination cycles within single enclosures. Countertop oven purchasers in Japan and South Korea demand maximum function density for compact kitchens.
Self-cleaning features dominate the established specification set. Smart diagnostics expand most quickly among commercial end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led manufacturing from Germany and China supplies premium built-in units to North American renovation markets, while domestic assembly partnerships in Mexico and Vietnam serve regional demand with reduced tariff exposure.
United States
Urban condominium densification in New York and Chicago accelerates demand for space-efficient countertop models with Wi-Fi connectivity. FCC certification governs radio-frequency emissions for all imported units. Appliance engineering clusters in the Midwest concentrate sensor calibration and firmware development activities.
Germany
Premium kitchen renovation cycles drive built-in oven replacement tied to whole-home automation upgrades. EU Ecodesign Directive mandates thermal-efficiency thresholds and standby-power limits. Manufacturing concentration in Bavaria and North Rhine-Westphalia anchors European supply for export markets.
China
Smart-home penetration in Shanghai and Shenzhen creates first-mover positioning for connected kitchen ecosystems. MIIT radio-type approval and GB standards fragment testing protocols for domestic-bound production. Yangtze River Delta clusters integrate semiconductor supply chains for proprietary chipset development.
Japan
Compact urban dwellings in Tokyo and Osaka favor multi-function countertop ovens with maximum cooking density. METI efficiency standards shape thermal system design for domestic market access. Kansai region manufacturers leverage precision engineering capabilities for sensor-array production.
South Korea
Quick-service restaurant chains adopt networked thermal management for fleet consistency across locations. MFDS-equivalent appliance safety frameworks align with international certification requirements. Seoul Capital Area hosts display-technology crossover from television-grade panel production.
Global Smart Ovens Market Competitive Environment
Listed leaders compete with private specialists across semiconductor integration and thermal engineering capabilities. The vendor base organizes into three tiers: diversified electronics conglomerates with captive chip supply, pure-play appliance manufacturers with backward integration into sensor facilities, and regional specialists focused on compact countertop segments. Strategic moves concentrate on modular platform architectures accommodating regulatory divergence and subscription-based software monetization.
Among diversified electronics conglomerates, Samsung Electronics exemplifies semiconductor supply chain leverage, while LG Electronics occupies a position bridging display-technology crossover. Whirlpool Corporation anchors the pure-play appliance tier with Midwest-based sensor calibration infrastructure. These three represent distinct competitive archetypes: chip-captive integration, panel-technology convergence, and manufacturing-cluster proximity.
| Leading Market Players |
|---|
| Samsung Electronics |
| Whirlpool Corporation |
| LG Electronics |
| Bosch Group |
| Haier Group |
| Electrolux |
| Breville Group |
| Panasonic Corporation |
| GE Appliances |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Yangtze River Delta foundries lock in semiconductor access and thermal sensor pricing visibility for built-in oven manufacturers serving German and US renovation markets. These arrangements insulate premium tier producers from spot-market volatility in copper heating elements and rare-earth magnet assemblies while exposing mid-tier competitors to raw-material cost compression.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Built-in ovens with CE marking and FCC certification command premium positioning due to multi-certification engineering overhead, while countertop variants face price erosion from private-label competition in North American retail channels. Residential users in urban condominiums demonstrate highest price sensitivity, whereas commercial operators prioritize total cost of ownership over upfront acquisition.
Supply Chain Analysis
Container availability constraints on the Shanghai–Los Angeles trade lane elevate inbound logistics costs for semiconductor-dependent thermal control modules. Supply concentrates in China for IoT connectivity chipsets, South Korea for display panels, and Germany for precision sensor arrays. Heating-element assemblies draw from concentrated copper and rare-earth magnet sourcing, creating single-source vulnerability for temperature algorithm hardware. Distribution runs through appliance retail networks and direct-to-builder channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-based recipe platforms that displace appliance-bound thermal programming, requiring defensive moves to retain hardware-software integration value.
For Market Incumbents: Shield proprietary temperature algorithm ecosystems through backward integration into Midwest sensor calibration facilities. Deepen firmware engineering capabilities to offset talent scarcity in embedded systems development. Counter cloud-platform substitution by bundling subscription recipe libraries with hardware trade-in programs. For New Entrants and Emerging Players: Differentiate on modular platform architectures that accommodate divergent FCC, CE marking, and MIIT radio-type approval tracks without unified global SKU engineering. Target India's underdeveloped smart-home penetration for first-mover positioning in Wi-Fi-enabled thermal precision. Pursue culinary school procurement channels where tactile touchscreen interfaces drive specification decisions. For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor-captive appliance specialists with proprietary chipset development capabilities in the Yangtze River Delta. Long-term viability hinges on defensible thermal engineering IP rather than assembly-scale advantages. Monitor EU Ecodesign Directive threshold tightening as an inflection signal for compliance-cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Supply Agreement | Proprietary chipset access from Yangtze River Delta foundries secures temperature algorithm differentiation against pure-play appliance competitors. |
| Modular Platform Architecture | Regional certification modules accommodate FCC, CE marking, and MIIT divergence without unified global product line engineering overhead. |
| Subscription Service Launch | Cloud recipe libraries convert hardware sales into recurring revenue streams with highest attachment rates among German and US urban condominium dwellers. |
| Sensor Calibration Facility Expansion | Midwest-based backward integration into thermal probe calibration reduces dependency on concentrated East Asian foundry capacity. |
| Display Technology Crossover | Television-grade panel production from Seoul Capital Area enables touchscreen recipe visualization and streaming content integration. |
Study Parameters
A standing panel of appliance engineering directors, IoT platform architects, retail category buyers, and commercial kitchen procurement managers provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with firmware development leads at Midwest manufacturing clusters and thermal sensor specialists in Bavaria and the Yangtze River Delta. Secondary validation drew from FCC equipment authorization databases, EU Ecodesign Directive compliance registries, MIIT radio-type approval filings, and customs trade records for heating-element and semiconductor imports. Bottom-up unit shipment estimates triangulated against top-down value projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, connectivity protocol, end-user category, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, smart-home penetration trajectories, and premium appliance trade-in velocity. Forecast inputs incorporated EU Ecodesign Directive threshold evolution, semiconductor foundry capacity expansion, and voice interface adoption curves among residential users.
The analysis sits within stated boundaries; outcomes outside sustained smart-home ecosystem expansion and stable East Asian foundry capacity would require recalibration. Forecasts reflect assumptions regarding regulatory harmonization timelines, raw-material price stability, and firmware engineering labor pool growth. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Toaster Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
On-The-Go Pots Market
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
Household Kitchen Appliances Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Residential Hobs Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
Russia Kitchen Appliances Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market