
 Commercial Tabletop Kitchen Products Market | 2026-2036
Commercial Tabletop Kitchen Products Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Tabletop Kitchen Products Market Intelligence
A scarcity of trained chefs and hospitality staff is bifurcating product demand toward either highly specialized or extremely durable, easy-to-use items. This shift benefits established brands known for reliability under stress. Villeroy & Boch leverages its brand heritage in the premium porcelain segment for fine dining establishments. In contrast, Steelite International specializes in durable and chip-resistant tableware engineered for high-turnover environments like hotels and large-scale catering.
Commercial tabletop kitchen products refer to durable dinnerware, flatware, glassware, and cookware engineered for repeated, high-volume use in food service settings. These items must meet specific performance criteria, such as resistance to thermal shock and industrial dishwashing chemicals. The tableware segment, particularly in porcelain and stainless steel, constitutes a significant portion of the market. Demand from hotels and full-service restaurants drives the premium material segments, while utilitarian plastic and glass items serve quick-service restaurants and cafes.
Product compliance is governed by stringent food contact material regulations. In the United States, the FDA sets guidelines for substances used in cookware and tableware, while in Europe, the EFSA enforces similar standards under Regulation (EC) 1935/2004. Manufacturers must navigate these and other national rules, like China's GB standards, to ensure market access. Future success depends on balancing material innovation with evolving global food safety and sustainability mandates.
Market Dynamics
The central structural force shaping the market is the bifurcation of product requirements, driven by a persistent scarcity of skilled hospitality labor. This pressures operators to choose between highly specialized equipment for trained chefs or exceptionally durable, easy-to-use products for high-turnover staff.
Growth Catalysts
- Hospitality Sector Expansion:The construction of new luxury hotels and resorts in major metropolitan hubs, particularly in the Middle East and Asia, creates concentrated pockets of demand for premium tabletop products.
- Catering Services Growth:An expansion in corporate and social event catering is driving volume sales, especially for durable and stackable dinnerware, glassware, and flatware designed for transport and high-frequency use.
- Material Regulation Compliance:Stricter food contact material standards, such as the EU's EFSA regulations, are spurring innovation in safer, compliant materials like lead-free porcelain and advanced polymers, creating new product categories.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of key inputs like stainless steel, high-purity clays for porcelain, and energy create pricing instability and margin pressure for manufacturers.
- Regulatory Fragmentation:Manufacturers face complex compliance hurdles, needing to meet disparate standards such as the FDA's guidelines in the US, EFSA rules in Europe, and GB standards in China.
- Substitution from Lower-Cost Alternatives:In segments like quick-service restaurants and institutional catering, traditional ceramic and metal products face competition from advanced, durable plastic and melamine alternatives.
Strategic Opportunities
- Emerging Tourism Markets:Developing hospitality sectors in regions like Southeast Asia and Latin America represent significant white space for tabletop product suppliers as new hotels and restaurants are established.
- Smart Tableware Integration:Incorporating technologies like RFID tags into dinnerware offers opportunities for automated inventory management in large-scale operations, creating a new value proposition for hotel and catering clients.
- Direct-to-Business E-commerce:Developing online sales channels allows manufacturers to directly reach small-to-medium-sized businesses like independent cafes and restaurants, bypassing traditional distributor networks.
Industry Challenges
- Skilled Labor Shortages:A lack of trained chefs and service staff within the end-user hospitality industry influences product design, demanding greater simplicity and durability over complex, specialized features.
- Supply Chain Resilience:Balancing cost-effective, long-distance manufacturing with the need for shorter lead times and reduced geopolitical risk is forcing a costly re-evaluation of global supply chain configurations.
- Certification Lead Times:The time and expense required to achieve food contact safety certifications for new materials across multiple jurisdictions can delay product launches and limit market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Tabletop Kitchen Products Market |
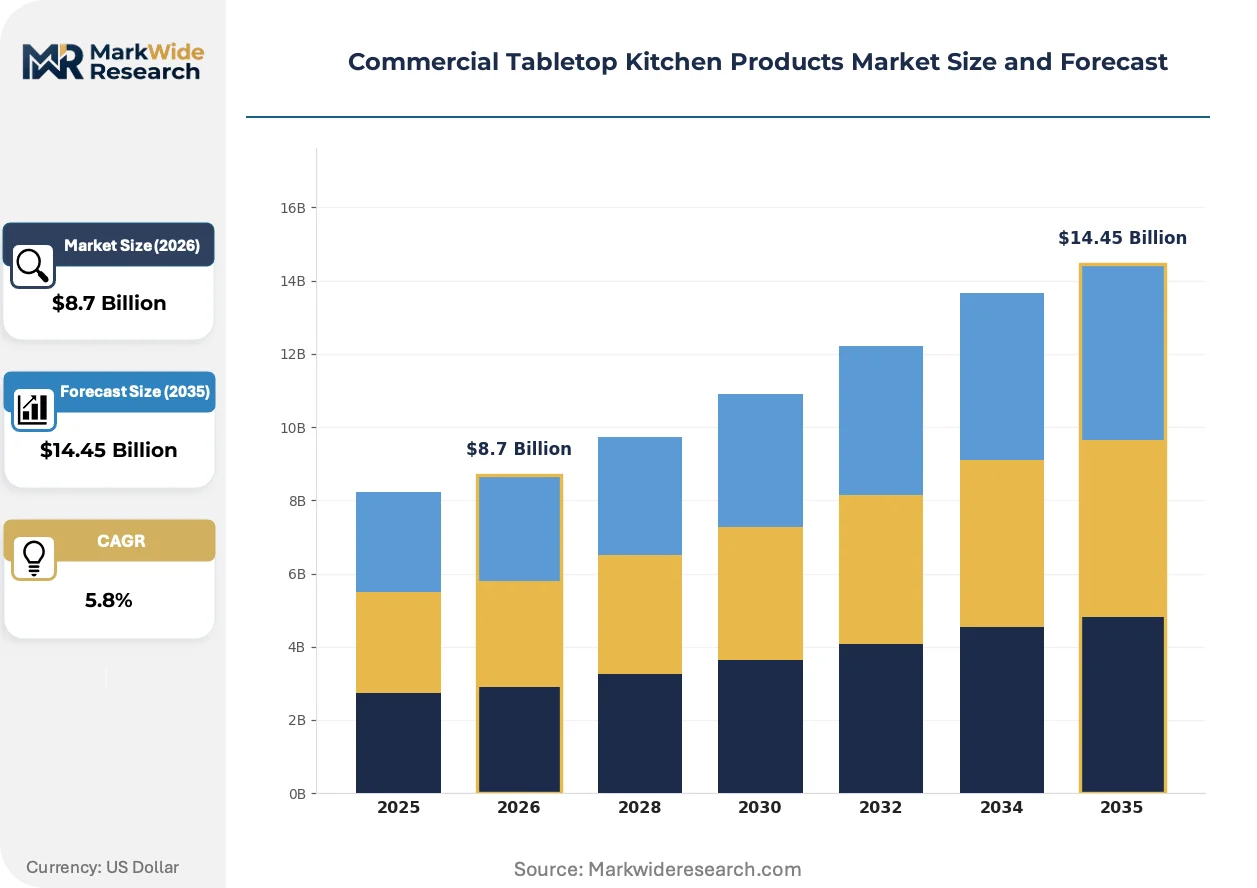
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tableware, Cookware, Glassware, Utensils Material: Porcelain, Stainless Steel, Glass, Plastic End User: Restaurants, Cafés, Catering Services, Hotels Distribution Channel: Online Retail, Distributors, Wholesalers, Supermarkets |
| Companies Covered | Villeroy & Boch, Lenox Corporation, The Oneida Group, Lifetime Brands, BHS Tabletop AG, Arc International, The Vollrath Company, Steelite International, Libbey Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Tabletop Kitchen Products Market Strategic Shifts & Innovations
Material science advancements and evolving operational demands from the hospitality industry are reshaping product development. The focus is on creating items that either enhance the fine dining experience or withstand the extreme rigors of high-volume food service with minimal staff skill.
Advanced material composites, particularly in ceramics and polymers, provide enhanced durability and chip-resistance. High-turnover establishments like large hotel chains and institutional caterers are the primary adopters of these engineered products. This development is bifurcating the market, separating premium, aesthetic-focused porcelain for fine dining from performance-driven materials designed for operational efficiency and lower replacement costs.
The European Union's Regulation (EC) 1935/2004 for food contact materials sets stringent migration limits for substances like lead and cadmium. This directly impacts manufacturing processes, especially for ceramic and enameled products. The porcelain and glassware segments are most affected, investing heavily in lead-free glazes and rigorous quality control to ensure compliance and maintain access to the European market.
Sustainability criteria are becoming a key factor in purchasing decisions within the hospitality sector. This shift pressures suppliers to provide transparent data on their products' lifecycle, from raw material sourcing to end-of-life recyclability, moving beyond simple durability metrics. The trend is most visible in corporate hotel chains across North America and Europe, where environmental, social, and governance (ESG) mandates influence procurement standards.
Commercial Tabletop Kitchen Products Market Segmentation
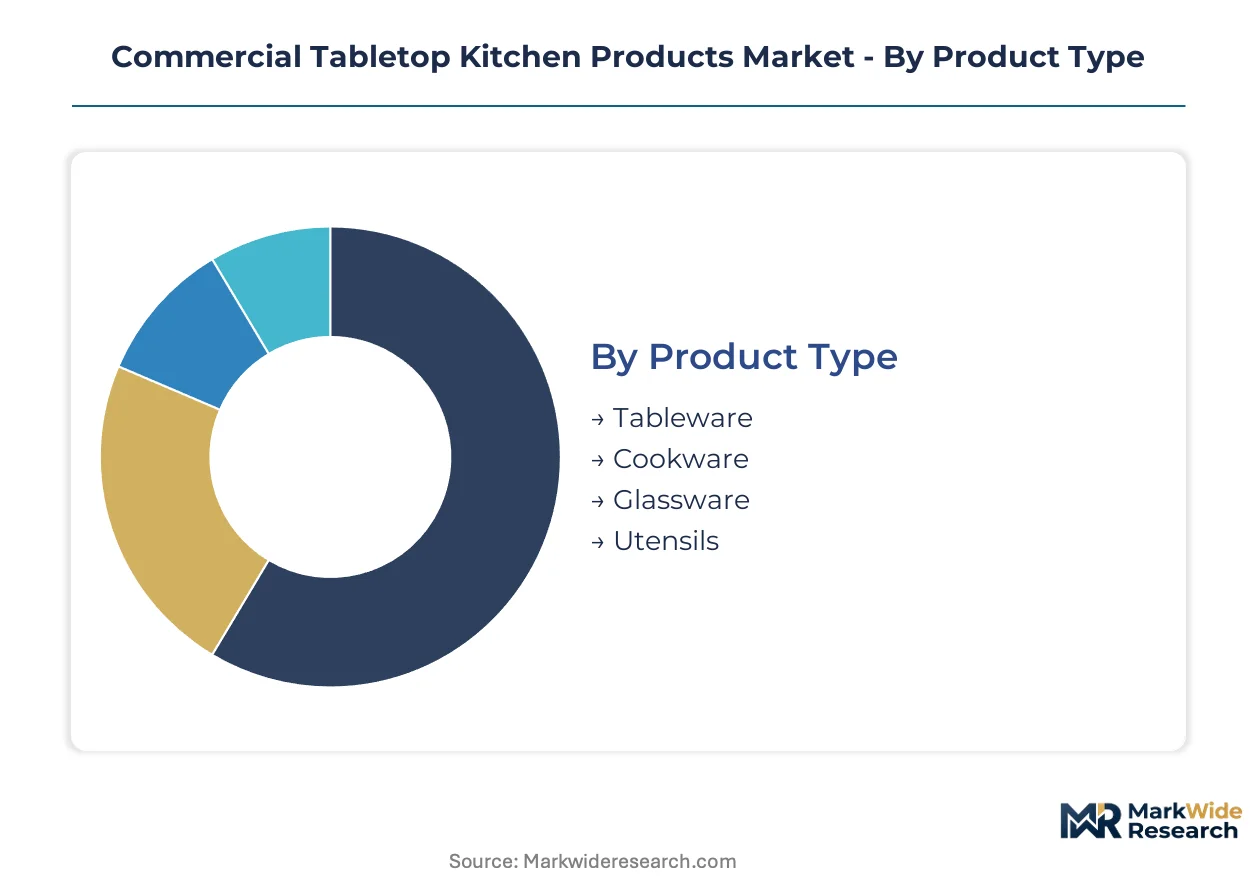
Understanding the distinct segments within the commercial tabletop kitchen products market is critical for manufacturers to tailor product development and market strategies. Each category reflects varying demands based on operational scale, aesthetic requirements, and compliance standards across the hospitality sector.
Product Type:
The product type segmentation highlights how different items cater to specific operational needs, with some segments showing stronger export potential than others due to specialized manufacturing capabilities or unique regional demand patterns.
- Tableware:This segment includes dinnerware, flatware, and serving pieces, frequently crafted from porcelain, ceramic, or stainless steel. Demand is robust from European fine dining establishments, which prioritize aesthetic design and material quality for their guest experience.
- Cookware:Encompassing pots, pans, and baking dishes, cookware is typically made from durable stainless steel or aluminum for high-volume kitchen use. The rapid expansion of catering services in the Middle East drives significant demand for robust, stackable cookware designed for frequent transport.
- Glassware:Comprises various beverage glasses and decanters, with manufacturers needing to meet stringent EFSA regulations for market access in Europe.
- Utensils:This category covers a wide range of serving tools and cutlery, experiencing high demand from quick-service restaurants in North America for their utilitarian design.
Tableware holds the largest share; momentum sits with Cookware.
Material:
Material choices define product performance and cost structures, with premium materials dominating high-end applications while more economical options serve volume-driven sectors.
- Porcelain:A premium ceramic material prized for its thermal shock resistance, chip durability, and elegant appearance, primarily used in high-end dinnerware. Luxury hotels in major metropolitan hubs like London and Dubai consistently procure lead-free porcelain for their fine dining and banquet services.
- Stainless Steel:Valued for its exceptional durability, corrosion resistance, and ease of sanitation, stainless steel is the material of choice for flatware and heavy-duty cookware. Corporate catering services across Germany increasingly specify stainless steel items for their longevity under rigorous industrial washing conditions.
- Glass:Used extensively for beverage service and certain serving pieces, with manufacturers in the United States adhering to strict FDA guidelines for food contact safety.
- Plastic:Offers a lightweight, shatter-resistant, and cost-effective alternative, widely adopted by quick-service restaurants and institutional catering facilities in China for high-volume, low-cost operations.
Stainless Steel leads the category in sales, while Porcelain is gaining share fastest.
End User:
The end-user segmentation illustrates how diverse hospitality operations influence product specifications, from aesthetic-driven choices in hotels to durability-focused procurement in catering services.
- Hotels:These establishments require a comprehensive range of durable and aesthetically pleasing tabletop products for various dining venues, from casual breakfast buffets to upscale restaurants. New luxury hotel developments in Singapore and Saudi Arabia specifically drive demand for premium, customized tabletop items.
- Restaurants:Spanning fine dining to casual eateries, restaurants influence product choices from specialized, artisan porcelain to robust, chip-resistant ceramics. Independent restaurants in France often prioritize unique dinnerware and glassware that complement their specific culinary themes and brand identity.
- Cafés:Primarily demand utilitarian and easy-to-clean items such as mugs, small plates, and basic cutlery, designed for high-turnover service.
- Catering Services:Focus on stackable, transport-friendly, and highly durable tableware and glassware, essential for large-scale events and off-site food delivery.
Demand from Hotels drives the majority of volume, with Catering Services exhibiting steepest expansion trajectory.
Distribution Channel:
Distribution channels delineate the pathways products take from manufacturers to end-users, highlighting the shift towards more direct and specialized procurement methods.
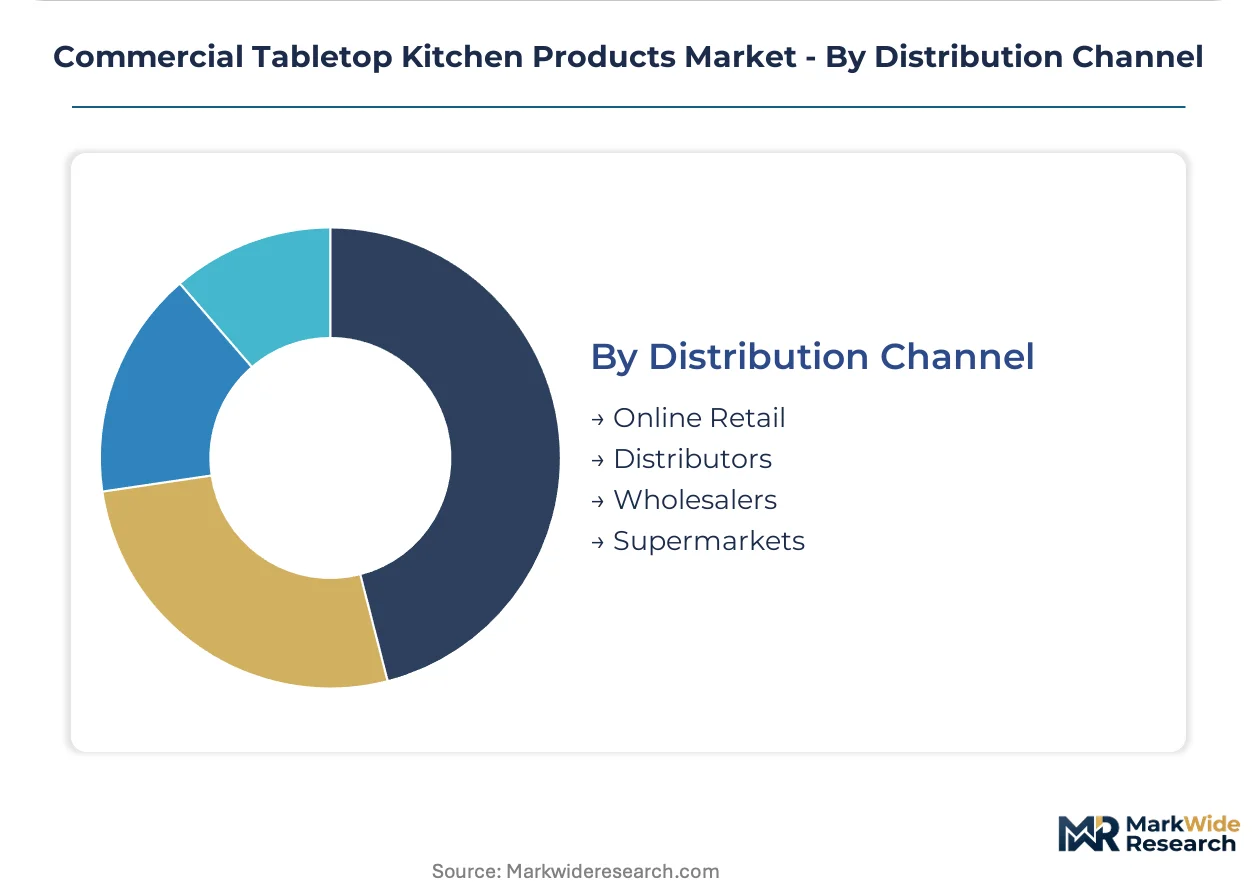
- Distributors:These entities serve as the primary channel, offering extensive product portfolios and comprehensive logistics support to a broad range of hospitality clients. Large national distributors in the United States manage complex supply chains for major hotel chains and multi-unit restaurant groups.
- Online Retail:This expanding channel provides direct access to manufacturers and specialized niche products, particularly beneficial for smaller businesses seeking unique or custom items. Independent cafes in Australia are increasingly sourcing their tabletop supplies through dedicated e-commerce platforms for convenience and variety.
- Wholesalers:Supply bulk orders to larger institutions and catering companies, with their focus primarily on volume and competitive pricing strategies.
- Supermarkets:Offer a limited selection of entry-level commercial tabletop products, mainly targeting small cafes or home-based catering businesses with basic needs.
Distributors remain the dominant channel for large volume orders, while Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Food Safety Authority (EFSA) regulations significantly influence market dynamics, particularly for materials used in food contact applications. Demand for commercial tabletop kitchen products is intensifying across key metropolitan hubs and emerging hospitality sectors globally. These regions exhibit distinct procurement patterns and regulatory landscapes.
Germany
Corporate catering services in Germany drive substantial demand for durable stainless steel cookware and high-performance dinnerware. The German Food and Feed Code (LFGB) sets rigorous standards for food contact materials, ensuring product safety and quality. Major industrial centers like Munich and Frankfurt show concentrated procurement for large-scale event catering operations.
China
Quick-service restaurants and institutional catering facilities in China require high volumes of cost-effective plastic and glass items. China's GB standards, particularly GB 4806, govern the safety of food contact materials, impacting local manufacturing and imports. Cities such as Shanghai and Beijing are centers for high-turnover food service operations, driving utilitarian product adoption.
United Kingdom
New luxury hotel developments in London and other major UK cities create strong demand for premium porcelain and specialized glassware. The UK's Food Safety Act 1990, alongside retained EU regulations, mandates strict compliance for all food-contact items. London's vibrant hospitality scene consistently seeks customized and aesthetically refined tabletop solutions.
Singapore
The expanding luxury hotel sector in Singapore fuels demand for sophisticated and durable tabletop products across various dining venues. The Singapore Food Agency (SFA) enforces stringent food safety regulations for commercial kitchenware and tableware. High-end establishments within the Marina Bay and Orchard Road districts are key consumers of custom-designed items.
France
Independent restaurants in France prioritize unique dinnerware and glassware that align with specific culinary themes and brand identities. French national regulations, complementing EU standards, ensure the safety and quality of materials used in hospitality settings. Parisian fine dining establishments often procure artisan porcelain and specialized glass items to enhance guest experiences.
Commercial Tabletop Kitchen Products Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure within the commercial tabletop kitchen products market. The market exhibits a tiered structure, with established brands focusing on premium segments and a larger group of manufacturers targeting mid-range and utilitarian applications. Strategic archetypes include heritage brands emphasizing craftsmanship, performance-driven innovators, and volume-focused producers. Dominant competitive moves involve portfolio diversification into new material composites and geographic expansion into emerging hospitality markets.
Specialists in durable, chip-resistant tableware engineered for high-turnover environments include Steelite International. On the premium porcelain segment for fine dining establishments, Villeroy & Boch leverages its brand heritage. The Oneida Group occupies a position providing a broad range of dinnerware, flatware, and glassware solutions for various food service settings.
| Leading Market Players |
|---|
| Villeroy & Boch |
| Lenox Corporation |
| The Oneida Group |
| Lifetime Brands |
| BHS Tabletop AG |
| Arc International |
| The Vollrath Company |
| Steelite International |
| Libbey Inc. |
Cost & Logistics Intelligence
Large-scale manufacturing efficiency in commercial tabletop products shapes both supply concentration and market price floors. This efficiency enables producers to meet high-volume demand from global hospitality chains, influencing competitive pricing across material segments.
Pricing Analysis
Geographic price spreads reflect material origin and regulatory compliance costs. Transactional per-unit pricing dominates, with price differentiation stemming from material quality grades and specific food contact certifications like EFSA approval. Pricing softness in utilitarian segments stems from competition from lower-cost plastic alternatives. Quick-service restaurants exhibit the highest price sensitivity, while luxury hotels prioritize brand premium and aesthetic design.
Supply Chain Analysis
China anchors high-volume plastic and glass production, while Germany leads in stainless steel manufacturing for industrial applications. Raw material dependencies include high-purity clays for porcelain and specialized alloys for stainless steel. Regulatory fragmentation across jurisdictions presents a structural risk, creating compliance hurdles for manufacturers. Distribution runs through established national distributors who manage complex logistics for major hospitality groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial tabletop kitchen products market is an early-cycle expansion story, with growth spurred by the global hospitality sector's increasing demand for both premium and durable items.
For Market Incumbents:
Secure existing market share through continuous investment in material science R&D, particularly for advanced polymers and lead-free ceramics. Diversify product portfolios to address the bifurcated demand for specialized fine dining items and highly durable, easy-to-use products. Regulatory shifts, such as stricter EFSA mandates, present a threat that can be leveraged through proactive certification investment.
For New Entrants and Emerging Players:
Certification fast-tracks for innovative, compliant materials offer a direct entry point into regulated markets like Europe. Target underpenetrated segments, such as sustainable tabletop solutions for corporate hotel chains, or smart tableware integration for inventory management. A digital-first, direct-to-business e-commerce strategy provides a cost-effective go-to-market angle for independent cafes and restaurants.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialists in advanced material composites or smart tableware integration. Long-term viability rests with companies demonstrating robust supply chain resilience and a strong track record of navigating complex food contact material regulations. A signal to watch is the successful commercialization of highly durable, sustainable products in high-volume catering environments.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Lead-Free Porcelain R&D | Ensures compliance with strict European food contact regulations and maintains access to premium markets. |
| Expand Direct-to-Business E-commerce | Reaches small-to-medium-sized hospitality businesses, bypassing traditional distributor networks for niche products. |
| Integrate RFID for Inventory Management | Offers a new value proposition for large hotel chains by automating stock tracking and reducing operational costs. |
| Develop Advanced Polymer Composites | Addresses demand for chip-resistant, lightweight, and durable items in high-turnover food service settings. |
| Target Emerging Tourism Markets | Captures significant growth opportunities from new luxury hotel developments in regions like Southeast Asia. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EFSA reports, FDA guidelines, GB standards, and industry association publications. The research involved interviews with hospitality procurement managers, hotel F&B directors, catering service operators, and material scientists. This approach allowed for bottom-up data collection and top-down market validation.
Segmentation dimensions modeled include product type, material, end-user, distribution channel, and regional regulatory frameworks. The analytical framework projects market growth across the analysis window by correlating historical data with forecast inputs like hospitality sector new construction rates and catering service expansion. Compound annual growth rates were derived from a multi-variant regression analysis considering economic indicators.
Decision-makers should treat outputs as directional under current geopolitical and regulatory assumptions; material deviation would warrant model refresh. Forecasts reflect a baseline scenario, acknowledging that shifts in raw material prices or new food safety mandates represent specific risk factors. Recalibration cycles align with material shifts in regulatory compliance and hospitality investment trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
Electric Countertop Griddles Market
Kitchen Appliances
US Household Coffee Machine Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Popcorn Makers Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Russia Kitchen Appliances Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
France Cookware Market
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
South Korea Kitchen Appliances Market