
 Global Hi-Tech Medical Devices Market | 2026-2036
Global Hi-Tech Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hi-Tech Medical Devices Market Analysis
ISO 13485 certification is rotating as the decisive gatekeeper for supplier qualification in connected surgical systems. Medtronic plc leverages in-house manufacturing scale across neurostimulation and diabetes care platforms. Siemens Healthineers anchors its position through R&D intensity in molecular imaging and AI-integrated diagnostics. Johnson & Johnson MedTech differentiates via specialization in robotic-assisted orthopedic surgery and advanced wound closure.
Hi-tech medical devices encompass electronically integrated instruments, sensors, and platforms engineered to sub-millimeter precision, often incorporating semiconductor-based signal processing, biocompatible alloys, and real-time data transmission protocols for diagnostic or therapeutic intervention. Imaging Devices command the largest installed base revenue pool across radiology departments worldwide, while AI-Powered Solutions within the Technology dimension capture the fastest expansion trajectory as hospitals deploy algorithmic triage and predictive analytics. Robotics applications in the Application layer concentrate margin pools in academic medical centers performing high-complexity procedures.
FDA premarket notification requirements and EU MDR technical documentation standards tighten compliance burdens for cross-border market entry, directly elevating barriers for smaller component suppliers. Japan's PMDA and China's NMPA operate parallel approval tracks that force dual-track regulatory investment from multinational manufacturers. Stakeholders must monitor convergence between software-as-medical-device frameworks and traditional hardware certification timelines to anticipate which product architectures will retain market access flexibility.
Market Dynamics
AI-powered diagnostic platforms are compressing traditional hardware procurement cycles as hospital systems demand algorithmic triage capabilities bundled with imaging infrastructure, forcing vendors to restructure R&D allocation toward software-medical-device convergence.
Growth Catalysts
- EU MDR recertification timelines:Compressed vendor eligibility windows accelerate consolidation among pre-qualified suppliers, concentrating procurement decisions around ISO 13485-certified manufacturers with established technical documentation.
- Robotic surgery reimbursement codes:National coverage achievements in Germany, Japan, and the United States expand addressable procedure volumes in academic medical centers performing high-complexity interventions.
- Remote patient monitoring infrastructure:Semiconductor-based signal processing advances enable real-time biocompatible sensor networks for chronic disease management, pulling demand from aging demographics in developed health systems.
Market Restraints
- Dual-track regulatory investment:Japan's PMDA and China's NMPA operate parallel approval tracks that force redundant clinical trial expenditure from multinational manufacturers seeking cross-border market access.
- Specialized alloy supply concentration:Biocompatible titanium and nitinol sourcing clusters in limited geographies expose device makers to input cost volatility and geopolitical disruption risk.
- Software-as-medical-device framework uncertainty:Convergence timelines between traditional hardware certification and algorithmic approval pathways create product architecture lock-in risks for platform developers.
Strategic Opportunities
- India's CDSCO fast-track pathways:Underpenetrated surgical robotics and molecular imaging markets offer first-mover positioning as domestic production incentives align with import substitution policies.
- AI-integrated diagnostics convergence:Machine learning triage algorithms merging with portable ultrasound and point-of-care testing platforms create new ambulatory care revenue pools outside hospital radiology departments.
- Brazil's ANVISA harmonization:Emerging regulatory alignment with FDA predicate device frameworks reduces duplicate submission burdens for cardiovascular and orthopedic implant manufacturers.
Industry Challenges
- ISO 13485 auditor scarcity:Certification body capacity constraints extend supplier qualification timelines for connected surgical systems, delaying contract awards.
- Legacy PACS integration complexity:Algorithmic diagnostic platforms face interoperability friction with hospital information systems built on decade-old imaging archive architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hi-Tech Medical Devices Market |
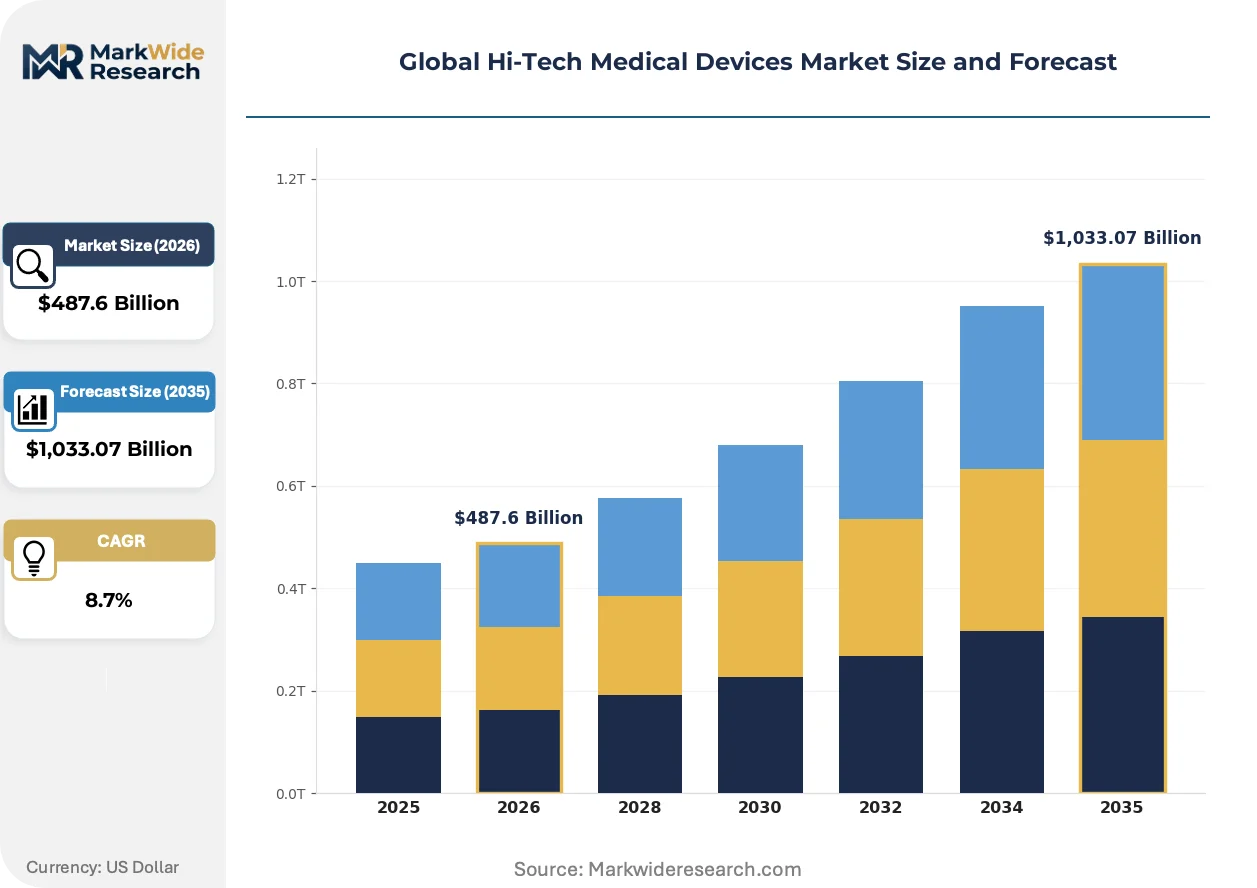
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,033.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Devices, Surgical Instruments, Monitoring Systems, Diagnostic Equipment Technology: AI-Powered Solutions, Robotics, Telemedicine, Wearable Technology End User: Hospitals, Clinical Labs, Rehabilitation Centers, Outpatient Facilities Application: Cardiology, Neurology, Orthopedics, Emergency Care |
| Companies Covered | Medtronic plc, Johnson & Johnson MedTech, Siemens Healthineers, Stryker Corporation, GE HealthCare, Royal Philips, Abbott Laboratories, Boston Scientific Corporation, Intuitive Surgical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hi-Tech Medical Devices Market Emerging Trajectories
Real-time data transmission protocols and edge computing architectures are restructuring how diagnostic information flows from point-of-care sensors to clinical decision support systems, compressing latency windows for therapeutic intervention.
Semiconductor-based biosensors with sub-millimeter precision are bifurcating the patient monitoring landscape. Wearable continuous glucose monitors and implantable cardiac sensors are penetrating home-based care settings faster than hospital procurement cycles. This technology is bifurcating established revenue streams between acute-care device vendors and consumer health platform operators.
EU MDR technical documentation standards are elevating post-market surveillance obligations for legacy device portfolios. Manufacturers must maintain clinical evidence registries spanning entire product lifecycles rather than premarket submission packages alone. Class III implantable devices face the steepest compliance cost escalation, driving portfolio rationalization among mid-scale European orthopedic suppliers.
Academic medical centers are unbundling after-sales service contracts from capital equipment purchases. Procurement committees now negotiate algorithm update subscriptions and predictive maintenance separately from hardware acquisition, compressing vendor pricing power. This pattern is most pronounced in the United States where health system consolidation has concentrated buying authority within centralized value analysis committees.
Global Hi-Tech Medical Devices Market Segmentation
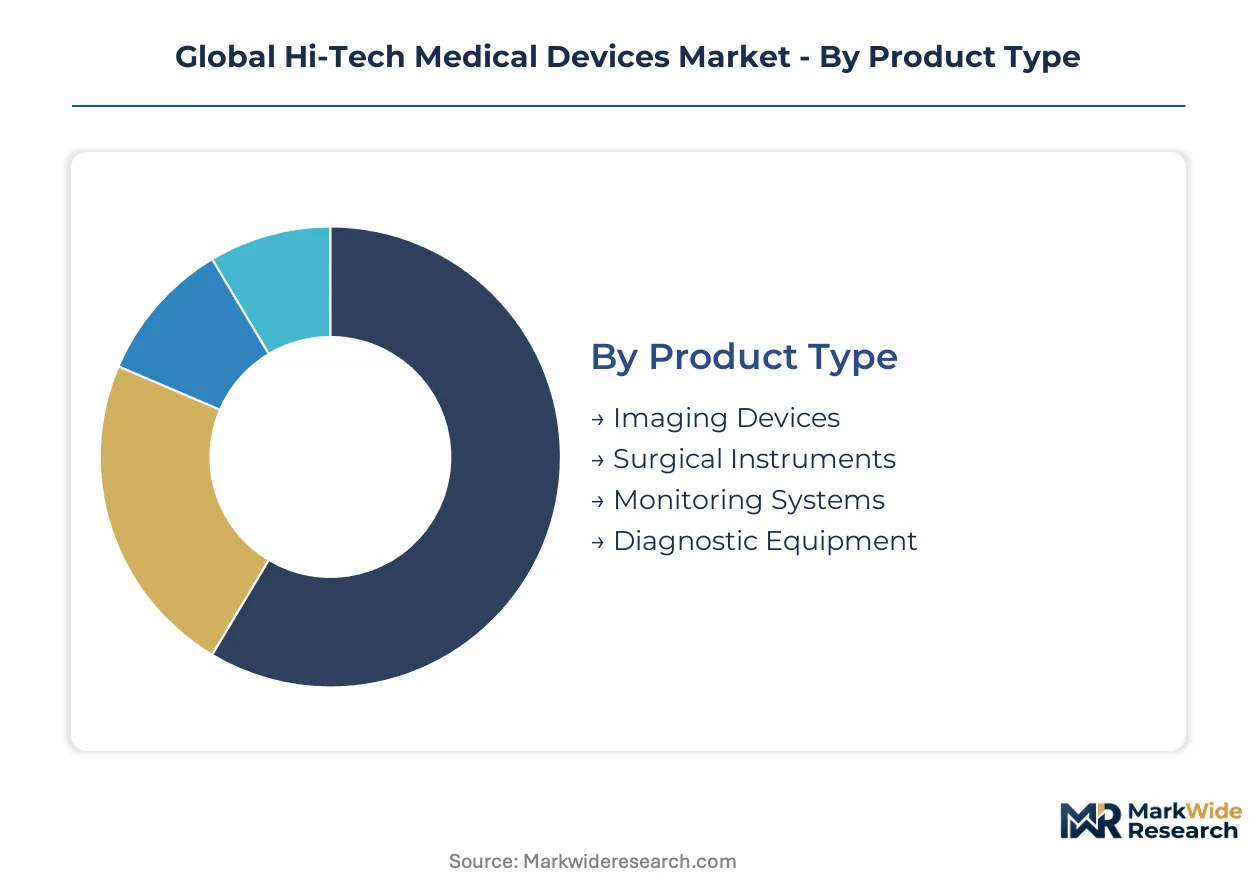
Segmentation in hi-tech medical devices reveals how technology convergence is eroding traditional hardware boundaries. Hospital procurement committees now evaluate bundled platforms rather than discrete equipment categories, forcing vendors to reposition across multiple segment definitions simultaneously.
Product Type:
Imaging Devices face the most acute substitution pressure as AI-enhanced software platforms reduce reliance on dedicated radiology hardware for routine diagnostics.
- Imaging Devices:MRI, CT, and ultrasound systems with semiconductor-based signal processing subsystems. Demand concentrates in Germany and the United States where academic medical centers perform high-complexity interventional procedures. Reimbursement compression for routine scans is accelerating platform consolidation.
- Surgical Instruments:Electronically integrated cutting, cauterizing, and stapling platforms engineered to sub-millimeter precision. Japan's hospital systems anchor procurement volume as PMDA approval pathways favor incremental innovation over radical platform shifts.
- Monitoring Systems:Real-time biocompatible sensor networks for intensive care and perioperative settings.
- Diagnostic Equipment:Point-of-care testing platforms with embedded algorithmic interpretation.
Imaging Devices anchors the volume base while AI-Powered Solutions within Diagnostic Equipment gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive robotics deployments from software-only algorithmic platforms that scale with minimal marginal hardware investment.
- AI-Powered Solutions:Machine learning triage algorithms and predictive analytics modules. United States health systems concentrate demand as FDA software-as-medical-device frameworks mature faster than EU MDR equivalents. Algorithm update subscriptions are unbundling from hardware purchases.
- Robotics:Motorized surgical platforms with haptic feedback and sub-millimeter positioning accuracy. Germany's statutory health insurance funds anchor volume through national reimbursement codes for orthopedic and urologic procedures.
- Telemedicine:Real-time data transmission protocols connecting remote clinicians to point-of-care diagnostics.
- Wearable Technology:Semiconductor-based biosensors for continuous physiological monitoring outside clinical settings.
Robotics captures the highest absolute revenue per installation while Wearable Technology expands most quickly into home-based chronic disease management.
End User:
Customer type determines procurement cycle length, with centralized hospital value analysis committees extending decision timelines compared to fragmented outpatient facility purchasing.
- Hospitals:Integrated delivery networks with centralized capital equipment committees. United States health system consolidation has concentrated buying authority within value analysis committees that negotiate algorithm subscriptions separately from hardware.
- Clinical Labs:High-throughput molecular diagnostics and automated pathology platforms. Germany's laboratory sector anchors European demand as EU MDR recertification compresses vendor eligibility windows.
- Rehabilitation Centers:Robotic-assisted mobility and neurostimulation systems for post-acute recovery.
- Outpatient Facilities:Portable imaging and point-of-care testing for ambulatory surgical procedures.
Hospitals dominate absolute procurement value while Outpatient Facilities are climbing the fastest as procedure volume shifts away from inpatient settings.
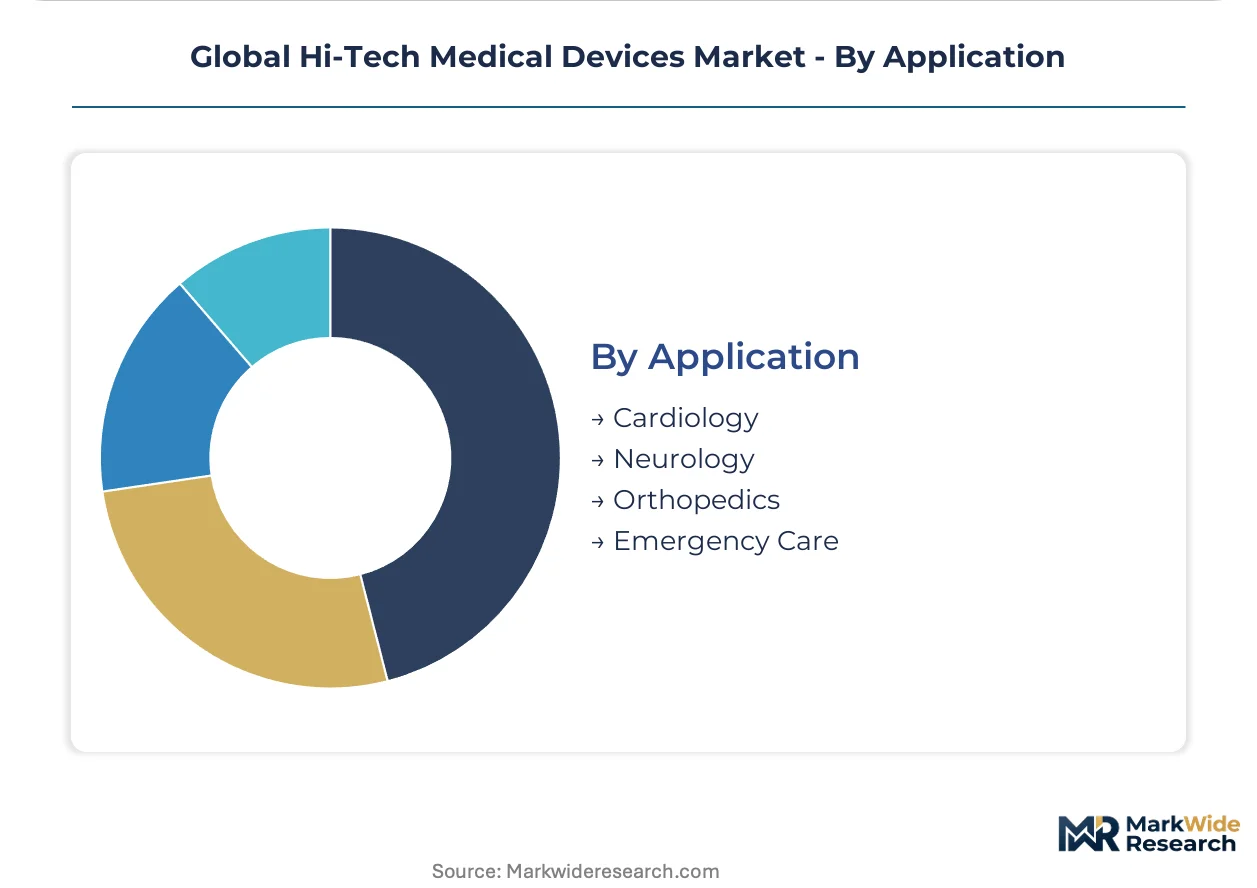
Application:
Application-layer margins concentrate where procedure complexity demands integrated hardware-software platforms that resist commoditization.
- Cardiology:Implantable cardiac sensors and robotic-assisted structural heart interventions. Japan's aging demographics pull demand for remote monitoring infrastructure as PMDA fast-tracks digital health submissions.
- Neurology:Neurostimulation platforms and AI-integrated intraoperative mapping systems. United States academic medical centers anchor volume for deep brain stimulation and responsive neurostimulation.
- Orthopedics:Robotic-assisted joint replacement and advanced wound closure systems.
- Emergency Care:Portable ultrasound and algorithmic triage for time-critical intervention.
Cardiology anchors the volume base through implantable device replacement cycles while Emergency Care gains share at the steepest rate as point-of-care AI reduces reliance on centralized radiology departments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement harmonization and domestic production incentives are redistributing procurement authority across health systems. Germany's statutory insurance funds, Japan's PMDA fast-track pathways, and India's PLI scheme for medical electronics are compressing vendor eligibility windows while opening new manufacturing clusters.
United States
Academic medical centers in Boston and Houston anchor demand for robotic-assisted orthopedic platforms. FDA software-as-medical-device frameworks mature faster than EU equivalents, pulling algorithmic triage development toward US health systems. Health system consolidation concentrates buying authority within value analysis committees that negotiate algorithm subscriptions separately from hardware.
Germany
Statutory health insurance funds anchor volume for robotic surgery through national reimbursement codes for orthopedic and urologic procedures. EU MDR recertification timelines compress vendor eligibility windows around ISO 13485-certified manufacturers. The Baden-Württemberg cluster concentrates precision engineering suppliers for surgical instrument subsystems.
Japan
Aging demographics pull demand for implantable cardiac sensors and remote monitoring infrastructure. PMDA operates parallel approval tracks that force dual-track regulatory investment from multinational manufacturers. The Kanto region around Tokyo anchors procurement volume as hospital systems favor incremental innovation over radical platform shifts.
China
NMPA approval pathways and domestic production incentives align with import substitution policies for surgical robotics. Semiconductor-based biosensor networks penetrate home-based care settings faster than hospital procurement cycles. The Yangtze River Delta cluster concentrates contract manufacturers for biocompatible alloy components.
India
CDSCO fast-track pathways for underpenetrated surgical robotics markets offer first-mover positioning. PLI scheme incentives for medical electronics manufacturing align with domestic production goals. The Maharashtra-Gujarat corridor attracts component suppliers seeking tariff advantages on imported precision alloys.
Global Hi-Tech Medical Devices Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity tiers, creating a bifurcated structure where scale-driven conglomerates face focused technology developers. The vendor base concentrates around three archetypes: diversified health conglomerates with in-house manufacturing scale, pure-play robotics specialists with haptic feedback IP, and algorithmic platform developers with software-as-medical-device clearance. M&A activity targets ISO 13485-certified component suppliers, while strategic partnerships between imaging hardware vendors and AI triage developers restructure R&D allocation.
Within the diversified conglomerate tier, Medtronic plc and Johnson & Johnson MedTech exemplify scale-driven positioning across neurostimulation and robotic-assisted surgery platforms. Siemens Healthineers occupies a position representing R&D intensity in molecular imaging and AI-integrated diagnostics. These three entities anchor the premium-tier competitive vector where technical documentation depth and established regulatory clearance histories determine contract eligibility.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson MedTech |
| Siemens Healthineers |
| Stryker Corporation |
| GE HealthCare |
| Royal Philips |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Intuitive Surgical, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with biocompatible alloy foundries lock in titanium and nitinol supply access while freezing price visibility across multi-year procurement cycles for Class III implantable device manufacturers. These arrangements concentrate pricing power with ISO 13485-certified suppliers in Germany and Japan who dominate precision machining for surgical instrument subsystems.
Pricing Analysis
Certification level (ISO 13485/FDA-grade versus non-certified) creates the primary spread between premium and standard tiers in surgical robotics and implantable devices. Three-tier pricing structure across premium, standard, and economy levels dominates capital equipment, while algorithm update subscriptions unbundle from hardware in AI-integrated diagnostics. Cost compression in the standard tier is intensifying because hospital value analysis committees negotiate service contracts separately from equipment purchases. Outpatient facilities demonstrate highest price sensitivity due to fragmented purchasing authority, whereas academic medical centers in the United States show lowest sensitivity given bundled procurement of high-complexity platforms.
Supply Chain Analysis
Container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for semiconductor-based sensor components sourced from Taiwan and South Korea. Biocompatible titanium feedstock concentrates in Chinese and Russian smelting operations, while nitinol shape-memory alloys hinge on limited US and European foundry capacity. Single-source vulnerability in precision machining for orthopedic implants exposes device makers to geopolitical disruption risk. Distribution runs through hospital GPO contracts and direct OEM relationships with academic medical centers, bypassing traditional medical device distributors for high-value robotics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 auditor scarcity and EU MDR technical documentation requirements have created a bottleneck where qualified suppliers command disproportionate contract eligibility, compressing margins for manufacturers without established certification depth.
For Market Incumbents: Fortify regulatory documentation depth through backward integration into precision alloy component manufacturing, securing captive supply of biocompatible titanium from the Yangtze River Delta cluster. Acquire ISO 13485-certified surgical instrument suppliers in Baden-Württemberg to compress vendor eligibility windows for EU MDR recertification. Channel control through direct hospital system partnerships in Germany and the United States anchors pricing power against algorithmic platform entrants. For New Entrants and Emerging Players: Lead with software-as-medical-device clearance pathways in the United States where FDA frameworks mature faster than EU equivalents, targeting algorithmic triage for emergency care applications in underpenetrated outpatient facilities. India's CDSCO fast-track pathways for surgical robotics offer first-mover positioning as PLI scheme incentives align with domestic production goals. A hospital system partnership model bypassing traditional GPO contracts accelerates procurement committee access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified conglomerates with established regulatory clearance histories over pure-play specialists. Long-term viability across the projection horizon rests on technical documentation depth and multi-regional approval portfolios rather than single-market dominance. Acquisition targets should demonstrate ISO 13485 certification with active EU MDR technical files and established relationships with hospital value analysis committees. The signal to monitor is convergence timelines between software-as-medical-device frameworks and traditional hardware certification pathways, which will determine which product architectures retain market access flexibility.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Software-as-medical-device clearance accelerates algorithmic triage deployment in US academic medical centers. |
| CE Marking Pathway | EU MDR technical documentation anchors vendor eligibility for German statutory insurance reimbursement codes. |
| Hospital System Partnership | Direct relationships with value analysis committees unbundle algorithm subscriptions from hardware procurement. |
| Software Companion Development | AI-integrated diagnostics convergence creates ambulatory care revenue pools outside radiology departments. |
| Reimbursement Strategy | National coverage achievements in Japan's PMDA fast-track pathways expand addressable procedure volumes. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, and CMS Medicare reimbursement code records. Primary fieldwork captured procurement cycle dynamics and algorithm subscription unbundling patterns across US health systems. Bottom-up and top-down triangulation reconciled installed base estimates with capital expenditure disclosures from academic medical centers.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type (imaging devices, surgical instruments, monitoring systems, diagnostic equipment), technology tier (AI-powered solutions, robotics, telemedicine, wearable technology), end user (hospitals, clinical labs, rehabilitation centers, outpatient facilities), and application (cardiology, neurology, orthopedics, emergency care). CAGRs derived from regression analysis of historical procurement cycles and reimbursement code expansion trajectories. Semiconductor-based sensor penetration curves and robotic surgery procedure volume assumptions anchored the projection horizon.
Forecasts assume regulatory continuity in FDA software-as-medical-device frameworks and EU MDR recertification timelines; material policy shifts in Japan's PMDA or China's NMPA would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Nasal Implant Market
Medical Devices
Global Gynecological Devices Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Global Heart Valve Devices Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Electrophysiology Market
Medical Devices
Global Self Care Medical Devices Market