
 Additional Defibrillator Accessories (AED) Market | 2026-2036
Additional Defibrillator Accessories (AED) Market Size, Share, and Industry Trends Forecast 2026-2036
Additional Defibrillator Accessories (AED) Market Outlook
A shortage of certified biomedical equipment technicians is unwinding service capacity across the installed base of automated external defibrillators. ZOLL Medical Corporation leverages its direct field-service network to sustain replacement electrode and battery attach rates in hospital accounts. Koninklijke Philips N.V. anchors its accessories revenue through long-term service contracts tied to its HeartStart device fleet. Stryker competes by extending its Physio-Control aftermarket platform into third-party compatible consumables.
Additional defibrillator accessories encompass electrodes, batteries, carry cases, and training peripherals engineered to specific impedance, voltage, and shelf-life parameters for cardiac resuscitation devices. Electrode pads incorporate conductive hydrogel layers with defined adhesion cycles and must maintain electrical conductivity across temperature ranges specified for emergency deployment. Batteries dominate replacement value pools given their finite calendar-life limitations and manufacturer-specific form factors. Training devices represent the fastest-growing product type as workplaces and schools expand mandated CPR-AED certification programs.
FDA 510(k) clearance pathways and the EU Medical Device Regulation govern accessory compatibility claims and biocompatibility testing for patient-contact components. The FDA requires predicate-device demonstrations for electrode substitutions, while MDR technical documentation demands clinical evidence for accessories classified as Class IIa or higher. Stakeholders must monitor evolving notified-body capacity constraints in Europe and FDA inspection backlogs that delay new supplier market entry timelines.
Market Dynamics
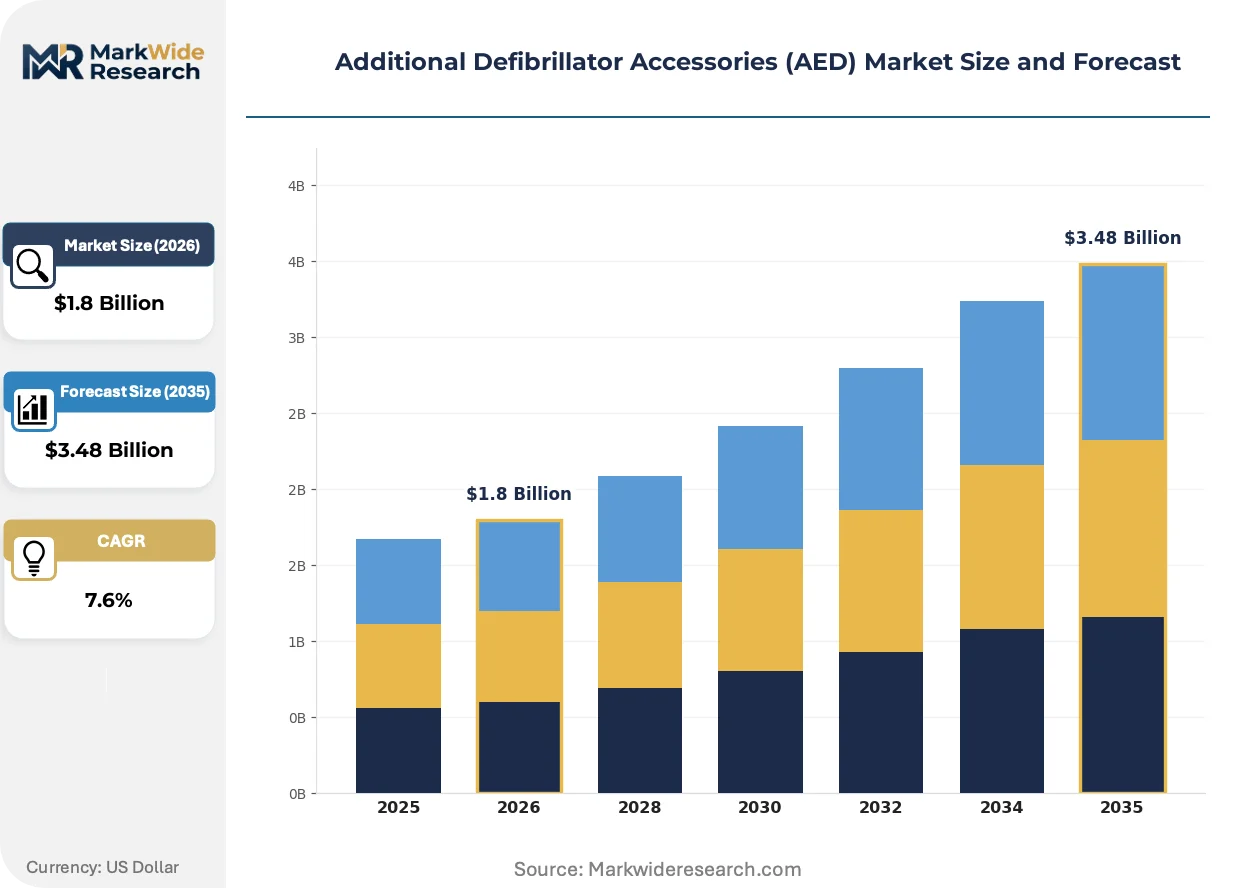
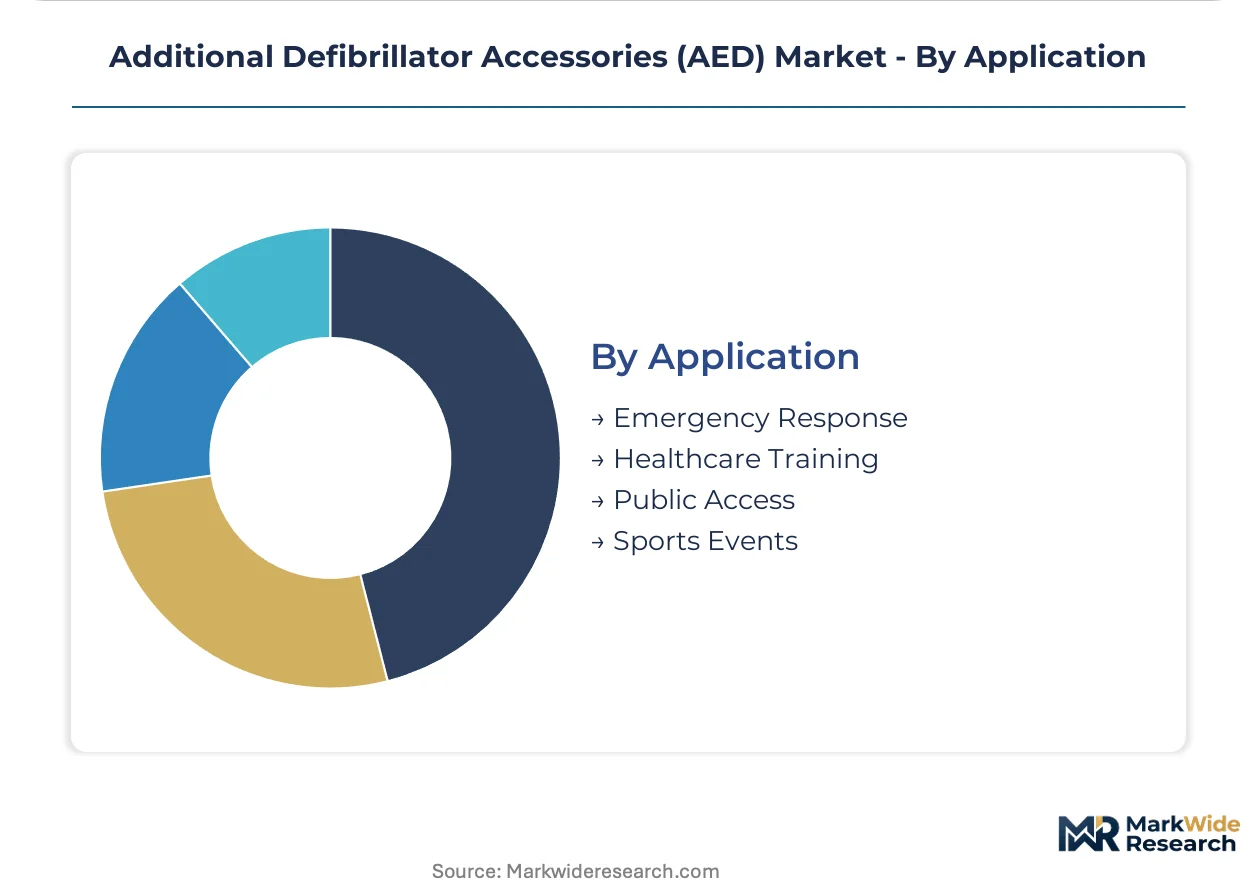
The Additional Defibrillator Accessories (AED) market is tightening around regulatory compliance velocity as FDA 510(k) clearance timelines and EU MDR technical documentation demands compress supplier qualification windows. Biomedical equipment technician shortages are simultaneously constraining service attach rates across the installed base.
Growth Catalysts
- Public Access Defibrillation Mandates:School and fitness center deployment requirements in the United States are accelerating replacement electrode and battery volumes through mandatory device presence laws.
- EU Medical Device Regulation:MDR classification of electrode pads as Class IIa devices is forcing clinical evidence upgrades that favor established suppliers with notified-body relationships.
- Conductive Hydrogel Advances:Polymer chemistry improvements extending adhesion cycles and temperature stability are expanding electrode deployment environments beyond traditional clinical settings.
Market Restraints
- Manufacturer-Specific Battery Form Factors:Proprietary lithium-manganese dioxide pack designs lock replacement demand to original equipment channels, limiting third-party penetration.
- Notified-Body Capacity Constraints:European Union technical documentation review backlogs are extending accessory market entry timelines by twelve to eighteen months for new suppliers.
- Calendar-Life Limitations:Defibrillator batteries degrade on shelf regardless of use cycles, creating forced replacement economics that strain rural and underfunded emergency service budgets.
Strategic Opportunities
- Workplace CPR-AED Certification Expansion:Corporate training mandates are driving demand for simulation electrodes and training peripherals as distinct product categories with separate procurement channels.
- FDA Pre-Submission Pathways:Early engagement with FDA Q-Sub programs offers predicate-device alignment strategies that compress 510(k) review timelines for electrode substitutions.
- Smart Battery Telemetry Integration:Bluetooth-enabled capacity monitoring is converging with fleet management software to enable condition-based replacement scheduling.
Industry Challenges
- Biomedical Equipment Technician Shortage:Certified BMET workforce gaps are delaying preventive maintenance compliance and compressing service revenue realization across hospital accounts.
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies for patient-contact hydrogel layers are extending product development timelines beyond commercial planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Additional Defibrillator Accessories (AED) Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrodes, Batteries, Carry Cases, Training Devices End User: Hospitals, Clinics, Schools, Fitness Centers Technology: Automatic, Semi-Automatic, Manual, Hybrid Application: Emergency Response, Healthcare Training, Public Access, Sports Events |
| Companies Covered | ZOLL Medical Corporation, Koninklijke Philips N.V., Stryker, Medtronic, Nihon Kohden Corporation, Shenzhen Mindray Bio-Medical Electronics, Schiller Americas, Cardiac Science Corporation, Defibtech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Additional Defibrillator Accessories (AED) Market Strategic Shifts
Technology convergence and regulatory recalibration are fragmenting traditional accessory procurement patterns. Suppliers are repositioning around digital connectivity and training ecosystem integration.
Smart electrode technology incorporating impedance sensing and real-time CPR feedback is decomposing the standalone pad replacement model. Hospital emergency departments and emergency medical services fleets are adopting these integrated systems fastest. The shift is compressing margins on commodity electrode sales while expanding software-enabled service contract value pools.
EU MDR Article 10 technical documentation requirements are mandating clinical performance data for electrode biocompatibility claims. Manufacturers must now submit post-market surveillance plans and periodic safety update reports previously exempt under the Medical Devices Directive. High-risk patient-contact accessories face the steepest compliance cost escalation.
After-sales service unbundling is fragmenting long-term contracting structures. Hospital procurement teams are separating device warranty, electrode supply, and battery replacement into distinct purchasing decisions. United States health system consolidation is accelerating this disaggregation as centralized supply chains negotiate category-specific terms.
Additional Defibrillator Accessories (AED) Market Segmentation
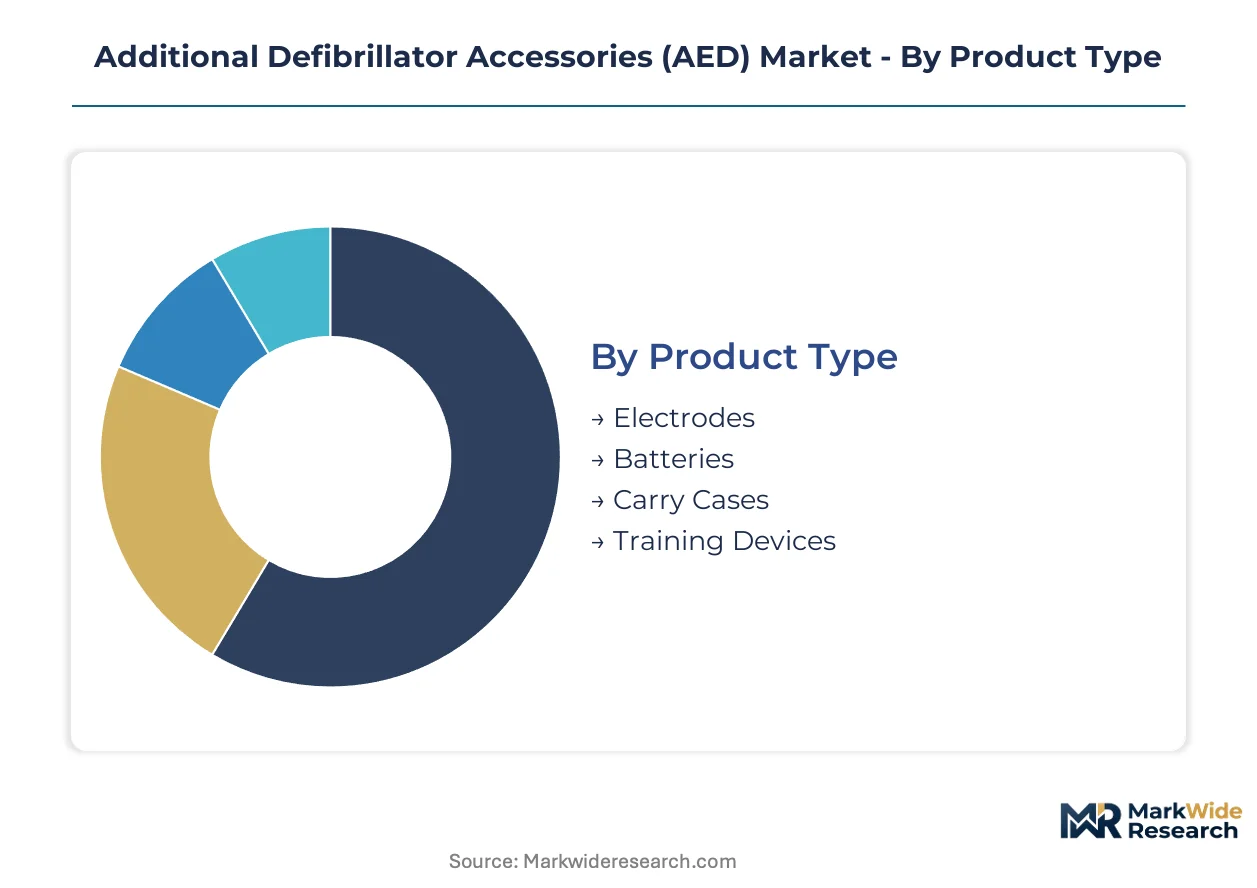
Accessory procurement patterns fragment sharply across use environments, with hospital buyers prioritizing regulatory compliance while public access deployments emphasize cost predictability. Margin concentration varies by segment maturity, with consumables commanding recurring revenue streams and training peripherals capturing expansion premiums.
Product Type:
Electrode pads and batteries concentrate replacement value pools through finite shelf-life economics, while carry cases and training peripherals operate on divergent margin structures tied to durability versus volume scaling.
- Electrodes:Multi-layer conductive hydrogel assemblies with defined impedance tolerances and adhesion cycle limits. Hospital emergency departments in the United States drive procurement volume through tightened cardiac arrest response protocols, with FDA 510(k) predicate requirements locking specifications to device-specific approvals.
- Batteries:Lithium-manganese dioxide packs with manufacturer-unique form factors and calendar-life degradation curves. Replacement demand concentrates in North American public access installations where state-level school and fitness center mandates enforce presence requirements with strict maintenance schedules.
- Carry Cases:Impact-resistant polymer housings with environmental sealing rated for temperature and moisture exposure during emergency transport.
- Training Devices:Simulation peripherals with reusable electrode interfaces and software-enabled CPR feedback modules for certification programs.
The dominant share belongs to Electrodes, while Training Devices are closing the gap fastest.
End User:
Procurement authority concentrates differently across settings, with hospitals integrating accessories into capital equipment contracts while schools and fitness centers purchase through decentralized supply channels.
- Hospitals:Integrated delivery networks negotiate multi-year electrode and battery supply agreements tied to device fleet management. United States health system consolidation is compressing vendor counts and standardizing around FDA-cleared predicate devices with established biocompatibility documentation.
- Clinics:Outpatient cardiac and urgent care facilities with lower device density but equivalent regulatory compliance burdens.
- Schools:Public and private educational institutions subject to state-level public access defibrillation mandates with defined maintenance inspection intervals.
- Fitness Centers:Commercial gym operators and recreational facilities facing liability-driven device presence requirements with high-visibility placement standards.
Hospitals retain the largest installed base, though Fitness Centers are expanding device counts most aggressively.
Technology:
Device intelligence levels determine accessory compatibility complexity, with automatic systems requiring minimal user intervention and manual configurations demanding specialized training peripherals.
- Automatic:Shock delivery without user initiation, demanding electrodes with integrated impedance sensing and real-time CPR coaching feedback. EMS fleets in the United States are adopting these systems fastest, compressing replacement cycles as software-enabled pads obsolete simpler designs.
- Semi-Automatic:User-activated shock delivery with rhythm analysis prompting, balancing automation with human oversight.
- Manual:Clinician-controlled energy selection and timing, restricted to hospital and advanced EMS settings with trained operator requirements.
- Hybrid:Configurable operation modes switching between automatic and manual functionality based on user credential detection.
Automatic systems hold the technology lead, while Hybrid configurations are gaining traction in mixed-use environments.
Application:
Use case intensity shapes replacement frequency, with emergency response demanding rapid-turn consumables and training applications prioritizing durability over clinical-grade specifications.
- Emergency Response:High-stakes deployment scenarios with temperature-stressed electrodes and capacity-verified batteries subject to regulatory inspection. Fire departments and ambulance services in the United States face the strictest replacement schedules, with state EMS offices enforcing documentation of pad and battery expiration compliance.
- Healthcare Training:Simulation-based certification programs with reusable training electrodes and software-integrated manikin peripherals. Corporate workplace mandates are expanding procurement volumes as employers across the United States implement CPR-AED certification requirements for designated response teams.
- Public Access:Airport, casino, and municipal building installations with environmental exposure and vandalism risks.
- Sports Events:Temporary venue deployments with rapid-setup requirements and mobile equipment protection needs.
Emergency Response commands the value pool, though Healthcare Training is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States prioritizing regulatory compliance and replacement volume while European markets emphasize clinical evidence standards and Asian markets concentrate on manufacturing scale and cost efficiency.
United States
School and fitness center mandates drive electrode pad replacement cycles through strict maintenance inspection laws. FDA 510(k) predicate requirements lock accessory specifications to device-specific approvals, favoring established suppliers with cleared portfolios. Texas and Florida lead public access deployment through state-level cardiac emergency response legislation.
Germany
Hospital procurement teams integrate accessories into multi-year device fleet management contracts with standardized biocompatibility documentation. EU MDR notified-body relationships determine supplier qualification velocity, compressing market entry for new entrants. Bavaria and North Rhine-Westphalia concentrate emergency medical service fleet upgrades.
Japan
Aging demographics accelerate automated external defibrillator presence in municipal buildings and transportation hubs. PMDA regulatory alignment with international standards streamlines accessory approval pathways for predicate-device substitutions. Tokyo and Osaka metropolitan regions drive training peripheral demand through workplace certification mandates.
China
Domestic manufacturing scale supports cost-competitive electrode and battery production for export markets. NMPA medical device registration requirements are tightening clinical evidence standards for patient-contact accessories. Yangtze River Delta industrial clusters concentrate conductive hydrogel material suppliers.
United Kingdom
NHS procurement frameworks standardize accessory specifications across integrated care systems, compressing vendor diversity. MHRA post-Brexit regulatory autonomy is diverging from EU MDR timelines, creating dual compliance burdens for suppliers. London and Southeast England concentrate hospital network consolidation and fleet standardization programs.
Additional Defibrillator Accessories (AED) Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding service contract value pools and the lower tier competing on replacement part compatibility. Hospital procurement consolidation favors suppliers with direct field-service networks and long-term fleet management relationships. Three archetypes dominate: integrated device-accessory-service providers, third-party compatible consumable specialists, and training ecosystem platform operators. Competitive moves center on backward integration into conductive hydrogel materials and geographic expansion of notified-body relationships for EU MDR compliance.
Within the integrated tier, ZOLL Medical Corporation and Koninklijke Philips N.V. exemplify service-anchored positioning through direct field networks and long-term contracting structures. Stryker occupies a position bridging original equipment and third-party compatible strategies. These three entities represent distinct approaches to capturing replacement value pools: field-service attach rates, device-fleet service contracts, and aftermarket platform extension respectively.
| Leading Market Players |
|---|
| ZOLL Medical Corporation |
| Koninklijke Philips N.V. |
| Stryker |
| Medtronic |
| Nihon Kohden Corporation |
| Shenzhen Mindray Bio-Medical Electronics |
| Schiller Americas |
| Cardiac Science Corporation |
| Defibtech |
| Others |
Value Chain & Pricing Dynamics
Conductive hydrogel manufacturing scale in the Yangtze River Delta anchors electrode production economics, compressing unit costs for high-volume hospital contracts while proprietary lithium-manganese dioxide cell formats in Japan and South Korea sustain premium pricing tiers for OEM-locked battery replacements.
Pricing Analysis
Long-term service contracts dominate hospital procurement, with integrated delivery networks negotiating multi-year electrode and battery supply agreements tied to device fleet management. Price differentiation rests on FDA 510(k) predicate clearance status and biocompatibility certification tier, with OEM-branded consumables commanding premiums over third-party compatible alternatives. Cost compression in the training peripheral segment is intensifying as workplace certification mandates expand procurement volumes. Public access deployments in schools and fitness centers exhibit the highest price sensitivity, while emergency medical services fleets prioritize reliability over unit cost.
Supply Chain Analysis
Container availability fluctuations on Asia-North America trade lanes are extending inbound lead times for conductive hydrogel raw materials sourced from Chinese chemical processors. Manufacturing concentrates in China, Japan, and Germany, with the Yangtze River Delta feeding electrode component supply and Bavarian industrial clusters producing precision battery management systems. The supply chain rests on lithium carbonate feedstock from South American salares and specialized polymer substrates from Japanese petrochemical producers. Single-source vulnerability in FDA-cleared predicate device approvals creates qualification bottlenecks for new electrode suppliers. Distribution runs through group purchasing organizations for hospital accounts and direct e-commerce channels for public access replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR classification upgrades for patient-contact accessories are accelerating competitive disruption, favoring suppliers with established notified-body relationships and clinical evidence portfolios over commodity-compatible entrants.
For Market Incumbents: Consolidate service contract attach rates by extending direct field-service networks into underserved rural emergency medical services fleets. Deepen backward integration into conductive hydrogel polymer production to secure supply continuity against raw material volatility. Lock hospital procurement through multi-year fleet management agreements that bundle device warranty, electrode supply, and predictive battery replacement scheduling. For New Entrants and Emerging Players: FDA Q-Sub pre-submission pathways offer the fastest qualification route for electrode substitutions targeting third-party compatible positions. White-space concentration exists in Bluetooth-enabled smart battery telemetry for automated external defibrillator fleet management software integration. Target corporate training peripheral procurement through direct sales to workplace safety officers bypassing traditional clinical distribution channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors suppliers with software-enabled service contract value pools over commodity replacement part vendors. Long-term viability across the analysis window hinges on EU MDR notified-body relationship depth and FDA 510(k) predicate device alignment. Acquisition targets should demonstrate established biocompatibility documentation and post-market surveillance infrastructure. Monitor notified-body capacity expansion announcements as the critical inflection signal for new supplier market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified-Body Relationship Expansion | Accelerates Class IIa electrode technical documentation review timelines for European market access. |
| Conductive Hydrogel Backward Integration | Captures margin from polymer chemistry advances extending electrode adhesion cycle performance. |
| Smart Battery Telemetry Platform Development | Enables condition-based replacement scheduling converging with fleet management software adoption. |
| Workplace Training Peripheral Direct Sales Channel | Bypasses clinical distribution to capture corporate CPR-AED certification mandate procurement volumes. |
| FDA Q-Sub Pre-Submission Engagement | Compresses 510(k) review timelines through predicate-device alignment for electrode substitution approvals. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract records. Interviews with biomedical equipment technicians, hospital purchasing committee members, group purchasing organization contract managers, and emergency medical services fleet supervisors informed demand-side validation. Secondary sources include FDA premarket notification filings, notified-body capacity reports, and conductive hydrogel polymer trade flow data. Bottom-up electrode and battery replacement volume estimates triangulate against top-down defibrillator installed base calculations.
Segmentation dimensions modeled span product type, end-user setting, device technology tier, and application intensity across the projection horizon. CAGRs derive from replacement cycle frequency analysis tied to calendar-life degradation curves and regulatory maintenance mandate compliance rates. Forecast inputs incorporate state-level public access defibrillation legislation expansion trajectories and EU MDR implementation phase transition timelines.
Underlying assumptions cover stable notified-body capacity expansion and FDA inspection backlog resolution, with deviation risk concentrated in biomedical equipment technician workforce availability and lithium raw material supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
Auto-Transfusion Systems Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
Surgical Display Market
Medical Devices
Deaver Retractor Market
Medical Devices
Smart Vision Aids Market
Medical Devices
Eye Massage Device Market