
 Europe Organ-On-Chip Market | 2026-2036
Europe Organ-On-Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Organ-On-Chip Market Insights
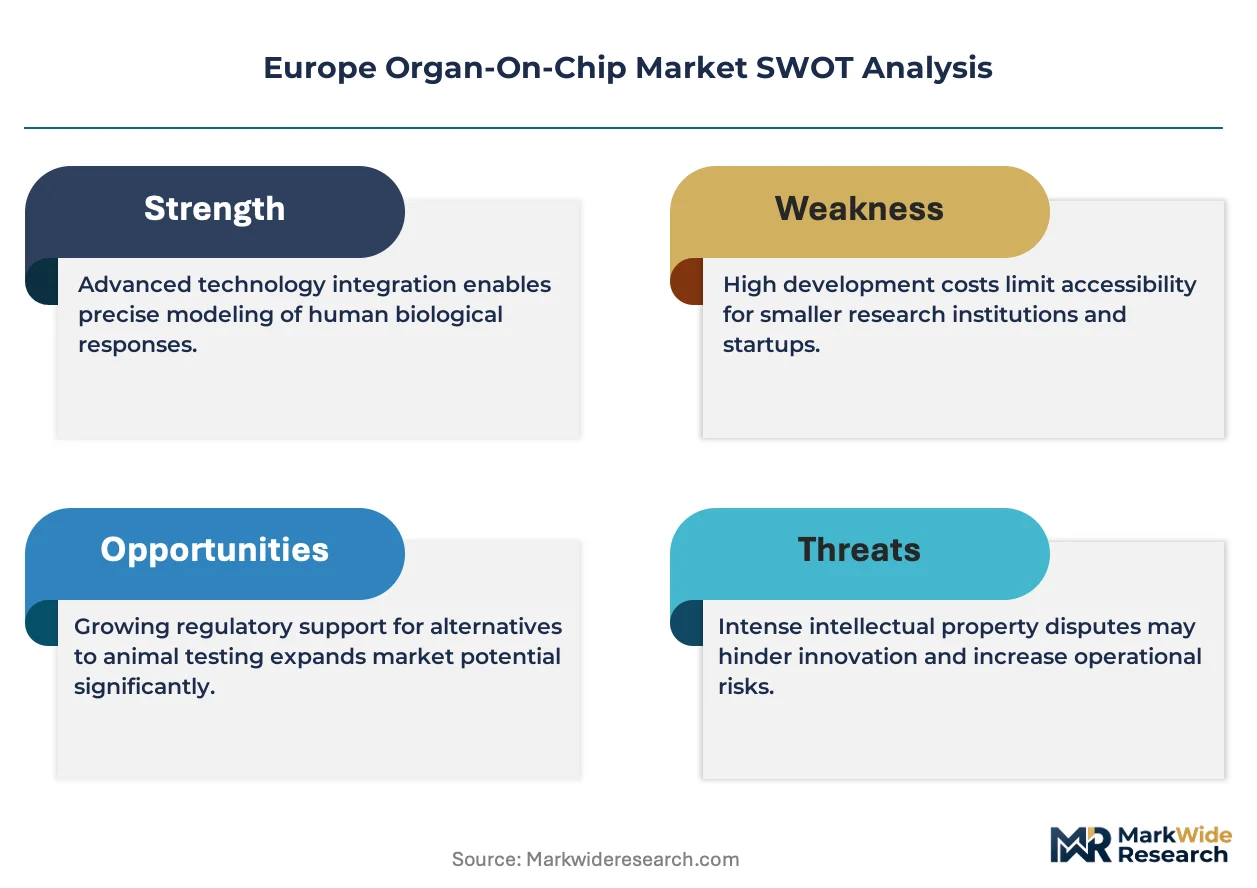
Software-defined assay workflows is decoupling hardware sales from recurring revenue in the Europe Organ-On-Chip space. MIMETAS B.V. leverages its OrganoPlate platform to dominate high-throughput perfused tissue models for pharmaceutical screening. BICO Group AB sustains broad portfolio coverage spanning bioprinting hardware through downstream analytics. AlveoliX AG specializes in lung-on-chip systems that anchor respiratory disease modeling contracts with Swiss and German research consortia.
Organ-on-chip technology integrates living human cells with microfluidic channels to replicate organ-level physiology, typically operating at microliter-scale volumes with continuous perfusion rates mimicking blood flow. These systems serve primarily to predict human drug responses before clinical trials, replacing animal models with physiologically relevant human tissue interfaces. Microfluidic devices command the largest installed base among product types due to their modularity and compatibility with standard laboratory automation. Drug testing applications absorb the majority of current spending, though personalized medicine segments are expanding fastest as biobanks and patient-derived cell sources mature. PDMS technology retains dominance in research settings for its optical clarity and ease of prototyping, while hydrogel-based systems are gaining share where extracellular matrix mimicry proves critical.
EMA guidelines on non-clinical safety evaluation and the EU Green Deal's animal testing reduction targets are reshaping validation requirements for preclinical models across member states. REACH restrictions on chemical hazard assessment are pushing toxicology departments toward human-relevant in vitro alternatives, directly expanding addressable demand. France's ANSM and Germany's BfArM are converging on qualification pathways for microphysiological systems in regulatory submissions. Stakeholders must monitor how EMA's qualification opinion process for organ-on-chip data evolves against traditional pharmacokinetic study packages.
Market Dynamics
EMA qualification pathways for microphysiological systems are compressing validation timelines and forcing contract research organizations to restructure their preclinical service portfolios around human-relevant in vitro data packages.
Growth Catalysts
- EU MDR and REACH frameworks:Tightening animal testing restrictions across member states are mandating pharmaceutical and chemical sectors to adopt human-relevant tissue models for regulatory submissions.
- Biotech hub clustering:Concentrated R&D infrastructure in Germany, Switzerland, and the United Kingdom is generating specialized demand for high-throughput perfused tissue screening platforms.
- Patient-derived cell maturation:Advancing biobank capabilities and induced pluripotent stem cell sourcing are enabling personalized medicine applications that require organ-specific microfluidic environments.
Market Restraints
- PDMS material limitations:Dominant silicone-based devices exhibit drug absorption and batch-to-batch variability that compromises pharmacokinetic study reproducibility in toxicology workflows.
- Specialized fabrication concentration:Cleanroom microfabrication expertise clusters in Swiss and German academic spin-offs, creating supply bottlenecks for standardized chip production at scale.
- EMA validation friction:Absence of harmonized qualification opinions for organ-on-chip data packages delays regulatory acceptance and extends pharmaceutical client decision cycles.
Strategic Opportunities
- French CRO underpenetration:ANSM's emerging qualification dialogue creates first-mover positioning for microphysiological system providers targeting Paris-Saclay and Lyon bioclusters.
- Multi-organ integration:Convergence of microfluidic perfusion with 3D bioprinting enables body-on-chip platforms that replicate systemic drug metabolism for chronic toxicity assessment.
- CE marking pathway expansion:EU MDR Class I device reclassification for certain organ-on-chip formats reduces notified body involvement and accelerates commercial deployment timelines.
Industry Challenges
- Microfluidic engineering talent scarcity:Cross-disciplinary expertise combining cell biology with MEMS fabrication remains concentrated in elite technical universities, constraining R&D team scaling.
- Pharmaceutical procurement inertia:Established toxicology departments maintain sunk investments in animal facility infrastructure, slowing budget reallocation toward in vitro platform validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Organ-On-Chip Market |
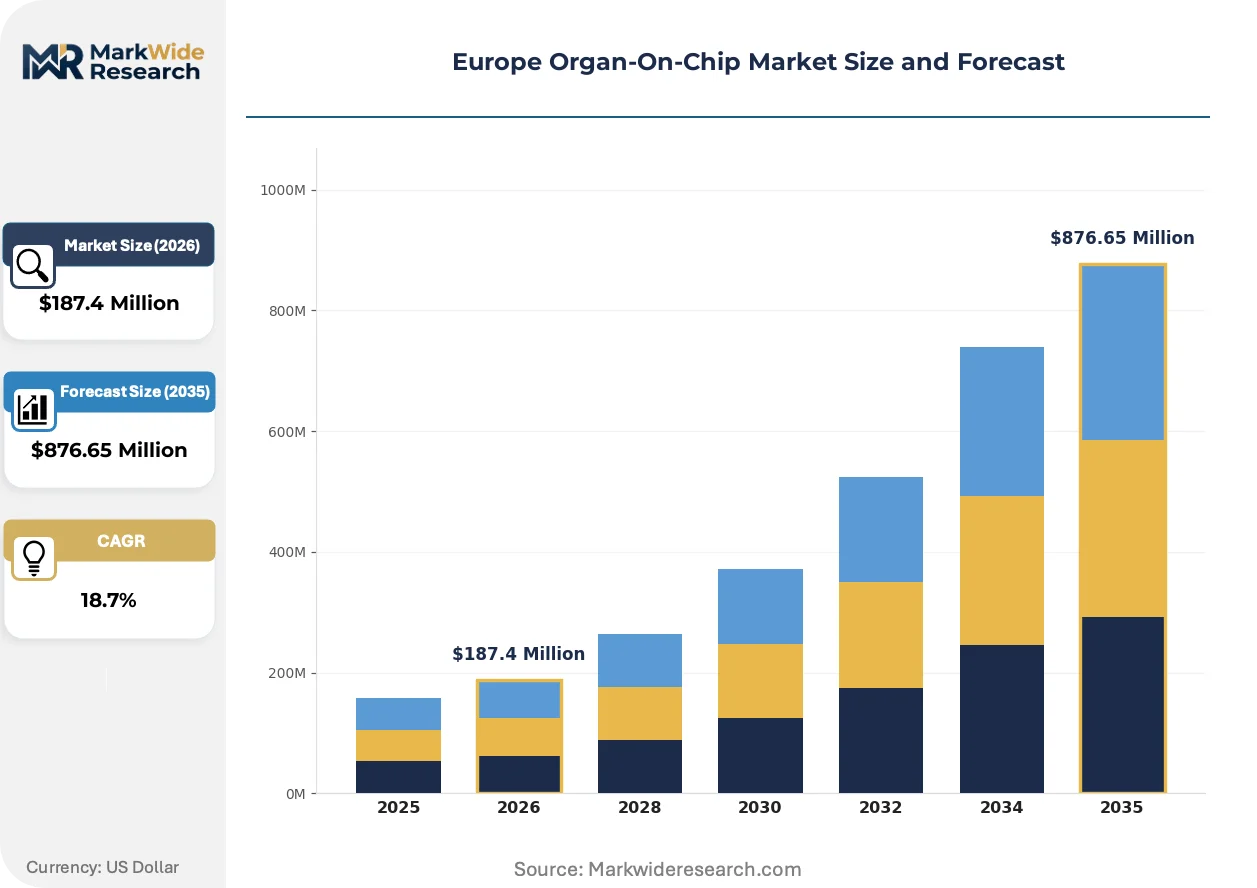
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidic Devices, Tissue Models, Organ Models, Cell Culture Plates Application: Drug Testing, Disease Modeling, Toxicity Testing, Personalized Medicine End User: Research Institutions, Pharmaceutical Companies, Biotechnology Firms, Academic Laboratories Technology: 3D Bioprinting, PMMA Technology, PDMS Technology, Hydrogel-based Systems |
| Companies Covered | BICO Group AB, AlveoliX AG, MIMETAS B.V., TissUse GmbH, CN Bio Innovations Ltd, InSphero, Dynamic42 GmbH, Fluigent, BiomimX S.r.l., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Organ-On-Chip Market Trends and Innovations
Hydrogel-based extracellular matrix mimics are displacing conventional PDMS substrates as pharmaceutical screening demands more physiologically relevant tissue interfaces. Software-defined assay workflows are decoupling hardware from recurring revenue. Regulatory qualification pathways are compressing validation timelines.
Photocrosslinkable hydrogel systems are expanding into liver and kidney model applications where stiffness-tunable matrices improve hepatocyte polarity and metabolic enzyme expression. Toxicology departments at mid-tier pharmaceutical firms are adopting these substrates faster than expected, compressing the competitive window for conventional PDMS providers to demonstrate functional equivalence.
REACH chemical hazard assessment restrictions are forcing toxicology service providers to demonstrate human-relevant exposure-response relationships. ECHA's 2023-2027 strategic roadmap explicitly prioritizes non-animal methods for skin sensitization and systemic toxicity endpoints. Contract research organizations in the Netherlands and Germany are restructuring their service catalogs to front-load organ-on-chip validation studies ahead of anticipated mandate expansion.
Pharmaceutical procurement departments are unbundling hardware acquisition from assay development services, favoring platform-agnostic contract research partners. Large-cap drug developers in Switzerland and the United Kingdom are consolidating vendor relationships around organizations that supply validated tissue models without captive instrumentation requirements. This pattern is most visible in respiratory disease programs where AlveoliX AG's lung-on-chip specifications have become informal procurement benchmarks.
Europe Organ-On-Chip Market Segmentation
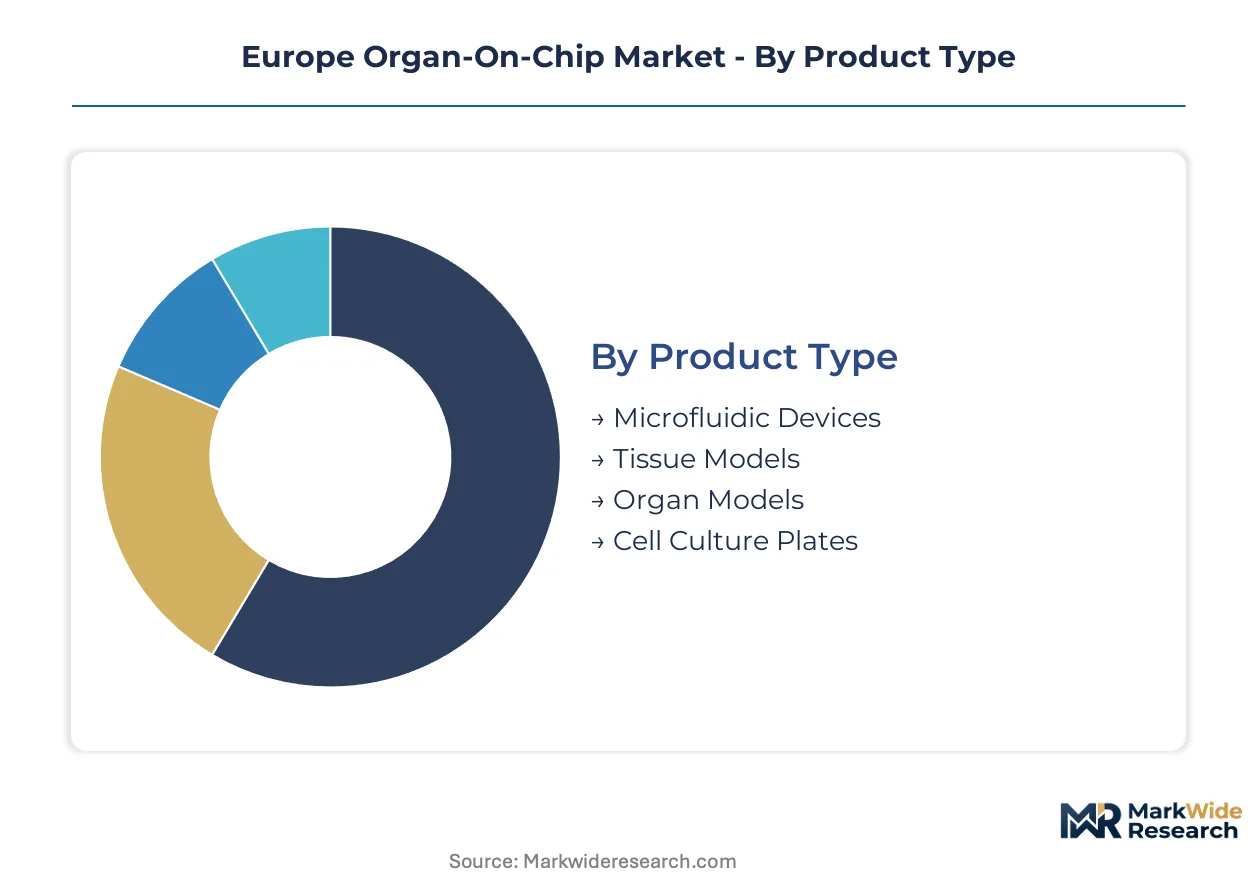
Organ-on-chip procurement patterns diverge sharply across product architectures, therapeutic applications, and institutional buyer types. Understanding these fault lines reveals where standardization pressures concentrate versus where customization premiums persist.
Product Type:
Cleanroom fabrication capacity clusters in Swiss and German academic spin-offs, concentrating supply leverage for complex microfluidic architectures.
- Microfluidic Devices:These systems integrate living cells with perfused channels at microliter scales, replicating organ-level physiology through continuous flow. German and Dutch pharmaceutical manufacturers dominate procurement, driven by REACH-mandated toxicology workflow replacements.
- Tissue Models:Pre-validated tissue constructs reduce assay development timelines for contract research organizations. Demand concentrates in United Kingdom biotech clusters where CROs restructure service portfolios around human-relevant data packages.
- Organ Models:Specialized liver, kidney, and lung configurations anchor respiratory and metabolic disease programs. Swiss research consortia specify these for chronic toxicity assessment contracts.
- Cell Culture Plates:Standardized multi-well formats bridge legacy automation infrastructure with organ-on-chip functionality. Academic laboratories in France and Belgium adopt these for budget-constrained pilot studies.
Today's leader: Microfluidic Devices. Tomorrow's challenger: Tissue Models.
Application:
Regulatory pressure intensity varies by therapeutic validation pathway, reshaping budget allocation across pharmaceutical R&D functions.
- Drug Testing:Primary revenue anchor where EMA qualification timelines compress preclinical decision cycles. Swiss and German drug developers front-load spending here to mitigate late-stage failure risks.
- Toxicity Testing:REACH restrictions and EU Green Deal targets mandate human-relevant alternatives for chemical hazard assessment. Netherlands-based toxicology service providers expand capacity fastest.
- Disease Modeling:Patient-derived cell integration enables mechanistic studies for rare diseases. United Kingdom biobanks drive specialized demand for neurodegenerative and respiratory indications.
- Personalized Medicine:Induced pluripotent stem cell sourcing matures, expanding fastest as biobank infrastructure scales. German university hospitals pilot these for oncology therapeutic selection.
Drug Testing commands current spending dominance. Personalized Medicine climbs the fastest as regulatory frameworks mature.
End User:
Procurement sophistication divides between capital-rich pharmaceutical incumbents and grant-dependent academic institutions.
- Pharmaceutical Companies:Integrated toxicology departments drive platform standardization, consolidating vendor relationships around validated tissue models without captive hardware requirements. Switzerland-based large-cap developers set informal procurement benchmarks.
- Biotechnology Firms:Mid-tier developers prioritize assay development services over hardware acquisition, favoring platform-agnostic contract research partners. United Kingdom clusters show highest outsourcing intensity.
- Research Institutions:Public funding cycles constrain capital deployment, favoring modular microfluidic devices compatible with existing automation. German Helmholtz centers anchor regional demand.
- Academic Laboratories:PDMS prototyping dominance persists where optical clarity and fabrication accessibility outweigh pharmacokinetic reproducibility concerns. French CNRS units concentrate basic research adoption.
Pharmaceutical Companies dictate pricing power today. Biotechnology Firms represent the fastest-growing procurement trajectory as CRO partnerships deepen.
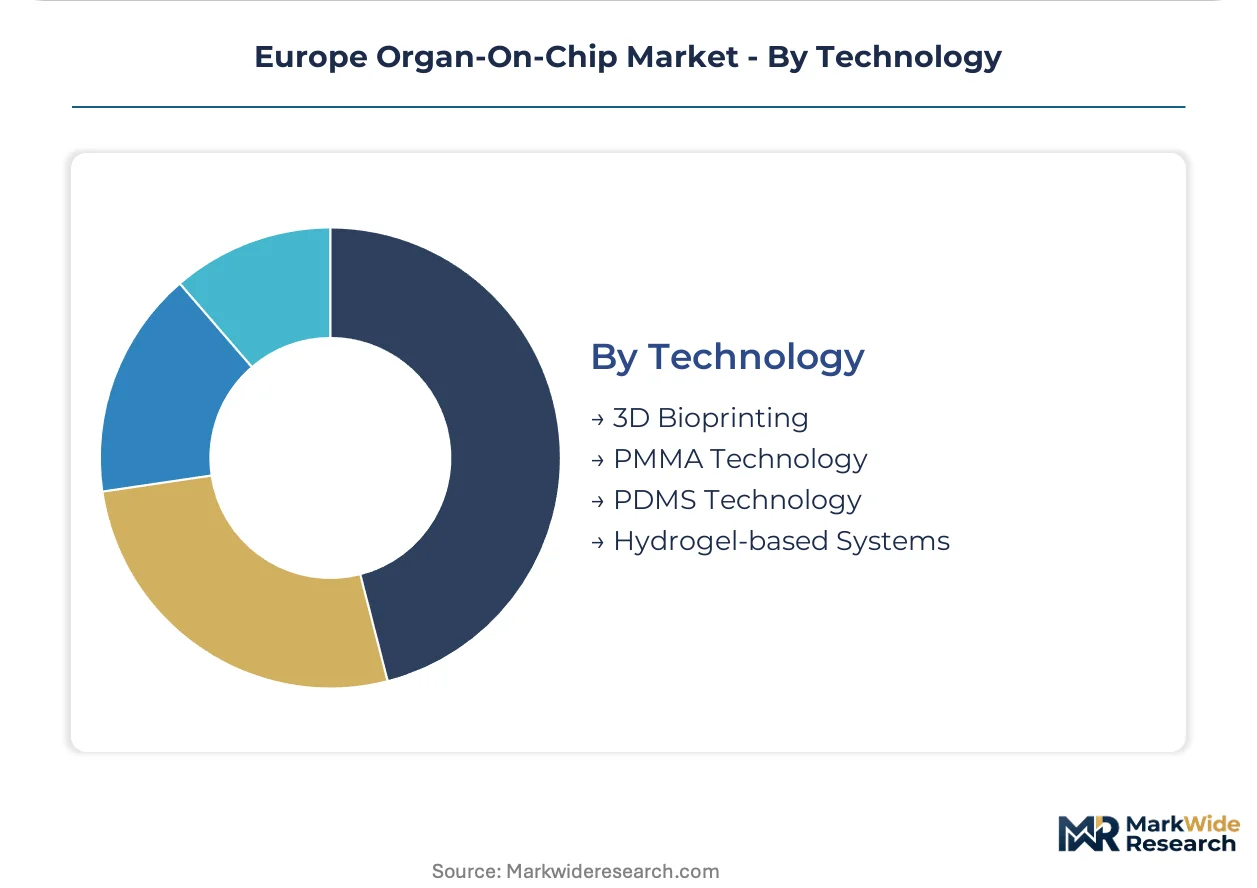
Technology:
Material science trade-offs between optical performance, batch consistency, and extracellular matrix fidelity segment competitive positioning.
- PDMS Technology:Silicone-based substrates retain research-setting dominance for optical clarity and rapid prototyping. Drug absorption and batch variability limitations drive pharmaceutical toxicology departments toward alternatives.
- Hydrogel-based Systems:Stiffness-tunable matrices improve hepatocyte polarity and metabolic enzyme expression in liver models. Mid-tier pharmaceutical firms in Germany and the Netherlands adopt faster than projected.
- 3D Bioprinting:Convergence with microfluidic perfusion enables body-on-chip platforms for systemic drug metabolism. Swiss technical universities anchor R&D concentration.
- PMMA Technology:Acrylic substrates offer intermediate optical and mechanical properties for standardized production. Emerging interest from French CROs seeking CE marking pathway efficiencies.
PDMS Technology holds installed base dominance. Hydrogel-based Systems gain share fastest where extracellular matrix mimicry proves critical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands higher absolute spending on organ-on-chip platforms than the United Kingdom, though British contract research organizations currently outsource more assay development services per capita to specialized vendors.
Germany
Pharmaceutical toxicology departments at Boehringer Ingelheim and Merck KGaA drive standardization demand for liver-on-chip models. BfArM qualification dialogues for microphysiological systems compress validation timelines for regulatory submissions. The Rhine-Main and Munich biotech clusters concentrate cleanroom fabrication expertise among academic spin-offs supplying PDMS and hydrogel devices.
United Kingdom
Mid-tier biotechnology firms prioritize platform-agnostic contract research partnerships over captive hardware investments. MHRA convergence with EMA qualification pathways accelerates adoption timelines for human-relevant preclinical data packages. The Cambridge-London corridor anchors specialized CRO capacity restructuring around validated tissue models.
Switzerland
Large-cap developers at Roche and Novartis consolidate vendor relationships around tissue model suppliers without instrumentation lock-in. Swissmedic maintains dialogue with EMA on microphysiological system acceptance criteria for safety pharmacology submissions. The Basel-Zurich axis hosts respiratory disease modeling contracts specifying lung-on-chip performance benchmarks.
Netherlands
REACH-mandated chemical hazard assessment pushes toxicology service providers toward human-relevant exposure-response demonstrations. ECHA's strategic roadmap prioritizes non-animal methods for skin sensitization endpoints. Leiden and Utrecht clusters expand organ-on-chip validation capacity ahead of anticipated regulatory mandate expansion.
France
ANSM's emerging qualification dialogue for microphysiological systems creates first-mover positioning opportunities. CNRS academic units concentrate basic research adoption of PDMS prototyping platforms for budget-constrained pilot studies. The Paris-Saclay and Lyon bioclusters underindex in CRO penetration relative to German and Swiss counterparts.
Europe Organ-On-Chip Market Competitive Landscape
Top-tier vendors anchor integrated platform offerings, while mid-tier specialists concentrate on tissue model supply without captive hardware requirements. The vendor base stratifies across three functional tiers: diversified life science conglomerates spanning bioprinting through analytics, pure-play microfluidic platform developers, and specialized organ-specific model providers. Strategic moves concentrate on portfolio unbundling to capture pharmaceutical procurement shifts, plus geographic expansion into underpenetrated French and Belgian CRO markets.
Among Dutch-origin platform developers, MIMETAS B.V. exemplifies the high-throughput perfused tissue screening archetype. BICO Group AB represents diversified conglomerate positioning across the hardware-to-analytics value chain. AlveoliX AG occupies a specialist position within respiratory disease modeling segments.
| Leading Market Players |
|---|
| BICO Group AB |
| AlveoliX AG |
| MIMETAS B.V. |
| TissUse GmbH |
| CN Bio Innovations Ltd |
| InSphero |
| Dynamic42 GmbH |
| Fluigent |
| BiomimX S.r.l. |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal animal testing reduction targets gate qualified supply for organ-on-chip platforms and premium-tier pricing access. REACH-mandated toxicology workflow replacements concentrate procurement power among pharmaceutical developers with validated tissue model requirements, compressing margins for non-compliant suppliers.
Pricing Analysis
Capacity additions in Swiss and German academic spin-offs are reshaping price floors for microfluidic device fabrication. Three-tier pricing structure across premium, standard, and economy levels segments by validation depth and regulatory qualification status. Cost compression in economy-tier PDMS prototyping intensifies as hydrogel-based alternatives capture mid-tier pharmaceutical contracts. Biotechnology firms in United Kingdom clusters exhibit highest price sensitivity, while Swiss large-cap developers prioritize assay reproducibility over unit cost.
Supply Chain Analysis
Refurbishment flows for precision microfluidic fabrication equipment concentrate secondary supply leverage among German cleanroom service providers. Germany, Switzerland, and the Netherlands anchor primary production capacity for PDMS and hydrogel substrates. Photolithography equipment and biocompatible polymers draw from specialized semiconductor and medical device supply chains. Single-source vulnerability around photoresist chemicals sourced from East Asian suppliers elevates disruption risk. Distribution runs through academic spin-offs and contract research organizations with captive fabrication expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between French CRO underpenetration and Swiss-German validation infrastructure density, exploiting ANSM-BfArM regulatory timeline differentials.
For Market Incumbents: Acquire specialized tissue model libraries to consolidate pharmaceutical procurement relationships around platform-agnostic supply. Hydrogel-based system developers threaten PDMS incumbents with faster pharmacokinetic validation cycles. Certification investment in EMA qualification pathways anchors defensive positioning against mid-tier entrants. For New Entrants and Emerging Players: Capture Paris-Saclay and Lyon biocluster contracts ahead of ANSM qualification pathway maturation. French toxicology service providers represent the most penetrable end-user segment given CRO restructuring timelines. Direct sales partnerships with German Helmholtz centers accelerate reference customer acquisition. For Investors and Strategic Acquirers: Roll-up economics work for specialized organ-specific model providers because EMA validation timelines compress competitive windows for standalone players. Five-to-ten year viability hinges on multi-organ integration capabilities. Monitor BfArM qualification opinion issuance frequency as inflection indicator for regulatory acceptance velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Qualification Pathway Investment | BfArM dialogue acceleration compresses validation timelines for liver-on-chip submissions. |
| French CRO Market Entry | ANSM emerging frameworks create first-mover positioning in underpenetrated Paris-Saclay cluster. |
| Hydrogel Substrate Transition | Stiffness-tunable matrices displace PDMS in mid-tier pharmaceutical toxicology departments. |
| Multi-Organ Platform Development | Body-on-chip convergence enables systemic drug metabolism contracts with Swiss research consortia. |
| Software-Defined Assay Unbundling | Recurring revenue decoupling from hardware sales captures pharmaceutical procurement shifts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with drug development executives, regulatory affairs leads at EMA and national agencies, toxicology department heads, and contract research organization procurement managers combined with secondary validation. EMA qualification opinion databases, REACH regulatory filings, ECHA strategic roadmap documents, and academic publication corpora anchored source triangulation. Bottom-up segment sizing and top-down market reconciliation verified magnitude estimates.
Segment-weighting approaches distributed value across product architectures, therapeutic applications, and institutional buyer types. Microfluidic devices, tissue models, organ models, and cell culture plates formed product dimensions alongside drug testing, toxicity testing, disease modeling, and personalized medicine applications. Pharmaceutical companies, biotechnology firms, research institutions, and academic laboratories structured end-user splits. CAGRs derived from installed base growth, replacement cycle analysis, and regulatory mandate expansion modeling. Patient-derived cell maturation curves and biobank infrastructure scaling informed personalized medicine trajectory assumptions.
EMA qualification opinion delays, hydrogel substrate batch consistency failures, and REACH mandate expansion timing are the dominant revision risks. Forecasts embed assumptions about regulatory acceptance velocity and pharmaceutical procurement budget reallocation. Practitioners should monitor ANSM-BfArM policy convergence and mid-tier pharmaceutical firm outsourcing intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
Guide Extension Catheter Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Global Contrast Media Injector Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Sperm Separation Systems Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
Spinal Osteosynthesis Units Market
Medical Devices
Tubal Obstruction Devices Market
Medical Devices
Europe Medical Devices Market