
 Single Use Contact Lenses Market | 2026-2036
Single Use Contact Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Single Use Contact Lenses Market Analytics
E-commerce distribution is fragmenting as direct-to-consumer platforms and telehealth-integrated channels redraw how single use contact lenses reach end users. Johnson & Johnson Vision Care leverages its Acuvue brand infrastructure to sustain dominant shelf presence across optometry offices and pharmacies. Alcon competes through its Precision1 and Dailies portfolios, anchoring premium positioning in silicone hydrogel daily disposables. CooperVision differentiates via Biofinity Energys and MyDay lines, specializing in digital eye strain and myopia management applications.
Single use contact lenses are sterile, individually packaged vision correction devices manufactured through cast-molding or lathe-cutting processes, typically incorporating hydrogel or silicone hydrogel polymers with water content ranging from thirty-eight to eighty percent and oxygen permeability values critical for corneal health. Their primary commercial purpose is to eliminate cleaning regimens, reduce infection risk, and support predictable replacement schedules for ametropic consumers. Spherical lenses dominate volume due to widespread myopia and hyperopia correction needs, while toric and multifocal variants command margin premiums by addressing astigmatism and presbyopia in aging populations. Silicone hydrogel leads material growth as practitioners prioritize higher oxygen transmissibility for extended daily wear compliance.
FDA 510(k) clearance requirements govern U.S. market entry for all new lens designs, while the EU Medical Device Regulation imposes stricter clinical evidence standards and post-market surveillance obligations on manufacturers serving European patients. The Contact Lens Rule enforced by the U.S. Federal Trade Commission mandates prescription verification for all sellers, shaping competitive dynamics between optometrist-controlled channels and online retailers. Stakeholders must monitor how telehealth prescription platforms and automated verification technologies reshape regulatory compliance burdens and channel economics.
Market Dynamics
Silicone hydrogel material substitution is compressing manufacturing margins while expanding clinical indications, forcing incumbents to reconfigure polymer supply chains and sterilization protocols around higher oxygen permeability specifications.
Growth Catalysts
- FDA 510(k) Streamlining:Accelerated clearance pathways for incremental lens design modifications reduce time-to-market for daily disposable variants, stimulating portfolio refreshes among established manufacturers.
- Telehealth Prescription Integration:Remote eye examination platforms paired with automated prescription verification expand addressable patient populations beyond traditional optometry office catchments.
- Myopia Progression Management:Pediatric ophthalmology protocols increasingly specify single-use lenses for juvenile myopia control, creating dedicated demand streams in school-age populations across East Asian markets.
Market Restraints
- Raw Material Concentration:Silicone hydrogel monomer supply concentrates among three specialty chemical producers in Germany and Japan, exposing lens manufacturers to input price volatility and allocation risk.
- EU MDR Compliance Burden:Stricter clinical evidence requirements and enhanced post-market surveillance obligations under the Medical Device Regulation extend certification timelines and inflate regulatory affairs staffing costs for European market entry.
- Refractive Surgery Substitution:Laser vision correction procedures, particularly SMILE and femtosecond LASIK, capture younger ametropic patients who would otherwise convert to long-term daily disposable lens wear.
Strategic Opportunities
- India Vision Correction Penetration:Contact lens wearing rates remain below five percent of addressable ametropic population, presenting first-mover advantages for daily disposable education and trial programs in tier-one cities.
- Blue Light Filtering Formulations:Polymer additives blocking high-energy visible light converge with digital eye strain complaints, opening premium positioning for screen-worker-specific daily disposable SKUs.
- Subscription Commerce Infrastructure:Direct-to-consumer replenishment platforms with AI-driven wear-schedule optimization reduce patient dropout rates and capture lifetime value previously fragmented through retail pharmacy channels.
Industry Challenges
- Specialized Polymer Chemistry Talent:Formulation scientists with expertise in silicone hydrogel copolymerization and surface wettability engineering command premium compensation, constraining R&D expansion at mid-tier manufacturers.
- Cleanroom Capital Intensity:Cast-molding production lines requiring ISO 14644 Class 7 environments and automated lens inspection systems demand eight-figure capital commitments per manufacturing facility.
- Prescription Verification Automation:FTC Contact Lens Rule compliance systems must integrate with disparate optometry practice management software, creating implementation friction for pure-play e-commerce entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Use Contact Lenses Market |
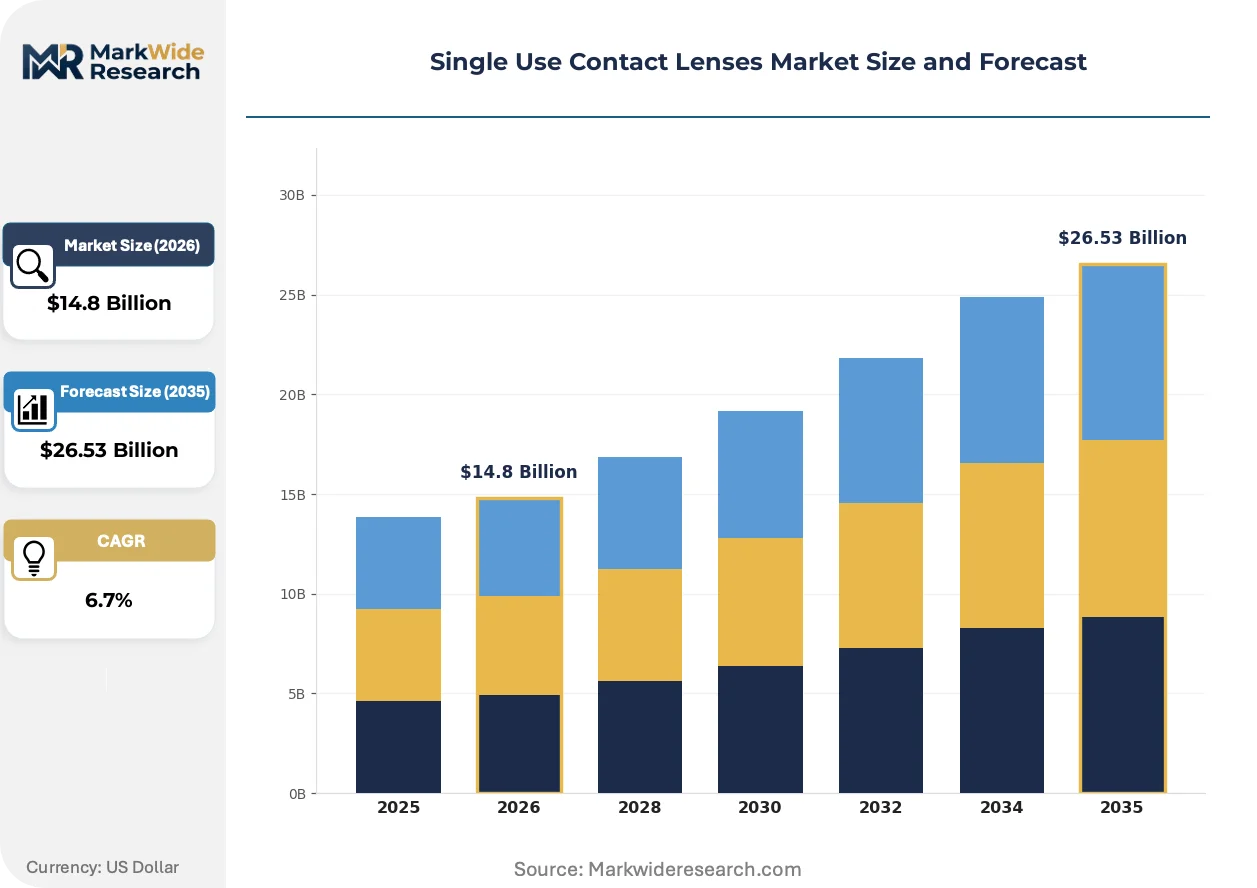
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spherical, Toric, Multifocal, Colored Material: Hydrogel, Silicone Hydrogel, Plastic, Others End User: Retail Consumers, Eye Care Professionals, Clinics, Online Shoppers Distribution Channel: Optometry Offices, Pharmacies, Specialty Stores, E-commerce |
| Companies Covered | Johnson & Johnson Vision Care, Alcon, CooperVision, Bausch + Lomb, The Cooper Companies, Menicon, Carl Zeiss Meditec, Hoya Corporation, EssilorLuxottica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Use Contact Lenses Market Evolving Landscape
Material science breakthroughs and regulatory digitization are compressing product lifecycles while telehealth integration restructures how prescriptions originate and convert to recurring lens shipments.
Silicone hydrogel formulations with water gradients—higher water content at the surface transitioning to silicone-rich cores—deliver simultaneous oxygen transmissibility and surface lubricity without supplemental wetting agents. Practitioners fitting extended daily wear schedules are adopting these materials at accelerating rates for patients with dry eye predisposition. Conventional hydrogel daily disposables lacking silicone components are rendering obsolete in premium segments as practitioners prioritize corneal physiological safety metrics.
EU Medical Device Regulation post-market surveillance requirements now mandate systematic collection of serious incident reports and periodic safety update reports for all lens classes. Manufacturers must maintain vigilance systems capable of traceability to individual production batches, inflating quality management system complexity. High-volume daily disposable producers serving European markets are responding by consolidating supplier audits and implementing blockchain-anchored batch records.
Subscription-based replenishment models with automated wear-schedule tracking are displacing episodic pharmacy purchases among digital-native contact lens wearers. Direct-to-consumer platforms with integrated telehealth prescription renewal capture patient lifetime value previously fragmented through optometry office dispensing. This behavioral shift concentrates most visibly in United States metropolitan markets where employer-sponsored vision benefits increasingly permit online redemption.
Single Use Contact Lenses Market Segmentation
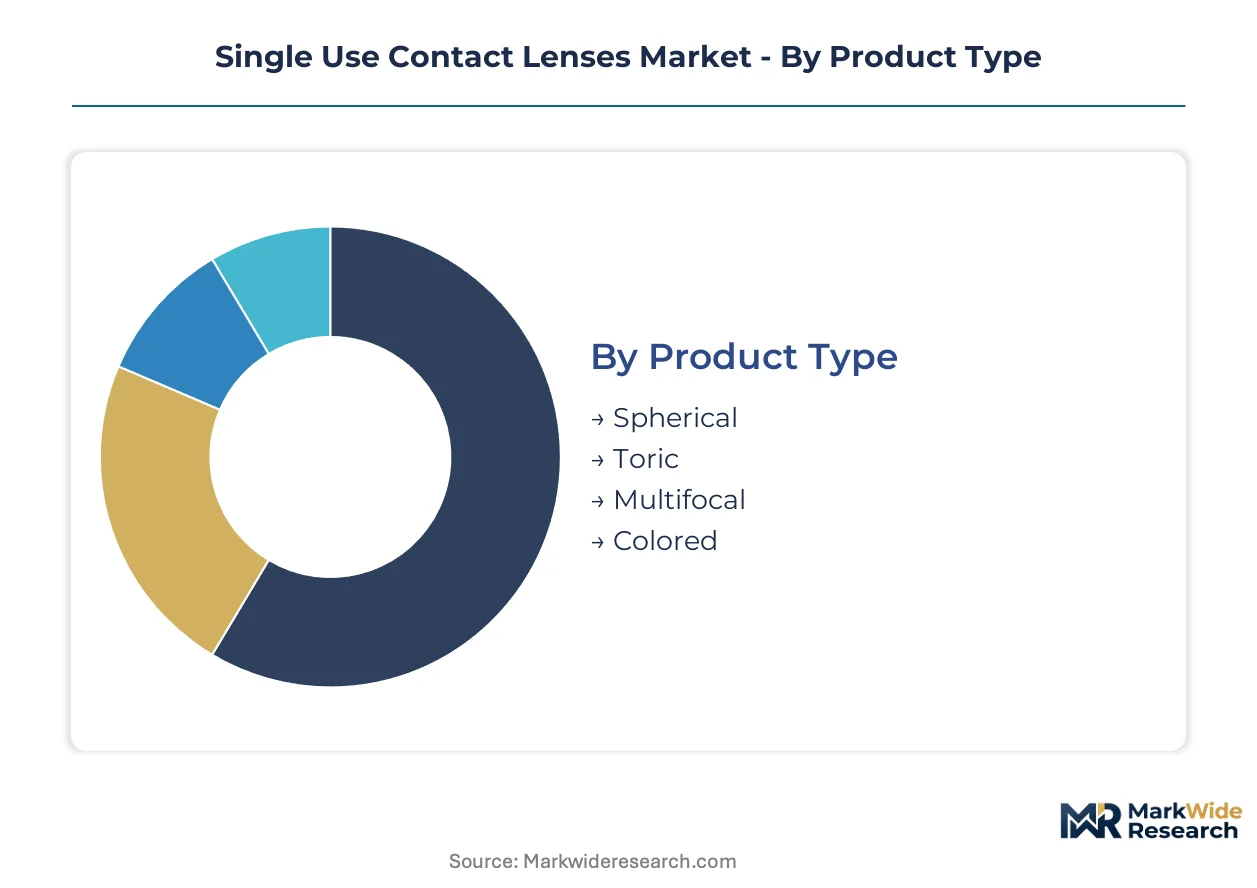
Segmentation in single use contact lenses reveals how material innovation, prescription complexity, and channel economics partition revenue across distinct patient needs and purchasing behaviors. Understanding these divides illuminates where manufacturers concentrate R&D investment versus where distributors capture margin.
Product Type:
Mature spherical correction dominates volume throughput, while emerging specialty designs reshape profitability profiles across aging demographics and aesthetic preferences.
- Spherical:Corrects simple myopia or hyperopia through uniform curvature across the entire optical zone. Demand concentrates among younger ametropic patients in the United States and East Asian school-age populations, driven by high-volume daily disposable protocols and myopia progression management programs.
- Toric:Incorporates two distinct curvatures to correct astigmatism, requiring precise rotational stability on-eye. Prescription volume clusters among working-age adults in Germany and Japan, where diagnostic precision and fitting expertise support premium positioning for this technically demanding category.
- Multifocal:Simultaneous vision designs with concentric or aspheric power zones address presbyopia without reading glasses. Growing adoption among professionals aged 45-60 in metropolitan US markets links to workplace productivity demands and reduced tolerance for bifocal spectacles.
- Colored:Cosmetic tinting with or without prescription power serves fashion-forward and theatrical applications. Trial rates surge among digital-native consumers in tier-one Indian cities and Brazilian urban centers, where social media visibility drives aesthetic lens experimentation.
Spherical lenses handle the majority of throughput; multifocal designs are climbing the fastest on share as presbyopic populations expand.
Material:
Cost tier stratification separates legacy hydrogel from premium silicone hydrogel, with plastic alternatives occupying economy positioning and experimental polymers probing niche indications.
- Hydrogel:Conventional polymer networks with 38-55% water content and moderate oxygen permeability. Volume persists in price-sensitive emerging markets and institutional procurement in Mexico and Southeast Asia, constrained by practitioner preference for physiological safety metrics favoring newer materials.
- Silicone Hydrogel:Silicone-integrated copolymers achieving 100+ Dk/t oxygen transmissibility with surface water gradients. Premium positioning in the United States, United Kingdom, and South Korea reflects practitioner prioritization of extended wear safety and dry eye patient compatibility.
- Plastic:Rigid gas-permeable daily disposables for specialized corneal conditions. Niche adoption among keratoconus patients in Australia and Canada leverages optical precision unavailable in soft lens alternatives.
- Others:Experimental biodegradable polymers and drug-eluting formulations in clinical development. Early trials in Swiss and Dutch academic medical centers explore sustained-release glaucoma medication delivery through disposable lens platforms.
Silicone hydrogel commands the dominant revenue share; biodegradable alternatives are gaining share fastest in sustainability-focused European markets.
End User:
Customer type segmentation tracks the shift from professional-mediated fitting toward self-directed digital purchasing, with clinical channels retaining complex prescription authority.
- Retail Consumers:Individual patients purchasing for personal use through any channel. Concentration in US employer-sponsored vision benefit programs and Japanese convenience store trial packs reflects accessibility-driven replenishment behaviors.
- Eye Care Professionals:Optometrists and ophthalmologists conducting diagnostic fitting and initial supply. Retained influence in toric and multifocal dispensing in France and Italy, where regulatory frameworks reinforce professional gatekeeping.
- Clinics:Institutional purchasers including hospital ophthalmology departments and surgical centers. Bulk procurement in China's public hospital system and India's corporate hospital chains supports post-refractive surgery and therapeutic lens applications.
- Online Shoppers:Direct-to-consumer purchasers via e-commerce platforms and subscription services. Fastest expansion among digital-native cohorts in US metropolitan markets and Nordic countries, where telehealth prescription integration reduces friction.
Retail consumers handle the majority of throughput; online shoppers represent the steepest expansion trajectory as telehealth infrastructure matures.
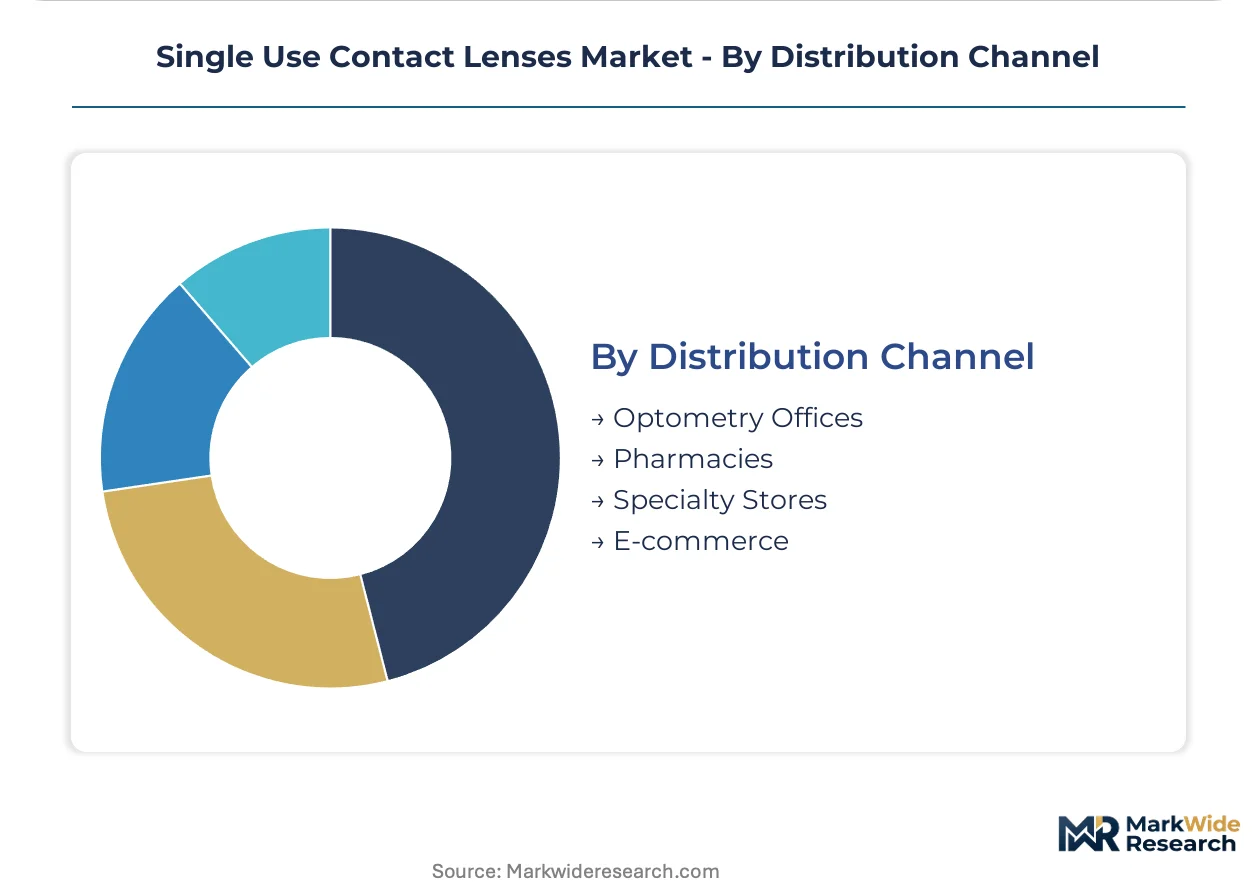
Distribution Channel:
Channel geography determines margin capture, with professional offices defending high-touch service premiums against e-commerce scale economies and pharmacy convenience positioning.
- Optometry Offices:Professional fitting with diagnostic equipment and personalized consultation. Dominates complex prescription categories in Germany, Japan, and Australia, where practitioner-patient relationships sustain premium pricing power.
- Pharmacies:Over-the-counter and prescription fulfillment with pharmacist guidance. Strong penetration in UK high street chains and Brazilian drugstore networks leverages foot traffic and insurance reimbursement convenience.
- Specialty Stores:Dedicated optical retailers with extended brand portfolios and aesthetic focus. Concentration in Italian fashion districts and South Korean shopping precincts serves colored lens and premium brand experimentation.
- E-commerce:Direct-to-consumer platforms with automated replenishment and telehealth integration. Subscription growth in US and Canadian markets concentrates among employed millennials seeking price transparency and wear-schedule optimization tools.
Optometry offices handle the majority of premium throughput; e-commerce is expanding most quickly on volume share as prescription verification automation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors trans-Pacific distribution for silicone hydrogel monomers, underwriting North America's manufacturing footprint. European rail corridors linking Frankfurt and Rotterdam sustain just-in-time polymer logistics. East Asian port clusters in Busan and Shanghai concentrate cast-molding capacity.
United States
Employer-sponsored vision benefits and telehealth prescription platforms drive daily disposable adoption among employed millennials. The FTC Contact Lens Rule mandates automated prescription verification, reshaping channel economics between optometry offices and e-commerce platforms. Johnson & Johnson Vision Care maintains manufacturing presence in Jacksonville, Florida, serving domestic replenishment demand.
Germany
Precision toric fitting expertise and statutory health insurance reimbursement sustain premium positioning for complex prescriptions. The EU Medical Device Regulation imposes batch-level traceability requirements, elevating quality management system costs. Heidelberg and Munich host specialized polymer chemistry research clusters advancing water gradient formulations.
Japan
Convenience store trial pack distribution and aging presbyopic populations expand multifocal lens penetration. METI guidelines on medical device software govern telehealth platform integration with prescription workflows. Osaka-based manufacturing facilities supply domestic silicone hydrogel demand with minimal import dependency.
India
Contact lens wearing rates below five percent of addressable ametropes create first-mover opportunities in tier-one cities. CDSCO medical device regulations require import licensing and local authorized representation for foreign manufacturers. Mumbai and Delhi-NCR clusters concentrate optometry training institutions and initial specialty retail presence.
South Korea
High myopia prevalence among school-age populations and national vision screening programs drive pediatric single-use lens protocols. MFDS oversees clinical trial requirements for myopia progression control indications. Seoul metropolitan area hosts dedicated optical retail precincts serving colored lens and premium brand experimentation.
Single Use Contact Lenses Market Competitive Landscape
On the supply side, the industry is consolidated around three integrated ophthalmic multinationals with captive polymer supply chains and established regulatory affairs infrastructure. Mid-tier specialists occupy niche positions in rigid gas-permeable daily disposables and therapeutic indications. Strategic archetypes include: diversified healthcare conglomerates with vision care divisions, pure-play contact lens manufacturers with regional manufacturing footprints, and optical equipment specialists backward-integrating into lens production. Dominant competitive moves center on silicone hydrogel material licensing agreements and direct-to-consumer subscription platform acquisitions.
Among diversified healthcare conglomerates, Johnson & Johnson Vision Care and Alcon exemplify archetypes with established brand infrastructure spanning professional and retail channels. CooperVision occupies a position within the pure-play specialist tier, with organizational structure dedicated exclusively to contact lens and myopia management applications. These three anchors collectively represent the supply-side concentration governing material innovation cycles and prescription verification system standards.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care |
| Alcon |
| CooperVision |
| Bausch + Lomb |
| The Cooper Companies |
| Menicon |
| Carl Zeiss Meditec |
| Hoya Corporation |
| EssilorLuxottica |
| Others |
Value Network & Pricing Analysis
German and Japanese specialty chemical producers dominate silicone hydrogel monomer supply, anchoring margin capture upstream while lens manufacturers downstream absorb input volatility through subscription pricing models that lock in patient lifetime value.
Pricing Analysis
Volume-discount tiering structures separate annual subscription commitments from episodic retail purchases, with silicone hydrogel daily disposables commanding premium positioning against conventional hydrogel alternatives. Price differentiation rests on oxygen permeability certification tiers and practitioner fitting fees bundled into initial prescriptions. Pricing pressure stems from telehealth platforms automating prescription verification and compressing dispensing margins. Price sensitivity concentrates among first-time wearers in emerging markets, while established silicone hydrogel users in the United States and United Kingdom exhibit lower elasticity.
Supply Chain Analysis
Export-control regimes on advanced polymer synthesis equipment limit technology transfer to aspiring manufacturers in India and Southeast Asia, preserving incumbent advantages in high-oxygen-permeability formulations. Raw material flows concentrate in Germany, Japan, and the United States for silicone hydrogel monomers, with cast-molding equipment sourced from Swiss and Italian precision engineering specialists. Supply chain risk centers on single-source vulnerability for surface-active polymer additives. Distribution runs through optometry offices for complex prescriptions, e-commerce platforms for replenishment, and pharmacy chains for trial conversions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single use contact lenses fragment across material tiers, prescription complexity, and channel economics, with telehealth prescription origination creating new entry points beyond traditional professional gatekeeping.
For Market Incumbents: Insulate silicone hydrogel supply positions through captive polymer chemistry partnerships and backward integration into monomer production. Lock in optometry office channel control via exclusive fitting software integrations that complicate competitor lens substitution. Defend against refractive surgery substitution by embedding myopia progression protocols into pediatric practice guidelines. For New Entrants and Emerging Players: Tier-one Indian cities with contact lens penetration below five percent represent the most penetrable entry point for daily disposable education and trial programs. Blue light filtering formulations for screen-worker segments in South Korean and United States metropolitan markets offer premium positioning without incumbent patent thickets. Direct-to-consumer subscription platforms with AI-driven wear-schedule optimization provide the essential go-to-market angle for patient retention. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play contact lens manufacturers with established regulatory affairs infrastructure and regional manufacturing footprints serving EU MDR and FDA 510(k) pathways. Long-term viability hinges on material science capabilities in silicone hydrogel water gradient formulations and telehealth platform integration. Watch for FDA clearance streamlining announcements as inflection indicators for portfolio refresh velocity and time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Hydrogel Material Licensing | Secures oxygen permeability advantages for extended daily wear compliance under FDA 510(k) pathways. |
| Telehealth Platform Acquisition | Captures prescription origination and automated verification infrastructure reshaping FTC Contact Lens Rule compliance. |
| Subscription Commerce Infrastructure | Reduces patient dropout rates through AI-driven wear-schedule optimization and recurring revenue capture. |
| Myopia Management Protocol Development | Positions pediatric single-use lenses as clinical standard for juvenile myopia progression control in East Asian markets. |
| Blue Light Filtering Formulation Launch | Addresses digital eye strain complaints among screen workers with premium polymer additive positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, and contact lens industry trade data. Primary interviews engaged regulatory affairs directors at ophthalmic multinationals, optometry practice owners, and polymer chemistry specialists at German and Japanese specialty chemical producers. Secondary validation drew from FTC enforcement actions, CMS vision benefit utilization data, and customs import records for silicone hydrogel monomers. Bottom-up patient population modeling triangulated against top-down manufacturer revenue aggregation across material and prescription complexity tiers.
Forecast inputs include myopia prevalence trajectories, telehealth platform penetration rates, and employer-sponsored vision benefit expansion patterns across the analysis window. Segmentation dimensions modeled encompass material chemistry tiers, spherical-toric-multifocal prescription categories, and optometry-pharmacy-e-commerce channel splits. CAGRs derive from patient population growth, replacement frequency shifts, and premium material substitution elasticities. Industry-specific inputs incorporate EU MDR certification timeline delays and FDA 510(k) clearance velocity for incremental lens designs.
Practitioners should monitor regulatory digitization timelines, raw material allocation announcements from monomer suppliers, and refractive surgery adoption curves for early signals of forecast deviation. Forecasts reflect assumptions regarding telehealth prescription platform scalability and practitioner fitting fee structures. Material shifts in EU MDR post-market surveillance enforcement intensity or silicone hydrogel monomer supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Cryoablation Devices Market
Medical Devices
Europe Surgical Microscopes Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Bone Power Tools Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Microscope Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Implantable Collamer Lens Market
Medical Devices
Medical Device Outsourcing Market