
 Ready-To-Use Laboratory Test Kits Market | 2026-2036
Ready-To-Use Laboratory Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Use Laboratory Test Kits Market Analytics
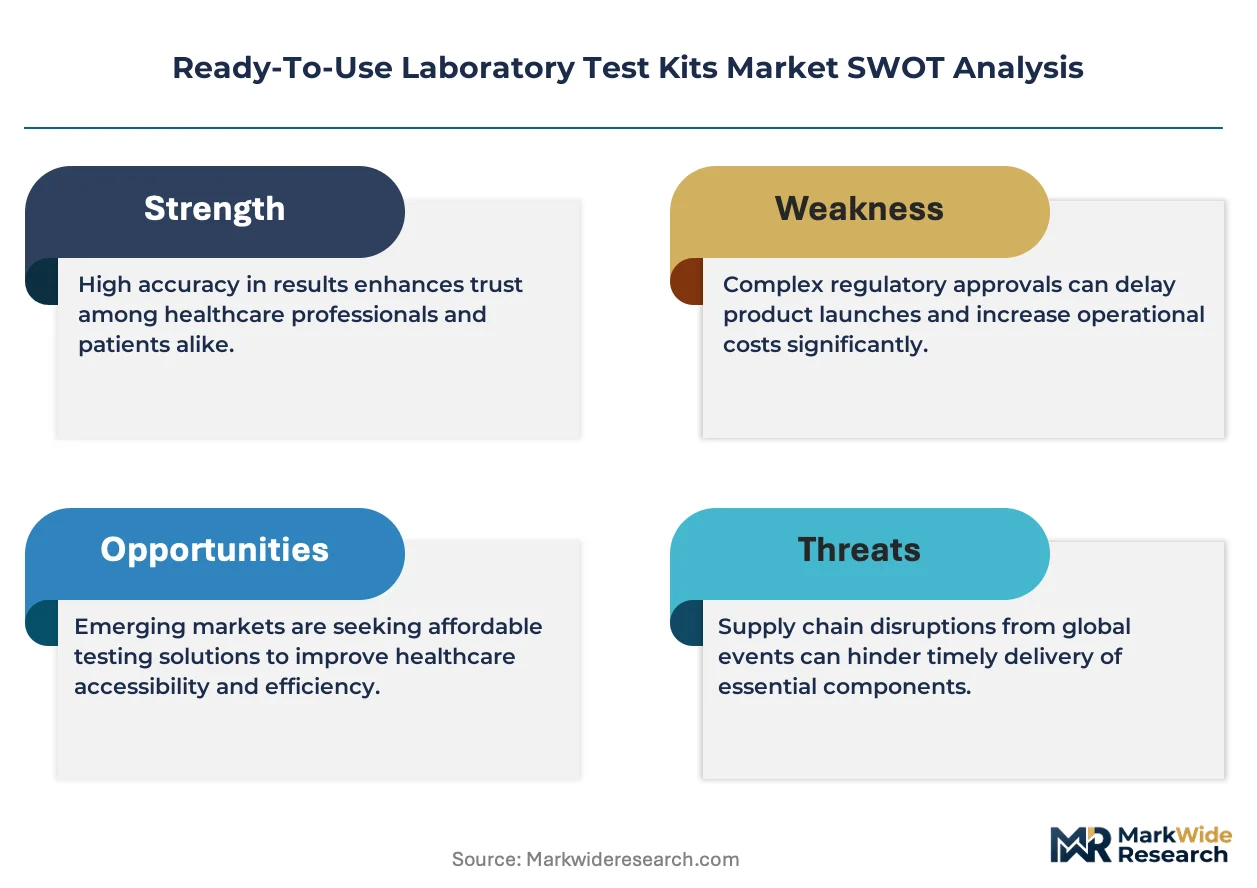
CE-IVD and FDA-cleared specification tiers is collapsing into a single premium-validated band as laboratories seek to reduce in-house assay development overhead. Abbott leverages backward integration into reagent manufacturing to sustain margin control across infectious disease panels. Thermo Fisher Scientific anchors North American distribution through direct channel contracts with integrated delivery networks. bioMérieux SA specializes in immunoassay automation, competing on turnaround-time guarantees rather than kit pricing alone.
Ready-to-use laboratory test kits are pre-formulated diagnostic reagent systems supplied in sealed, stability-tested configurations with defined sensitivity and specificity parameters, manufactured under ISO 13485 quality management to eliminate end-user preparation steps. These products serve clinical laboratories requiring reproducible results without batch-to-batch calibration drift. Infectious disease panels occupy the largest revenue pool given recurring respiratory and bloodstream pathogen screening volumes, while lateral flow formats represent the fastest-expanding technology segment as point-of-care sites adopt visual-read platforms. Home users constitute the smallest but most margin-accretive end-user category due to premium pricing on over-the-counter sexual health and fertility assays.
FDA enforces premarket notification pathways under 21 CFR 809 for moderate-complexity kits, while EMA's In Vitro Diagnostic Regulation mandates notified-body conformity assessment for CE marking. ISO 15189 accreditation requirements in hospital laboratories further filter supplier eligibility toward manufacturers with documented analytical performance claims. Stakeholders must monitor evolving WHO prequalification criteria for diagnostics in low-resource settings, as these standards increasingly influence procurement specifications in emerging-market tenders.
Market Dynamics
Centralized hospital procurement offices are consolidating vendor panels around dual FDA-EMA cleared platforms, compressing supplier diversity and forcing mid-tier manufacturers toward private-label partnerships or exit.
Growth Catalysts
- IVDR Convergence:EMA's In Vitro Diagnostic Regulation harmonizes CE-IVD standards across EU member states, reducing duplicate validation costs for kit manufacturers seeking European market entry.
- Respiratory Panel Volume:Seasonal respiratory pathogen surveillance programs in Germany and the United States generate recurring bulk orders for multiplex immunoassay formats.
- Stabilized Reagent Chemistry:Lyophilized master-mix formulations extend cold-chain tolerance, enabling distribution to clinical laboratories in regions with intermittent refrigeration infrastructure.
Market Restraints
- Polymerase Cost Volatility:Reverse transcriptase and DNA polymerase enzymes face supply concentration among three specialty chemical suppliers, creating input price instability for molecular diagnostic kit producers.
- Notified-Body Bottleneck:EMA-designated conformity assessment bodies maintain 12-18 month queues for IVDR technical documentation review, delaying product launches regardless of analytical validation completeness.
- Lateral Flow Substitution:Visual-read point-of-care devices capture routine infectious disease screening volume previously directed to laboratory analyzers, compressing central lab kit pull-through.
Strategic Opportunities
- India Diagnostic Expansion:CDSCO's streamlined medical device registration pathway and PLI scheme incentives attract kit manufacturers to establish localized production for domestic hospital network tenders.
- At-Home Fertility Tracking:Over-the-counter luteinizing hormone and progesterone metabolite assays command premium pricing from direct-to-consumer channels, bypassing institutional procurement discount structures.
- Digital Connectivity Mandates:FDA's guidance on interoperability for in vitro diagnostic data systems creates demand for kits with embedded RFID lot tracking and automated result transmission to laboratory information systems.
Industry Challenges
- ISO 15189 Auditor Shortage:Hospital laboratory accreditation bodies lack sufficient trained assessors to clear backlogs, delaying supplier qualification and contract activation timelines.
- Legacy Analyzer Integration:Pre-validated kits must maintain backward compatibility with installed bases of 10-15 year-old immunoassay platforms, constraining reagent reformulation flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Use Laboratory Test Kits Market |
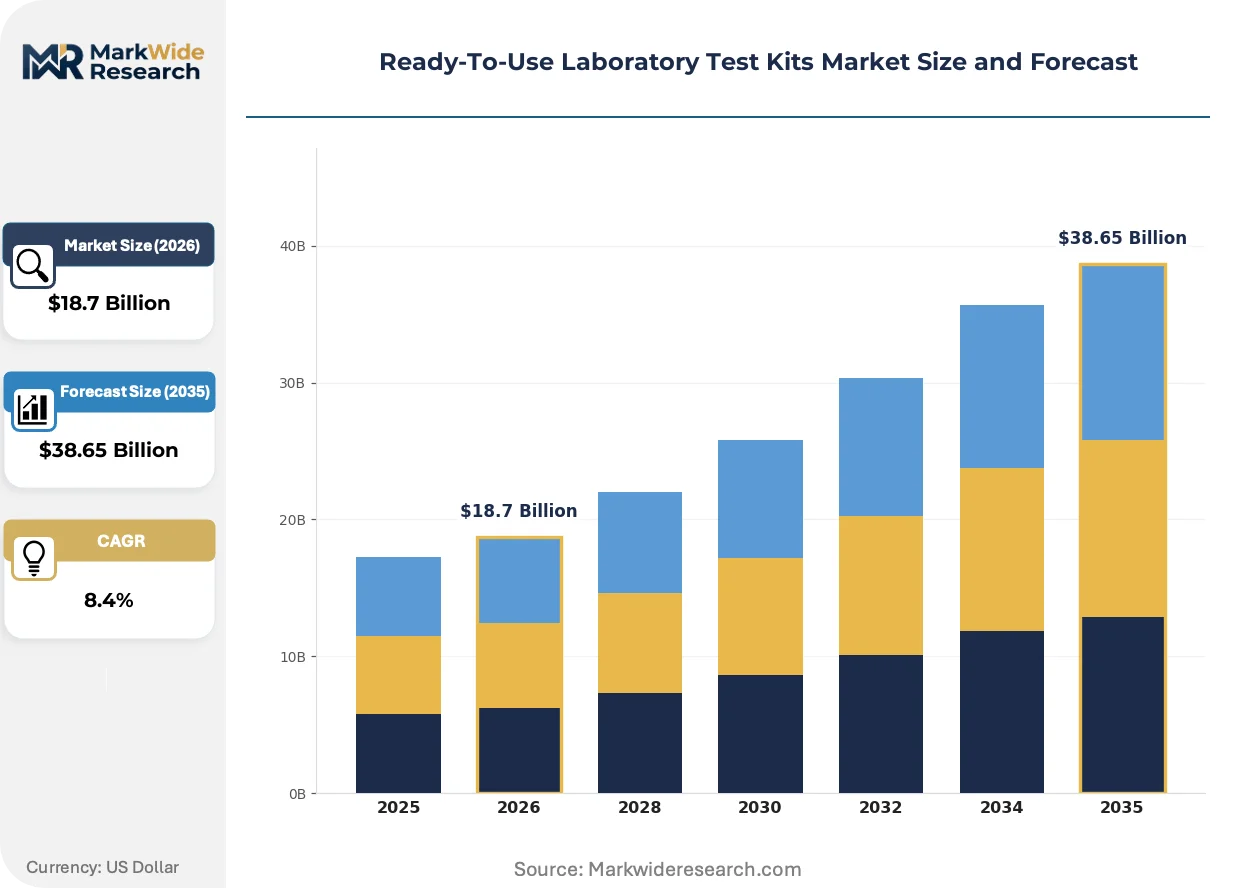
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infectious Disease, Cancer, Cardiac Markers, Drug Testing End User: Hospitals, Diagnostics Labs, Home Users, Research Institutions Application: Clinical Diagnostics, Environmental Testing, Food Safety, Veterinary Testing Technology: ELISA, PCR, Immunoassay, Lateral Flow |
| Companies Covered | Abbott, Thermo Fisher Scientific, Inc., F. Hoffmann-La Roche Ltd., Danaher Corporation, bioMérieux SA, DiaSorin S.P.A, Quidel Corporation, ACON Laboratories, Inc., OraSure Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Use Laboratory Test Kits Market Evolving Landscape
Reagent manufacturing and assay design are converging around shelf-stability engineering and automated sample-to-answer processing, compressing the traditional separation between kit suppliers and platform manufacturers.
Lyophilized bead-based reagent formats are displacing liquid-phase master mixes in infectious disease panels. Clinical laboratories in the United States and Germany are adopting these formats to eliminate cold-chain dependency and reduce shipping costs. The technology is displacing regional distribution center requirements, enabling direct-to-laboratory fulfillment from centralized manufacturing sites.
EMA's In Vitro Diagnostic Regulation enforcement timeline is compressing the window for legacy CE-IVD certificate reliance. Kit manufacturers must complete notified-body conformity assessment by May 2026 or withdraw products from EU markets. Medium-scale specialty assay producers are responding by prioritizing high-volume infectious disease panels for IVDR transition while discontinuing niche oncology biomarker kits.
Integrated delivery networks are consolidating laboratory procurement decisions at the system level rather than individual hospital autonomy. Group purchasing organizations in the United States are replacing site-specific vendor relationships with multi-year sole-source contracts spanning 50-400 affiliated laboratories. This concentration is most visible in Texas and Florida health systems, where three IDNs control diagnostic supply decisions for over sixty percent of hospital beds in their respective states.
Ready-To-Use Laboratory Test Kits Market Segmentation
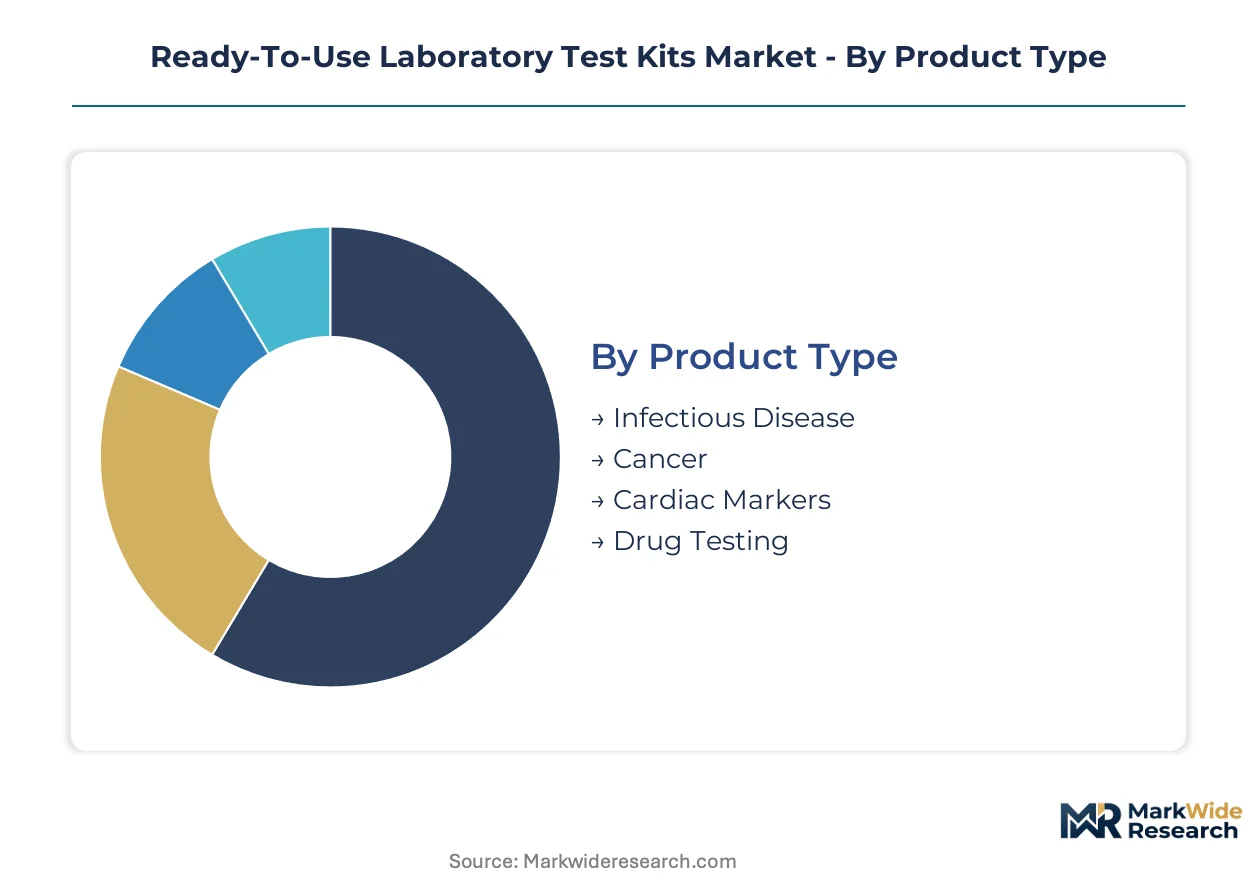
Segmentation in ready-to-use laboratory test kits reveals distinct procurement patterns across clinical and non-clinical channels. Product specifications, regulatory clearance tiers, and end-user technical capabilities determine kit format selection and pricing power.
Product Type:
Infectious disease panels dominate domestic hospital procurement in the United States and Germany, while cancer and cardiac marker kits flow through specialized export channels to centralized reference laboratories.
- Infectious Disease:Multiplex respiratory and bloodstream pathogen panels ship in lyophilized configurations for shelf-stable deployment. Demand concentrates in seasonal surveillance programs across German hospital networks and United States integrated delivery networks, driven by recurring bulk tender structures.
- Cancer:Tumor marker assays require cold-chain logistics and specialized handling protocols. Export-led distribution serves centralized oncology reference laboratories in Switzerland and Japan, constrained by EMA and PMDA batch-release documentation requirements.
- Cardiac Markers:Troponin and natriuretic peptide rapid tests serve emergency department triage protocols.
- Drug Testing:Workplace and forensic toxicology panels target third-party laboratory services with chain-of-custody documentation.
Infectious disease commands the established base. The steepest expansion runs through cancer biomarker assays as companion diagnostic linkages deepen.
End User:
Cost tier differentiation separates institutional procurement with volume discount structures from premium direct-to-consumer channels where price sensitivity collapses.
- Hospitals:Acute care facilities mandate FDA-cleared or CE-IVD kits with embedded RFID lot tracking for LIS integration. Procurement flows through centralized hospital system offices in Texas and Florida health networks, compressing vendor diversity around dual-cleared platforms.
- Diagnostics Labs:Commercial reference laboratories prioritize throughput economics and analyzer compatibility with 10-15 year-old installed equipment bases. Demand clusters in United States and China where national reimbursement frameworks favor standardized testing menus.
- Home Users:Over-the-counter fertility and sexual health assays bypass institutional discount structures entirely.
- Research Institutions:Investigational-use-only kits operate outside clinical diagnostic regulatory pathways.
Diagnostics labs command the established base. The steepest expansion runs through home users as direct-to-consumer channels capture premium pricing on fertility tracking assays.
Application:
Volume concentration in clinical diagnostics contrasts with fragmented, specification-diverse demand across environmental, food safety, and veterinary channels.
- Clinical Diagnostics:Patient specimen testing under ISO 15189-accredited laboratory workflows represents the core revenue pool. Demand anchors in United States hospital networks and German centralized laboratory systems where reimbursement codes lock in standardized kit procurement.
- Environmental Testing:Water and soil contaminant assays serve regulatory compliance monitoring. Export concentration targets industrial laboratory services in China under MEE environmental monitoring mandates.
- Food Safety:Pathogen detection kits align with FSMA and EU hygiene package requirements.
- Veterinary Testing:Companion animal and livestock diagnostic panels follow separate regulatory pathways.
Clinical diagnostics commands the established base. The steepest expansion runs through food safety as supply chain traceability mandates tighten.
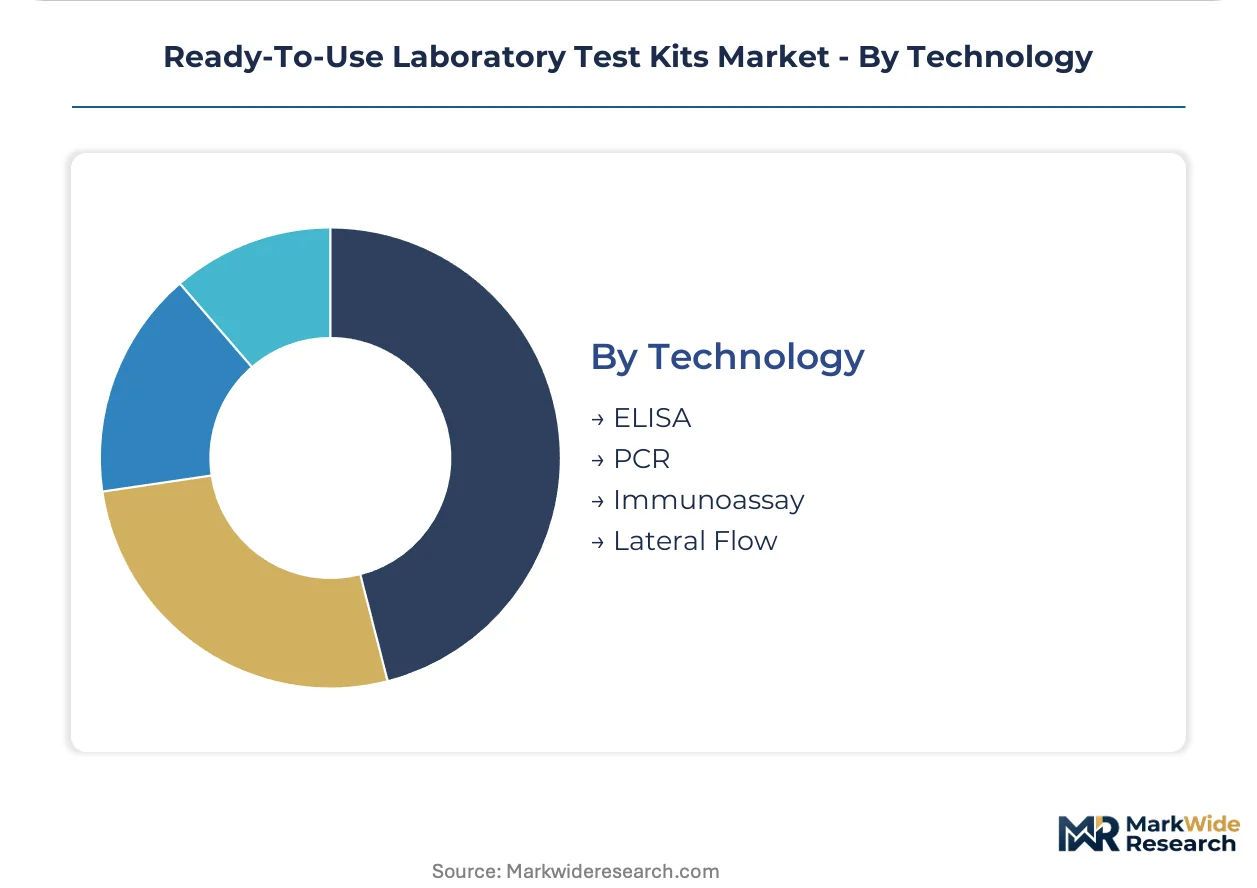
Technology:
Maturity gradients separate established immunoassay platforms from emerging molecular and point-of-care formats competing on turnaround time.
- Immunoassay:Automated chemiluminescent and enzyme-linked formats anchor high-throughput clinical laboratory workflows. Demand concentrates in United States and Germany where installed analyzer bases create switching-cost barriers for alternative technologies.
- Lateral Flow:Visual-read platforms eliminate equipment dependency for point-of-care deployment. Adoption accelerates in United States urgent care clinics and retail health settings, displacing central laboratory volume for routine infectious disease screening.
- PCR:Nucleic acid amplification requires thermal cycler infrastructure and trained operator protocols.
- ELISA:Plate-based enzyme immunoassays retain cost advantages for batch processing in research settings.
Immunoassay commands the established base. Lateral flow is expanding most quickly as point-of-care sites adopt visual-read platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows concentrate from German and United States manufacturing clusters toward hospital networks in emerging markets, while China increasingly supplies domestic demand through localized production under CDSCO registration pathways.
United States
Integrated delivery networks in Texas and Florida control procurement for over sixty percent of hospital beds within their states, consolidating vendor panels around dual FDA-EMA cleared platforms. FDA enforces premarket notification pathways under 21 CFR 809 for moderate-complexity kits. Boston and San Diego clusters host molecular diagnostic kit development operations serving national reference laboratory contracts.
Germany
Centralized hospital networks generate recurring bulk orders for multiplex respiratory pathogen panels through seasonal surveillance tenders. EMA's In Vitro Diagnostic Regulation mandates notified-body conformity assessment for CE marking, with enforcement compressing legacy certificate reliance by May 2026. The Rhine-Ruhr and Munich metropolitan regions concentrate immunoassay manufacturing and distribution logistics.
China
Domestic hospital procurement favors standardized testing menus under national health reimbursement frameworks. NMPA registration requirements and MEE environmental monitoring mandates shape kit specifications for clinical and industrial channels. The Yangtze River Delta and Pearl River Delta clusters host manufacturing operations targeting both domestic tenders and export markets.
India
CDSCO's streamlined medical device registration pathway and PLI scheme incentives attract kit manufacturers to establish localized production. Domestic hospital network tenders drive demand for shelf-stable infectious disease panels. Maharashtra and Gujarat industrial corridors concentrate contract manufacturing operations serving South Asian distribution networks.
Japan
PMDA batch-release documentation requirements constrain import timelines for oncology reference laboratory assays. Centralized laboratory systems anchor demand for automated immunoassay platforms with backward compatibility requirements. The Kanto and Kansai metropolitan areas concentrate clinical diagnostics procurement decision-making.
Ready-To-Use Laboratory Test Kits Market Competitive Landscape
Concentration sits with diversified life science conglomerates and specialized diagnostic manufacturers competing through regulatory clearance breadth and analyzer platform integration. The vendor base stratifies across premium-validated tiers and mid-scale private-label suppliers. Strategic archetypes include backward-integrated reagent manufacturers, distribution-anchored platform specialists, and automation-focused turnaround-time competitors. Dominant competitive moves span sole-source contracting with integrated delivery networks and lyophilized reformatting for cold-chain elimination.
Among diversified conglomerates, Abbott and Thermo Fisher Scientific occupy positions exemplifying regulatory breadth and channel control archetypes. bioMérieux SA represents the automation-specialist tier competing on operational metrics rather than kit pricing alone. These three entities anchor the competitive structure through distinct vectors: Abbott through backward integration into reagent manufacturing, Thermo Fisher Scientific through direct channel contracts with integrated delivery networks, and bioMérieux SA through immunoassay automation specialization.
| Leading Market Players |
|---|
| Abbott |
| Thermo Fisher Scientific, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Danaher Corporation |
| bioMérieux SA |
| DiaSorin S.P.A |
| Quidel Corporation |
| ACON Laboratories, Inc. |
| OraSure Technologies |
| Others |
Value Network & Pricing Analysis
Lyophilized bead-based reagent formats displacing liquid-phase master mixes simultaneously compress cold-chain logistics costs and relocate manufacturing concentration toward centralized United States and German production hubs. This substitution collapses regional distribution center requirements while anchoring premium pricing power with manufacturers controlling shelf-stability engineering capabilities.
Pricing Analysis
Integrated delivery networks anchor a three-tier pricing structure across premium, standard, and economy levels in the United States and Germany. Price differentiation rests on dual FDA-EMA clearance status and embedded RFID lot tracking for laboratory information system integration. Cost compression in standard-tier infectious disease panels is intensifying because group purchasing organizations consolidate procurement across 50-400 affiliated laboratories. Diagnostics laboratories exhibit highest price sensitivity due to throughput economics pressure, while home users demonstrate least sensitivity on direct-to-consumer fertility assays.
Supply Chain Analysis
Strategic stockpiling of lyophilized reagents dominates inventory strategy as manufacturers buffer against polymerase enzyme supply volatility. Manufacturing concentration centers on the United States, Germany, and China, with the Yangtze River Delta and Rhine-Ruhr metropolitan regions anchoring production. Reverse transcriptase and DNA polymerase enzymes draw from three specialty chemical suppliers, creating single-source vulnerability for molecular diagnostic kit producers. Distribution runs through direct channel contracts with integrated delivery networks and group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of trained ISO 15189 auditors and notified-body assessment capacity constrains supplier qualification velocity, creating competitive moats for manufacturers with established regulatory documentation archives.
For Market Incumbents: Shield market position by accelerating backward integration into reagent manufacturing to capture margin control from polymerase suppliers, while expanding lyophilized format portfolios to exploit cold-chain elimination economics against liquid-phase competitors. For New Entrants and Emerging Players: Differentiate on turnaround-time guarantees for immunoassay automation rather than kit pricing alone, targeting India's CDSCO-registered domestic hospital tenders and at-home fertility tracking channels where institutional discount structures do not apply. For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors manufacturers with completed IVDR conformity assessments and dual-cleared platform portfolios. Long-term viability across the five-to-ten year window hinges on RFID-enabled digital connectivity and automated result transmission capabilities. Acquisition targets should demonstrate established relationships with Texas and Florida integrated delivery networks. The signal to watch is FDA guidance evolution on interoperability mandates for in vitro diagnostic data systems.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Conformity Assessment Completion | EMA's May 2026 enforcement deadline mandates notified-body certification for EU market retention. |
| Lyophilized Reagent Format Expansion | Shelf-stable configurations eliminate cold-chain dependency and reduce shipping costs for German and United States distribution. |
| Integrated Delivery Network Partnership | Sole-source contracting with Texas and Florida health systems locks in multi-year procurement commitments. |
| RFID Lot Tracking Integration | FDA interoperability guidance creates demand for automated result transmission to laboratory information systems. |
| India Localized Production Establishment | CDSCO streamlined registration and PLI scheme incentives attract manufacturing for South Asian hospital tenders. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EMA IVDR technical documentation filings, and hospital procurement contract records preceded structured interviews with clinical laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists at kit manufacturers. Secondary validation drew from ISO 13485 quality management system audits, notified-body conformity assessment timelines, and integrated delivery network annual supply chain disclosures. Bottom-up segmentation sizing and top-down market triangulation reconciled variance across primary and secondary sources.
Variance decomposition across product type, end user, application, technology, and geographic regulatory cluster dimensions shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and value-per-test economics across the projection horizon. Modeled inputs incorporated seasonal respiratory panel demand cycles in Germany, reimbursement code stability under United States Medicare frameworks, and CDSCO registration pathway velocity in India.
Material uncertainties — polymerase supply concentration, notified-body assessment queue lengths, and lateral flow substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement timelines and procurement consolidation velocity. Revision becomes warranted when IVDR transition delays or group purchasing organization contract renegotiations cross thresholds that alter manufacturer pricing power.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Test Strips Market
Testing Services
Global Metabolic Testing Market
Testing Services
Tablet Hardness Testers Market
Testing Services
Lab Screening Test Kit Market
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Americas Sterility Testing Market
Testing Services
Diagnostic Shipper Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Addison Disease Testing Market
Testing Services
Global Cannabis Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Global Mosquito Borne Infections Testing Market