
 Precision Medicine Market | 2026-2036
Precision Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Medicine Market Analysis
Next-generation sequencing reagents are expanding their share of per-patient testing economics as laboratories shift from single-gene assays to comprehensive genomic profiling panels. Thermo Fisher Scientific anchors its position through backward integration into reagent manufacturing and instrument platforms that lock in recurring consumable revenue. Illumina dominates high-throughput sequencing installed base and sustains pricing power through proprietary flow cell chemistry. QIAGEN specializes in sample preparation workflows that compete on automation compatibility and regulatory pre-validation for clinical labs.
Precision medicine encompasses therapies and diagnostics tailored to individual genetic, biomarker, or molecular profiles rather than population-average disease definitions. The field relies on nucleic acid extraction protocols achieving picogram sensitivity, bioinformatics pipelines mapping variants against curated databases, and companion assays demonstrating analytical validity for specific drug indications. Cancer Treatment leads application-level revenue as pharmaceutical companies leverage biomarker stratification to rescue failed oncology programs and secure accelerated regulatory review. Genomic Data Analysis represents the fastest-expanding product category as health systems confront terabyte-scale sequencing outputs and demand interpretive software with clinical decision support integration. Companion Diagnostics maintains mature margin pools where FDA co-approval requirements create high switching costs for therapy-test pairings.
FDA's in vitro diagnostic guidance and EMA's companion diagnostic regulation shape development timelines by mandating prospective biomarker validation before pivotal trials. The EU AI Act and GDPR impose additional compliance layers on machine learning algorithms processing genomic data for treatment recommendations. Stakeholders must monitor evolving reimbursement frameworks for multi-cancer early detection tests as Medicare coverage determinations will signal whether liquid biopsy platforms achieve routine screening economics or remain confined to recurrence monitoring applications.
Market Dynamics
The transition from single-gene assays to comprehensive genomic profiling panels is compressing per-test economics while expanding clinical utility, forcing laboratories to reconfigure workflows around higher-throughput platforms and integrated bioinformatics pipelines.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's streamlined review for biomarker-guided therapies reduces development timelines and expands patient access to targeted oncology treatments.
- Medicare Coverage Expansion:United States reimbursement decisions for companion diagnostics increasingly validate commercial viability for molecular test developers entering clinical markets.
- Comprehensive Genomic Profiling:Next-generation sequencing panels are replacing fragmented single-gene testing, consolidating laboratory spend and improving diagnostic yield per specimen.
Market Restraints
- Reagent Supply Concentration:Proprietary flow cell chemistry and consumable lock-in strategies by dominant sequencing platform vendors create switching costs for clinical laboratories.
- GDPR Compliance Burden:The EU AI Act and data protection frameworks impose additional validation layers on machine learning algorithms processing genomic data for treatment recommendations.
- Bioinformatics Bottleneck:Terabyte-scale sequencing outputs exceed interpretive capacity at many health systems, delaying clinical decision support integration.
Strategic Opportunities
- Multi-Cancer Early Detection:Liquid biopsy platforms targeting asymptomatic screening populations await Medicare coverage determinations that would unlock routine testing economics beyond recurrence monitoring.
- Sample Preparation Automation:Pre-validated extraction workflows compatible with high-throughput clinical operations address laboratory staffing constraints and reduce turnaround variability.
- EMA Companion Diagnostic Regulation:Harmonized European approval pathways for therapy-test pairings create consolidated addressable markets for diagnostic developers with regulatory pre-validation capabilities.
Industry Challenges
- Variant Interpretation Workforce Gap:Clinical laboratories face acute shortages of molecular pathologists and genomic counselors capable of translating complex profiling results into actionable treatment recommendations.
- Legacy EHR Integration:Health systems struggle to embed genomic decision support into existing electronic health record architectures without disrupting physician workflow efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Medicine Market |
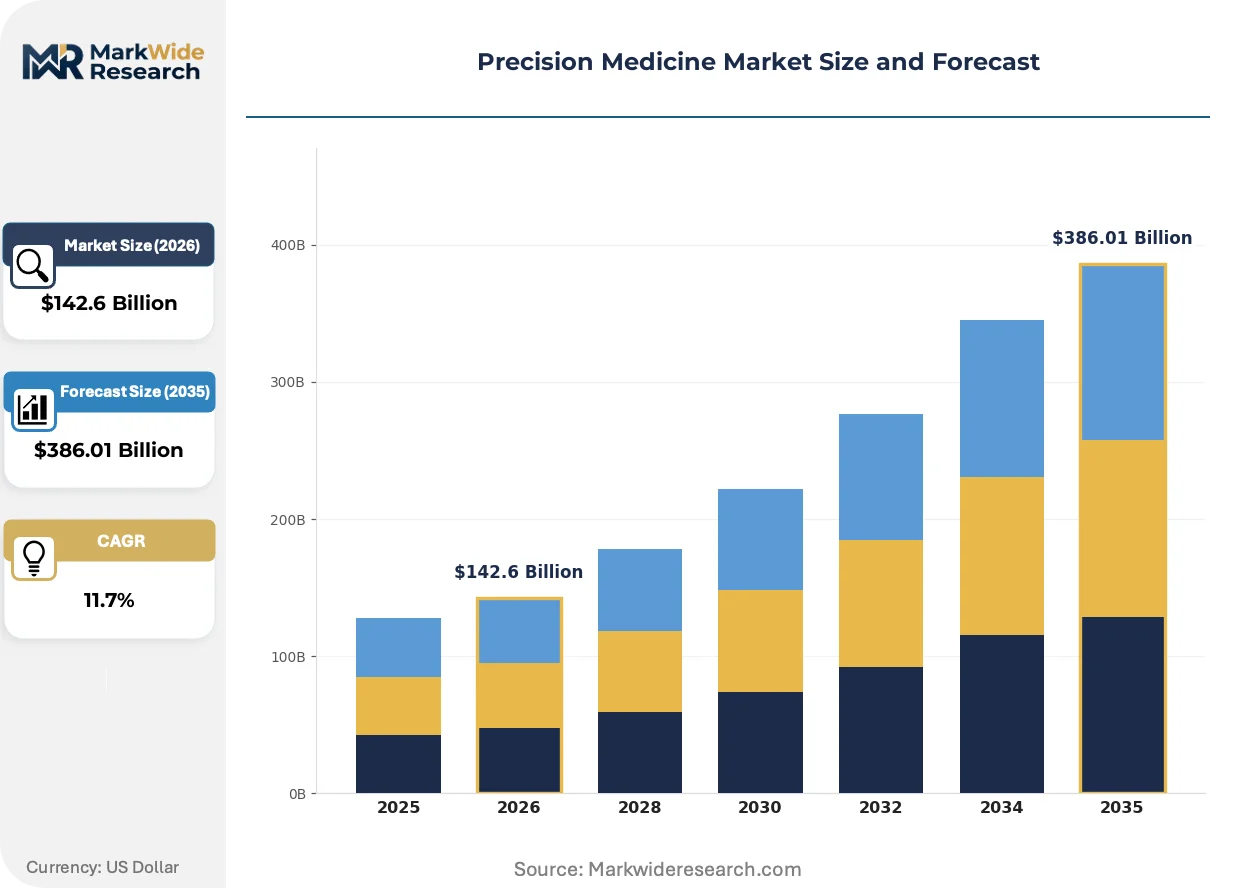
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $386.01 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Companion Diagnostics, Targeted Therapies, Genomic Data Analysis, Biomarkers End User: Pharmaceutical Companies, Healthcare Providers, Research Institutions, Diagnostic Labs Technology: NGS, Bioinformatics, CRM Systems, Machine Learning Application: Cancer Treatment, Genetic Testing, Rare Diseases, Metabolic Disorders |
| Companies Covered | F. Hoffmann-La Roche Ltd, Illumina, Inc., Thermo Fisher Scientific Inc., Novartis AG, Agilent Technologies, Inc., QIAGEN N.V., Pfizer Inc., Merck & Co., Inc., Guardant Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Medicine Market Emerging Trajectories
Cloud-native bioinformatics architectures are displacing on-premise computational infrastructure, enabling health systems to scale genomic analysis without proportional capital investment in sequencing hardware and data storage systems.
Portable sequencing devices are decentralizing molecular diagnostics from centralized academic medical centers toward community oncology practices and point-of-care settings. Regional hospital networks in the United States and district hospitals in India are adopting nanopore-based platforms for rapid turnaround on urgent cases. This technology is compressing the geographic distance between specimen collection and diagnostic result, reducing cold-chain logistics costs and enabling same-day treatment decisions.
The EU AI Act imposes risk-classification requirements on algorithms generating treatment recommendations from genomic data, mandating human oversight and traceability documentation. Pharmaceutical companies developing companion diagnostic algorithms must now validate explainability features alongside analytical performance. Oncology departments at European academic centers are responding by establishing dedicated governance committees for artificial intelligence deployment in molecular tumor boards.
Oncology practices are consolidating molecular testing procurement through integrated delivery networks and group purchasing organizations, displacing hospital-specific laboratory contracts. These buying collectives negotiate volume-based pricing with national reference laboratories and demand standardized reporting formats across their member institutions. The concentration is most visible in United States metropolitan markets where independent oncology groups have merged into platform-scale networks with centralized pathology operations.
Precision Medicine Market Segmentation
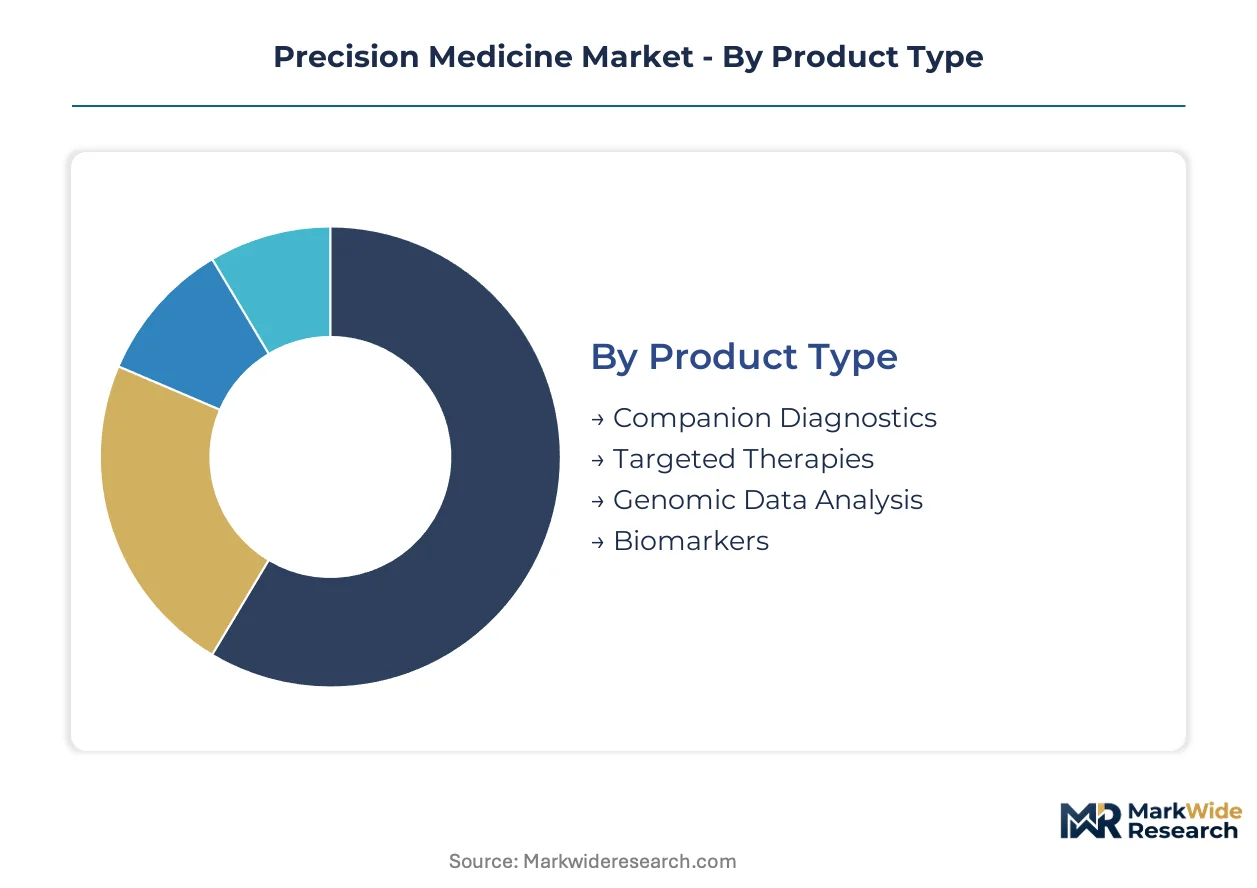
Molecular stratification demands distinct regulatory pathways across product categories, with FDA co-approval requirements and EMA companion diagnostic frameworks creating tiered compliance burdens that reshape competitive positioning. Segmentation reveals where capital concentrates versus where capability gaps persist.
Product Type:
Companion diagnostics carry the heaviest certification load, requiring synchronized FDA PMA or de novo pathways alongside therapeutic approvals, while genomic data analysis tools navigate evolving EU AI Act risk classifications for clinical decision support algorithms.
- Companion Diagnostics:Analytically validated assays demonstrating clinical utility for specific drug indications, locked into therapy-test pairings through FDA co-approval mandates. Academic medical centers in the United States drive procurement volume as Medicare coverage decisions validate commercial viability for test developers.
- Genomic Data Analysis:Cloud-native bioinformatics pipelines processing terabyte-scale sequencing outputs into actionable variant interpretations. Health systems in Germany and France demand explainability documentation under EU AI Act oversight requirements, compressing vendor selection timelines.
- Targeted Therapies:Biomarker-guided pharmaceuticals securing accelerated FDA review through biomarker stratification.
- Biomarkers:Molecular signatures qualifying patients for selective therapeutic mechanisms.
Companion diagnostics sits at the top of the volume ranking, with genomic data analysis climbing the fastest.
End User:
Customer archetypes diverge sharply on procurement sophistication, with integrated delivery networks negotiating enterprise pricing while research institutions prioritize customization over standardization.
- Pharmaceutical Companies:Sponsors of therapy-test co-development programs bearing full biomarker validation costs through pivotal trials. Roche and AstraZeneca operations in Switzerland and the United Kingdom concentrate demand for regulatory pre-validated companion diagnostic partnerships.
- Healthcare Providers:Oncology departments embedding molecular profiling into routine care pathways. United States metropolitan hospital networks consolidate testing procurement through group purchasing organizations, displacing site-specific laboratory contracts.
- Research Institutions:Academic centers generating real-world evidence for biomarker discovery.
- Diagnostic Labs:Commercial reference laboratories scaling high-throughput operations.
Healthcare providers capture the largest addressable spend, with pharmaceutical companies expanding fastest as rescue strategies for failed oncology programs multiply.
Technology:
Platform selection locks laboratories into recurring consumable revenue streams, with chemistry-proprietary ecosystems creating switching costs that concentrate supply-side power.
- NGS:Next-generation sequencing platforms shifting from single-gene assays to comprehensive genomic profiling panels. Thermo Fisher Scientific and Illumina installed bases in Massachusetts and California anchor per-patient testing economics through reagent backward integration.
- Machine Learning:Algorithms generating treatment recommendations from genomic variant databases. EU AI Act risk-classification requirements in France and Germany mandate human oversight and traceability documentation, extending validation timelines.
- Bioinformatics:Computational pipelines mapping variants against curated clinical databases.
- CRM Systems:Patient data infrastructure coordinating precision medicine workflows.
NGS dominates current installed capacity, with machine learning gaining share fastest as regulatory frameworks crystallize.
Application:
Disease area selection determines reimbursement feasibility, with oncology securing coverage determinations that metabolic and rare disease indications have yet to replicate.
- Cancer Treatment:Molecular tumor profiling guiding targeted therapy selection across solid and hematologic malignancies. FDA accelerated approval pathways compress development timelines for biomarker-stratified indications, concentrating investment in lung and colorectal malignancies.
- Genetic Testing:Germline variant analysis for hereditary risk assessment and carrier screening. United States preventive services coverage under ACA mandates drives volume in prenatal and oncology settings.
- Rare Diseases:Exome and genome sequencing for diagnostic odyssey resolution.
- Metabolic Disorders:Pharmacogenomic guidance for enzyme-deficiency management.
Cancer treatment commands the revenue concentration, with rare diseases expanding most quickly as diagnostic odyssey economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts anchors precision medicine commercialization through the concentration of sequencing platform developers and academic medical centers. The United States, Germany, China, Japan, and Switzerland represent the primary demand centers where regulatory frameworks and reimbursement policies determine market access.
United States
Medicare coverage determinations for companion diagnostics validate commercial viability for molecular test developers entering clinical markets. FDA accelerated approval pathways compress development timelines for biomarker-guided therapies. The Boston-Cambridge corridor concentrates sequencing platform innovation alongside academic medical centers integrating molecular profiling into routine oncology care.
Germany
Healthcare providers in Bavaria and North Rhine-Westphalia demand explainability documentation for clinical decision support algorithms under EU AI Act oversight requirements. EMA companion diagnostic regulation shapes synchronized therapy-test approval timelines. The Heidelberg-Mannheim biotech cluster anchors genomic data analysis vendor selection as health systems confront terabyte-scale sequencing outputs.
China
NMPA regulatory pathways for in vitro diagnostics are expanding market access for domestic sequencing platform manufacturers. The country's national pharmaceutical regulator mandates analytical validity demonstrations for companion assays paired with targeted therapies. The Yangtze River Delta biopharma corridor concentrates liquid biopsy platform development for multi-cancer early detection applications.
Japan
PMDA approval frameworks for biomarker-stratified oncology therapies align with global regulatory standards while maintaining distinct clinical trial requirements. METI industrial policy supports genomic medicine infrastructure investments. The Tokyo-Osaka corridor concentrates pharmaceutical company demand for regulatory pre-validated companion diagnostic partnerships.
Switzerland
Swissmedic oversight of therapy-test co-development programs attracts pharmaceutical sponsors seeking harmonized European approval pathways. Roche operations in Basel concentrate demand for backward-integrated reagent manufacturing and instrument platforms. The Basel-Zurich corridor anchors precision medicine commercialization strategy for global pharmaceutical companies.
Precision Medicine Market Vendor Landscape
Global majors compete with regional champions across sequencing platform installed base and reagent supply concentration. The vendor base organizes around chemistry-proprietary ecosystems that lock clinical laboratories into recurring consumable revenue streams. Three archetypes dominate: integrated platform-reagent developers, specialized sample preparation workflow providers, and liquid biopsy test developers. Competitive positioning depends on backward integration into consumable manufacturing and regulatory pre-validation capabilities for clinical lab automation.
Among Swiss and American pharmaceutical and diagnostics conglomerates, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific Inc. occupy positions anchoring reagent backward integration and instrument platform ecosystems. Illumina, Inc. represents the high-throughput sequencing installed base archetype, sustaining pricing power through proprietary flow cell chemistry. These three companies exemplify the platform-lock strategy that concentrates supply-side power and creates switching costs for clinical laboratories.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| Novartis AG |
| Agilent Technologies, Inc. |
| QIAGEN N.V. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Guardant Health |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks consolidating molecular testing procurement through group purchasing organizations are forcing reagent suppliers toward volume-based contract structures that compress per-test margins while locking in multi-year consumable commitments.
Pricing Analysis
Input-cost pass-through from proprietary flow cell chemistry and nucleic acid extraction kits shapes per-patient testing economics, with reagent backward integration allowing platform vendors to capture recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates FDA PMA-validated companion diagnostics from research-use-only panels and laboratory-developed tests. Pricing pressure stems from Medicare coverage determinations demanding analytical validity demonstrations that extend validation timelines and raise fixed costs. Hospital networks exhibit highest price sensitivity, while pharmaceutical sponsors in therapy-test co-development programs absorb premium pricing for regulatory pre-validation.
Supply Chain Analysis
Domestic-content mandates under China's NMPA regulatory pathways and India's PLI scheme for medical devices are reshaping sourcing patterns for sequencing instruments and diagnostic consumables. Manufacturing concentrates in the United States, China, and Switzerland, with reagent production anchored in Massachusetts and Basel clusters. Raw material dependencies include semiconductor components for sequencing hardware, fluorophores for detection chemistry, and synthetic oligonucleotides for panel content. Single-source vulnerability from Illumina's proprietary flow cell ecosystem creates switching costs for clinical laboratories. Distribution runs through national reference laboratories and integrated delivery networks consolidating procurement across metropolitan hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in the United States-Germany corridor, where FDA accelerated approval pathways compress development timelines relative to EMA's extended validation requirements, lowering capital-at-risk for biomarker-guided therapy programs.
For Market Incumbents: Lock in reagent backward integration and instrument platform ecosystems to defend against nanopore-based portable sequencing entrants disrupting centralized laboratory economics. Prioritize regulatory pre-validation investments for EU AI Act compliance on genomic data analysis algorithms, as explainability documentation requirements extend vendor selection timelines and create switching costs. Expand high-throughput automation partnerships with academic medical centers to secure multi-year consumable contracts before procurement consolidation accelerates.
For New Entrants and Emerging Players: Cloud-native bioinformatics architectures offer a technology-first wedge into health systems confronting terabyte-scale sequencing outputs and workforce gaps in variant interpretation. Target community oncology practices and district hospitals in India adopting point-of-care nanopore platforms for rapid turnaround applications underserved by centralized reference laboratories. Pursue sample preparation automation partnerships emphasizing regulatory pre-validation and compatibility with existing high-throughput clinical operations.
For Investors and Strategic Acquirers: Asymmetric upside sits with genomic data analysis vendors possessing EU AI Act compliance capabilities and clinical decision support integration expertise, as health systems demand explainable machine learning pipelines. Long-term viability hinges on recurring revenue models anchored in cloud-based subscription architectures rather than transactional per-test licensing. Monitor Medicare coverage determinations for multi-cancer early detection tests as the inflection signal for liquid biopsy platform economics transitioning from recurrence monitoring to routine screening applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Validation Investment | EMA companion diagnostic frameworks and FDA PMA pathways demand synchronized therapy-test validation timelines. |
| Cloud-Native Bioinformatics Development | Health systems in Germany and France require EU AI Act-compliant algorithms with traceability documentation. |
| Sample Preparation Automation | Laboratory staffing constraints drive demand for pre-validated extraction workflows compatible with high-throughput operations. |
| Liquid Biopsy Platform Expansion | Medicare coverage determinations will signal whether multi-cancer early detection achieves routine screening economics. |
| Integrated Delivery Network Partnership | United States metropolitan hospital networks consolidate procurement through group purchasing organizations displacing site-specific contracts. |
Methodological Framework
Multiple input streams — primary interviews with molecular pathologists, regulatory affairs leads at diagnostic developers, hospital procurement managers, and pharmaceutical biomarker strategists — were reconciled against FDA 510(k) and PMA filings, EMA companion diagnostic submissions, CMS Medicare coverage determinations, and ClinicalTrials.gov biomarker-stratified trial records. Bottom-up demand modeling across oncology departments and reference laboratories was cross-validated through top-down expenditure analysis from health system financial disclosures and pharmaceutical R&D pipeline databases.
Historical adoption curves for NGS platforms and companion diagnostics were cross-referenced against expert panel inputs on reimbursement trajectory and regulatory timeline evolution across the analysis window. Segmentation modeling incorporated product type, end-user archetype, technology platform, and application area dimensions. CAGRs were derived from fitted growth curves anchored in Medicare coverage expansion assumptions and FDA accelerated approval pathway utilization rates for biomarker-guided therapies.
The model holds under stable reimbursement frameworks and continued FDA-EMA regulatory harmonization; deviation in Medicare coverage determinations for multi-cancer early detection or EU AI Act enforcement intensity would shift adoption timelines and vendor competitive positioning. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
PDX Models Market
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
Asia-Pacific Computer-Aided Drug Discovery Market
Medical Research
Forensic Medicine Market
Medical Research
Global Mice Model Market
Medical Research
Cancer Mouse Models Market
Medical Research
Epigenomics Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
Antibody-Mediated Rejection Prevention Market
Medical Research
Mice Model Technologies Market
Medical Research
FFPE Tissue Samples Market
Medical Research
North America Biobanks Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Global in Vitro Lung Model Market