
 Global GI Stool Testing Market | 2026-2036
Global GI Stool Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global GI Stool Testing Market Foresight
Buyer concentration among clinical laboratories is shifting as hospital networks consolidate reference lab contracts while independent diagnostic centers fragment into specialized GI service lines. Exact Sciences Corporation leverages its molecular diagnostics platform to anchor the colorectal cancer screening segment. bioMérieux sustains competitive positioning through immunoassay breadth and European regulatory sophistication. Thermo Fisher Scientific competes on manufacturing scale, supplying reagents and instrumentation across multiple stool testing modalities.
GI stool testing encompasses the laboratory analysis of fecal specimens to detect pathogens, occult blood, inflammatory markers, DNA mutations, and microbiome alterations, typically processed through immunoassay, molecular, microscopic, or chemical methods with turnaround times ranging from hours to several days depending on test complexity. Its primary commercial purpose is to enable non-invasive screening and diagnosis of gastrointestinal diseases while reducing reliance on endoscopic procedures. Molecular diagnostics commands the fastest expansion trajectory driven by multi-target stool DNA technology and polymerase chain reaction-based pathogen panels. Immunoassays occupy the largest installed base due to lower capital requirements and established reimbursement codes. Pathogen detection applications concentrate margin pools where acute infectious disease protocols mandate rapid turnaround.
FDA premarket review pathways, the EU In Vitro Diagnostic Regulation, and Japan's PMDA quality management standards collectively determine market access timelines and clinical evidence requirements for stool-based assays. These frameworks elevate barriers for novel biomarker introductions while accelerating substitution of older guaiac-based methods with fecal immunochemical and molecular alternatives. Stakeholders must monitor evolving reimbursement decisions from Medicare, statutory health insurers in Germany, and Japan's Ministry of Health as these determine adoption velocity for premium-priced molecular screening platforms.
Market Dynamics
Multi-target stool DNA technology is fragmenting the colorectal cancer screening hierarchy, compressing reimbursement timelines and forcing immunoassay incumbents to defend installed base through test-menu bundling.
Growth Catalysts
- FDA premarket review modernization:Streamlined 510(k) pathways for novel biomarker panels accelerate commercialization timelines for molecular diagnostic developers.
- Germany's statutory health insurance framework:Preventive screening mandates for adults over 50 sustain fecal immunochemical test volumes through primary care networks.
- Polymerase chain reaction pathogen detection:Hospital laboratory consolidation favors automated PCR platforms that replace culture-based infectious disease workflows.
Market Restraints
- Reagent supply concentration:Thermo Fisher Scientific and bioMérieux control critical nucleic acid extraction chemistries, creating single-source vulnerability for mid-tier laboratories.
- EU In Vitro Diagnostic Regulation compliance costs:Performance study requirements and notified body bottlenecks extend time-to-market by 18-24 months for novel assays.
- Colonoscopy substitution ceiling:Positive stool DNA tests still require endoscopic confirmation, limiting complete procedural displacement in high-risk patient stratification.
Strategic Opportunities
- Japan's aging demographic tailwind:Ministry of Health reimbursement alignment for non-invasive screening creates expansion space for premium molecular platforms in Tokyo-Osaka corridor laboratories.
- Microbiome therapeutic monitoring:Fecal calprotectin and zonulin biomarker integration with biologic therapy management opens adjacent revenue streams in inflammatory bowel disease centers.
- Direct-to-consumer channel emergence:Telehealth-integrated sample collection kits bypass traditional clinical laboratory procurement, capturing wellness-oriented screening demand.
Industry Challenges
- Molecular diagnostics talent scarcity:Clinical laboratories compete for bioinformaticians capable of interpreting multi-analyte stool DNA reports, compressing operational margins through wage inflation.
- Legacy immunoassay infrastructure lock-in:Capital equipment depreciation schedules and reagent rental contracts delay PCR platform transitions in resource-constrained health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global GI Stool Testing Market |
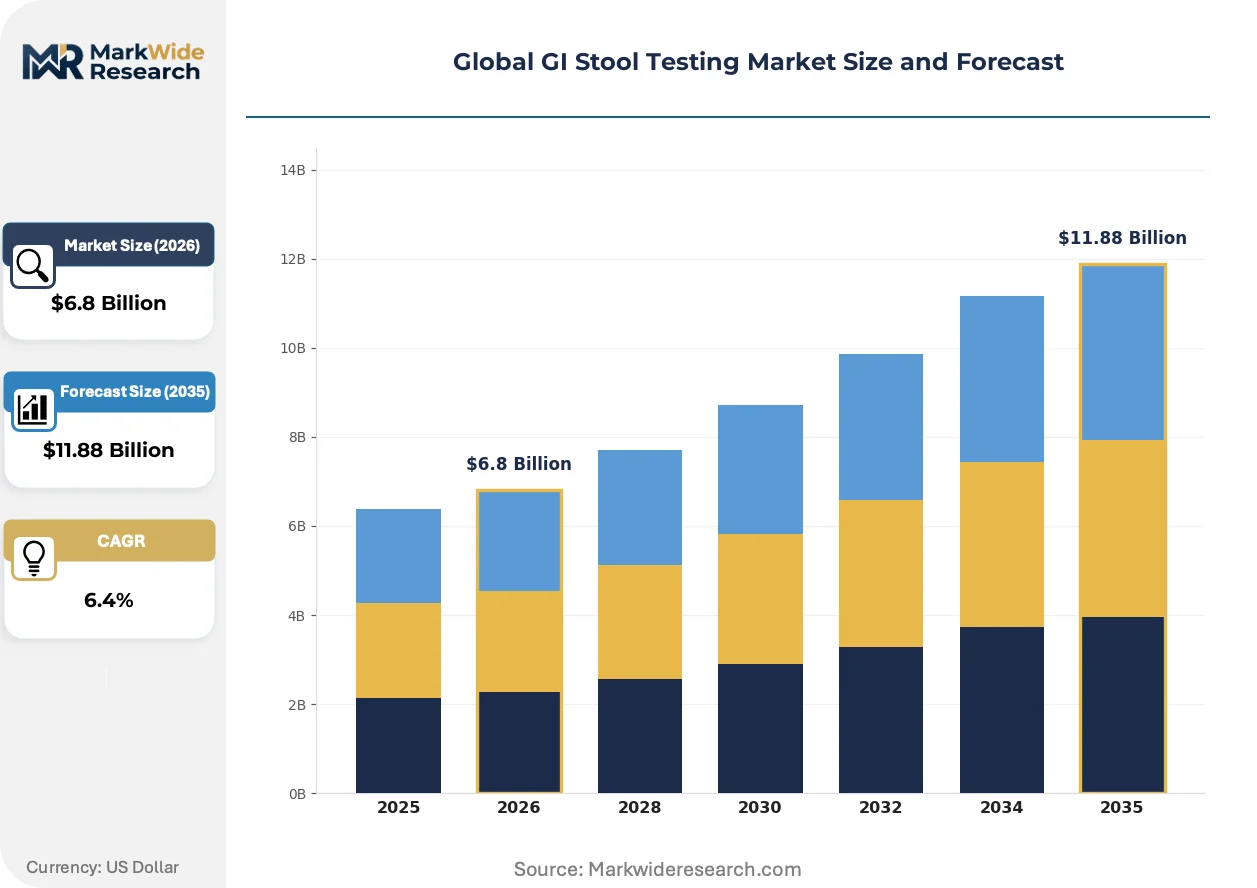
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Molecular Diagnostics, Microscopy, Chemical Tests Application: Pathogen Detection, Digestive Disorder Diagnosis, Colorectal Cancer Screening, Nutrient Malabsorption Analysis End User: Clinical Laboratories, Research Institutes, Diagnostic Centers, Academic Hospitals Distribution Channel: Hospital Pharmacies, Online Retailers, Direct Sales, Medical Distributors |
| Companies Covered | Abbott Laboratories, Exact Sciences Corporation, bioMérieux, Thermo Fisher Scientific, Becton Dickinson and Company, Roche Diagnostics, QuidelOrtho Corporation, Danaher, Genova Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global GI Stool Testing Market Shifts & Advancements
Stool testing architecture is bifurcating between centralized high-complexity molecular hubs and distributed point-of-care immunoassay nodes, with artificial intelligence interpretation layers threading between both tiers.
Next-generation sequencing panels for gastrointestinal pathogens are modularizing laboratory workflow design. Large health system laboratories in the United States adopt configurable assay menus that swap enteric bacterial targets without instrument revalidation. This modularizing capability compresses turnaround time variability and enables surge capacity during seasonal norovirus peaks.
Japan's PMDA quality management standards are tightening post-market surveillance requirements for fecal occult blood devices. Manufacturers must now submit real-world performance data from domestic clinical sites, elevating documentation burdens for European exporters. The immunoassay segment bears disproportionate compliance cost as older guaiac-based products face forced obsolescence.
Hospital network procurement is consolidating reference laboratory contracts into multi-year sole-source agreements with price-volume tiers. Independent diagnostic centers respond by fragmenting into specialized GI service lines with dedicated pathologist oversight. This concentration-fragmentation tension is most visible in Germany, where statutory insurer regional tenders favor consolidated bidders while private pay patients seek boutique turnaround speeds.
Global GI Stool Testing Market Segmentation
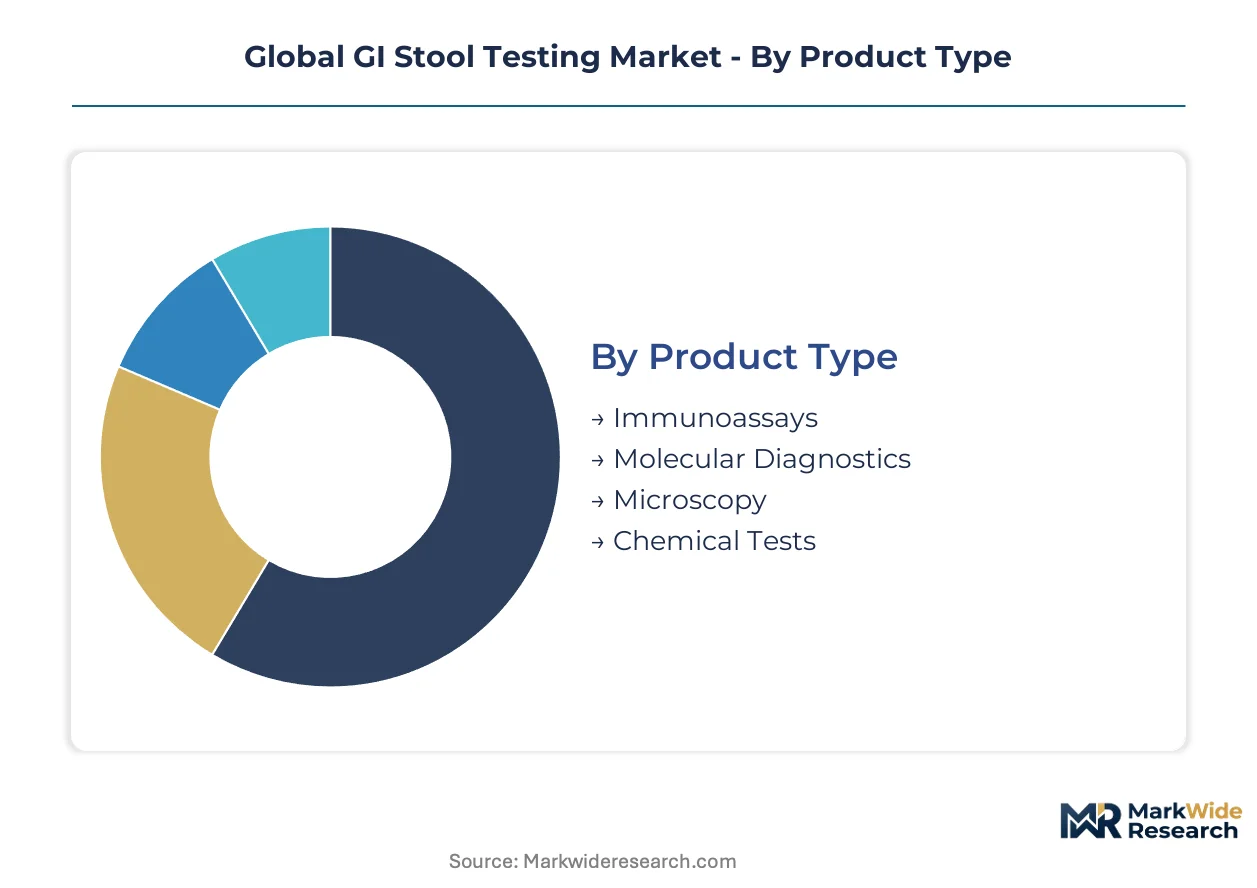
Product architecture, application priority, and procurement channel each create distinct margin profiles and competitive dynamics for stool testing vendors. Understanding these segment boundaries clarifies where technology substitution accelerates versus where installed base defenses hold.
Product Type:
Capital intensity and reimbursement tier determine which modality wins laboratory procurement decisions.
- Molecular Diagnostics:Multi-target stool DNA and PCR-based pathogen panels deliver highest analytical specificity through nucleic acid amplification. Demand clusters in United States reference laboratories where Medicare reimbursement codes for non-invasive colorectal screening have stabilized. FDA premarket review pathways favor well-characterized biomarker signatures, compressing development timelines for established platforms.
- Immunoassays:Fecal immunochemical tests and calprotectin assays rely on antibody-antigen binding with lower per-test costs and minimal batch calibration. Germany's statutory health insurance framework sustains volume through mandated screening protocols for adults over 50, anchoring installed base across primary care networks.
- Microscopy:Direct ova and parasite examination requires trained parasitologists with manual slide preparation. Academic hospitals in Japan maintain competency for tropical disease referral cases.
- Chemical Tests:Guaiac-based occult blood detection represents legacy methodology facing forced obsolescence under EU In Vitro Diagnostic Regulation performance standards.
Volume sits with immunoassays; growth tilts toward molecular diagnostics.
Application:
Clinical urgency and test reimbursement depth separate routine screening from acute diagnostic protocols.
- Colorectal Cancer Screening:Population-scale prevention programs drive the largest addressable patient volume. United States health systems prioritize stool DNA adoption to reduce colonoscopy burden while Japan's Ministry of Health expands reimbursement for molecular platforms in Tokyo-Osaka corridor laboratories.
- Pathogen Detection:Norovirus, C. difficile, and enteric bacterial panels command premium pricing where hospital laboratory consolidation favors automated PCR workflows. Seasonal demand surges require modular assay menus that swap targets without instrument revalidation.
- Digestive Disorder Diagnosis:Fecal calprotectin and inflammatory markers support inflammatory bowel disease therapeutic monitoring. Specialized GI service lines in German independent diagnostic centers capture biologic therapy management revenue.
- Nutrient Malabsorption Analysis:Elastase and fat quantification assays serve pancreatic insufficiency and celiac disease protocols. Research institutes drive method development for microbiome-integrated nutritional assessment.
Revenue concentrates in colorectal screening; pathogen detection claims the steepest expansion trajectory.
End User:
Technical sophistication and purchasing authority shape vendor engagement models across customer types.
- Clinical Laboratories:High-throughput reference sites process tens of thousands of specimens annually with LIS-integrated automation. Hospital network consolidation in the United States compresses vendor lists into multi-year sole-source agreements.
- Diagnostic Centers:Independent facilities fragment into specialized GI service lines with dedicated pathologist oversight and boutique turnaround speeds. Germany's regional insurer tenders favor consolidated bidders while private pay segments seek differentiated service.
- Academic Hospitals:Teaching institutions maintain microscopy competency and rare pathogen reference capability. Japan's PMDA quality management standards tighten post-market surveillance documentation for device performance.
- Research Institutes:Method development and biomarker validation programs drive early-stage assay design. Next-generation sequencing panel modularization originates in these settings before commercial transfer.
Procurement authority sits with clinical laboratories; innovation partnerships tilt toward academic hospitals.
Distribution Channel:
Channel economics and regulatory handling requirements determine route-to-market efficiency.
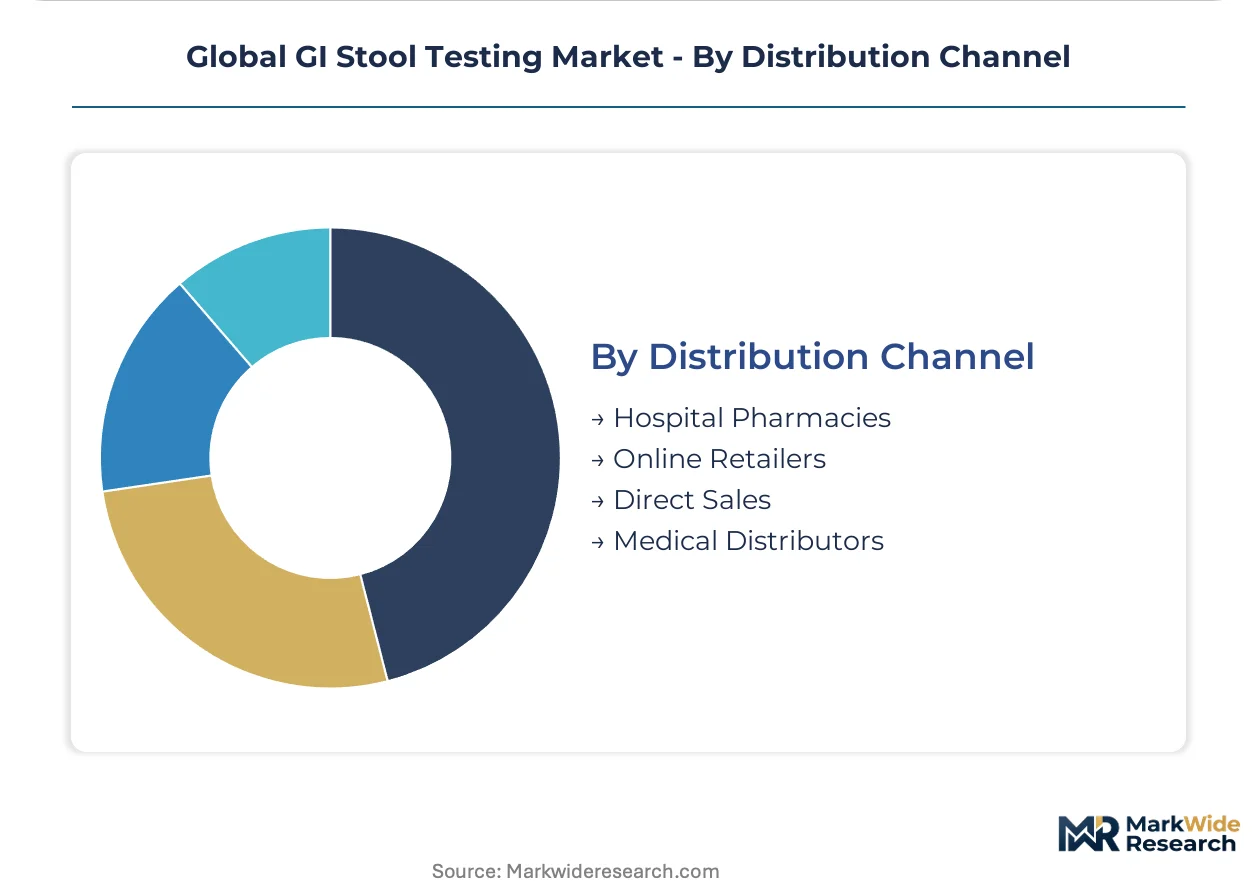
- Medical Distributors:Regional logistics networks manage cold-chain specimen collection kits and reagent replenishment. Thermo Fisher Scientific and bioMérieux leverage distributor relationships for nucleic acid extraction chemistry placement.
- Direct Sales:Molecular platform vendors deploy specialized diagnostic specialists for high-complexity laboratory instrumentation. Capital equipment depreciation schedules and reagent rental contracts lock in multi-year relationships.
- Hospital Pharmacies:Integrated health systems centralize procurement for point-of-care immunoassay consumables. Formulary committees govern test menu standardization across facility networks.
- Online Retailers:Telehealth-integrated sample collection kits bypass traditional laboratory procurement for wellness-oriented screening. Direct-to-consumer channels capture demand outside reimbursement-constrained clinical pathways.
Installed base sits with medical distributors; channel expansion tilts toward online retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for GI stool testing concentrates in three national markets where aging demographics, reimbursement frameworks, and laboratory infrastructure align. The United States, Germany, and Japan collectively shape volume distribution and technology adoption trajectories for molecular and immunoassay platforms.
United States
Medicare reimbursement codes for non-invasive colorectal cancer screening sustain fecal immunochemical test volumes while commercial insurers expand coverage for multi-target stool DNA assays. FDA premarket review modernization through streamlined 510(k) pathways accelerates molecular diagnostic commercialization timelines. Reference laboratory consolidation in the Southeast and Midwest compresses vendor lists into multi-year sole-source agreements with price-volume tiers.
Germany
Statutory health insurance mandates for adults over 50 anchor fecal immunochemical test demand through primary care networks across Baden-Württemberg and Bavaria. The EU In Vitro Diagnostic Regulation elevates performance study requirements for novel biomarker introductions, extending time-to-market by 18-24 months. Independent diagnostic centers in Berlin-Brandenburg fragment into specialized GI service lines with dedicated pathologist oversight and boutique turnaround speeds.
Japan
Ministry of Health reimbursement alignment for non-invasive screening creates expansion space for premium molecular platforms serving Tokyo-Osaka corridor laboratories. PMDA quality management standards tighten post-market surveillance requirements, demanding real-world performance data from domestic clinical sites. Academic hospitals in Kansai maintain microscopy competency for tropical disease referral cases and rare pathogen reference capability.
United Kingdom
National Health Service bowel cancer screening programme procurement favors high-throughput immunoassay automation with LIS-integrated workflows. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment pathways for stool-based devices. London-Southeast laboratory networks consolidate reference testing while regional hubs in the Midlands maintain surge capacity for seasonal norovirus peaks.
China
NMPA medical device registration reforms accelerate review timelines for imported molecular diagnostic platforms serving tier-one hospital laboratories. Dual carbon goals drive domestic manufacturers toward energy-efficient reagent production and reduced cold-chain logistics intensity. Yangtze River Delta health system procurement centralizes into provincial tender consortia favoring automated PCR platform bundles with multi-year service contracts.
Global GI Stool Testing Market Competitive Landscape
United States producers anchor one tier; European specialists hold regulatory sophistication advantages. Market structure bifurcates between consolidated molecular diagnostics platforms and fragmented immunoassay consumables suppliers. Three archetypes dominate: integrated life science conglomerates with manufacturing scale, pure-play molecular diagnostics developers with biomarker depth, and European immunoassay incumbents with reimbursement navigation expertise. Competitive moves center on reagent rental contract lock-in and automated platform transitions displacing legacy infrastructure.
Among United States-based developers, Exact Sciences Corporation occupies a position exemplifying molecular platform anchoring in colorectal screening. Thermo Fisher Scientific represents the scale-driven archetype through nucleic acid extraction chemistry supply across multiple testing modalities. bioMérieux, as a French société anonyme, sits within the European regulatory sophistication tier, leveraging immunoassay breadth and notified body relationship depth to navigate EU IVD compliance requirements.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Exact Sciences Corporation |
| bioMérieux |
| Thermo Fisher Scientific |
| Becton Dickinson and Company |
| Roche Diagnostics |
| QuidelOrtho Corporation |
| Danaher |
| Genova Diagnostics |
| Others |
Supply & Pricing Matrix
EU In Vitro Diagnostic Regulation sustainability documentation requirements gate qualified supply access and premium-tier pricing eligibility for molecular diagnostic platforms. Reagent manufacturers must demonstrate reduced environmental impact across extraction chemistry production to win contracts with consolidated United States hospital networks and German statutory health insurers.
Pricing Analysis
Volume concentrates in fecal immunochemical tests while margins concentrate in multi-target stool DNA platforms. Three-tier pricing structure across premium molecular, standard immunoassay, and economy chemical test levels reflects FDA clearance tier and clinical evidence depth. Price differentiation hinges on Medicare reimbursement alignment and EU notified body certification status. Cost compression in immunoassay tiers is intensifying because German regional tenders favor consolidated bidders with scale economies. Price sensitivity peaks among independent diagnostic centers in Berlin-Brandenburg; least sensitivity sits with United States reference laboratories capturing colonoscopy avoidance value.
Supply Chain Analysis
Bioinformatician workforce scarcity in Massachusetts and California constrains nucleic acid extraction chemistry manufacturing expansion. Critical reagent supply concentrates in the United States, France, and Japan. Production draws from specialized polymerase enzymes, monoclonal antibody stocks, and stabilized nucleic acid transport media. Single-source vulnerability pervades mid-tier laboratory procurement where Thermo Fisher Scientific and bioMérieux control extraction chemistry formulations. Distribution runs through medical distributor networks managing cold-chain specimen collection kit logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity bottlenecks under EU In Vitro Diagnostic Regulation extend molecular assay approval timelines, sustaining premium pricing for cleared platforms. Supply constraints in qualified manufacturing prop test kit valuations across the analysis window.
For Market Incumbents: Anticipate PCR platform substitution waves by bundling immunoassay test menus with automated molecular instrumentation. Exact Sciences Corporation's multi-target stool DNA anchoring threatens fecal immunochemical installed base; defend through reagent rental contract lock-in and LIS-integrated workflow embedding. Prioritize backward integration into nucleic acid extraction chemistry production to reduce single-source dependency exposure. For New Entrants and Emerging Players: The premium-economy price-point gap in direct-to-consumer telehealth-integrated screening kits offers white-space capture opportunity. Target online retail channels bypassing traditional clinical laboratory procurement with wellness-oriented positioning. Japan's Tokyo-Osaka corridor laboratories present the most penetrable geography where Ministry of Health reimbursement alignment favors novel molecular platforms. Pursue microbiome therapeutic monitoring partnerships with inflammatory bowel disease centers as anchor application. For Investors and Strategic Acquirers: FDA 510(k) clearance for novel biomarker panels is the leading indicator that molecular diagnostic platform valuations will inflect upward. Five-to-ten year viability favors pure-play developers with biomarker depth over diversified life science conglomerates with manufacturing scale alone. Acquisition target archetype: European notified body relationship holders with EU IVD compliance infrastructure. Signal to watch: Medicare reimbursement code expansion for non-invasive colorectal screening beyond current fecal immunochemical and stool DNA categories.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Medicare code alignment for stool DNA tests anchors United States commercialization timelines. |
| CE Marking Pathway | EU IVD notified body relationships compress molecular assay approval durations for European market entry. |
| Hospital System Partnership | Sole-source agreements with consolidated United States networks lock in multi-year reagent volumes. |
| Software Companion Development | AI interpretation layers for multi-analyte stool DNA reports differentiate platform offerings. |
| Regulatory Approval Pathway | PMDA quality management standard compliance opens Japan Ministry of Health reimbursement access. |
Research Methodology
Independent corroboration across laboratory operations directors, molecular diagnostics platform engineers, hospital GPO contracts managers, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with clinical laboratory stakeholders combined secondary validation through FDA 510(k) filings, EU IVD notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up test volume modeling and top-down market sizing triangulate across molecular diagnostics, immunoassay, microscopy, and chemical test modality segments.
Comparable-period anchoring to historical fecal immunochemical test adoption curves and stool DNA reimbursement trajectories shaped projection framework construction. Segmentation dimensions modeled span product type, application priority, end-user technical sophistication, and distribution channel regulatory handling requirements. CAGRs derive from test volume elasticity to reimbursement decisions and laboratory automation investment cycles. Forecast inputs incorporate seasonal norovirus surge patterns and biologic therapy monitoring protocol expansion in inflammatory bowel disease centers.
Underlying measurement precision varies by segment; molecular diagnostics and immunoassay categories carry tighter precision than microscopy and legacy chemical test methodologies. Forecasts reflect assumptions on Medicare reimbursement stability, EU IVD notified body capacity recovery, and Japan PMDA documentation requirement evolution. Material deviation in FDA premarket review pathway modernization or statutory health insurance mandate modifications warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
US Viral Clearance Market
Testing Services
Host Cell Protein Testing Market
Testing Services
Drug Tester Market
Testing Services
In-Vitro Diagnostic Services Market
Testing Services
Vestibular Testing System Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Medical Device Analytical Testing Outsourcing Market
Testing Services
Large Molecule Bioanalytical Testing Services Market
Testing Services
Antibiotic Residue Test Kits Market