
 Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market | 2026-2036
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market Foresight
The pricing gap between patented lipopeptides and generic glycopeptides is repositioning procurement strategies across health systems. Pfizer Inc. leverages its hospital sales infrastructure to sustain volume leadership in intravenous formulations. Merck & Co., Inc. anchors its position through backward integration into active pharmaceutical ingredient supply. Basilea Pharmaceutica Ltd. differentiates via specialization in oral step-down therapies that reduce length-of-stay.
Methicillin-Resistant Staphylococcus Aureus drugs comprise antibacterial agents engineered to overcome penicillin-binding protein modifications, with lipopeptides disrupting cell membrane potential through calcium-dependent depolarization. These therapies serve the primary purpose of treating refractory skin, bloodstream, and pneumonia infections where standard beta-lactam therapy fails. Oxazolidinones capture disproportionate margin pools in outpatient parenteral antimicrobial therapy programs due to oral bioavailability advantages. Intravenous administration retains volume dominance in intensive care settings, though oral routes gain traction in early discharge protocols. Hospital pharmacies constitute the principal distribution node, controlling formulary access and influencing prescribing patterns through antimicrobial stewardship committees.
The FDA's Qualified Infectious Disease Product program shapes clinical trial design through streamlined review pathways, while EMA's antimicrobial resistance strategy mandates environmental risk assessments for manufacturing discharge. BIS quality standards in India govern import certification for finished formulations. Stakeholders must monitor how evolving pharmacoeconomic thresholds in CMS reimbursement will reshape investment priorities across the development pipeline.
Market Dynamics
The FDA's Qualified Infectious Disease Product designation compresses clinical trial timelines by four years, reshaping how developers sequence regulatory submissions across multiple geographies simultaneously.
Growth Catalysts
- Streamlined FDA Pathways:The Qualified Infectious Disease Product program grants priority review and extended market exclusivity, accelerating commercialization for novel anti-MRSA agents targeting refractory bloodstream infections.
- Hospital Antimicrobial Stewardship Mandates:CMS reimbursement conditions now require documented resistance surveillance, driving formulary adoption of newer agents with narrower resistance profiles.
- Calcium-dependent Depolarization Mechanisms:Lipopeptide platforms that disrupt cell membrane potential without cross-resistance to glycopeptides are capturing intensive care unit protocols.
Market Restraints
- Fermentation Input Volatility:Daptomycin and other lipopeptide active pharmaceutical ingredients depend on Streptomyces roseosporus cultivation, exposing margins to serum albumin and soy flour price swings.
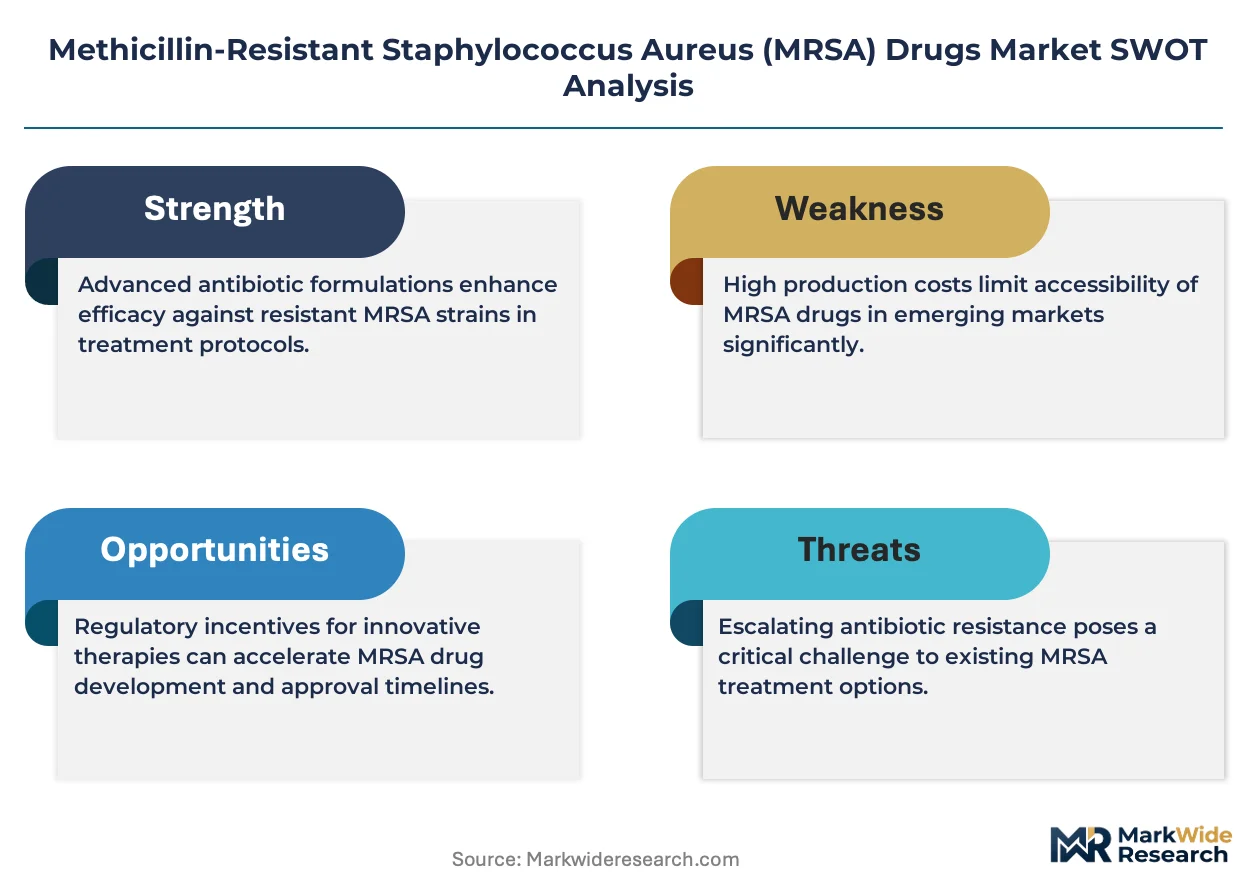
- Single-Source API Concentration:China dominates lipopeptide intermediate production, creating supply vulnerability for European and North American finished dose manufacturers.
- Generic Glycopeptide Substitution:Vancomycin and teicoplanin commoditization in outpatient parenteral programs caps pricing power for novel intravenous therapies.
Strategic Opportunities
- Oral Step-Down Protocols:Oxazolidinone tablets enabling early hospital discharge represent underpenetrated territory in United States bundled payment models.
- Environmental Risk Assessment Waivers:EMA's antimicrobial resistance strategy creates fast-track pathways for manufacturers demonstrating manufacturing discharge controls.
- Long-Acting Lipoglycopeptide Formulations:Single-dose intravenous regimens that eliminate daily nursing administration are gaining traction in skilled nursing facilities.
Industry Challenges
- Specialized Pharmacokinetic Modeling Talent:Lipopeptide therapeutic drug monitoring requires expertise in protein binding kinetics that outpaces current clinical microbiology training pipelines.
- Antimicrobial Stewardship Committee Navigation:Hospital pharmacy and therapeutics committees impose escalating evidentiary hurdles for formulary inclusion, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market |
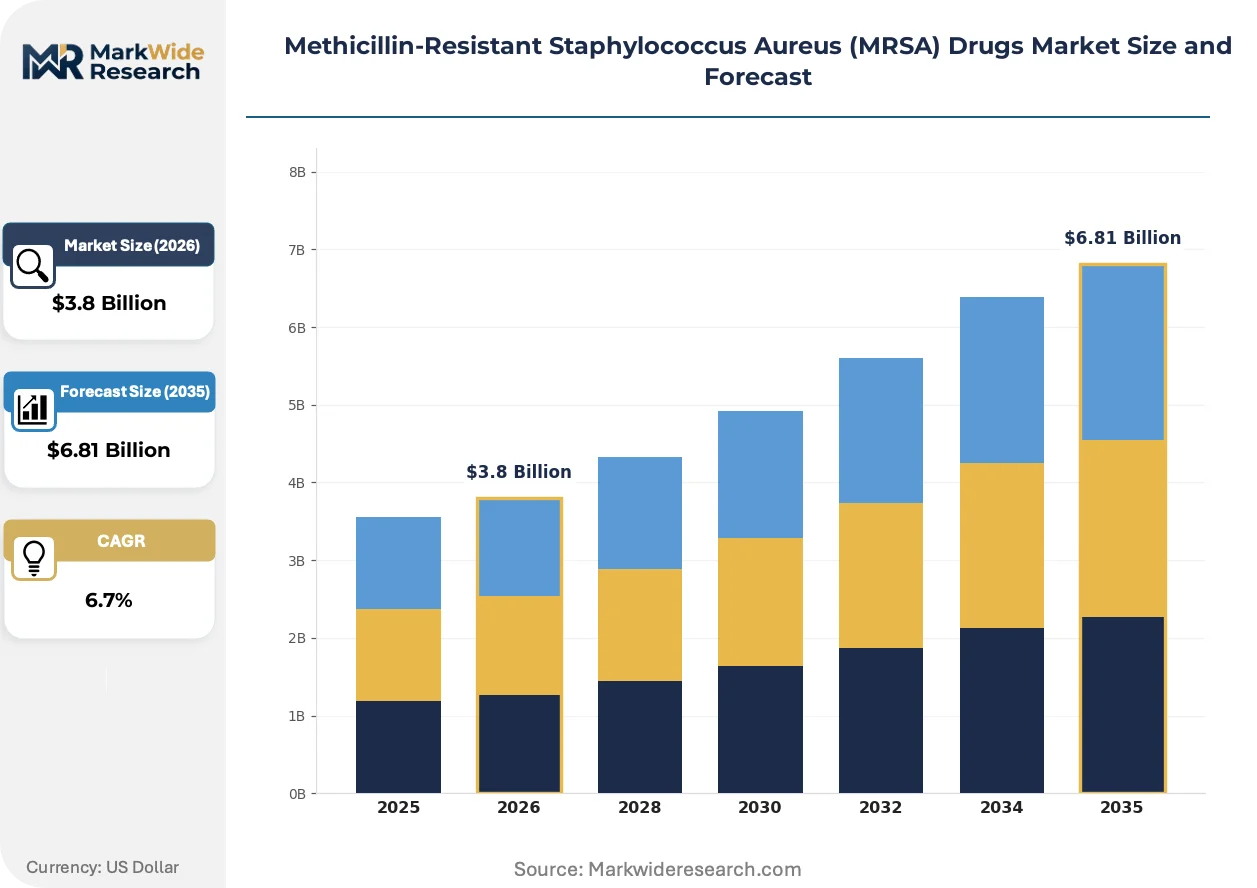
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-Lactams, Glycopeptides, Lipopeptides, Oxazolidinones Administration Route: Intravenous, Oral, Topical, Inhalation End User: Hospitals, Clinics, Home Care, Long-Term Care Facilities Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., AbbVie Inc., Johnson & Johnson, Allergan plc, Theravance Biopharma, Melinta Therapeutics Inc., Basilea Pharmaceutica Ltd., Paratek Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market Shifts & Advancements
Next-generation antibacterial platforms are compressing development timelines while regulatory agencies tighten environmental manufacturing standards. These forces are simultaneously expanding accessible patient populations and raising production compliance costs.
Next-generation lipoglycopeptides with dual-mechanism cell wall and membrane activity are rewriting therapeutic positioning in complicated skin and skin structure infections. Hospital infectious disease specialists are adopting these agents for vancomycin-refractory cases at twice the pace of standard lipopeptide protocols. This mechanism expansion is compressing the addressable market for traditional glycopeptide salvage therapy.
EMA's antimicrobial resistance manufacturing discharge requirements now mandate environmental risk assessments for all antibiotic active pharmaceutical ingredient production. European facilities must demonstrate zero detectable discharge of resistance-selecting compounds into wastewater streams. Contract manufacturers in Germany and Switzerland are investing in closed-loop fermentation systems to maintain EMA good manufacturing practice certification.
Hospital procurement committees are unbundling antimicrobial therapy from bundled infection episode payments, creating separate reimbursement tracks for oral step-down regimens. United States acute care systems are replacing 28-day intravenous courses with 14-day IV-to-oral transitions in bloodstream infection protocols. This consumption-pattern shift favors agents with bioavailability exceeding ninety percent in outpatient parenteral programs.
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market Segmentation
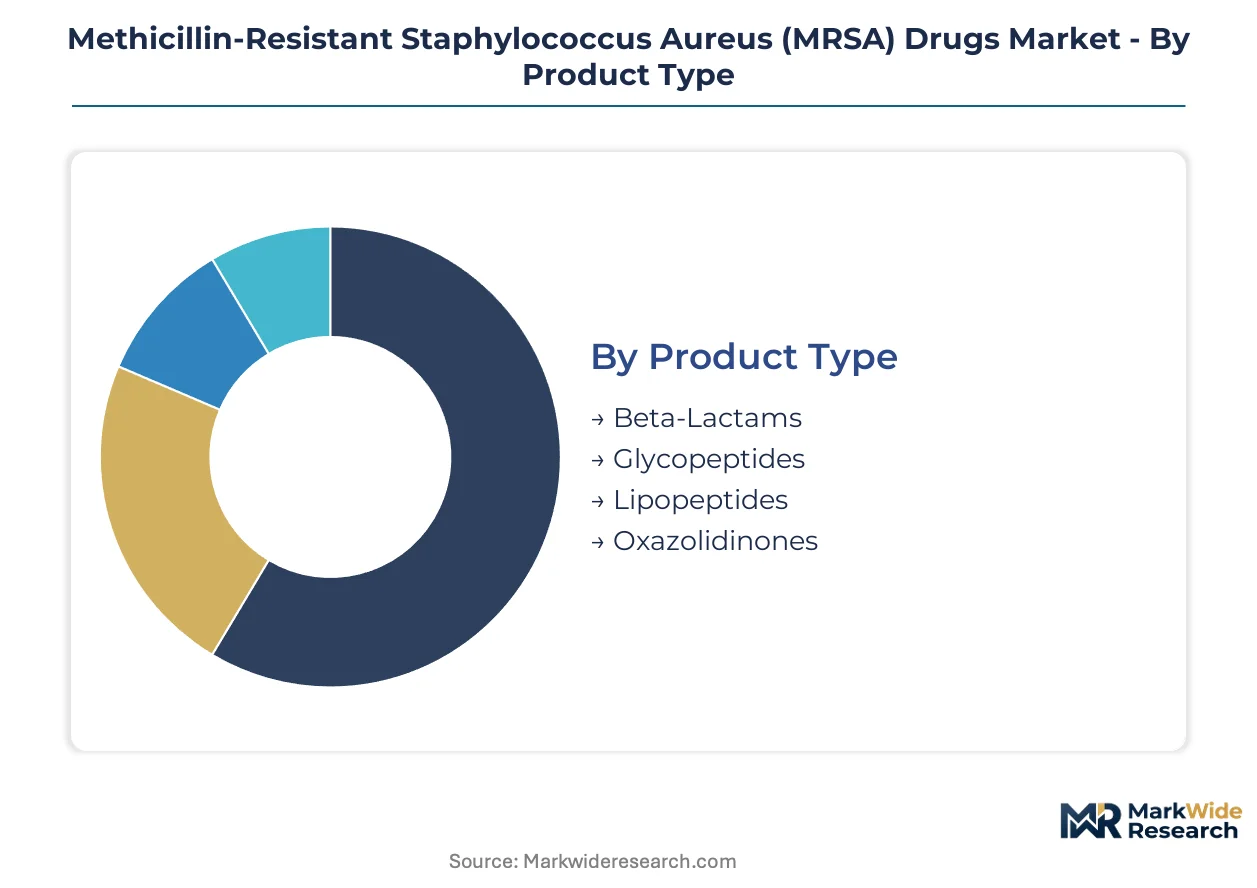
Segmentation in the MRSA drugs market reveals how clinical utility, reimbursement structures, and supply chain constraints fragment purchasing decisions across health systems. Understanding these divides explains why lipopeptides command premium positioning while glycopeptides face commoditization pressure.
Product Type:
Volume leadership clusters in legacy agents with expired patent protection, while premium capture concentrates in mechanism-differentiated platforms with resistance-evasion profiles.
- Glycopeptides:Vancomycin and teicoplanin formulations retain the highest prescription volumes in hospital formularies due to decades of resistance surveillance data and established therapeutic drug monitoring protocols. United States academic medical centers continue standardizing these agents for methicillin-susceptible Staphylococcus aureus coverage, though vancomycin-intermediate strains are eroding confidence in salvage therapy.
- Lipopeptides:Daptomycin disrupts cell membrane potential through calcium-dependent depolarization without cross-resistance to glycopeptides, positioning it for vancomycin-refractory bloodstream infections and right-sided endocarditis. Intensive care units in tertiary hospitals drive disproportionate demand where renal function permits, as myopathy risk limits concurrent statin use.
- Oxazolidinones:Linezolid and tedizolid offer complete oral bioavailability enabling early hospital discharge in outpatient parenteral antimicrobial therapy programs.
- Beta-Lactams:Ceftaroline and ceftobiprole represent the only beta-lactam options with anti-MRSA activity, though cross-reactivity limits use in severe penicillin allergy.
Mature deployment sits with glycopeptides. Newer deployment is concentrated in lipopeptides.
Administration Route:
Hospital reimbursement mechanics favor intravenous delivery in acute episodes, while bundled payment models accelerate oral transition protocols.
- Intravenous:Retains volume dominance in intensive care settings where bioavailability certainty and rapid attainment of therapeutic levels determine outcomes. Hospital pharmacies control procurement through antimicrobial stewardship committee oversight, with lipoglycopeptide single-dose regimens gaining traction in skilled nursing facilities to eliminate daily nursing administration.
- Oral:Oxazolidinone tablets capture disproportionate margin pools in outpatient parenteral programs due to bioavailability exceeding ninety percent. United States acute care systems are replacing 28-day intravenous courses with 14-day IV-to-oral transitions in bloodstream infection protocols.
- Topical:Mupirocin and retapamulin address localized skin and soft tissue colonization in decolonization protocols prior to orthopedic surgery.
- Inhalation:Limited to cystic fibrosis populations with persistent MRSA airway colonization requiring suppressive therapy.
Acute-phase therapy concentrates in intravenous delivery. Step-down and chronic suppression are expanding most quickly in oral and topical routes.
End User:
Procurement authority and formulary control determine segment profitability, with centralized hospital purchasing contrasting fragmented long-term care decision-making.
- Hospitals:Academic medical centers and tertiary referral hospitals generate the highest per-patient revenue through complex bloodstream infection and pneumonia cases requiring combination therapy. Antimicrobial stewardship committees impose escalating evidentiary hurdles for formulary inclusion, extending sales cycles for novel agents.
- Long-Term Care Facilities:Skilled nursing facilities represent underpenetrated territory for single-dose lipoglycopeptide formulations that eliminate daily intravenous access requirements and reduce nursing labor.
- Clinics:Outpatient infusion centers manage stable patients requiring prolonged intravenous therapy in outpatient parenteral antimicrobial therapy programs.
- Home Care:Home infusion services support early discharge protocols with nursing visits for intravenous administration or patient self-administration training.
Formulary control sits with hospital pharmacy and therapeutics committees. Volume expansion is climbing the fastest in long-term care facilities adapting to bundled payment incentives.
Distribution Channel:
Channel selection reflects therapy acuity, with hospital pharmacies controlling access to intravenous formulations and retail channels capturing oral maintenance therapy.
- Hospital Pharmacies:Principal distribution node for intravenous lipopeptides and lipoglycopeptides, controlling formulary access and influencing prescribing patterns through antimicrobial stewardship protocols. Group purchasing organizations aggregate demand across health systems to negotiate tiered pricing based on volume commitments.
- Wholesalers:McKesson, AmerisourceBergen, and Cardinal Health maintain cold chain infrastructure for temperature-sensitive biological formulations while managing inventory for hospital and retail pharmacy customers.
- Retail Pharmacies:Capture oral oxazolidinone prescriptions for outpatient parenteral antimicrobial therapy completion and decolonization regimens.
- Online Pharmacies:Limited penetration due to controlled substance scheduling and temperature-controlled shipping requirements for parenteral antibiotics.
Procurement concentration sits with hospital pharmacies. Channel diversification is gaining share fastest in retail pharmacies serving outpatient parenteral programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors pharmaceutical innovation for anti-MRSA development, hosting contract research organizations that accelerate clinical trial execution. Hospital networks in this cluster drive early adoption of novel lipopeptide formulations through antimicrobial stewardship protocols.
United States
Nosocomial infection surveillance programs sustain high-volume prescribing of intravenous lipopeptides in tertiary care centers. The FDA's Qualified Infectious Disease Product designation compresses regulatory timelines for developers targeting refractory bloodstream infections. New Jersey's pharmaceutical manufacturing belt hosts fermentation facilities producing daptomycin active pharmaceutical ingredients under strict environmental discharge controls.
Germany
Academic medical centers in Berlin and Munich generate demand for combination therapy protocols in pneumonia cases. EMA antimicrobial resistance manufacturing standards mandate closed-loop fermentation systems for antibiotic API production. The Rhine-Main biotech cluster concentrates contract manufacturing organizations specializing in lipoglycopeptide formulation.
Switzerland
Basel's pharmaceutical hub drives investment in oral step-down therapies that reduce hospital length-of-stay. Swissmedic maintains stringent pharmacovigilance requirements for novel antibacterial agents entering hospital formularies. The country's precision fermentation capabilities support lipopeptide intermediate production with minimal environmental discharge.
India
Generic glycopeptide manufacturing for export markets concentrates in Hyderabad and Ahmedabad. BIS quality standards govern import certification for finished anti-MRSA formulations entering domestic hospital supply chains. The country's contract research organizations manage bioequivalence studies for oral oxazolidinone generics targeting outpatient parenteral programs.
Japan
Aging demographics and extended hospital stays sustain demand for single-dose lipoglycopeptide formulations in long-term care facilities. PMDA's streamlined review pathways for anti-infective agents accelerate market entry for mechanism-differentiated therapies. The Kansai region's fermentation infrastructure supports domestic production of lipopeptide active pharmaceutical ingredients.
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market Competitive Landscape
Capital-heavy producers compete with asset-light developers across the anti-MRSA landscape, with fermentation-based API manufacturers facing distinct margin pressures from synthetic chemistry specialists. The market structures around three tiers: global hospital sales infrastructure operators, backward-integrated fermentation specialists, and oral formulation niche players. Consolidation concentrates among entities controlling lipopeptide supply chains, while fragmentation persists in generic glycopeptide distribution. Dominant competitive moves include captive supply integration into Streptomyces cultivation and strategic positioning for CMS bundled payment qualification.
Among US-based pharmaceutical conglomerates, Merck & Co., Inc. and Pfizer Inc. exemplify contrasting infrastructure strategies. Merck's position reflects backward integration into active pharmaceutical ingredient supply, while Pfizer leverages hospital sales networks for intravenous formulation volume leadership. Basilea Pharmaceutica Ltd. occupies a specialized tier focused on oral step-down therapies, representing the asset-light archetype that reduces patient length-of-stay without fermentation capacity investment.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| AbbVie Inc. |
| Johnson & Johnson |
| Allergan plc |
| Theravance Biopharma |
| Melinta Therapeutics Inc. |
| Basilea Pharmaceutica Ltd. |
| Paratek Pharmaceuticals, Inc. |
| Others |
Supply & Pricing Matrix
EMA antimicrobial resistance manufacturing discharge requirements gate qualified supply for European hospital formularies and anchor premium-tier pricing access for lipopeptide formulations with verified zero-detectable discharge credentials. This environmental compliance layer separates fermentation-based API producers eligible for CMS bundled payment qualification from commodity glycopeptide suppliers facing margin compression.
Pricing Analysis
Hospital reimbursement tied to documented resistance surveillance and length-of-stay reduction anchors value-based pricing for novel anti-MRSA agents. Three-tier pricing structure across premium lipopeptides, standard lipoglycopeptides, and economy generic glycopeptides reflects certification grade and therapeutic drug monitoring complexity. Cost compression in the glycopeptide tier is intensifying because vancomycin commoditization in outpatient parenteral programs caps pricing power. Long-term care facilities and skilled nursing operators exhibit highest price sensitivity, while academic medical centers prioritize mechanism differentiation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees and group purchasing organizations mandate multi-supplier qualification for lipopeptide active pharmaceutical ingredients. Supply concentrates in China for fermentation intermediates, India for generic glycopeptide finished doses, and Switzerland for precision lipopeptide production. Daptomycin and other lipopeptide APIs draw from Streptomyces roseosporus cultivation, resting on serum albumin and soy flour inputs. Single-source API concentration in Chinese lipopeptide intermediate production creates supply vulnerability for North American and European finished dose manufacturers. Distribution runs through hospital pharmacies controlling formulary access, with wholesalers managing cold chain logistics for temperature-sensitive biological formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around backward-integrated fermentation specialists with captive Streptomyces cultivation capacity, as generic glycopeptide commoditization and EMA environmental compliance costs force asset-light developers toward exit or acquisition.
For Market Incumbents: Deploy antimicrobial stewardship committee relationship infrastructure to secure formulary placement ahead of novel lipoglycopeptide launches. Deepen backward integration into active pharmaceutical ingredient supply through captive fermentation capacity in Switzerland or Germany to satisfy EMA zero-discharge mandates. Defend against oxazolidinone tablet substitution in outpatient parenteral programs by demonstrating superior resistance surveillance data for intravenous formulations in bloodstream infection protocols. For New Entrants and Emerging Players: FDA Qualified Infectious Disease Product designation in the United States opens a window for streamlined regulatory entry targeting refractory bloodstream infections with mechanism-differentiated platforms. Skilled nursing facilities represent the most penetrable segment for single-dose lipoglycopeptide formulations eliminating daily nursing administration. Pursue hospital system partnership structures that bundle formulary access with resistance surveillance data sharing agreements. For Investors and Strategic Acquirers: CMS reimbursement condition tightening around documented stewardship compliance is the leading indicator that formulary control will concentrate among entities with hospital sales infrastructure and environmental certification. Long-term viability favors backward-integrated specialists with fermentation assets in regulated jurisdictions over synthetic chemistry-dependent developers. Target acquisition profiles center on oral step-down therapy specialists with bioavailability data exceeding ninety percent. Watch for PMDA streamlined review pathway activation for anti-infective agents as the signal for Japanese market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Fermentation System Investment | EMA zero-discharge certification preserves API supply access for European hospital formularies. |
| Oral Step-Down Protocol Development | CMS bundled payment qualification reduces patient length-of-stay in bloodstream infection cases. |
| Antimicrobial Stewardship Data Partnership | Hospital pharmacy committee relationships secure formulary placement for novel lipoglycopeptides. |
| Single-Dose Lipoglycopeptide Formulation | Skilled nursing facility adoption eliminates daily intravenous access nursing labor requirements. |
| Backward Integration into Streptomyces Cultivation | Captive lipopeptide intermediate production insulates margins from Chinese supply concentration risk. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for regulatory pathway and pipeline status verification. Primary interviews with drug development executives, hospital procurement managers, formulary directors, and payer access specialists combined with secondary validation to triangulate market sizing. Bottom-up prescription volume modeling and top-down revenue aggregation approaches were cross-checked for consistency across the analysis window.
Bottom-up modeling segmented demand by product type, administration route, end user, and distribution channel, while top-down validation anchored totals to hospital pharmaceutical spending patterns. CAGRs were derived from fitted growth curves calibrated to historical adoption rates of prior anti-MRSA agents. Forecast inputs included resistance surveillance data trends, CMS reimbursement condition evolution, and EMA manufacturing discharge standard implementation timelines across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for long-acting lipoglycopeptide formulations would alter the outlook if single-dose regimens displace multi-day intravenous courses faster than anticipated. Deviation in FDA Qualified Infectious Disease Product designation granting rates or EMA environmental waiver approvals would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Health Economics and Outcomes Research (HEOR) Services Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Metabolomics Market
Medical Research
Epigenetics Market
Medical Research
Global Humanized Mouse Model Market
Medical Research
Cancer Mouse Models Market
Medical Research
Mice Model Technologies Market
Medical Research
Precision Medicine Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
Human Osteoblasts Market
Medical Research
US Academic Medical Centers Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
Organoids and Spheroids Market
Medical Research
Forensic Medicine Market
Medical Research
Epigenomics Market