
 PDX Models Market | 2026-2036
PDX Models Market Size, Share, and Industry Trends Forecast 2026-2036
PDX Models Market Insights
The FDA's Animal Rule pathway is recalibrating cost-of-entry calculus for preclinical oncology services, forcing contract research organizations to expand vivarium capacity and histopathology capabilities. Charles River Laboratories leverages its North American footprint to sustain large-scale xenograft production for immuno-oncology pipelines. Crown Bioscience anchors its competitive position through specialized hu-PDX platforms targeting hematologic malignancies. WuXi AppTec competes on integrated drug-discovery-to-IND submission workflows that compress development timelines for biotech sponsors.
Patient-derived xenografts involve implantation of human tumor tissue into immunodeficient murine hosts, maintaining original stromal architecture and genomic heterogeneity with passage-to-passage stability exceeding 80% molecular fidelity across 10 generations. These models serve as predictive surrogates for clinical drug response, enabling pharmaceutical sponsors to prioritize compounds with superior translational probability before Phase I investment. Oncology Research applications currently dominate service revenue within the Application dimension, while Personalized Medicine represents the fastest-expanding segment as companion diagnostic developers seek co-clinical trial frameworks. Tumor Xenografts within Product Type retain mature, high-volume positioning, though Genetic Editing technology integration is displacing conventional cell-line-derived approaches in premium pricing tiers.
EMA's MDR framework and FDA's GLP standards collectively shape vivarium accreditation requirements, mandating specific-pathogen-free husbandry protocols and chain-of-custody documentation for human tissue sourcing. China's NMPA has issued draft guidelines aligning domestic preclinical oncology study designs with ICH S9 carcinogenicity benchmarks, expanding addressable demand for compliant PDX providers. Japan's PMDA maintains distinct xenograft acceptance criteria for regenerative medicine products, creating regulatory fragmentation that stakeholders must monitor when structuring multi-regional IND strategies.
Market Dynamics
Immuno-oncology pipelines are forcing contract research organizations to reconfigure vivarium infrastructure around humanized PDX platforms that replicate tumor microenvironment complexity with greater fidelity than conventional xenografts.
Growth Catalysts
- FDA Animal Rule Pathway:The FDA's alternative approval mechanism for medical countermeasures is expanding toxicology study requirements that favor PDX-based efficacy demonstrations for biologic candidates.
- Companion Diagnostic Co-Development:Pharmaceutical sponsors now require PDX-matched clinical trial frameworks to validate biomarker-driven patient stratification strategies alongside therapeutic candidates.
- CRISPR-Engineered Immunodeficient Hosts:Advanced genetic editing of murine strains is enabling superior human immune system engraftment for immuno-oncology model development.
Market Restraints
- Human Tissue Supply Volatility:Biorepository access constraints and informed consent complexity create batch-to-batch variability in tumor specimen availability for large-scale studies.
- Specialized Histopathology Bottlenecks:Certified veterinary pathologists capable of cross-species tumor characterization remain concentrated in NCI-designated cancer center corridors.
- Cell-Line-Derived Model Substitution:Engineered cell lines with CRISPR-introduced mutations offer faster turnaround and lower per-study costs for early-stage compound screening.
Strategic Opportunities
- China NMPA Alignment:Draft guidelines harmonizing domestic preclinical oncology studies with ICH S9 benchmarks are expanding compliant PDX service demand from domestic biotech sponsors.
- Personalized Medicine Application Expansion:Individual patient avatar models for treatment selection in refractory oncology cases represent an emerging direct-to-clinic revenue stream.
- Multi-Regional IND Strategy Services:Regulatory fragmentation between FDA, EMA, and PMDA xenograft acceptance criteria creates advisory service opportunities for cross-border filing support.
Industry Challenges
- Chain-of-Custody Documentation Burden:GLP-compliant tissue sourcing requires specimen tracking systems that extend from surgical collection through histopathological analysis.
- Specific-Pathogen-Free Husbandry Capital Intensity:Barrier facility construction and maintenance for immunodeficient colonies demands sustained infrastructure investment with multi-year depreciation cycles.
- Genomic Fidelity Verification Complexity:Passage-to-passage molecular stability monitoring requires sequencing capabilities that many mid-tier providers lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PDX Models Market |
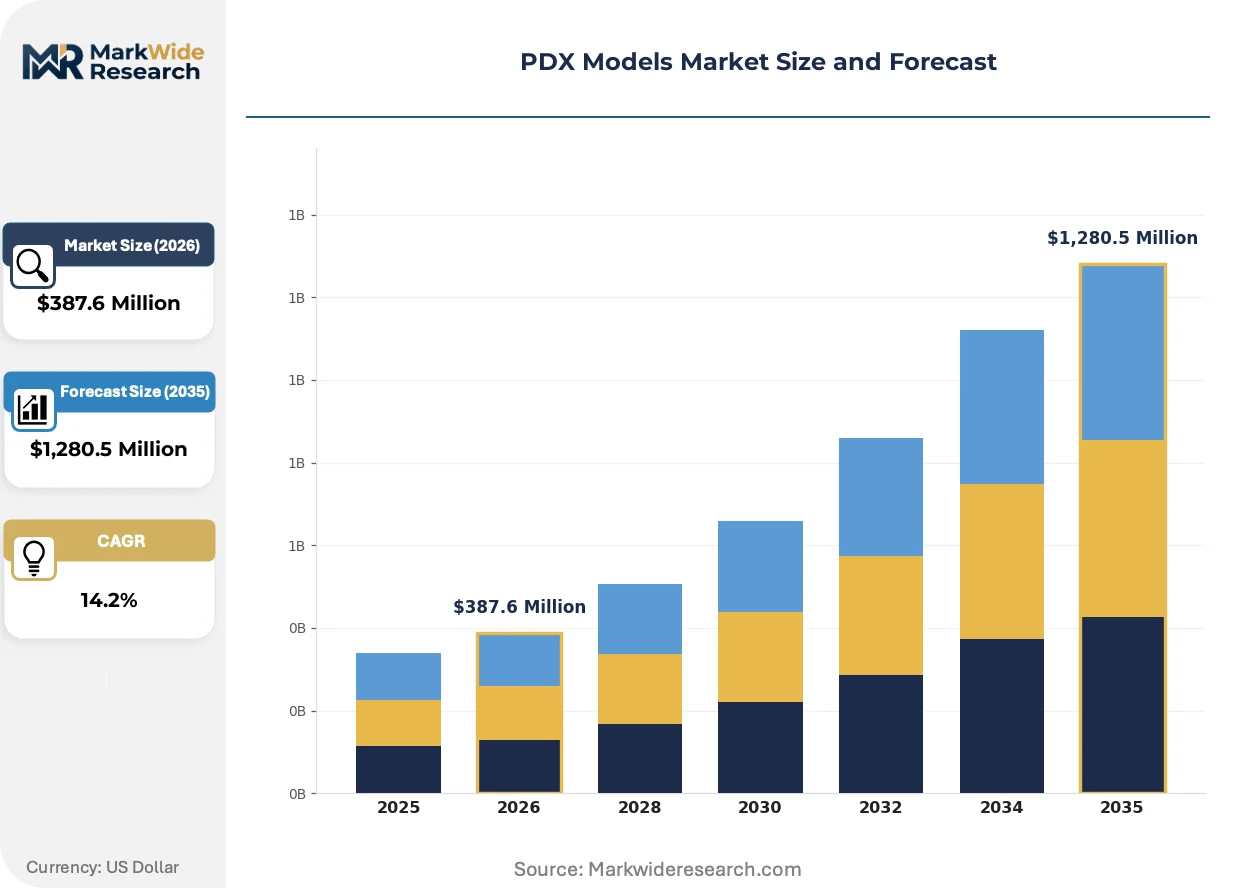
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Xenograft Models, Patient-Derived Xenografts, In Vivo Models, Tumor Xenografts Application: Oncology Research, Drug Development, Personalized Medicine, Biomarker Discovery End User: Pharmaceutical Companies, Research Institutions, Biotech Firms, Academic Organizations Technology: Genetic Editing, 3D Bioprinting, Imaging Techniques, Cell Culture |
| Companies Covered | Charles River Laboratories, Crown Bioscience, The Jackson Laboratory, Champions Oncology, WuXi AppTec, Oncodesign, Hera BioLabs, EPO Berlin-Buch GmbH, Taconic Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PDX Models Market Trends and Innovations
Technological convergence between genetic engineering and tissue preservation methods is compressing model development timelines while expanding the addressable range of tumor indications.
Humanized PDX platforms incorporating patient-matched immune components are unifying previously separate preclinical and clinical immunotherapy development workflows. Large pharmaceutical sponsors now mandate these models for checkpoint inhibitor combination studies. This unification is collapsing the traditional handoff friction between translational medicine and clinical operations teams.
EMA's MDR framework is tightening vivarium accreditation standards for European oncology study submissions. Sponsors must now demonstrate specific-pathogen-free husbandry protocols and comprehensive tissue provenance documentation. Contract research organizations serving EMA-bound filings are accelerating facility certification investments ahead of formal audit deadlines.
Biotech sponsors are consolidating preclinical service procurement around integrated drug-discovery-to-IND submission partnerships rather than discrete study contracts. This behavior compresses vendor selection cycles and favors providers with captive histopathology, bioanalytical, and regulatory writing capabilities. The United States exhibits the most pronounced consolidation as venture-backed oncology companies prioritize speed-to-IND milestones.
PDX Models Market Segmentation
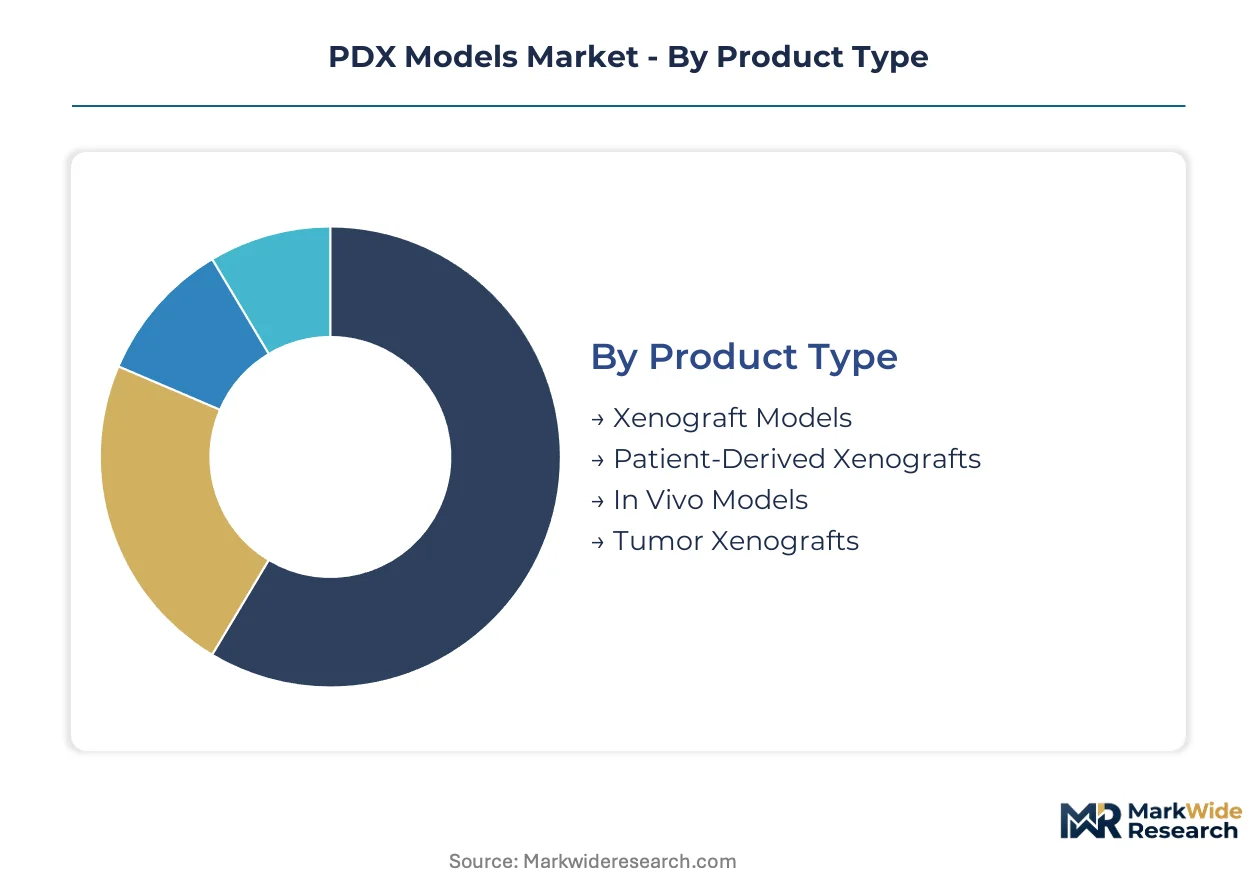
PDX model segmentation reveals how technical specifications, therapeutic applications, and end-user procurement priorities reshape vendor positioning. Each dimension carries distinct margin profiles and regulatory compliance requirements that determine competitive viability.
Product Type:
Replacement cycles accelerate as genetic editing capabilities displace conventional xenograft platforms with superior human immune system engraftment.
- Patient-Derived Xenografts:Human tumor tissue maintains original stromal architecture and genomic heterogeneity with passage-to-passage molecular fidelity exceeding 80% across 10 generations. Demand concentrates in United States NCI-designated cancer centers where biorepository access enables large-scale immuno-oncology validation studies constrained by GLP tissue sourcing requirements.
- Tumor Xenografts:Cell-line-derived models offer faster turnaround and standardized reproducibility for early-stage compound screening workflows. Procurement from pharmaceutical sponsors prioritizes these platforms for high-throughput efficacy assessments where cost-per-study metrics dominate vendor selection criteria.
- Xenograft Models:Broad category encompassing conventional immunodeficient host implantations without patient-matched tissue sourcing.
- In Vivo Models:Live-animal testing platforms spanning pharmacokinetic and toxicology study designs beyond oncology applications.
Volume placements concentrate in Tumor Xenografts; the faster expansion belongs to Patient-Derived Xenografts.
Application:
Cost tier differentiation separates premium-priced personalized medicine services from standardized oncology research contracts.
- Oncology Research:Preclinical validation of therapeutic candidates against human tumor biology dominates current service revenue through checkpoint inhibitor combination studies and biomarker-driven patient stratification frameworks. United States pharmaceutical sponsors mandate these models for FDA Animal Rule pathway submissions.
- Personalized Medicine:Individual patient avatar models enable treatment selection in refractory oncology cases through co-clinical trial frameworks. Companion diagnostic developers in Europe and Asia-Pacific drive fastest segment expansion as EMA MDR framework tightens vivarium accreditation standards.
- Drug Development:Integrated discovery-to-IND submission workflows compress development timelines for biotech sponsors.
- Biomarker Discovery:Molecular profiling services linking preclinical response patterns to clinical trial enrollment criteria.
Revenue concentration sits with Oncology Research; Personalized Medicine claims the steepest expansion trajectory.
End User:
Customer type determines contract structure complexity from discrete study procurement to multi-year integrated partnerships.
- Pharmaceutical Companies:Large sponsors consolidate procurement around captive histopathology, bioanalytical, and regulatory writing capabilities with speed-to-IND milestones driving vendor selection. United States venture-backed oncology companies exhibit the most pronounced consolidation behavior.
- Biotech Firms:Emerging sponsors prioritize compressed timelines and flexible study designs over established provider scale.
- Research Institutions:Academic centers maintain internal biorepositories and histopathology capabilities for investigator-initiated studies.
- Academic Organizations:Grant-funded research programs with limited commercial translation requirements.
Contract value concentrates in Pharmaceutical Companies; Biotech Firms are gaining share fastest.
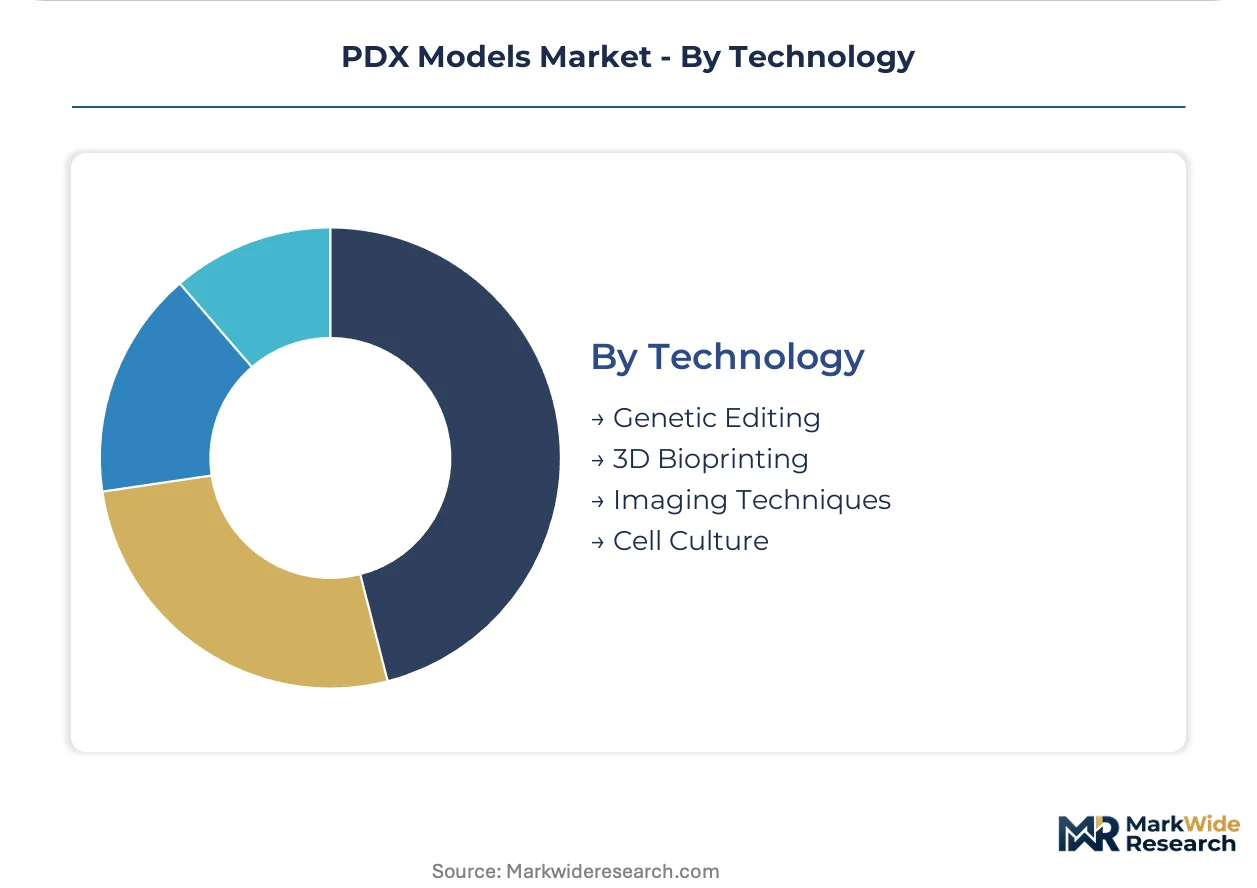
Technology:
Supply concentration among providers with in-house sequencing and genetic engineering capabilities shapes competitive access.
- Genetic Editing:CRISPR-engineered immunodeficient hosts enable superior human immune system engraftment for hu-PDX platform development. Charles River Laboratories and Crown Bioscience deploy these capabilities across North American and Asian facilities to serve immuno-oncology pipeline demand.
- Imaging Techniques:Non-invasive longitudinal monitoring of tumor progression reduces animal usage while generating quantitative efficacy data.
- 3D Bioprinting:Emerging scaffold-based tissue reconstruction methods for microenvironment complexity replication.
- Cell Culture:Conventional in vitro expansion methods preceding xenograft implantation.
Platform investments concentrate in Genetic Editing; Imaging Techniques show the fastest capability adoption rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and Boston's Route 128 corridor concentrate preclinical contract research through state-level biotech tax credits and NCI-designated cancer center proximity. These zones anchor North American PDX production capacity.
United States
NCI-designated cancer centers in Boston, Houston, and San Francisco maintain extensive biorepositories that feed immuno-oncology validation studies. FDA Animal Rule pathway submissions require GLP-compliant tissue sourcing that concentrates procurement among accredited vivarium operators. Charles River Laboratories leverages its Wilmington, Massachusetts footprint to sustain large-scale xenograft production for pharmaceutical sponsors.
China
Domestic biotech sponsors in Shanghai and Suzhou drive compliant PDX service demand following NMPA draft guidelines aligning preclinical oncology studies with ICH S9 carcinogenicity benchmarks. WuXi AppTec anchors integrated drug-discovery-to-IND submission workflows from its Zhangjiang Hi-Tech Park base. The Yangtze River Delta corridor captures venture capital flows into oncology pipeline development.
Germany
EMA MDR framework tightening on vivarium accreditation standards accelerates facility certification investments ahead of formal audit deadlines. EPO Berlin-Buch GmbH operates from the capital's biotech cluster where specific-pathogen-free husbandry protocols meet European oncology study submission requirements. Heidelberg and Munich academic medical centers supply tumor specimens for hematologic malignancy models.
Japan
PMDA maintains distinct xenograft acceptance criteria for regenerative medicine products, creating regulatory fragmentation that complicates multi-regional IND strategies. Taconic Biosciences serves Japanese pharmaceutical sponsors from its global platform while navigating Tokyo's specialized preclinical requirements. Osaka's pharmaceutical corridor demands patient-derived models for combination therapy studies.
United Kingdom
Companion diagnostic developers in Cambridge and Oxford drive fastest segment expansion for personalized medicine applications as MHRA post-Brexit alignment with EMA standards proceeds. Champions Oncology maintains European service capabilities through UK-based operations. London's translational medicine clusters prioritize co-clinical trial frameworks linking PDX response to biomarker validation.
PDX Models Market Competitive Landscape
North American producers anchor the premium-tier service segment; Asian specialists hold volume positioning through integrated manufacturing workflows. The market structure consolidates around three operational archetypes: full-service contract research organizations with captive regulatory writing capabilities, platform specialists concentrating on humanized PDX technologies, and regional providers competing on compressed study timelines. Dominant competitive moves include strategic partnerships linking biorepository access to histopathology services and geographic expansion through facility certification in multiple regulatory jurisdictions.
Within the full-service contract research tier, Charles River Laboratories and WuXi AppTec exemplify providers with integrated discovery-to-IND capabilities spanning North American and Asian production footprints. Crown Bioscience occupies a specialist position through concentrated investment in hematologic malignancy platforms. These three anchors demonstrate how competitive positioning separates through technology specialization versus geographic coverage breadth rather than discrete product differentiation.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Crown Bioscience |
| The Jackson Laboratory |
| Champions Oncology |
| WuXi AppTec |
| Oncodesign |
| Hera BioLabs |
| EPO Berlin-Buch GmbH |
| Taconic Biosciences |
| Others |
Pricing and Supply Chain Analysis
CRISPR-engineered immunodeficient host production is simultaneously compressing per-model development costs and concentrating supply among providers with captive genetic engineering capabilities, reshaping how pharmaceutical sponsors evaluate total cost of ownership against vendor accreditation tiers.
Pricing Analysis
Lead-time-driven pricing stratification separates rush-order hu-PDX platforms commanding premium placement fees from standard-turnaround cell-line-derived models procured on spot contracts. Three-tier pricing structure across GLP-certified, SPF-compliant, and conventional vivarium tiers reflects certification-grade differentiation, with FDA Animal Rule pathway submission requirements intensifying cost compression in the middle tier. Academic research institutions exhibit highest price sensitivity, while immuno-oncology pipeline sponsors prioritize molecular fidelity verification over per-study economics.
Supply Chain Analysis
Single-source vulnerability sits with NCI-designated cancer center biorepositories in the United States, where surgical specimen collection protocols feed downstream PDX production across Charles River Laboratories and Crown Bioscience facilities. Human tumor tissue sourcing draws from Boston, Houston, and San Francisco medical centers, while immunodeficient murine strain breeding rests on Taconic Biosciences and The Jackson Laboratory genetic stocks. Tariff exposure on cryopreservation media and sequencing reagents threatens margin stability. Distribution runs through integrated CRO partnerships rather than spot market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PDX Models Market operates as a cost-of-compliance story where EMA MDR framework vivarium accreditation requirements create substantial barrier-to-entry moats for accredited operators against uncertified competitors.
For Market Incumbents: Deploy biorepository access exclusivity agreements to lock in surgical specimen flows from NCI-designated cancer centers before emerging platform specialists consolidate regional tissue sourcing relationships. CRISPR-engineered cell-line substitution threatens conventional xenograft volumes, necessitating accelerated hu-PDX platform certification investments in China and Germany to capture NMPA and EMA-bound filing demand. For New Entrants and Emerging Players: Contract research organization partnerships offer the most penetrable channel for accessing pharmaceutical sponsor procurement cycles without captive histopathology infrastructure. White-space opportunities concentrate in personalized medicine patient avatar services for European companion diagnostic developers and multi-regional IND strategy advisory for Japan PMDA regulatory fragmentation. A specialized hematologic malignancy platform positioning bypasses crowded solid tumor model competition. For Investors and Strategic Acquirers: Re-rating potential sits with integrated discovery-to-IND submission providers given biotech sponsor procurement consolidation behavior compressing vendor selection cycles. Long-term viability over the next decade hinges on genomic fidelity verification capabilities and cross-border facility certification breadth. Monitor FDA Animal Rule pathway expansion announcements as inflection indicators for biologic candidate toxicology service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Vivarium Certification Investment | EMA MDR framework compliance unlocks European oncology study submission revenue from EPO Berlin-Buch GmbH competitors. |
| Hu-PDX Platform Development Partnership | Humanized immune system engraftment capabilities capture checkpoint inhibitor combination study mandates from large pharmaceutical sponsors. |
| Biorepository Access Exclusivity Agreement | Surgical specimen chain-of-custody control secures molecular fidelity verification advantages against cell-line-derived model substitution. |
| Multi-Regional IND Advisory Service Launch | Regulatory fragmentation between FDA, EMA, and PMDA creates high-margin cross-border filing support revenue streams. |
| Integrated Histopathology Capability Acquisition | Captive veterinary pathology services compress pharmaceutical sponsor vendor selection cycles toward single-provider partnerships. |
Research Methodology
Multi-period observation of FDA Animal Rule pathway submission volumes, NCI cancer center biorepository expansion announcements, and immuno-oncology pipeline progression anchored the trend analysis, supplemented by interviews with preclinical services procurement directors, regulatory affairs leads at biotech sponsors, veterinary pathologists at contract research organizations, and companion diagnostic development executives. Secondary validation drew from FDA GLP inspection records, EMA MDR facility certification databases, ClinicalTrials.gov immuno-oncology study registrations, and NMPA draft guideline publications. Bottom-up service revenue modeling triangulated against top-down pharmaceutical R&D expenditure allocation estimates.
Segment-weighting across product type, application, end user, technology, and regional regulatory cluster dimensions informed value distribution analysis throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections incorporating sponsor procurement consolidation behavior and genetic editing technology diffusion curves. Humanized PDX platform adoption rates and personalized medicine co-clinical trial framework penetration served as industry-specific forecast sensitivity inputs.
Caveats apply where NMPA guideline finalization delays, human tissue supply volatility from informed consent complexity, or CRISPR-engineered cell-line substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and biotech venture funding sustainability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Preventive Medicine Market
Medical Research
Human Osteoblasts Market
Medical Research
Organoids and Spheroids Market
Medical Research
Placenta Market
Medical Research
Global Mice Model Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
US Academic Medical Centers Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Precision Medicine Market
Medical Research
Health Economics and Outcomes Research (HEOR) Services Market
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
Global Human Liver Models Market
Medical Research
FFPE Tissue Samples Market