
 Cancer Mouse Models Market | 2026-2036
Cancer Mouse Models Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Mouse Models Market Insights
Platform licensing revenue from proprietary genetically engineered backgrounds is reshaping how suppliers capture value in cancer mouse models. Charles River Laboratories leverages its global breeding infrastructure to sustain long-term supply agreements with top-20 pharmaceutical sponsors. The Jackson Laboratory anchors the academic and nonprofit segments through its extensive distribution network of JAX mice. Taconic Biosciences differentiates via specialized immunodeficient lines that command premium positioning in cell-line-derived xenograft workflows.
Cancer mouse models are living biological systems—typically immunodeficient or humanized strains—implanted with human tumor tissue or engineered with oncogenic mutations to replicate disease pathology for preclinical therapeutic evaluation. Their primary purpose is to predict human drug response, with engraftment rates and tumor growth kinetics serving as critical functional parameters for protocol validation. Genetically engineered models capture the fastest-growing segment as CRISPR knock-in capabilities expand targetable mutation portfolios. Patient-derived xenograft platforms concentrate margin pools due to their clinical correlation advantages and higher per-study pricing. Syngeneic models retain steady demand from immuno-oncology developers seeking intact murine immune contexts.
FDA guidelines on animal model qualification for drug development, combined with NIH mandates for rigor and reproducibility in preclinical research, elevate standards for model characterization and data documentation. EMA's parallel emphasis on translational validity pressures European suppliers to align phenotyping protocols across jurisdictions. Contract research organizations and pharmaceutical sponsors must monitor evolving regulatory expectations around humanized model validation as cell therapy and bispecific antibody pipelines advance.
Market Dynamics
CRISPR-based genome editing has compressed model development timelines from years to months, forcing suppliers to rebuild pricing architectures around speed-to-validity rather than breeding scale alone. Pharmaceutical sponsors now demand humanized xenograft platforms with validated engraftment kinetics before contract execution.
Growth Catalysts
- FDA Animal Rule Pathway:The FDA's regulatory framework for certain oncology biologics mandates qualified animal models, creating mandatory procurement pull from sponsors seeking accelerated approval pathways.
- Immuno-oncology Pipeline Expansion:Bispecific antibodies and cell therapies require humanized immune system contexts that only advanced xenograft platforms can provide.
- Boston-San Diego Biotech Clustering:Geographic concentration of immuno-oncology developers sustains premium pricing for patient-derived xenograft models with documented clinical correlation.
Market Restraints
- Specialized Breeding Infrastructure Concentration:Germline transmission capability for complex knock-in models concentrates among a limited supplier base, creating single-source vulnerability.
- Human Tissue Sourcing Constraints:Consent and logistics frameworks for patient-derived xenograft establishment vary by jurisdiction, limiting model availability for rare cancer subtypes.
- Validation Cost Escalation:NIH mandates for rigor and reproducibility require expanded phenotyping documentation that extends pre-study timelines without commensurate pricing recovery.
Strategic Opportunities
- Chinese Contract Research Expansion:Domestic biopharma R&D growth in China outpaces local model production capacity, creating import substitution potential for validated immunodeficient lines.
- Organoid-Xenograft Convergence:Integration of patient-derived organoid expansion with orthotopic implantation protocols enables higher-throughput screening with preserved tumor heterogeneity.
- EMA Parallel Market Access:EMA's translational validity emphasis pressures European sponsors to adopt phenotyping protocols that match US standards, opening cross-Atlantic model certification services.
Industry Challenges
- Genome Engineering Talent Scarcity:CRISPR guide design and embryonic stem cell manipulation expertise concentrates among a narrow specialist cohort, constraining model customization throughput.
- Humanized Model Validation Complexity:Immune cell reconstitution kinetics vary across human donor sources, complicating protocol standardization for cell therapy developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Mouse Models Market |
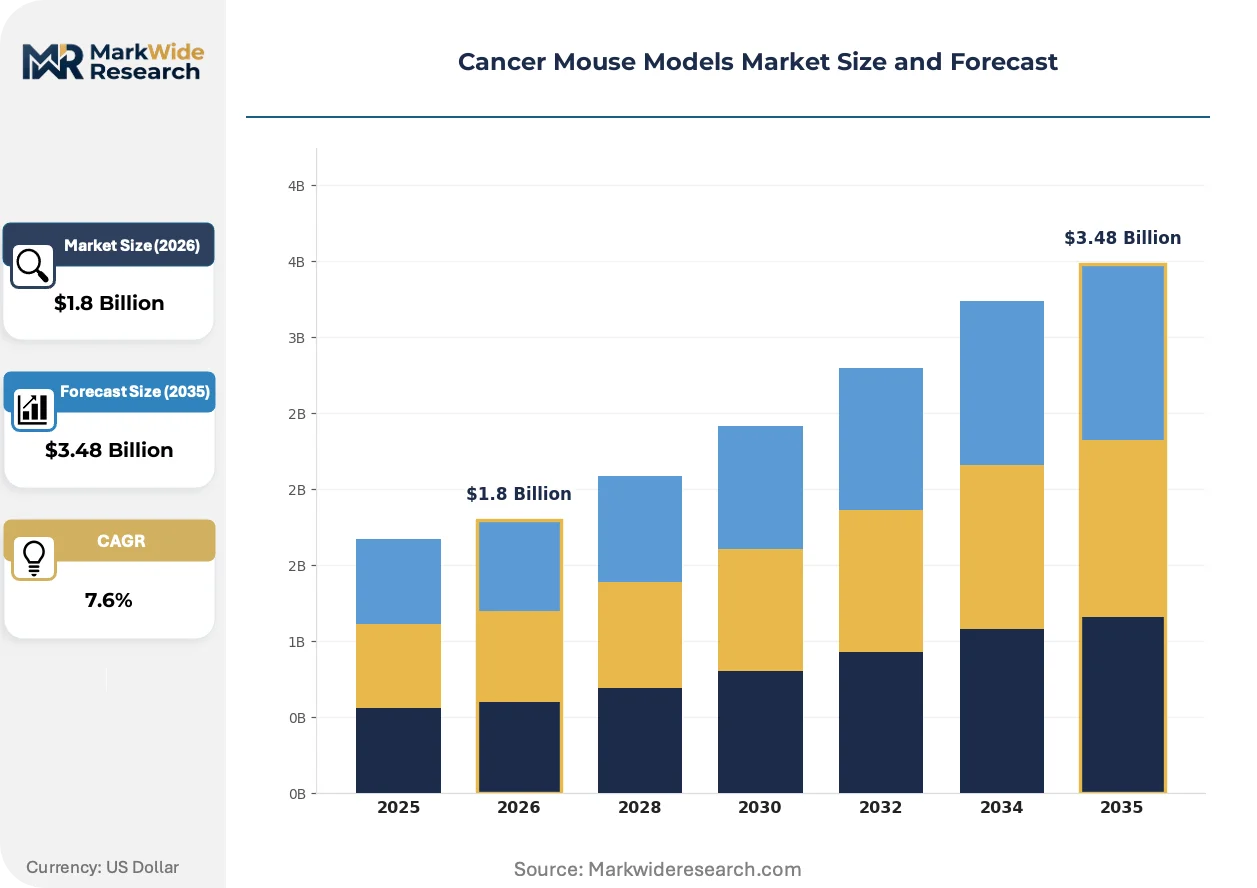
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Model Type: Xenograft, Syngeneic, Genetically Engineered, Patient-Derived Application: Drug Discovery, Toxicology Testing, Biomarker Discovery, Research Delivery Mode: Intravenous, Subcutaneous, Intraperitoneal, Oral End User: Pharmaceutical Companies, Academic Institutes, Contract Research Organizations, Biotechnology Firms |
| Companies Covered | Charles River Laboratories, The Jackson Laboratory, Taconic Biosciences, Crown Bioscience, Envigo, Inotiv, GenOway, Biocytogen Pharmaceuticals, Shanghai Model Organisms Center, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Mouse Models Market Trends and Innovations
Preclinical oncology workflows are fragmenting into specialized model tiers, with sponsors segmenting discovery, efficacy, and regulatory submission phases across distinct platform types rather than consolidating on single suppliers.
CRISPR prime editing is rendering obsolete conventional homologous recombination methods for introducing precise oncogenic point mutations into mouse germlines. Top-20 pharmaceutical sponsors now specify prime-edited knock-in capabilities in master service agreements. The technology is compressing development timelines for complex alleles that previously required embryonic stem cell targeting.
EMA's updated guidance on qualification of animal models for oncology drug development now explicitly references humanized platform validation standards. European contract research organizations must align phenotyping protocols with FDA expectations to serve multinational sponsor programs. German and Swiss biotech clusters are accelerating adoption of JAX-distributed immunodeficient backgrounds to preempt regulatory scrutiny.
Subscription-based model access agreements are displacing per-animal transactional purchasing among mid-cap biotech sponsors. Charles River Laboratories and Taconic Biosciences now structure annual minimum commitments with breeding priority guarantees. This shift concentrates procurement leverage with sponsors who can forecast pipeline demand twelve to eighteen months forward.
Cancer Mouse Models Market Segmentation
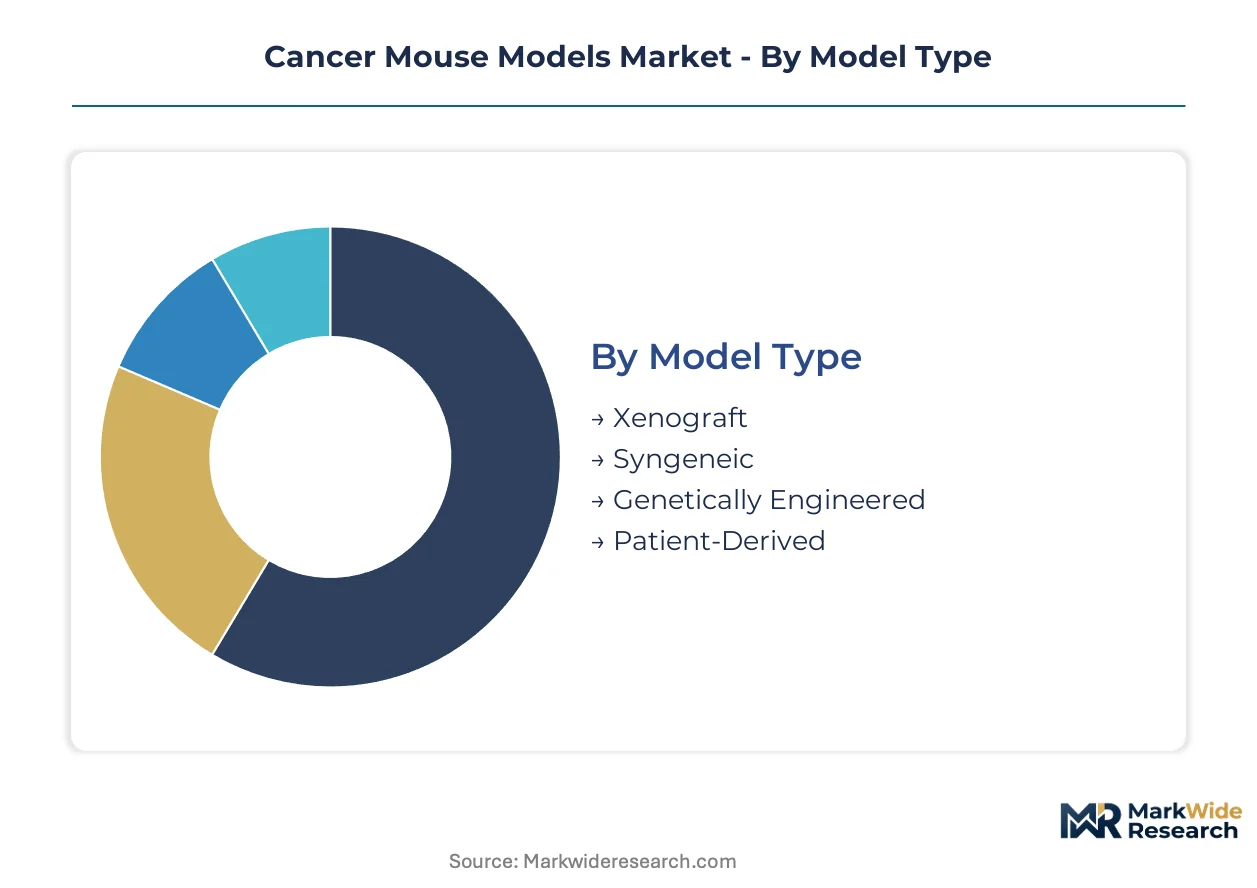
Model segmentation in cancer mouse platforms determines validation pathways, pricing tiers, and regulatory documentation requirements. Pharmaceutical sponsors now source across multiple segment categories rather than consolidating procurement, fragmenting supplier relationships.
Model Type:
Mature xenograft platforms anchor volume procurement while emerging genome engineering capabilities reshape competitive positioning.
- Patient-Derived:These models implant fresh human tumor tissue directly into immunodeficient mice, preserving stromal architecture and clonal heterogeneity. Demand concentrates among Boston and San Diego biotech clusters seeking clinical correlation for immuno-oncology assets. FDA's Animal Rule pathway elevates their validation documentation burden.
- Genetically Engineered:CRISPR knock-in and conditional activation systems enable precise oncogenic driver modeling. Pharmaceutical sponsors specify prime-edited capabilities in master service agreements, compressing development timelines from embryonic stem cell targeting. Germline transmission expertise concentrates among limited supplier bases.
- Xenograft:Cell line-derived tumor implantation into immunodeficient backgrounds remains the workhorse for high-throughput screening.
- Syngeneic:Murine tumor cell lines in immunocompetent hosts preserve intact immune contexts for checkpoint inhibitor evaluation.
Patient-derived models retain volume leadership; genetically engineered platforms hold the steepest expansion curve.
Application:
Cost tier stratification separates discovery-phase screening from regulatory submission workflows with divergent documentation standards.
- Drug Discovery:Lead optimization and target validation consume the highest model volumes, with sponsors demanding validated engraftment kinetics before contract execution. Humanized xenograft platforms command premium positioning for bispecific antibody and cell therapy pipelines.
- Biomarker Discovery:Pharmacodynamic endpoint development requires longitudinal sampling protocols and standardized histopathological scoring. NIH mandates for rigor and reproducibility elevate phenotyping documentation requirements without commensurate pricing recovery.
- Toxicology Testing:Safety pharmacology studies utilize established model lines with extensive historical control data.
- Research:Academic and nonprofit investigators prioritize JAX-distributed immunodeficient backgrounds through existing distribution networks.
Drug discovery commands procurement volume; biomarker discovery is climbing the fastest.
Delivery Mode:
Route selection hinges on tumor microenvironment requirements and therapeutic mechanism of action.
- Subcutaneous:Flank implantation enables facile tumor measurement and remains standard for efficacy screening. Charles River Laboratories and Taconic Biosciences structure annual minimum commitments with breeding priority guarantees for high-volume subcutaneous workflows.
- Intravenous:Systemic cell dissemination models metastatic progression and requires specialized imaging infrastructure. Orthotopic protocols are expanding fastest as sponsors prioritize organ-specific microenvironments.
- Intraperitoneal:Ovarian and gastric cancer modeling utilizes peritoneal cavity implantation with distinct growth kinetics.
- Oral:Gastrointestinal tract tumor modeling requires specialized surgical expertise and localized delivery systems.
Subcutaneous delivery dominates transaction volume; intravenous routes are gaining share fastest.
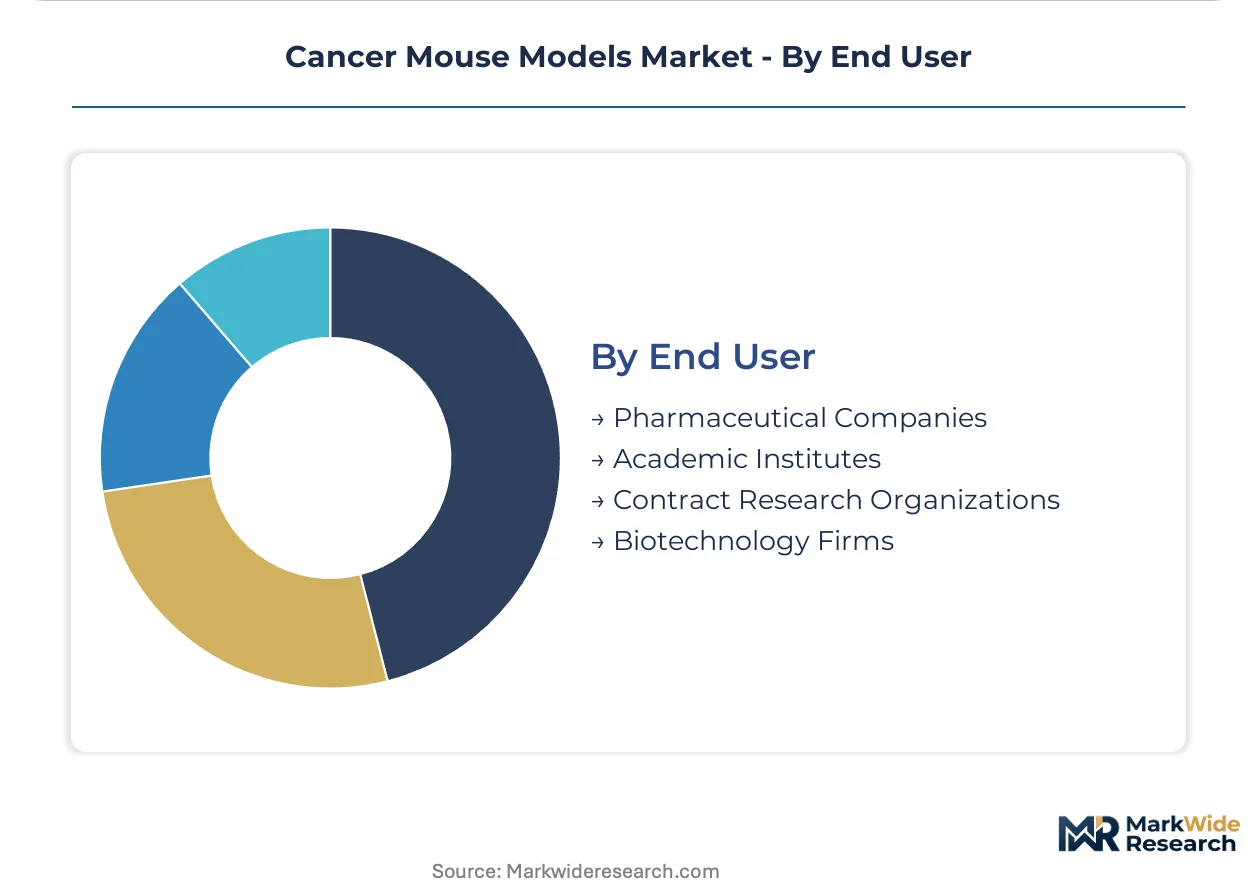
End User:
Customer type determines pricing architecture, contract structure, and technical support intensity.
- Pharmaceutical Companies:Top-20 sponsors now specify prime-edited knock-in capabilities and demand humanized platforms with validated immune cell reconstitution kinetics. Subscription-based access agreements displace per-animal purchasing with twelve-to-eighteen-month demand forecasting.
- Contract Research Organizations:Multi-site phenotyping protocol standardization pressures European CROs to align with FDA expectations for multinational sponsor programs. EMA's translational validity emphasis accelerates adoption of JAX-distributed immunodeficient backgrounds.
- Academic Institutes:NIH funding sustains demand through The Jackson Laboratory's extensive distribution network.
- Biotechnology Firms:Mid-cap sponsors concentrate procurement leverage through breeding priority guarantees.
Pharmaceutical companies retain procurement volume leadership; contract research organizations hold the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States sponsors prioritize patient-derived xenograft platforms for clinical correlation, while Chinese biopharma pursues cost-efficient genetically engineered alternatives for high-throughput screening.
United States
NIH funding and immuno-oncology pipeline density sustain premium procurement for humanized models. FDA's Animal Rule pathway mandates qualified animal models for certain oncology biologics, elevating validation documentation requirements. Boston and San Diego biotech clusters concentrate demand for patient-derived xenograft models with documented clinical correlation.
Germany
EMA's translational validity emphasis accelerates adoption of standardized phenotyping protocols. The country's national pharmaceutical regulator pressures European sponsors to align with FDA expectations for multinational programs. Heidelberg and Munich biotech clusters drive demand for JAX-distributed immunodeficient backgrounds.
China
Domestic biopharma R&D growth outpaces local model production capacity, creating import substitution pressure. NMPA guidelines on animal model qualification shape validation requirements for oncology drug development. Shanghai and Beijing biotech corridors concentrate demand for validated immunodeficient lines.
Switzerland
Swissmedic oversight elevates standards for model characterization in regulatory submission workflows. Basel's pharmaceutical hub sustains premium pricing for genetically engineered models with precise oncogenic driver mutations. The country's contract research organizations align phenotyping protocols with multinational sponsor requirements.
United Kingdom
Academic research funding through UK Research and Innovation sustains demand for JAX-distributed models. The Medicines and Healthcare products Regulatory Agency emphasizes rigor and reproducibility in preclinical documentation. London and Cambridge biotech clusters concentrate procurement for biomarker discovery workflows.
Cancer Mouse Models Market Competitive Landscape
Capability concentration sits with genome engineering specialists; scale advantage sits with global breeding infrastructure operators. The market structures around three tiers: platform licensors with proprietary genetic backgrounds, high-volume breeders with distribution networks, and regional specialists with localized immunodeficient lines. Dominant competitive moves include subscription-based access agreements displacing per-animal transactions and CRISPR prime editing capabilities reshaping master service agreement specifications.
Within the platform licensing tier, Charles River Laboratories and The Jackson Laboratory represent contrasting scale-versus-specialization archetypes. Charles River exemplifies the global breeding infrastructure operator with long-term supply agreement structures. The Jackson Laboratory anchors academic and nonprofit distribution networks. Taconic Biosciences occupies a position among specialized immunodeficient line developers serving cell-line-derived xenograft workflows.
| Leading Market Players |
|---|
| Charles River Laboratories |
| The Jackson Laboratory |
| Taconic Biosciences |
| Crown Bioscience |
| Envigo |
| Inotiv |
| GenOway |
| Biocytogen Pharmaceuticals |
| Shanghai Model Organisms Center |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency for germline transmission capability among CRISPR genome engineering specialists determines both pricing tier spreads and supply chain shape in cancer mouse models. Contract structures for patient-derived xenograft platforms concentrate premium procurement leverage with Boston and San Diego biotech clusters capable of twelve-to-eighteen-month demand forecasting.
Pricing Analysis
Long-term subscription agreements now displace per-animal transactional purchasing among mid-cap biotech sponsors. Three-tier pricing structure across prime-edited genetically engineered models, validated patient-derived xenograft platforms, and standard cell-line-derived xenografts reflects differentiation by immune cell reconstitution kinetics and clinical correlation documentation. Cost compression in cell-line-derived xenografts is intensifying because high-volume screening sponsors negotiate breeding priority guarantees. Academic institutes exhibit highest price sensitivity; top-20 pharmaceutical sponsors demonstrate lowest sensitivity due to regulatory submission requirements.
Supply Chain Analysis
Charles River Laboratories, The Jackson Laboratory, and Taconic Biosciences hold captive breeding infrastructure capacity across the United States, Germany, and China. Germline transmission expertise draws from embryonic stem cell manipulation specialists, CRISPR guide design cohorts, and immunodeficient strain repositories. Single-source vulnerability concentrates in complex knock-in model production where embryonic stem cell targeting capability rests on limited supplier bases. Distribution runs through JAX-distributed networks for academic segments and direct long-term supply agreements for pharmaceutical sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cancer mouse models market sits in a cyclical recovery phase driven by immuno-oncology pipeline expansion and FDA Animal Rule pathway maturation. CRISPR prime editing capabilities and humanized platform validation standards are compressing development timelines and reshaping competitive positioning.
For Market Incumbents: Harden germline transmission expertise retention through specialist compensation structures and embryonic stem cell capability investments. Consolidate breeding infrastructure scale advantages via subscription-based access agreements that lock twelve-to-eighteen-month demand forecasts from mid-cap biotech sponsors. CRISPR prime editing talent scarcity threatens customization throughput; vertical integration into guide design and embryonic stem cell manipulation preserves margin position.
For New Entrants and Emerging Players: Chinese contract research expansion represents the most penetrable entry point, where domestic biopharma R&D growth outpaces local model production capacity. Organoid-xenograft convergence workflows offer second white-space targeting, enabling higher-throughput screening with preserved tumor heterogeneity through patient-derived organoid expansion protocols. Go-to-market positioning should emphasize validated immunodeficient line import substitution for Shanghai and Beijing biotech corridors.
For Investors and Strategic Acquirers: The market sits at a capability consolidation phase that favors genome engineering specialists with prime-edited knock-in platforms. Long-term viability across the analysis window rests on CRISPR talent retention and humanized model validation standardization. Acquisition target archetype: regional specialists with localized immunodeficient lines and embryonic stem cell manipulation expertise. The signal to watch is EMA translational validity guidance alignment with FDA expectations, which will compress phenotyping protocol standardization timelines for European contract research organizations.
| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Prime Editing Capability Investment | Prime-edited knock-in platforms compress complex allele development timelines from embryonic stem cell targeting. |
| Humanized Model Validation Standardization | FDA Animal Rule pathway mandates qualified immune cell reconstitution kinetics for oncology biologics approval. |
| Subscription-Based Access Agreement Expansion | Annual minimum commitments with breeding priority guarantees lock procurement leverage from mid-cap biotech sponsors. |
| Organoid-Xenograft Convergence Development | Patient-derived organoid expansion with orthotopic implantation enables higher-throughput screening with preserved tumor heterogeneity. |
| Cross-Atlantic Model Certification Services | EMA translational validity emphasis pressures European sponsors to adopt phenotyping protocols matching FDA expectations. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, and laboratory animal science directors and secondary validation through FDA Animal Rule guidance documents, EMA translational validity guidance, and NIH rigor and reproducibility mandates anchors the qualitative findings. Bottom-up and top-down triangulation incorporates ClinicalTrials.gov immuno-oncology pipeline tracking, Charles River Laboratories and The Jackson Laboratory public disclosures, and contract research organization service agreement structures.
Calibration against historical model procurement volumes, engraftment rate benchmarks, and pricing tier evolution informs the analytical framework across the analysis window. Segmentation dimensions modeled include model type, application, delivery mode, and end user, with regional regulatory cluster differentiation. CAGRs were derived from sponsor pipeline density, NIH funding trajectories, and CRISPR technology adoption curves. Forecast inputs incorporate germline transmission capacity constraints and human tissue sourcing logistics frameworks.
Practitioners should monitor CRISPR guide design talent migration, FDA humanized model validation guidance updates, and Chinese NMPA animal model qualification rulemaking for early signals of forecast revision. Forecasts reflect assumptions around immuno-oncology pipeline continuity and embryonic stem cell manipulation expertise concentration. Quarterly review of sponsor master service agreement specifications and EMA phenotyping protocol alignment timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
North America Biobanks Market
Medical Research
Global Humanized Mouse Model Market
Medical Research
Malaria Vaccine Market
Medical Research
Global Mice Model Market
Medical Research
Epigenomics Market
Medical Research
Asia-Pacific Computer-Aided Drug Discovery Market
Medical Research
Forensic Medicine Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Preventive Medicine Market
Medical Research
Antibody-Mediated Rejection Prevention Market
Medical Research
Global Human Liver Models Market
Medical Research
Placenta Market
Medical Research
Epigenetics Market
Medical Research
PDX Models Market
Medical Research
Life Science R&D Infrastructure Outsourcing Market