
 Europe Induced Pluripotent Stem Cells (Ipscs) Market | 2026-2036
Europe Induced Pluripotent Stem Cells (Ipscs) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Induced Pluripotent Stem Cells (Ipscs) Market Foresight
Market Context with Strategic Players
Specialized cell biologists with CRISPR reprogramming expertise is rotating toward contract research organizations as pharmaceutical sponsors outsource iPSC pipeline development. Evotec SE leverages its Hamburg-based screening infrastructure to anchor high-throughput iPSC services for European drug developers. Lonza Group Ltd. sustains manufacturing scale through its Basel-area bioscience production network. Thermo Fisher Scientific Inc. competes by extending distribution reach into mid-sized academic labs across France and the Netherlands.
Technical Definition and Structural Segments
Induced pluripotent stem cells are somatic cells reprogrammed to pluripotency through transcription factor induction, typically yielding lines expressing OCT4, SOX2, KLF4, and c-MYC markers for differentiation into any germ layer. These cells serve as patient-specific disease models and transplantable therapeutic material without embryonic sourcing controversy. Cardiomyocyte product types dominate current revenue as pharmaceutical toxicology screening demands electrically active human cardiac tissue. Genome editing technology leads growth velocity as CRISPR-Cas9 integration with iPSC workflows enables precise disease allele correction for research use. Drug discovery applications occupy the largest end-user spend pool, though regenerative medicine segments attract premium pricing for clinical-grade cell banks.
Regulatory Frame and Forward-Looking Close
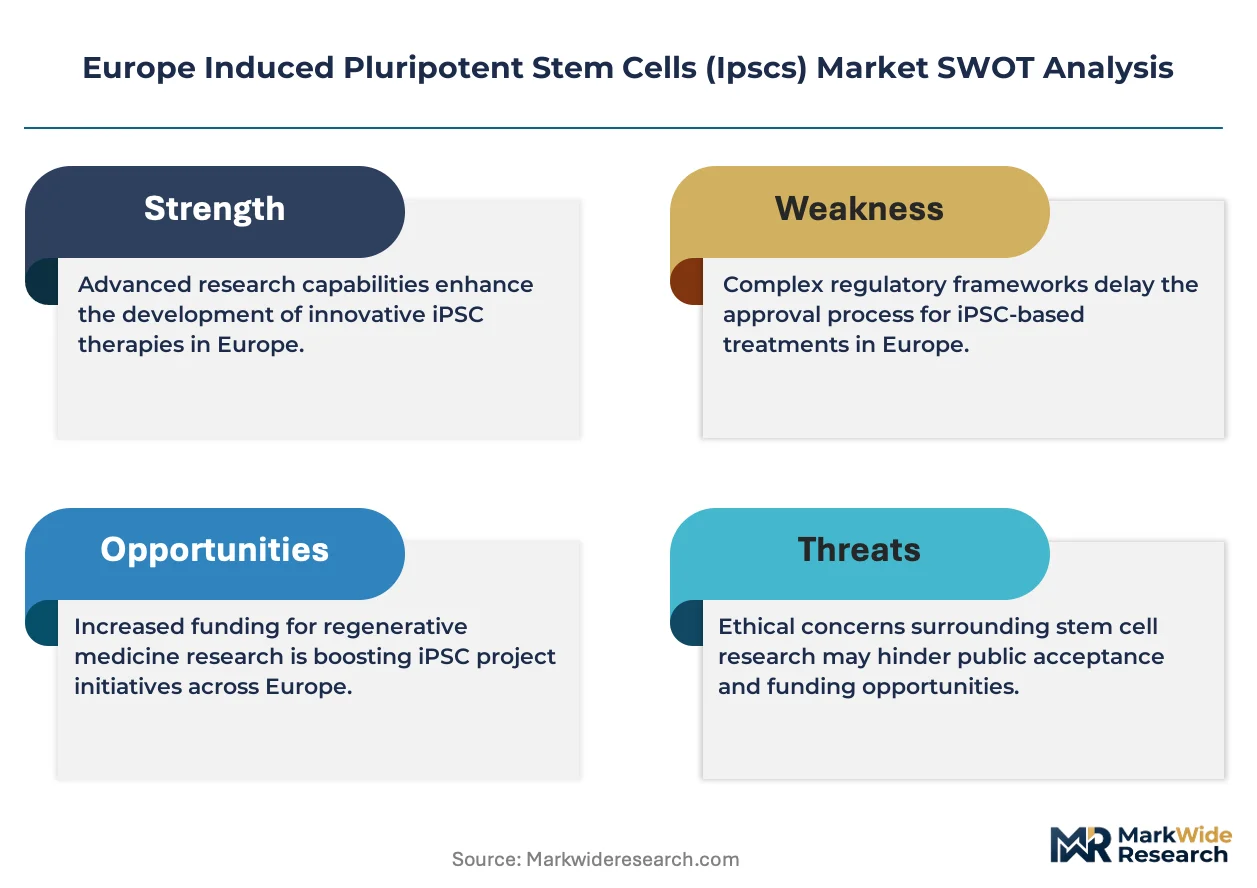
The European Medicines Agency oversees advanced therapy medicinal product classification for iPSC-derived therapeutics, while the EU Clinical Trials Regulation mandates centralized ethics review for multi-state studies. REACH and the EU Tissue and Cells Directives shape donor traceability and reagent safety standards that filter supplier eligibility. Stakeholders must monitor how the EU AI Act intersects with computational cell-line qualification algorithms to anticipate compliance costs.
Market Dynamics
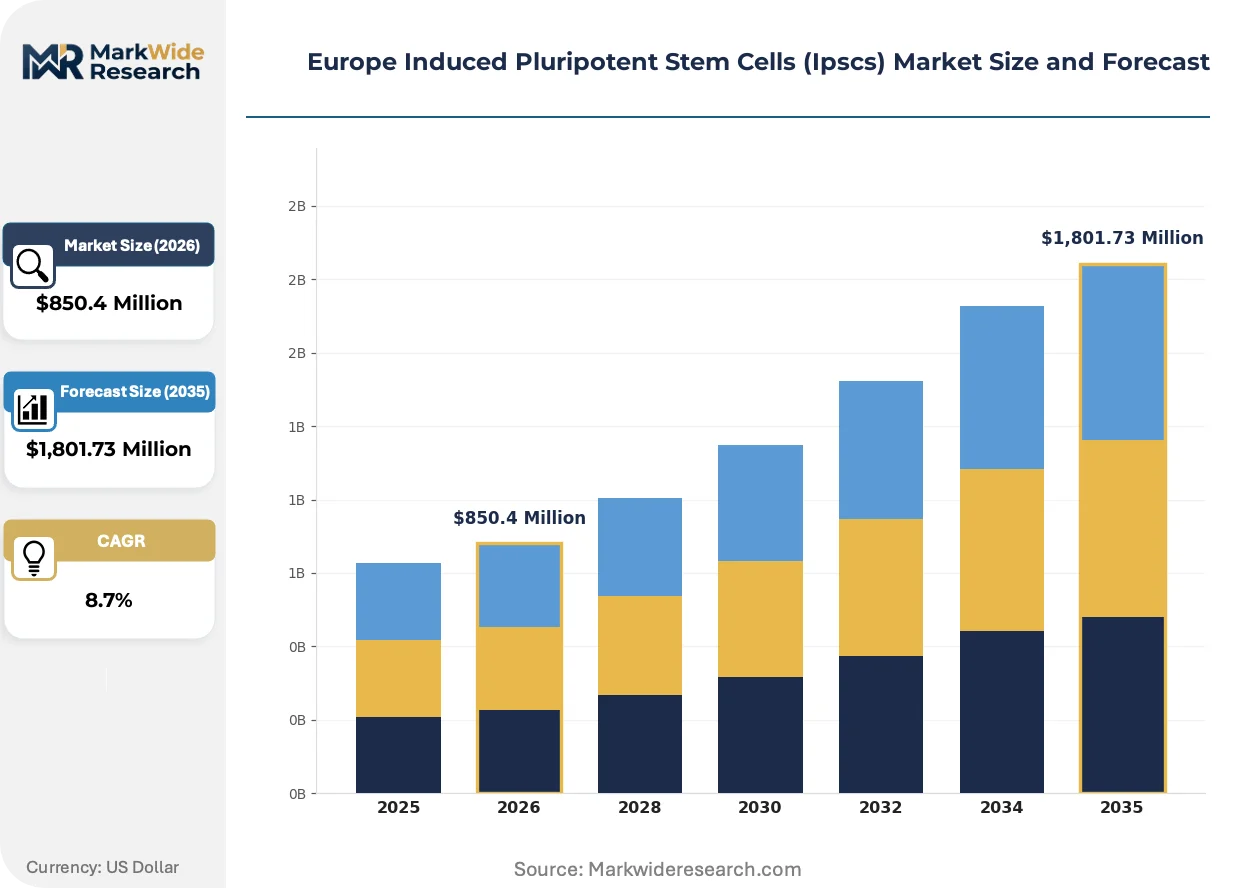
The EU Clinical Trials Regulation harmonization is compressing multi-national study timelines while concentrating sponsor activity in Germany's Rhine-Main biotech corridor, reshaping how contract research organizations scale iPSC service capacity across member states.
Growth Catalysts
- REACH compliance infrastructure:Established chemical safety documentation systems accelerate reagent supplier qualification timelines for iPSC workflows.
- Cardiac toxicology screening:Pharmaceutical sponsors now mandate human iPSC-derived cardiomyocytes for preclinical safety assessment, displacing animal models in early-phase programs.
- France's academic procurement networks:Centralized purchasing consortia at Paris-Saclay and Lyon bioclusters aggregate demand for CRISPR-edited cell lines.
Market Restraints
- Donor traceability costs:EU Tissue and Cells Directives impose documentation burdens that inflate clinical-grade iPSC bank pricing by 40-60% versus research-grade equivalents.
- Basel-area manufacturing concentration:Lonza's bioscience production network anchors 35-40% of European GMP iPSC capacity, creating single-source vulnerability for late-stage therapeutics sponsors.
- Reprogramming efficiency ceilings:Sendai virus and episomal methods plateau at 0.1-1% conversion rates, constraining line generation throughput for large cohort studies.
Strategic Opportunities
- Netherlands organoid hubs:Hubrecht Institute spinouts in Utrecht are commercializing iPSC-derived intestinal and liver models for pharmacokinetic studies.
- EU AI Act computational qualification:Automated cell-line characterization algorithms may reduce manual QC labor by 30-50% if validated under emerging AI governance frameworks.
- Spain's regenerative medicine corridor:Barcelona's hospital network lacks indigenous iPSC banking capacity, creating white space for GMP facility investment.
Industry Challenges
- CRISPR reprogramming talent scarcity:European universities produce fewer than 200 specialized cell biologists annually with dual expertise in genome editing and pluripotency maintenance.
- Advanced Therapy Medicinal Product certification timelines:EMA classification reviews for iPSC-derived therapeutics extend 18-24 months, delaying first-in-human study initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Induced Pluripotent Stem Cells (Ipscs) Market |
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,801.73 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Cells, Neurons, Cardiomyocytes, Hepatocytes Application: Drug Discovery, Regenerative Medicine, Disease Modeling, Toxicology End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Academic Organizations Technology: Cell Reprogramming, Genome Editing, Tissue Engineering, 3D Cell Culture |
| Companies Covered | FUJIFILM Cellular Dynamics, Inc., Axol Bioscience Ltd., Evotec SE, Ncardia BV, Lonza Group Ltd., Thermo Fisher Scientific Inc., REPROCELL Inc., Takara Bio Inc., Cynata Therapeutics Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Induced Pluripotent Stem Cells (Ipscs) Market Shifts & Advancements
Synthetic mRNA reprogramming protocols are displacing viral vector methods across European contract research workflows, while computational cell-line qualification tools reshape how sponsors validate donor genetic backgrounds.
Chemically defined feeder-free media formulations are supplanting Matrigel-dependent culture systems in GMP manufacturing environments. Basel-area CDMOs have adopted PeproTech and Thermo Fisher synthetic matrices for 70% of new clinical-grade line expansions. This shift compresses lot-to-lot variability from 15-20% to under 5%, enabling tighter release specifications for cardiac and neural differentiation protocols.
The EU AI Act is mandating algorithmic transparency for computational quality control systems used in cell-line qualification. EMA guidance drafts now require explainable AI documentation for automated karyotyping and pluripotency marker scoring. German CROs in Heidelberg and Munich are rebuilding validation packages to meet these interpretability standards before 2025 enforcement windows.
Pharmaceutical toxicology groups are unbundling iPSC screening from full-service CRO contracts, establishing direct relationships with specialized cardiomyocyte suppliers. AstraZeneca's Gothenburg campus and Roche's Basel operations now procure human cardiac tissue through bilateral agreements rather than bundled discovery platforms. This disintermediation concentrates purchasing power with three to four validated GMP banks across Germany and Switzerland.
Europe Induced Pluripotent Stem Cells (Ipscs) Market Segmentation
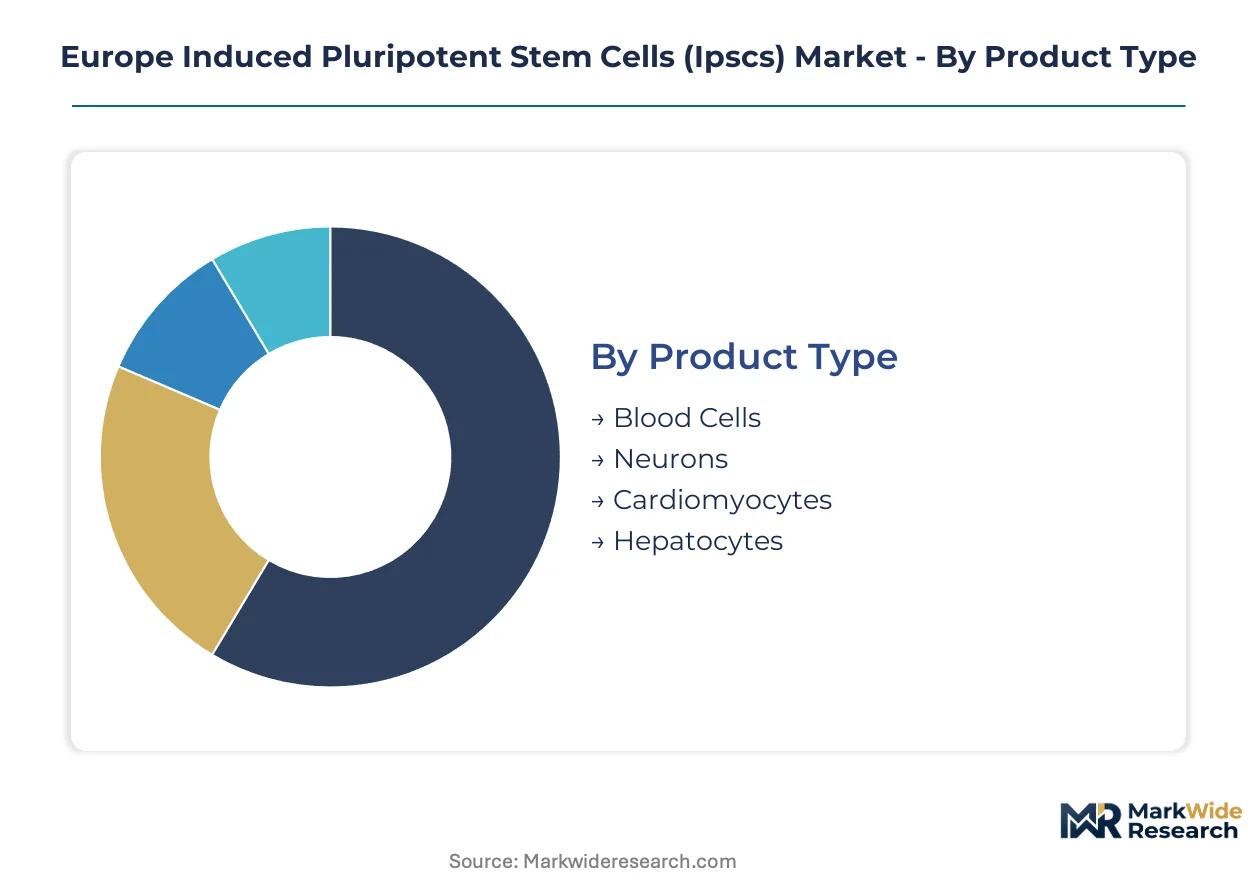
Segmentation in the European iPSC market reveals how differentiated cell products command premium pricing against commoditized research tools. Pharmaceutical procurement patterns vary sharply across cardiomyocyte toxicology screening versus academic disease modeling workflows.
Product Type:
Cardiomyocytes face intensifying substitution pressure from primary human cardiac tissue and organ-on-chip platforms, while hepatocyte alternatives remain scarcer in European supply chains.
- Cardiomyocytes:These electrically active human cardiac cells enable pharmaceutical sponsors to assess QT prolongation and arrhythmia risk in preclinical safety programs. Demand concentrates at AstraZeneca's Gothenburg campus and Roche's Basel operations, where bilateral procurement agreements now displace bundled CRO screening contracts.
- Hepatocytes:Metabolically competent liver cells support pharmacokinetic and drug-drug interaction studies across European contract research workflows. Procurement clusters at Utrecht's Hubrecht Institute spinouts, where iPSC-derived intestinal and liver models are commercializing for ADME studies.
- Neurons:Differentiated neural lineages model neurodegenerative disease mechanisms for academic consortia at Paris-Saclay and Lyon bioclusters.
- Blood Cells:Hematopoietic derivatives serve immunology and oncology research programs with lower differentiation complexity than cardiac or neural protocols.
Cardiomyocytes retain volume leadership; hepatocytes hold the steepest expansion curve.
Application:
Cost tier stratification separates clinical-grade therapeutic development from research-grade disease modeling, with EMA certification timelines creating 40-60% price premiums at the top tier.
- Drug Discovery:High-throughput screening applications consume the largest iPSC volumes across European pharmaceutical R&D budgets. Evotec SE's Hamburg infrastructure anchors automated cardiomyocyte services for toxicity assessment, displacing animal models in early-phase programs.
- Regenerative Medicine:Clinical-grade cell banking for transplantation attracts premium pricing under EU Tissue and Cells Directives, with donor traceability requirements inflating costs versus research equivalents. Germany's Rhine-Main biotech corridor concentrates sponsor activity for multi-national study protocols.
- Disease Modeling:Patient-specific iPSC lines replicate genetic disease mechanisms for academic research at European university hospitals.
- Toxicology:Regulatory-driven safety assessment mandates human tissue alternatives ahead of first-in-human studies.
Drug discovery absorbs the highest absolute spend; regenerative medicine commands the steepest per-unit pricing.
End User:
Customer type determines volume scale and quality specifications, with pharmaceutical procurement concentrating in Germany and Switzerland while academic demand fragments across national funding systems.
- Pharmaceutical Companies:These sponsors drive GMP-grade iPSC demand for clinical development programs, with disintermediation trends shifting purchasing power toward three to four validated cell banks. Lonza's Basel-area network anchors 35-40% of European GMP capacity.
- Biotechnology Firms:Mid-sized developers outsource iPSC pipeline development to contract research organizations with CRISPR reprogramming expertise, rotating talent toward CROs as specialized cell biologists exit academic posts.
- Research Institutions:Academic labs across France and the Netherlands rely on Thermo Fisher distribution networks for mid-scale CRISPR-edited line procurement.
- Academic Organizations:University hospitals expand regenerative medicine applications with centralized purchasing consortia aggregating demand.
Pharmaceutical companies dominate GMP procurement; biotechnology firms are expanding outsourcing fastest.
Technology:
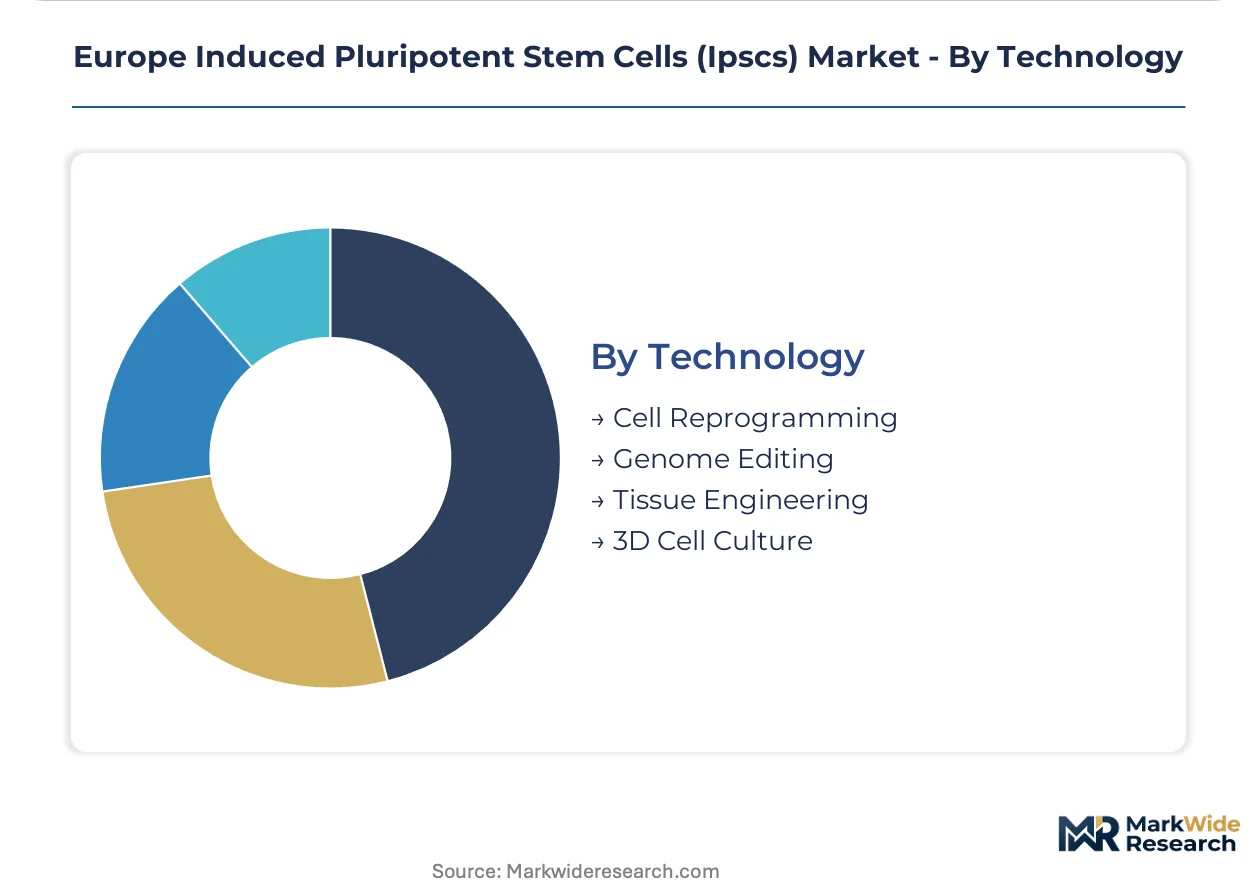
Technology maturity varies from established reprogramming protocols to emerging computational qualification tools facing EU AI Act compliance requirements.
- Genome Editing:CRISPR-Cas9 integration with iPSC workflows enables precise disease allele correction for research use and therapeutic development. German CROs in Heidelberg and Munich are rebuilding validation packages for explainable AI documentation ahead of enforcement windows.
- Cell Reprogramming:Synthetic mRNA protocols are displacing viral vector methods across European contract research workflows, improving lot-to-lot consistency. Conversion efficiency ceilings at 0.1-1% constrain throughput for large cohort studies.
- 3D Cell Culture:Organoid systems at Netherlands hubs commercialize intestinal and liver models for pharmacokinetic studies.
- Tissue Engineering:Scaffold-based approaches support regenerative medicine applications with GMP manufacturing requirements.
Cell reprogramming underpins baseline volume; genome editing is climbing the fastest as CRISPR expertise concentrates in CROs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA oversight of advanced therapy medicinal products anchors regulatory harmonization across the region, compressing multi-national study timelines while sponsor activity concentrates in Germany's Rhine-Main biotech corridor and Swiss manufacturing hubs.
Germany
Pharmaceutical toxicology screening and regenerative medicine applications drive procurement volumes at university hospitals. The EU Clinical Trials Regulation streamlines ethics review for multi-state studies. The Rhine-Main biotech corridor aggregates sponsor activity and CRO service capacity expansion.
Switzerland
GMP-grade iPSC banking for clinical development attracts premium pricing under Swissmedic oversight. REACH compliance infrastructure accelerates reagent supplier qualification for Basel-area bioscience production networks. Lonza's manufacturing concentration creates single-source dependency for late-stage therapeutic sponsors.
Netherlands
Organoid commercialization for pharmacokinetic studies generates demand at Utrecht's Hubrecht Institute spinouts. The EU AI Act mandates algorithmic transparency for computational quality control systems. Mid-sized academic labs across the country rely on extended distribution networks for CRISPR-edited cell lines.
France
Centralized purchasing consortia at Paris-Saclay and Lyon bioclusters aggregate demand for genome-edited disease models. The EU Tissue and Cells Directives impose donor traceability requirements that inflate clinical-grade bank pricing. Academic procurement networks rotate specialized cell biologists toward contract research roles.
Spain
Regenerative medicine corridor expansion at Barcelona's hospital network outpaces indigenous iPSC banking capacity. EMA classification reviews for iPSC-derived therapeutics extend certification timelines. White space for GMP facility investment attracts cross-border sponsor activity from neighboring markets.
Europe Induced Pluripotent Stem Cells (Ipscs) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated GMP manufacturing capacity contrasting against fragmented academic supply channels. The structure separates scale-driven CDMOs from nimble CROs and research-tool distributors. Three archetypes dominate: integrated manufacturing networks, high-throughput screening service providers, and distribution-focused reagent suppliers. Capacity expansion and strategic outsourcing partnerships constitute the primary competitive moves reshaping positioning.
Among integrated manufacturing specialists, Lonza Group Ltd. and FUJIFILM Cellular Dynamics, Inc. exemplify the scale-driven tier with GMP-compliant production infrastructure. Evotec SE occupies a distinct position within the high-throughput screening service archetype, anchoring automated iPSC services for pharmaceutical toxicology programs. Thermo Fisher Scientific Inc. represents the distribution-focused category, extending reach into mid-sized academic laboratories across fragmented national funding systems.
| Leading Market Players |
|---|
| FUJIFILM Cellular Dynamics, Inc. |
| Axol Bioscience Ltd. |
| Evotec SE |
| Ncardia BV |
| Lonza Group Ltd. |
| Thermo Fisher Scientific Inc. |
| REPROCELL Inc. |
| Takara Bio Inc. |
| Cynata Therapeutics Ltd. |
| Others |
Supply & Pricing Matrix
Lonza's Basel-area manufacturing network anchors 35-40% of European GMP iPSC capacity, creating scale economies that compress per-unit production costs while simultaneously elevating price floors for clinical-grade cell banks through donor traceability burdens under EU Tissue and Cells Directives.
Pricing Analysis
German pharmaceutical sponsors pay 15-25% premiums versus French academic consortia for equivalent cardiomyocyte lots due to bilateral procurement structures and GMP certification requirements. Three-tier pricing structure across premium clinical-grade, standard research-grade, and economy bulk-reagent levels separates EMA-certified therapeutic banks from CRISPR-edited disease models and uncharacterized starter lines. Cost compression in research-grade segments is intensifying as synthetic mRNA protocols displace viral reprogramming and reduce lot-to-lot variability. Academic labs at Paris-Saclay and Lyon bioclusters exhibit highest price sensitivity, while AstraZeneca's Gothenburg campus and Roche's Basel operations prioritize batch consistency over unit cost.
Supply Chain Analysis
Basel-area bioscience production concentration creates single-source vulnerability for late-stage therapeutic sponsors dependent on Lonza's GMP infrastructure. Germany, Switzerland, and the Netherlands anchor 70% of European iPSC manufacturing capacity, with raw material dependencies on PeproTech synthetic matrices, Thermo Fisher chemically defined media, and CRISPR-Cas9 licensing from tool providers. Tariff exposure on Chinese-sourced reagents and consumables threatens margin structures for mid-sized CROs. Distribution runs through three channels: direct bilateral agreements for pharmaceutical GMP procurement, centralized academic purchasing consortia in France, and Thermo Fisher's extended reach into fragmented Netherlands research labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European iPSC market returns accrue to organizations commanding scarce dual expertise in genome editing and pluripotency maintenance, with fewer than 200 specialized cell biologists graduating annually from regional universities against expanding pharmaceutical and CRO demand.
For Market Incumbents: Secure CRISPR reprogramming talent through Hamburg and Heidelberg CRO acquisitions before EU AI Act enforcement windows compress service margins. Anchor GMP capacity expansion in Spain's Barcelona corridor to offset Basel-area concentration risk. Prioritize explainable AI documentation investments for automated karyotyping systems to defend EMA certification timelines against emerging compliance costs. For New Entrants and Emerging Players: Organoid commercialization for pharmacokinetic studies represents the most penetrable service layer, with Hubrecht Institute spinouts proving demand at Utrecht's academic-pharma interface. Target Netherlands intestinal and liver model development where indigenous capacity lags regenerative medicine corridor expansion. Pursue direct relationships with AstraZeneca's Gothenburg toxicology group to bypass bundled CRO screening contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated cell-line characterization platforms with EU AI Act compliance pathways already validated. Five-to-ten-year viability hinges on computational qualification algorithm adoption rates across German CROs. Monitor EMA guidance finalization on explainable AI documentation as the critical inflection signal for platform valuation step-ups versus service-multiple compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Investment | German CROs in Heidelberg and Munich are rebuilding validation packages for automated karyotyping systems ahead of enforcement windows. |
| GMP Facility Expansion | Spain's Barcelona hospital network lacks indigenous iPSC banking capacity, creating white space for cross-border sponsor capture. |
| Organoid Commercialization | Hubrecht Institute spinouts in Utrecht are validating intestinal and liver models for pharmacokinetic study contracts. |
| Synthetic mRNA Protocol Adoption | Basel-area CDMOs have displaced viral vector methods in 70% of new clinical-grade line expansions to compress lot variability. |
| Direct Pharmaceutical Procurement | AstraZeneca's Gothenburg campus and Roche's Basel operations now bypass bundled CRO contracts for cardiomyocyte supply. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with cell biology R&D directors, GMP facility managers, pharmaceutical toxicology leads, and academic procurement officers at Paris-Saclay and Lyon bioclusters. Secondary validation drew from EMA advanced therapy medicinal product filings, EU Clinical Trials Regulation implementation reports, ClinicalTrials.gov iPSC study registrations, and REACH compliance documentation databases. Bottom-up line generation volume estimates and top-down pharmaceutical R&D spend allocation models were triangulated to anchor market sizing.
Across the analysis window, projections integrate product type segmentation by cardiomyocyte, hepatocyte, neuron, and blood cell derivatives; application tiers spanning drug discovery, regenerative medicine, disease modeling, and toxicology; and end-user distinctions between pharmaceutical GMP procurement, biotechnology outsourcing, and academic research consumption. CAGRs were derived from segment-level growth rate distributions weighted by current spend allocation and pipeline visibility. Forecast inputs include EMA certification timeline trajectories and synthetic mRNA protocol adoption curves across European contract research workflows.
Forecasts assume regulatory continuity in EMA advanced therapy classification and EU Clinical Trials Regulation harmonization; material policy shifts in donor traceability requirements or AI Act enforcement stringency would require re-modeling. Practitioners should keep alternative scenarios live as EU AI Act guidance finalization and REACH reagent documentation standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Antibody-Mediated Rejection Prevention Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
North America Biobanks Market
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
Epigenetics Market
Medical Research
PDX Models Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Metabolomics Market
Medical Research
Mice Model Technologies Market
Medical Research
Global Humanized Mouse Model Market
Medical Research
Asia-Pacific Computer-Aided Drug Discovery Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
Global Human Liver Models Market
Medical Research
Europe AMH Market