
 Global Bile Duct Cancer Market | 2026-2036
Global Bile Duct Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bile Duct Cancer Market Foresight
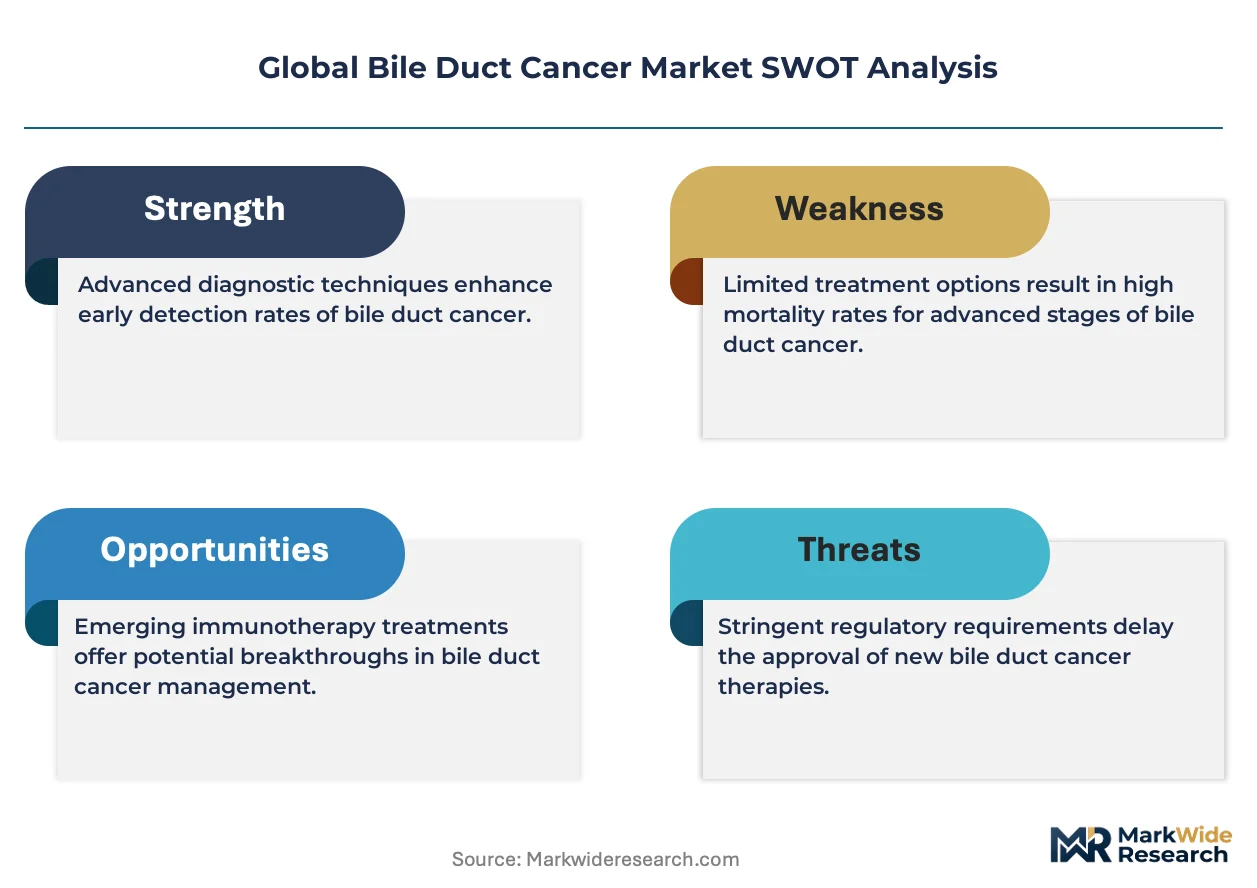
Oncology fellowship training shortages in hepatobiliary subspecialties is unwinding treatment capacity at major academic centers. Merck & Co. leverages its PD-1 franchise to compete in frontline cholangiocarcinoma combinations. Eli Lilly anchors its position through targeted agent development in FGFR-altered subsets. Bristol-Myers Squibb navigates competitive IO combinations with dual checkpoint strategies.
Bile duct cancer, or cholangiocarcinoma, comprises malignant epithelial tumors arising from biliary tract epithelium with histopathologic subtypes including intrahepatic, perihilar, and distal classifications based on anatomic origin relative to the liver hilum. The disease requires multidisciplinary management involving surgical resection, systemic therapy, and locoregional approaches depending on staging and molecular profiling. Targeted therapy segments command premium positioning where FGFR2 fusions and IDH1 mutations define addressable biomarker subsets. Immunotherapy represents the fastest-expanding modality as PD-1/PD-L1 inhibitors secure approvals across lines of therapy. Chemotherapy maintains volume leadership as the backbone of first-line standards despite erosion from novel combinations.
The FDA accelerates review timelines through breakthrough therapy and orphan drug designations for cholangiocarcinoma indications. EMA parallel scientific advice programs coordinate multinational trial designs across European member states. Japan's PMDA implements sakigake designation pathways that compress review periods for serious oncology conditions. Stakeholders must monitor biomarker-driven label expansions and companion diagnostic co-development requirements as the competitive landscape fragments across molecularly defined subsets.
Market Dynamics
FDA's accelerated approval pathway for orphan oncology indications is compressing clinical trial timelines and fragmenting commercialization strategies across molecularly defined patient subsets. This regulatory velocity is forcing developers to front-load biomarker infrastructure investment before pivotal studies commence.
Growth Catalysts
- Breakthrough Therapy Designation:FDA's expedited review mechanism compresses development timelines for cholangiocarcinoma candidates, attracting venture capital into previously deprioritized indications.
- FGFR2 Fusion Testing:Expanded adoption of next-generation sequencing in hepatobiliary oncology centers creates addressable patient populations for targeted therapy segments.
- Japan:PMDA's sakigake designation pathway accelerates market access for serious oncology conditions, drawing multinational trial investment into East Asian patient recruitment.
Market Restraints
- Companion Diagnostic Co-development Costs:Parallel validation of biomarker assays alongside therapeutic candidates doubles program expenditure and extends regulatory timelines.
- Hepatobiliary Surgical Volume Concentration:Resection capability clusters at academic medical centers in the United States, Germany, and Japan, limiting addressable patient pools elsewhere.
- IDH1 Inhibitor Substitution:Oral targeted agents erode chemotherapy backbone utilization in second-line settings, compressing revenue per treated patient.
Strategic Opportunities
- Perioperative Immunotherapy:Neoadjuvant PD-1 combinations in resectable disease represent unlabeled territory with potential to expand eligible surgical populations.
- Liquid Biopsy Adoption:Circulating tumor DNA monitoring enables real-time resistance surveillance, creating service revenue streams beyond drug sales.
- EMA Parallel Scientific Advice:Coordinated multinational trial designs reduce redundant regulatory submissions across European member states.
Industry Challenges
- Hepatobiliary Fellowship Shortages:Subspecialty training pipeline gaps constrain treatment capacity at major academic centers, creating patient access bottlenecks.
- Cross-Platform Biomarker Harmonization:Discordant FGFR2 fusion detection between tissue-based and liquid biopsy platforms complicates patient selection for clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bile Duct Cancer Market |
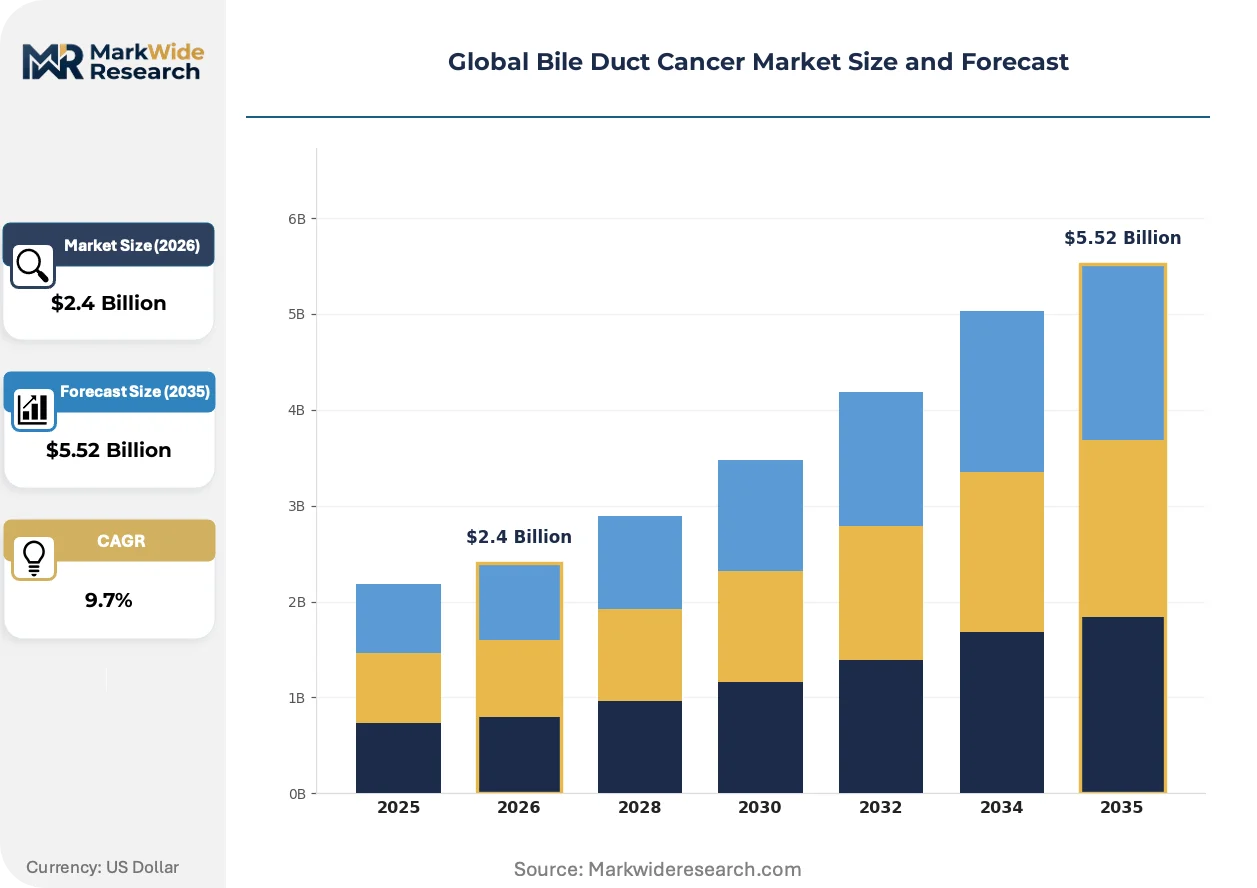
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiation Therapy, Supportive Care Therapy Area: Intrahepatic, Perihilar, Distal, Extrahepatic End User: Oncology Centers, Specialty Clinics, Research Institutes, Diagnostic Laboratories Delivery Mode: Intravenous, Oral, Injectable, Implantable |
| Companies Covered | Merck & Co., Inc., Eli Lilly and Company, Pfizer Inc., Incyte Corporation, Taiho Pharmaceutical, F. Hoffmann-La Roche Ltd, AstraZeneca PLC, Eisai Co., Ltd., Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bile Duct Cancer Market Shifts & Advancements
Biomarker-driven trial design is fragmenting development programs into molecularly homogeneous cohorts, compressing traditional histology-based enrollment models. This precision pivot demands parallel investment in diagnostic infrastructure and therapeutic pipelines.
Next-generation sequencing panels are decomposing the monolithic cholangiocarcinoma diagnosis into actionable molecular subtypes. Oncology centers in the United States and Japan are adopting comprehensive genomic profiling as standard-of-care for all newly diagnosed patients. This molecular decomposition is enabling basket trial enrollment and compressing time-to-treatment initiation for biomarker-matched therapies.
EMA's orphan drug designation framework is reshaping European market access negotiations for cholangiocarcinoma indications. The designation triggers protocol assistance and fee waivers that offset development costs for rare oncology subsets. Manufacturers are responding by prioritizing centralized EU regulatory submissions over fragmented national pathways.
Academic medical centers are unbundling multidisciplinary tumor board services from institutional chemotherapy administration. Community oncology practices in Germany and select United States regions are purchasing remote hepatobiliary consultation to retain patients locally. This service disintermediation is visible most acutely in regions lacking proximate academic surgical volumes.
Global Bile Duct Cancer Market Segmentation
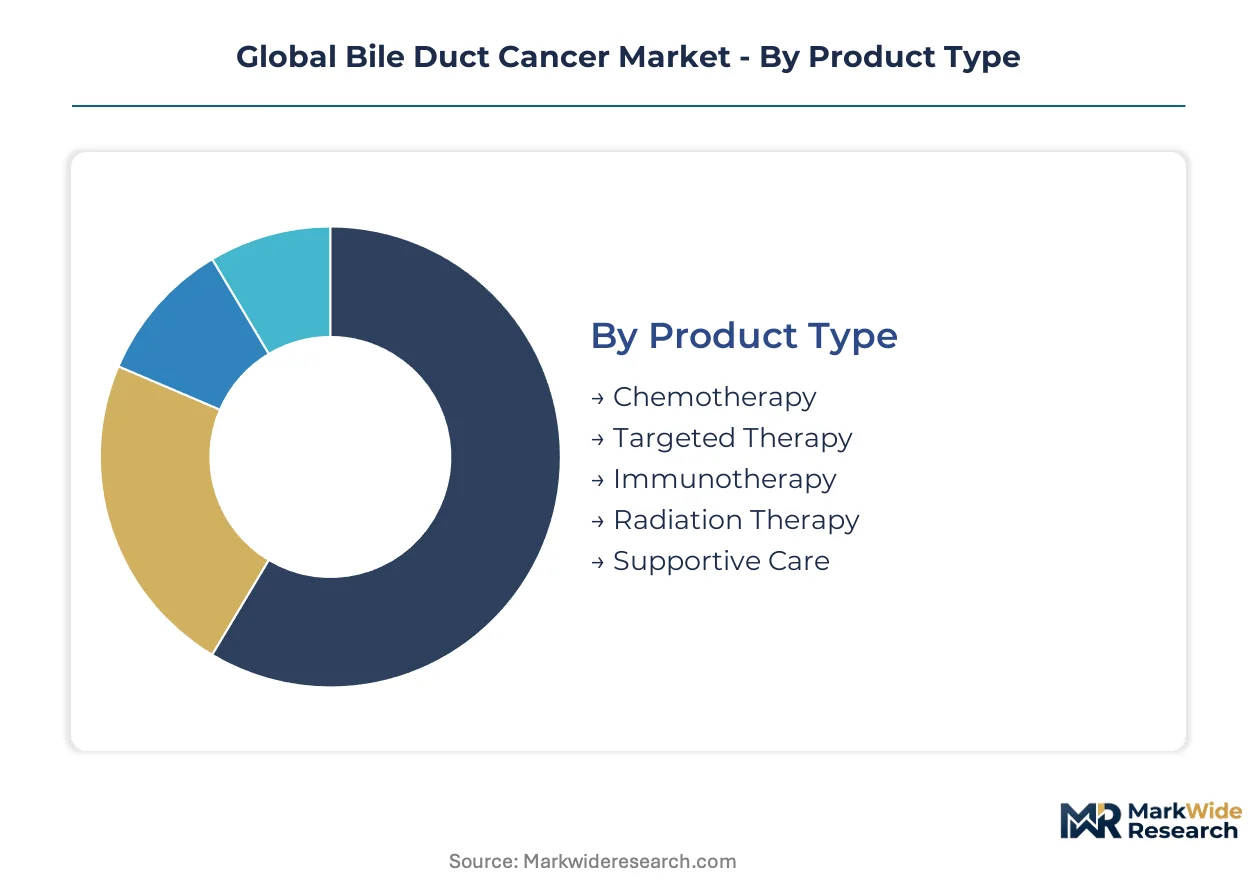
Cholangiocarcinoma treatment protocols fragment across molecular subtypes, surgical resectability, and line of therapy, creating distinct margin pools that reward biomarker-matched positioning. Segmentation clarity determines whether developers capture premium pricing in targeted subsets or compete for volume in chemotherapy backbones.
Product Type:
Margin concentration tilts toward agents with companion diagnostic requirements and accelerated regulatory pathways, where pricing power reflects biomarker exclusivity rather than commodity substitution.
- Chemotherapy:Gemcitabine-cisplatin combinations constitute the first-line standard of care across all anatomical subtypes. Demand concentrates in community oncology practices in the United States and Germany, where infusion infrastructure supports high patient throughput despite erosion from novel combinations.
- Targeted Therapy:FGFR2 inhibitors and IDH1 antagonists command reimbursement premiums in biomarker-selected populations. Academic medical centers in Japan and the United States drive adoption where next-generation sequencing penetration enables patient identification.
- Immunotherapy:PD-1/PD-L1 inhibitors are expanding across lines of therapy with checkpoint blockade combinations under investigation.
- Radiation Therapy:External beam and stereotactic body approaches address locally advanced unresectable disease.
- Supportive Care:Biliary drainage and palliative interventions manage complications of obstructive presentations.
Chemotherapy holds installed capacity across first-line settings. Immunotherapy is rotating up the share rankings through label expansions and combination development.
Therapy Area:
Volume distribution tracks anatomical complexity and surgical candidacy, with resectable intrahepatic cases offering curative intent margins versus palliative approaches in advanced presentations.
- Intrahepatic:Arising from bile ducts within the liver parenchyma, this subtype demonstrates rising incidence in Western populations and carries the highest FGFR2 fusion prevalence. Hepatobiliary surgical programs at Mayo Clinic and Memorial Sloan Kettering anchor resection volumes in the United States.
- Perihilar:Klatskin tumors at the hepatic hilum require complex biliary reconstruction and vascular management. German university hospitals concentrate expertise where extended hepatectomy with portal vein resection achieves curative outcomes.
- Distal:Extrahepatic tumors below the cystic duct junction often present with obstructive jaundice and pancreatobiliary involvement.
- Extrahepatic:Encompassing perihilar and distal subtypes, this grouping reflects traditional anatomical classification systems.
Intrahepatic holds installed capacity with expanding biomarker-addressable populations. Perihilar is rotating up the share rankings through neoadjuvant protocol development.
End User:
Service intensity and reimbursement sophistication determine customer segmentation, with academic centers capturing complex resections and community sites retaining stable chemotherapy administration.
- Oncology Centers:Comprehensive cancer centers coordinate multidisciplinary care including surgical oncology, medical oncology, and interventional radiology. Major institutions in Japan and Germany integrate genomic profiling into standard diagnostic workups.
- Specialty Clinics:Hepatobiliary-focused practices concentrate in metropolitan areas with transplant infrastructure.
- Research Institutes:Academic medical centers conduct biomarker-driven trials and early-phase combination studies.
- Diagnostic Laboratories:Reference labs perform companion diagnostic testing for FGFR2 fusion and IDH1 mutation status.
Oncology centers hold installed capacity with integrated care coordination. Diagnostic laboratories are rotating up the share rankings through liquid biopsy service expansion.
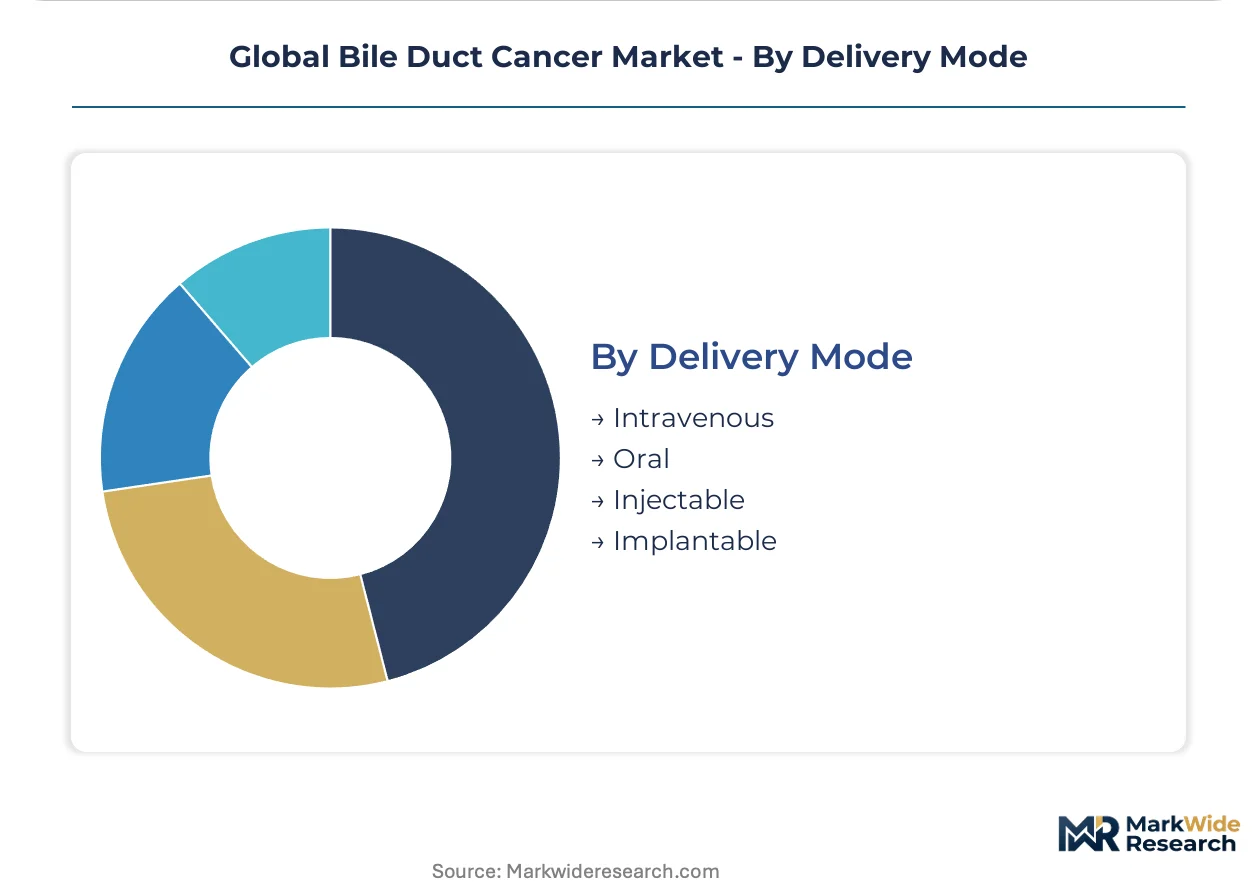
Delivery Mode:
Administration infrastructure requirements shape competitive dynamics, with oral agents enabling community dispersion versus infusion-dependent therapies concentrating at academic hubs.
- Intravenous:Cytotoxic chemotherapy and monoclonal antibodies require infusion center capacity and nursing supervision. United States oncology practices maintain extensive ambulatory infusion networks.
- Oral:Targeted small molecules including FGFR and IDH1 inhibitors enable home administration and expand addressable geography beyond academic centers.
- Injectable:Subcutaneous and intramuscular formulations support specific immunotherapy and supportive care agents.
- Implantable:Hepatic arterial infusion pumps and biliary stents address locoregional drug delivery and palliative drainage.
Intravenous holds installed capacity across cytotoxic backbone regimens. Oral delivery is rotating up the share rankings through targeted agent development and patient convenience preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's accelerated approval pathway anchors the United States as the dominant geography, while Japan's PMDA and Germany's academic medical centers concentrate specialized treatment capacity. These three markets drive biomarker testing adoption and surgical volume for cholangiocarcinoma management.
United States
Comprehensive genomic profiling at Mayo Clinic and Memorial Sloan Kettering identifies FGFR2 fusion and IDH1 mutation subsets. FDA breakthrough therapy designations compress development timelines for orphan oncology indications. The Southeast and Midwest regions expand community oncology access through telemedicine-linked tumor boards.
Japan
PMDA's sakigake designation accelerates review for serious oncology conditions, drawing multinational trial investment. National Health Insurance reimbursement for next-generation sequencing enables standardized molecular profiling. Tokyo and Osaka academic centers concentrate hepatobiliary surgical expertise and biomarker-driven enrollment.
Germany
EMA parallel scientific advice coordinates multinational protocols across European member states. University hospitals in Munich and Hamburg perform complex perihilar resections with portal vein reconstruction. The country's reference laboratory network validates companion diagnostics for FGFR2 fusion detection.
United Kingdom
NICE technology appraisals determine reimbursement for targeted agents in biomarker-selected populations. The Royal Marsden and Christie NHS Foundation Trusts anchor clinical trial enrollment in Greater London and Manchester. NHS England's genomic medicine service expands molecular testing access beyond academic centers.
Switzerland
Swissmedic's streamlined orphan drug reviews attract European headquarters for specialty oncology developers. Basel and Zurich host concentrated pharmaceutical R&D operations. The country's proximity to German and French clinical networks facilitates cross-border patient recruitment for pivotal studies.
Global Bile Duct Cancer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the cholangiocarcinoma therapeutic space. Large-cap pharmaceutical companies with established oncology franchises control frontline immunotherapy and targeted agent portfolios. Mid-scale biotechnology firms concentrate on biomarker-defined subsets and novel mechanism combinations. Competitive dynamics center on companion diagnostic co-development partnerships and accelerated regulatory pathway navigation.
Within the integrated pharmaceutical tier, Merck & Co., Inc. and Bristol-Myers Squibb Company occupy positions shaped by checkpoint inhibitor franchise extension into hepatobiliary indications. Eli Lilly and Company represents targeted therapy development focus through FGFR-altered subset addressing. These three entities exemplify divergent strategic archetypes: immunotherapy platform leverage, dual checkpoint combination exploration, and precision oncology portfolio construction.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Eli Lilly and Company |
| Pfizer Inc. |
| Incyte Corporation |
| Taiho Pharmaceutical |
| F. Hoffmann-La Roche Ltd |
| AstraZeneca PLC |
| Eisai Co., Ltd. |
| Bristol-Myers Squibb Company |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between oncology biopharma developers and specialized API manufacturers lock in supply access for FGFR2 inhibitor programs while anchoring price visibility across multi-year development cycles. These contracts concentrate procurement leverage among holders of FDA breakthrough therapy designations, compressing spot-market participation for orphan oncology inputs.
Pricing Analysis
Geographic price spreads widen between United States academic medical centers and community oncology practices in Germany and Japan, reflecting reimbursement divergence across single-payer and multi-payer systems. Three-tier pricing structure across premium, standard, and economy levels segments by biomarker exclusivity and companion diagnostic bundling, with FGFR2 fusion-matched therapies commanding premium positioning. Pricing pressure stems from IDH1 inhibitor substitution eroding chemotherapy backbone utilization. Community oncology practices exhibit highest price sensitivity; integrated cancer centers show lowest due to bundled service margins.
Supply Chain Analysis
Inventory lead times for hepatobiliary surgical consumables stretch across United States, German, and Japanese distribution networks, reflecting concentration of specialized resection programs. Active pharmaceutical ingredient synthesis draws from Switzerland, India, and United States contract manufacturing organizations. Supply chain risk centers on single-source vulnerability for FGFR2 companion diagnostic reagents. Distribution runs through academic medical center procurement consortia and regional oncology GPOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oncology center consolidation into multi-hospital systems concentrates formulary decision-making power, shifting procurement leverage toward integrated delivery networks and away from standalone academic institutions.
For Market Incumbents: Consolidate biomarker diagnostic infrastructure through captive laboratory partnerships or in-house NGS platform deployment to defend against substitution from oral targeted agents. Lock in hepatobiliary surgical capacity via exclusive affiliation agreements with Mayo Clinic and Memorial Sloan Kettering-tier institutions. Priority lever: backward integration into liquid biopsy development. For New Entrants and Emerging Players: Differentiate on perioperative immunotherapy protocols in resectable intrahepatic cholangiocarcinoma, the least penetrated segment with no established neoadjuvant standard. Target Southeast and Midwest United States community oncology practices via telemedicine-linked tumor board services. Go-to-market angle: remote hepatobiliary consultation subscriptions. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale biotechnology firms with Phase II-ready FGFR2 programs and existing companion diagnostic partnerships, positioned for FDA accelerated approval pathway navigation. Long-term viability hinges on molecular subset fragmentation sustaining premium pricing. Signal to watch: PMDA sakigake designation awards as East Asian trial investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-development | FDA parallel review of therapeutic and assay compresses regulatory timelines for FGFR2 fusion programs. |
| Perioperative Immunotherapy Protocol Development | Neoadjuvant PD-1 combinations in resectable disease expand eligible surgical populations at major academic centers. |
| Liquid Biopsy Service Expansion | Circulating tumor DNA monitoring enables real-time resistance surveillance beyond drug revenue streams. |
| EMA Parallel Scientific Advice Engagement | Coordinated multinational trial designs reduce redundant submissions across European member states. |
| Hepatobiliary Fellowship Pipeline Investment | Subspecialty training expansion addresses treatment capacity bottlenecks at concentrated academic centers. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation. Sources included FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market sizing across the analysis window.
Variance decomposition separated volume, price, and mix effects across therapy area, product type, and line of therapy segmentation dimensions. CAGRs were derived from modeled patient incidence flows, treatment rate assumptions, and pricing trajectory inputs. Forecast sensitivity incorporated biomarker testing penetration curves and regulatory approval probability weightings.
Material uncertainties — regulatory rejection of accelerated approval submissions, biomarker platform discordance, and hepatobiliary surgical capacity constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from clinical trial readouts and reimbursement determinations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Necrotizing Fasciitis Treatment Market