
 Epigenomics Market | 2026-2036
Epigenomics Market Size, Share, and Industry Trends Forecast 2026-2036
Epigenomics Market Intelligence
The direct-to-researcher sales channel for reagents and kits is rewriting competitive dynamics in the epigenomics field, favoring companies with strong e-commerce platforms. Illumina leverages its dominant position in sequencing hardware to drive consumable sales. Thermo Fisher Scientific competes through its broad portfolio of life sciences products and global distribution reach. Qiagen specializes in sample and assay technologies, offering integrated workflows for academic and biotech clients.
Epigenomics is the study of heritable changes in gene expression that do not involve alterations to the underlying DNA sequence. These modifications, including DNA methylation and histone acetylation, regulate how genes are turned on or off in response to environmental factors. DNA Methylation Kits and other reagent-based products constitute a significant portion of sales, driven by their routine use in experiments. Within technology, Next-Generation Sequencing represents the fastest-growing segment, displacing older microarray methods for comprehensive analysis.
Regulatory frameworks from the U.S. FDA and Europe's EMA heavily influence the commercialization path for epigenetic-based diagnostics and therapeutics. In China, the NMPA's evolving guidelines for companion diagnostics are shaping market access strategies for precision oncology products. The key decision for instrument and reagent suppliers is how to balance support for open research platforms versus developing proprietary, clinically validated systems.
Market Dynamics
The epigenomics market's structure is being reshaped by the rapid maturation of Next-Generation Sequencing technologies. This technological shift is democratizing high-throughput analysis, moving it from specialized core facilities into standard research and clinical development workflows, altering both cost structures and competitive dynamics.
Growth Catalysts
- Precision Oncology Demand:The expansion of precision oncology is creating sustained demand for epigenetic analysis, particularly DNA methylation and histone modification profiling, to identify novel drug targets and patient stratification biomarkers.
- Government Research Funding:National-level initiatives, such as those funded by the NIH in the United States, provide substantial, non-dilutive capital for basic and translational epigenomics research, supporting instrument and consumable purchasing.
- NGS Technology Advancement:Continuous improvements in Next-Generation Sequencing platforms are increasing throughput and decreasing costs, making comprehensive epigenome-wide association studies more accessible to a broader range of academic and biotech laboratories.
Market Restraints
- High Instrument Costs:The significant capital outlay required for high-throughput sequencing instruments and associated infrastructure remains a substantial barrier to entry for smaller academic labs and biotech startups.
- Bioinformatics Bottleneck:Analyzing and interpreting the vast datasets generated by epigenomic studies requires specialized computational skills and infrastructure, creating a significant bottleneck that can limit research productivity.
- Reimbursement Uncertainty:Ambiguous or non-existent reimbursement pathways for epigenetic-based diagnostics in many healthcare systems, including those in parts of Europe, deter investment in clinical test development.
Strategic Opportunities
- Non-Oncology Applications:Expanding research into the epigenetic basis of neurodegenerative diseases, autoimmune disorders, and metabolic conditions presents a significant opportunity for market diversification beyond cancer.
- Liquid Biopsy Integration:Developing and validating epigenetic markers, such as cell-free DNA methylation patterns, for use in non-invasive liquid biopsies offers a major growth avenue in early disease detection and monitoring.
- Multi-Omics Analysis Platforms:There is a growing opportunity for tools and software that integrate epigenetic data with genomics, transcriptomics, and proteomics to provide a more holistic view of cellular function and disease pathology.
Industry Challenges
- Data Standardization:A lack of universally accepted standards for data generation, analysis, and reporting across different platforms and laboratories hinders the comparability and reproducibility of research findings.
- Skilled Personnel Shortage:The field faces a persistent shortage of trained bioinformaticians and data scientists who possess the dual expertise in biology and computational analysis required to interpret complex epigenetic data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epigenomics Market |
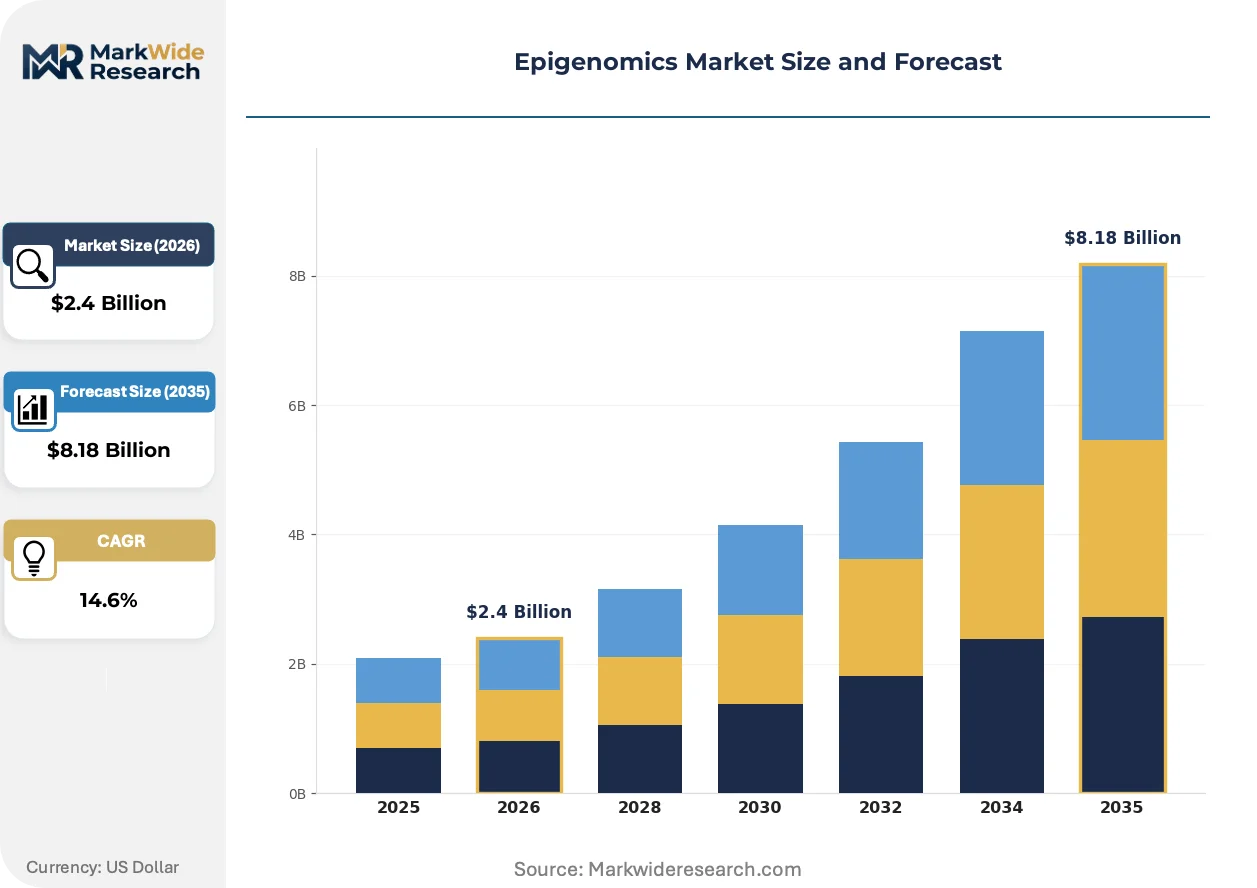
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Methylation Kits, Histone Modification Reagents, Chromatin Accessibility Assays, RNA Expression Analysis, Epigenetic Sequencers Technology: Next-Generation Sequencing, Microarray, PCR-based Methods, Mass Spectrometry, Single-Cell Analysis Application: Cancer Research, Drug Discovery, Agricultural Biotechnology, Neurological Disorder Studies, Forensic Science End User: Academic Institutions, Biotechnology Companies, Contract Research Organizations, Government Research Labs, Diagnostic Centers |
| Companies Covered | Diagenode, Abcam, Illumina, F. Hoffmann-La Roche, Oxford Nanopore Technologies, Merck KGaA, Active Motif, Thermo Fisher Scientific, Qiagen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epigenomics Market Strategic Shifts & Innovations
The market is defined by a transition from exploratory research towards clinical utility. This evolution is driving innovation in single-cell analysis, creating specific regulatory pathways for companion diagnostics, and altering how research institutions procure essential tools and reagents for their experiments.
Single-cell epigenomic sequencing provides the ability to profile epigenetic modifications within individual cells. Academic research centers and pharmaceutical R&D teams are rapidly adopting this method to understand cellular heterogeneity in complex tissues like tumors. This technology is collapsing the analytical assumptions of bulk sequencing, which averages signals across thousands of cells and obscures critical cell-to-cell variability.
Regulatory bodies are adapting to the rise of precision medicine. China's NMPA, for instance, is actively developing clearer guidelines for the co-development and approval of companion diagnostics. This initiative reduces uncertainty for developers, directly impacting companies creating epigenetic tests intended to guide specific cancer therapies. The precision oncology segment is responding by tailoring clinical trial designs to meet these evolving Chinese market access requirements.
Direct-to-researcher purchasing of reagents through online portals is becoming a dominant channel. This trend disintermediates centralized institutional purchasing departments, allowing individual labs to acquire materials with greater speed and autonomy. The shift is most visible within well-funded academic clusters in the United States and Europe, where e-commerce platforms enable faster experimental iteration.
Epigenomics Market Segmentation
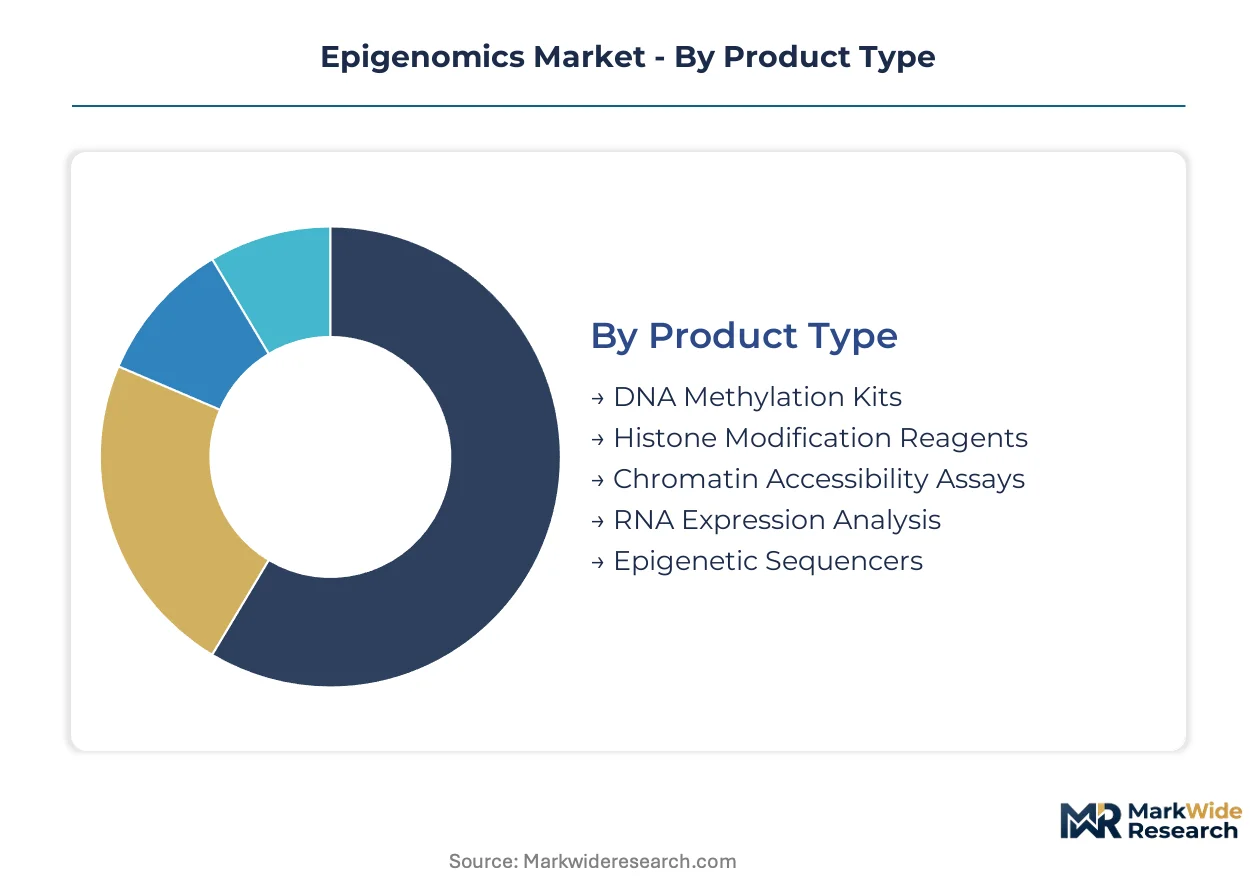
Understanding the epigenomics market requires a detailed segmentation across product types, technologies, applications, and end users. This granular analysis reveals distinct growth drivers and competitive dynamics within each sub-segment. The market structure reflects both established research tools and rapidly advancing diagnostic platforms.
Product Type:
The turnover rates for epigenomic products vary significantly, with consumable kits experiencing faster repurchase cycles compared to high-capital instrumentation. Researchers frequently acquire reagent-based products for ongoing experimental needs. Instrument platforms, however, represent long-term investments for laboratories.
- DNA Methylation Kits:These reagent-based products identify specific methylation patterns on DNA, a fundamental epigenetic modification. Their routine use in academic and pharmaceutical research drives consistent demand, particularly for cancer biomarker discovery.
- Epigenetic Sequencers:High-throughput instruments enable comprehensive analysis of epigenomic modifications across entire genomes. These advanced platforms are crucial for large-scale studies and support the development of novel diagnostic assays.
- Histone Modification Reagents:These kits and antibodies target chemical alterations to histone proteins, which regulate gene accessibility. They are essential for studies exploring chromatin structure and gene expression.
- Chromatin Accessibility Assays:Methods like ATAC-seq and DNase-seq quantify the openness of chromatin, indicating active gene regulatory regions. These assays provide critical insights into gene regulation.
- RNA Expression Analysis:While not purely epigenomic, these products often complement epigenetic studies by measuring gene activity downstream of epigenetic changes. Researchers use them to correlate epigenetic marks with functional outcomes.
DNA Methylation Kits anchor the volume base while Epigenetic Sequencers gain share at the steepest rate.
Technology:
Technology segments in epigenomics are differentiated by their initial capital expenditure and per-sample running costs. Advanced sequencing platforms require substantial upfront investment, whereas PCR-based methods offer lower entry barriers. This cost differentiation influences adoption patterns across various research settings.
- Next-Generation Sequencing:This technology allows for high-throughput, comprehensive profiling of epigenomic modifications across entire genomes. NGS platforms are increasingly central to large-scale research projects and clinical assay development due to their data richness.
- Single-Cell Analysis:These innovative methods enable the study of epigenetic modifications at the resolution of individual cells, revealing cellular heterogeneity. Academic centers and pharmaceutical R&D teams are rapidly adopting single-cell epigenomics.
- Microarray:Older microarray methods provide a more targeted, lower-throughput analysis of epigenetic markers. Their use is declining as NGS offers more comprehensive and flexible solutions for epigenome-wide studies.
- PCR-based Methods:These techniques offer sensitive and cost-effective detection of specific epigenetic markers, often used for validation or targeted analysis. PCR remains a foundational tool in many epigenomic workflows.
- Mass Spectrometry:Mass spectrometry identifies and quantifies epigenetic modifications, particularly histone modifications, based on their molecular mass. It provides detailed biochemical characterization of these marks.
Next-Generation Sequencing is expanding most quickly while Microarray methods are experiencing reduced adoption.
Application:
The diverse applications of epigenomics span from foundational scientific inquiry to targeted clinical development, each addressing distinct biological questions. Specific applications drive demand for specialized reagents and analytical tools. Translational research efforts are particularly impactful.
- Cancer Research:This application focuses on identifying epigenetic biomarkers for early detection, prognosis, and therapeutic response in various cancers. Precision oncology initiatives heavily rely on epigenomic profiling for patient stratification.
- Drug Discovery:Epigenomic insights guide the development of novel therapeutics targeting epigenetic enzymes and pathways. Pharmaceutical companies utilize these studies to identify new drug targets and optimize treatment strategies.
- Agricultural Biotechnology:Researchers investigate epigenetic modifications in crops to improve yield, stress resistance, and nutritional value. This area holds potential for developing more resilient and productive agricultural systems.
- Neurological Disorder Studies:This application explores the epigenetic basis of neurodegenerative and psychiatric conditions, seeking biomarkers and therapeutic targets. Studies identify how environmental factors influence brain function.
- Forensic Science:Epigenetic markers can provide information about an individual's age, tissue origin, or exposure to environmental factors from biological samples. This offers new tools for crime scene investigation.
Cancer Research drives significant investment, while Agricultural Biotechnology represents an emerging area of interest.
End User:
End-user segments define the primary consumers of epigenomics products and services, each with unique funding mechanisms and research priorities. Academic institutions often conduct basic research, whereas biotechnology companies focus on commercializing discoveries. This influences procurement patterns and technology adoption.
- Academic Institutions:Universities and research centers globally conduct fundamental epigenomics research, driven by government grants and institutional funding. They represent a major concentration of end-user activity, particularly in the United States.
- Biotechnology Companies:These firms develop and commercialize epigenomic tools, diagnostics, and therapeutics. Their focus includes R&D for novel drug targets and the creation of clinically validated assays.
- Contract Research Organizations:CROs provide specialized epigenomic services to pharmaceutical and biotechnology clients, including assay development and high-throughput screening. They support externalized research efforts.
- Government Research Labs:National research institutes and agencies conduct mission-driven epigenomics research, often focusing on public health or environmental impacts. They contribute to large-scale data generation projects.
- Diagnostic Centers:Clinical laboratories utilize epigenomic tests for disease diagnosis, prognosis, and treatment selection, especially in oncology. Reimbursement pathways significantly influence their adoption of new assays.
Academic Institutions underpin foundational research, while Diagnostic Centers are increasingly influential in clinical adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for epigenomics products varies regionally, with the United States often commanding higher premiums due to established research funding and clinical adoption. Conversely, market access strategies in China are heavily influenced by local regulatory frameworks, shaping pricing for precision oncology products. This dynamic creates distinct commercial landscapes.
United States
Academic institutions and pharmaceutical R&D drive significant demand for epigenomic tools, particularly in cancer research. National-level initiatives, such as those funded by the NIH, provide substantial capital for basic and translational epigenomics research. The Boston-Cambridge biotech cluster actively develops novel epigenetic diagnostics and therapies.
Germany
Precision oncology initiatives and strong academic research propel the demand for advanced epigenomic analysis in Germany. Europe's EMA regulatory frameworks influence the commercialization path for epigenetic-based diagnostics and therapeutics across the region. Research hubs in Munich and Heidelberg focus on integrating epigenomic data into patient care.
China
The expansion of precision oncology creates sustained demand for epigenetic analysis to identify novel drug targets and patient stratification biomarkers. China's NMPA's evolving guidelines for companion diagnostics are shaping market access strategies for precision oncology products. Major biotech parks in Shanghai and Shenzhen are heavily investing in epigenomic research and development.
Japan
Neurological disorder studies and drug discovery efforts generate specific demand for epigenomic reagents and sequencers. Japan's PMDA influences the approval process for new epigenetic diagnostics and therapies within the country. Research centers in Tokyo and Kyoto are advancing single-cell epigenomic sequencing applications.
United Kingdom
Government research funding supports extensive epigenomics studies, particularly in understanding disease mechanisms. The UK's MHRA oversees the approval of novel epigenetic diagnostic tools. The Oxford-Cambridge arc is a key area for academic and biotech collaboration in epigenomic research.
Epigenomics Market Key Industry Players
Integrated solution providers and specialized reagent suppliers split the epigenomics market, each targeting distinct customer segments based on research focus and budgetary constraints. Companies pursue strategic partnerships to expand technology offerings and diversify portfolios into emerging application areas, particularly in precision oncology. This dynamic environment fosters continuous innovation in both high-throughput instrument platforms and specialized consumable kits.
Among leading technology providers, Illumina exemplifies a hardware-driven strategy, leveraging its dominant sequencing platform to drive consumable sales globally. Thermo Fisher Scientific represents a broad portfolio approach, offering extensive life sciences products and global distribution capabilities across various research and clinical domains. Qiagen, a Germany-based company, anchors the market for specialized sample and assay technologies, providing integrated workflows for academic and biotech clients. These companies navigate the evolving landscape, balancing support for open research platforms with the development of proprietary, clinically validated systems. Their competitive positioning depends heavily on continuous innovation in high-throughput analysis and robust data interpretation solutions.
| Leading Market Players |
|---|
| Diagenode |
| Abcam |
| Illumina |
| F. Hoffmann-La Roche |
| Oxford Nanopore Technologies |
| Merck KGaA |
| Active Motif |
| Thermo Fisher Scientific |
| Qiagen |
Cost & Logistics Intelligence
Upstream concentration of highly specialized epigenetic sequencers from dominant hardware providers like Illumina and Thermo Fisher Scientific heavily influences consumable pricing and margin pools downstream.
Pricing Analysis
Configured-to-order services for epigenomic assay development command a premium, contrasting with the standard per-unit pricing for routine reagents. The market employs a hybrid pricing model, combining high-capital instrument sales with transactional reagent purchases and project-based service fees. Price differentiation stems from brand premium for established technology providers and the customization level for specialized research applications. Pricing softness for Next-Generation Sequencing platforms reflects continuous technological advancements and increasing market accessibility. Academic institutions demonstrate the highest price sensitivity for common reagents, while large pharmaceutical companies prioritize performance over cost for critical drug discovery projects.
Supply Chain Analysis
Contract manufacturing capacity for specialized enzymes and molecular biology reagents largely resides in the United States and Germany, with a growing presence in China for basic chemical inputs. The epigenomics supply chain draws from a diverse set of raw material dependencies, including specialized enzymes, synthetic oligonucleotides, and high-purity antibodies. Single-source vulnerability for proprietary reagents or niche instrument components represents a structural supply chain risk. Distribution runs through a dual model, with direct-to-researcher online platforms for reagents and specialized sales/service teams managing high-capital instrument placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epigenomics market is at a platform-economics inflection point, driven by the integration of multi-omics data platforms and the need for interoperability across diverse analytical tools.
For Market Incumbents:Insulate core sequencing hardware revenue streams against emerging lower-cost platforms by investing in proprietary bioinformatics solutions. Focus on vertical integration into AI-driven data interpretation tools to combat the data analysis bottleneck. Leverage existing global distribution networks to maintain market share against the threat of specialized regional providers. Invest in R&D for novel single-cell epigenomic applications to diversify revenue beyond bulk sequencing.
For New Entrants and Emerging Players:Establish a beachhead in non-oncology applications, such as neurodegenerative disease research or infectious disease epigenetics, where established players have less focus. The most penetrable segment for new entrants involves specialized, user-friendly single-cell epigenomic assay kits targeting academic research labs. A strong go-to-market angle involves developing robust e-commerce platforms for direct-to-researcher sales, bypassing traditional procurement channels. Focus on providing integrated, easy-to-use workflows that simplify complex epigenomic analysis.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with specialized reagent and assay developers possessing unique intellectual property in epigenetic marker discovery. The long-term viability of epigenomics companies is strong, particularly for those with clinically validated diagnostic platforms. Acquisition target archetypes include small biotech firms with proprietary liquid biopsy markers or advanced bioinformatics capabilities. The signal to watch is successful reimbursement pathway approvals for epigenetic tests within major healthcare systems, indicating clinical adoption and revenue predictability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates diverse epigenomic data streams, enhancing analytical depth for researchers and clinicians. |
| Product Launch | Introduces novel single-cell epigenomic assays, expanding research capabilities into cellular heterogeneity. |
| Strategic Partnership | Combines sequencing hardware expertise with specialized bioinformatics, creating comprehensive solutions for end-users. |
| Acquisition of Specialist Firm | Secures proprietary epigenetic biomarker panels, accelerating diagnostic development in precision oncology. |
| Regulatory Approval Pathway | Validates epigenetic tests for clinical use, opening access to broader patient populations and reimbursement. |
Research Approach
Initial hypotheses were tested against primary input from epigenomics researchers, biotech R&D directors, clinical lab managers, and regulatory specialists, then refined. This approach combined in-depth primary interviews with rigorous secondary validation. Secondary data sources included NIH grant databases, NMPA and FDA guidance documents, peer-reviewed scientific literature, and company SEC filings. Bottom-up and top-down triangulation ensured data consistency across various market segments.
The demand-supply-balance framework guided quantitative modeling, projecting market dynamics over the projection horizon. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory environment. Compound annual growth rates were derived from historical trends and anticipated future adoption rates. Industry-specific forecast inputs included Next-Generation Sequencing platform adoption curves and precision oncology clinical trial pipelines.
Stress conditions across R&D funding fluctuations and regulatory approval timelines for novel diagnostics were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and market acceptance. Unforeseen technological disruptions or shifts in reimbursement policies could revise projections. Cross-checking against large-scale epidemiological studies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Organoids and Spheroids Market
Medical Research
Metabolomics Market
Medical Research
Europe AMH Market
Medical Research
Epigenetics Market
Medical Research
Chromatin Immunoprecipitation Sequencing Market
Medical Research
North America Biobanks Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
Placenta Market
Medical Research
Antibody-Mediated Rejection Prevention Market
Medical Research
Global Mice Model Market
Medical Research
Mice Model Technologies Market
Medical Research
Global Human Liver Models Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Health Economics and Outcomes Research (HEOR) Services Market
Medical Research
Malaria Vaccine Market
Medical Research
Clinical Genomics Market