
 Medical Device Contract Research Organization Market | 2026-2036
Medical Device Contract Research Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Contract Research Organization Market Intelligence
Decentralized clinical trial technology is reshaping how medical device sponsors collect real-world evidence and interact with investigators. Thermo Fisher Scientific leverages its PPD division's global site network to sustain multi-regional pivotal studies across orthopedic and cardiovascular indications. IQVIA anchors its competitive position through integrated data assets that link trial outcomes to commercial analytics. ICON plc differentiates via therapeutic depth in oncology devices and digital health endpoints.
A medical device contract research organization provides outsourced clinical, regulatory, and post-market services to sponsors seeking to demonstrate safety and efficacy under ISO 14155 and applicable national standards. These entities manage protocol design, site qualification, biostatistics, and quality assurance to satisfy notified body and regulator scrutiny prior to commercial authorization. Clinical trials services command the largest revenue share due to prolonged enrollment timelines and complex endpoint adjudication in Class III devices. Regulatory affairs consulting represents the fastest-expanding segment as sponsors navigate EU MDR recertification deadlines and FDA breakthrough device designation pathways.
FDA premarket approval and 510(k) clearance pathways, EU MDR notified body conformity assessments, and ISO 13485 quality management standards collectively determine market access timelines and CRO selection criteria. Sponsors operating across multiple jurisdictions face divergent clinical evidence requirements that favor CROs with established regulatory intelligence capabilities. Stakeholders must evaluate partner investments in decentralized trial infrastructure and artificial intelligence-enabled data quality tools as these capabilities separate execution leaders from traditional service providers.
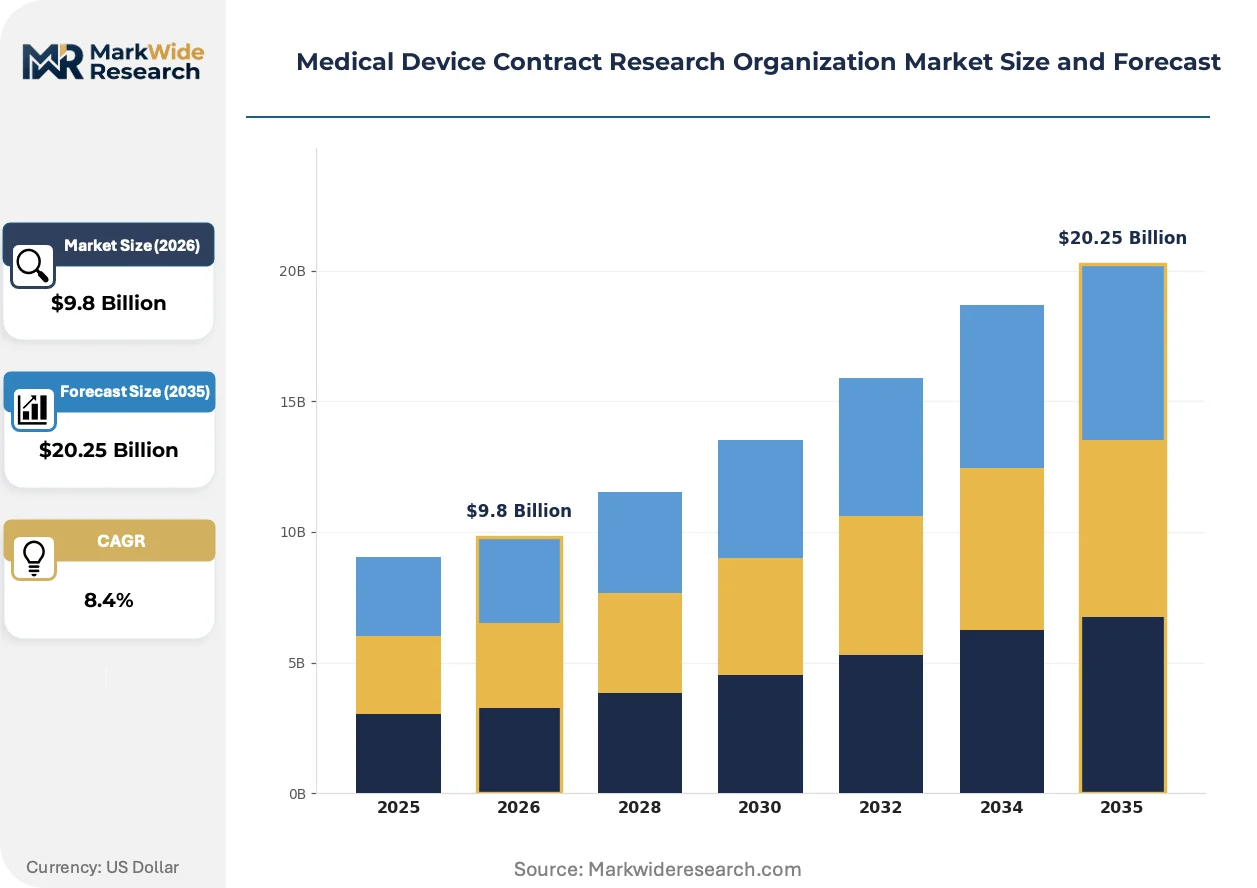
Market Dynamics
Decentralized trial infrastructure is compressing site activation timelines and redistributing clinical operations away from traditional academic medical centers toward direct-to-patient models.
Growth Catalysts
- EU MDR recertification mandates:The 2024-2026 notified body capacity crunch compels legacy device sponsors to outsource technical documentation and post-market clinical follow-up to specialized partners.
- Active implantable device pipelines:Neuromodulation and cardiac rhythm management trials require specialized endpoint adjudication capabilities that internal teams rarely maintain.
- China NMPA regulatory convergence:Domestic sponsors seeking global market access now demand CROs fluent in simultaneous FDA and NMPA submission strategies.
Market Restraints
- Qualified investigator scarcity:Principal investigators with Class III device trial experience concentrate in Germany, the United States, and Japan, creating site access bottlenecks.
- ISO 14155 compliance costs:Sponsor-mandated quality system upgrades and audit readiness programs inflate service delivery overhead.
- Single-source dependency:Core lab services for imaging endpoints rely on a concentrated vendor base in North America and Western Europe.
Strategic Opportunities
- India CDSCO regulatory expansion:The country's medical device rules 2017 amendment creates pathways for imported device trials with reduced local clinical data requirements.
- Digital health endpoint convergence:Wearable-derived biomarkers and electronic patient-reported outcomes are merging with traditional safety endpoints in cardiovascular and orthopedic studies.
- Real-world evidence collection:Post-market surveillance mandates under FDA 21st Century Cures Act provisions enable CROs to convert regulatory compliance into longitudinal data services.
Industry Challenges
- Biostatistician specialization gaps:Adaptive trial design and Bayesian methods for small-population device studies require talent pools that remain shallow outside Boston and Basel.
- Legacy data system integration:Sponsor ERP and CTMS platforms often resist API-based interoperability with modern eCOA and telemedicine platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Contract Research Organization Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Trials, Regulatory Affairs, Data Management, Consulting End User: Pharmaceutical Companies, Biotechnology Firms, Medical Device Companies, Research Institutions Application: In-Vitro Diagnostics, Surgical Devices, Monitoring Equipment, Therapeutic Devices Delivery Model: On-Site Services, Remote Services, Hybrid Services, Outsourced Services |
| Companies Covered | Thermo Fisher Scientific (PPD Division), Parexel International, IQVIA Holdings Inc, ICON plc, Syneos Health, Fortrea, MCRA, Labcorp Drug Development (Covance), Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Contract Research Organization Market Strategic Shifts & Innovations
Artificial intelligence and distributed data capture are rewriting the economics of medical device evidence generation, compressing timelines while expanding the types of endpoints sponsors can credibly submit.
Remote patient monitoring platforms with integrated electronic clinical outcome assessment capabilities are virtualizing the traditional site-visit model. Mid-sized orthopedic and diabetes device sponsors now deploy direct-to-patient protocols for feasibility studies previously requiring 12-month site qualification cycles. This virtualization is collapsing the distinction between pivotal trial data and post-market surveillance streams.
The FDA breakthrough device designation pathway now incorporates structured benefit-risk frameworks that reward sponsors presenting quantitative decision analysis. Device sponsors pursuing neurological and cardiovascular indications must pre-negotiate trial designs through the pre-submission process, embedding CRO biostatisticians earlier in protocol development. EU MDR recertification deadlines are forcing legacy manufacturers to retrofit real-world performance data into technical documentation originally drafted under the medical device directive.
Sponsor procurement functions now unbundle full-service contracts into modular engagements spanning protocol writing, site management, and regulatory submission. Large-cap strategics in Minnesota and California pilot milestone-based payment structures that tie CRO fees to enrollment velocity rather than fixed full-time equivalents. This restructuring concentrates contract value with partners demonstrating interoperable data infrastructure rather than therapeutic reputation alone.
Medical Device Contract Research Organization Market Segmentation
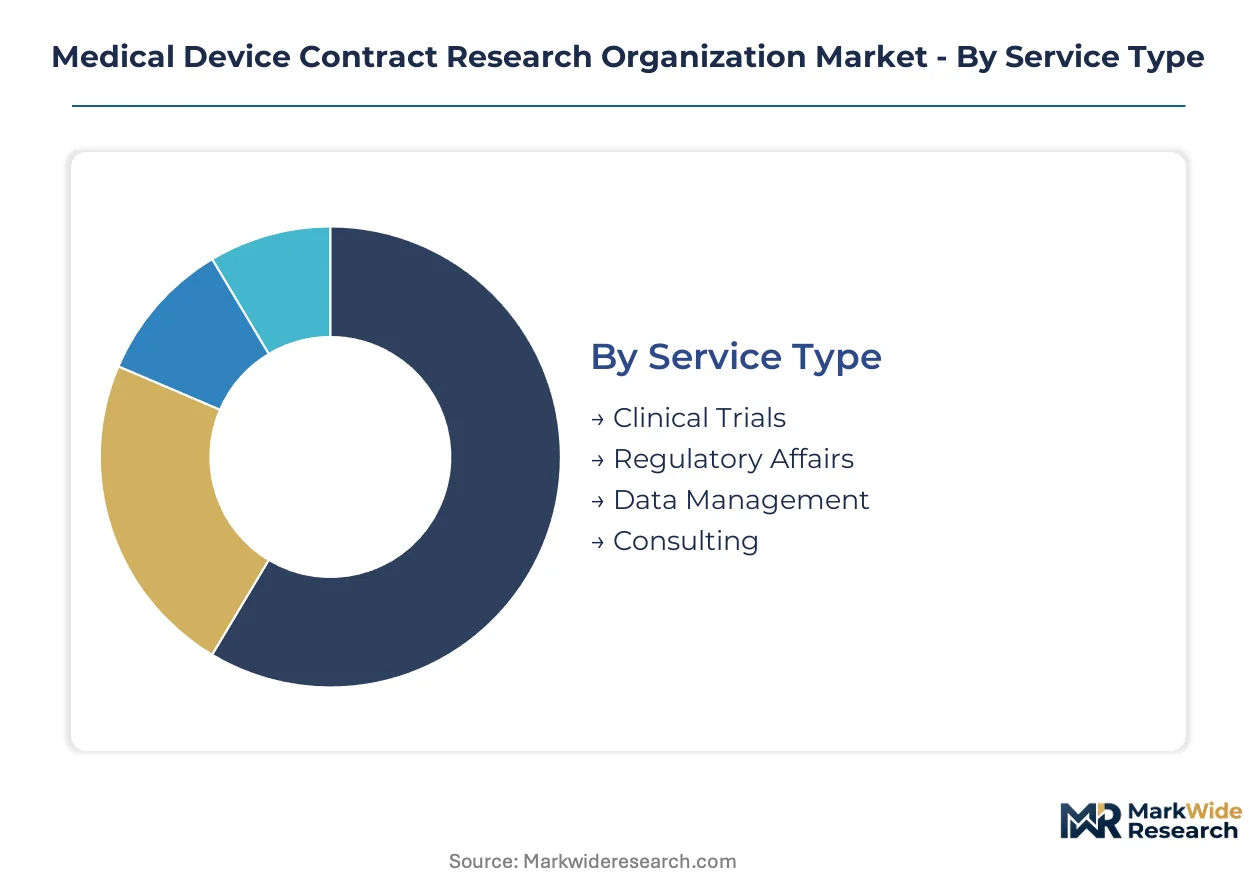
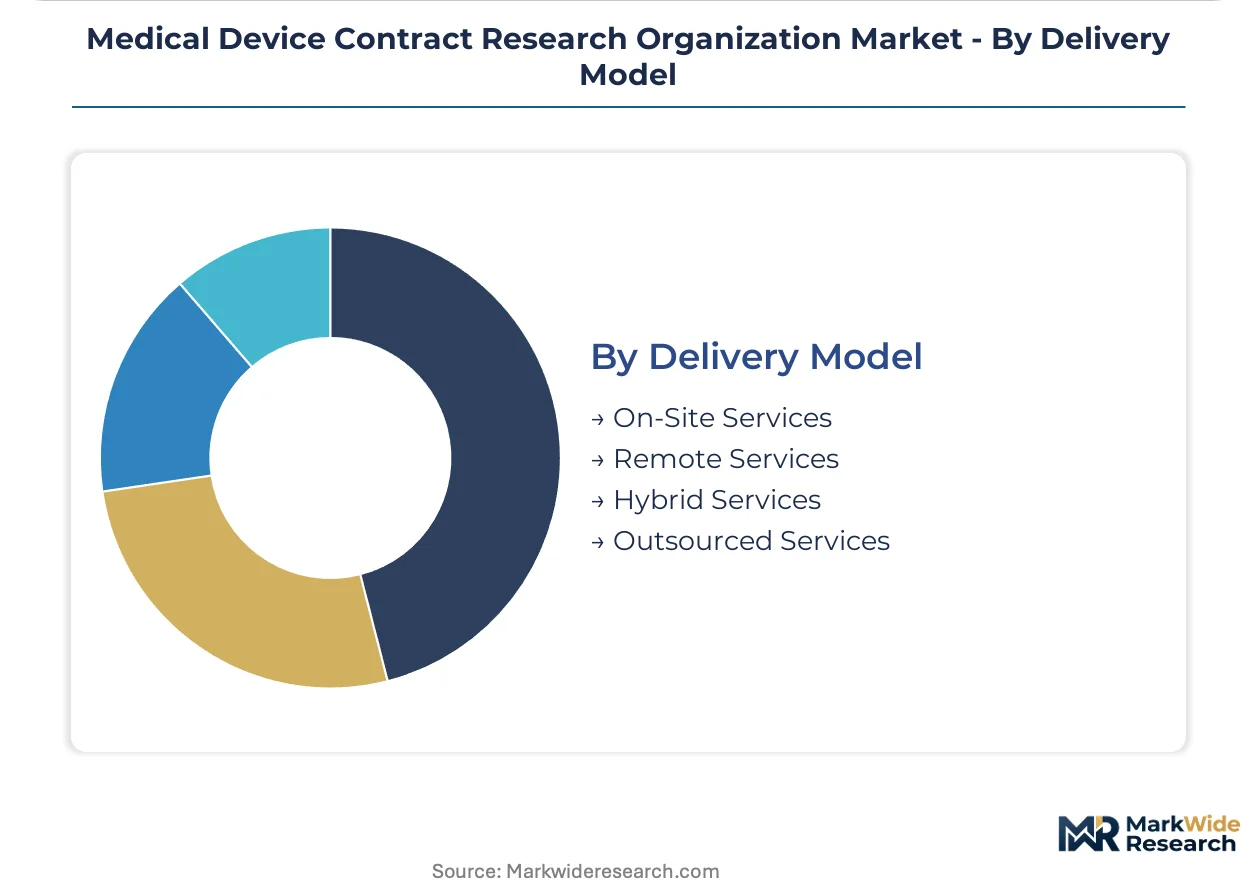
Medical device CRO segmentation reveals divergent margin profiles and contract durations across service types and delivery models. Sponsors unbundle engagements based on regulatory complexity and endpoint adjudication requirements, concentrating procurement on partners with specialized capabilities.
Service Type:
Clinical trial cycle times vary dramatically from protocol design through database lock, with regulatory consulting turning over fastest as sponsors pursue parallel-track submissions.
- Clinical Trials:Protocol development, site activation, patient enrollment, and endpoint adjudication for Class II and III devices under ISO 14155. Demand concentrates in cardiovascular and orthopedic indications where pivotal studies extend 24-36 months and FDA pre-submission meetings shape trial design.
- Regulatory Affairs:Technical documentation compilation, notified body liaison, and submission strategy for EU MDR recertification and FDA 510(k)/PMA pathways. Sponsors in Germany and the United States drive volume as legacy device manufacturers face compressed deadlines to update technical files.
- Data Management:Electronic data capture configuration, database validation, and statistical programming for regulatory submission datasets.
- Consulting:Quality system gap assessments, regulatory intelligence, and post-market surveillance strategy development.
Clinical Trials anchors the volume base while Regulatory Affairs gains share at the steepest rate.
End User:
Customer procurement sophistication spans from fully outsourced development to targeted regulatory support, with contract value scaling to pipeline complexity and geographic breadth.
- Medical Device Companies:Full-service clinical and regulatory outsourcing from feasibility through post-market surveillance. Boston and Minneapolis clusters concentrate demand for neuromodulation and structural heart trials requiring specialized endpoint adjudication.
- Pharmaceutical Companies:Combination product development support spanning drug-device interface validation and dual regulatory pathway navigation.
- Biotechnology Firms:Early-stage device feasibility studies and regulatory strategy for novel biomaterial platforms.
- Research Institutions:Investigator-initiated studies and grant-funded device evaluations with limited commercialization pathways.
Medical Device Companies command the largest contract values while Pharmaceutical Companies expand most quickly into combination product services.
Application:
Device class and indication type determine clinical evidence requirements, with active implantables demanding the longest enrollment timelines and most complex safety monitoring.
- Surgical Devices:Orthopedic and general surgery trials with mechanical endpoints and shorter follow-up periods. China and Germany concentrate demand as domestic manufacturers seek global market access through simultaneous FDA and NMPA submissions.
- Therapeutic Devices:Active implantables including cardiac rhythm management and neuromodulation systems requiring long-term safety surveillance. FDA breakthrough device designation pathways and EU MDR recertification deadlines compel specialized CRO partnerships.
- In-Vitro Diagnostics:Analytical and clinical validation studies for companion diagnostics and point-of-care platforms.
- Monitoring Equipment:Wearable and remote patient monitoring trials integrating digital health endpoints with traditional safety measures.
Surgical Devices generate the highest transaction frequency while Therapeutic Devices command premium pricing for specialized expertise.
Delivery Model:
Service configuration determines cost structure and timeline compression potential, with hybrid models gaining traction as sponsors balance site access with patient convenience.
- Hybrid Services:Blended site-based and direct-to-patient protocols leveraging decentralized trial infrastructure. Sponsors in the United States and Western Europe adopt this model to reduce site activation bottlenecks while maintaining investigator oversight for Class III devices.
- Remote Services:Fully virtualized data collection through telemedicine platforms and electronic clinical outcome assessment tools.
- On-Site Services:Traditional site management with embedded clinical research associates and centralized monitoring.
- Outsourced Services:Functional service provider arrangements for discrete activities like biostatistics or medical writing.
Hybrid Services is climbing the fastest as sponsors retrofit protocols for regulatory acceptance of decentralized endpoints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German CROs export regulatory consulting services to Boston and Minneapolis medical device clusters facing EU MDR recertification deadlines. This transatlantic knowledge corridor concentrates specialized technical documentation expertise in Frankfurt and Munich.
United States
FDA premarket approval pathways and breakthrough device designations drive sponsor demand for specialized clinical trial execution. The 21st Century Cures Act mandates expanded real-world evidence collection post-authorization. Minneapolis and Boston host the densest orthopedic and neuromodulation trial clusters, with CROs embedding biostatisticians directly into sponsor pre-submission meetings.
Germany
Notified body capacity constraints under EU MDR compel legacy device manufacturers to outsource technical file updates and post-market clinical follow-up. BfArM and notified body coordination requirements favor CROs with established Cologne and Tübingen regulatory intelligence operations. The Munich-Stuttgart corridor concentrates active implantable device innovation requiring specialized endpoint adjudication capabilities.
China
NMPA regulatory convergence with FDA standards enables simultaneous submission strategies for domestic sponsors seeking global market access. The medical device rules 2017 amendment creates streamlined pathways for imported device trials. Shanghai and Beijing clusters drive demand for CROs fluent in dual regulatory navigation, particularly for cardiovascular and orthopedic indications.
India
CDSCO regulatory expansion under the 2017 medical device rules amendment reduces local clinical data requirements for imported device trials. Hyderabad and Bangalore clusters attract feasibility studies for diabetes and surgical devices seeking cost-efficient enrollment. CROs with established Mumbai regulatory operations capture sponsor demand for emerging market access strategies.
Switzerland
Swissmedic alignment with EU MDR standards maintains market access equivalence despite non-EU status. Basel and Zurich host specialized biostatistics talent pools for adaptive trial designs and Bayesian methods. CROs leverage Swiss regulatory neutrality to manage multi-jurisdictional submissions spanning FDA, EMA, and Health Canada pathways.
Medical Device Contract Research Organization Market Key Industry Players
On the supply side, the industry is consolidating around integrated data assets and therapeutic specialization rather than geographic coverage alone. Tier-one operators maintain global site networks while mid-sized players compete on regulatory intelligence depth in specific jurisdictions. Three archetypes dominate: full-service strategics with laboratory-to-clinic integration, boutique specialists in active implantable devices, and technology-enabled platforms leveraging decentralized trial infrastructure. Competitive moves center on milestone-based contract restructuring and artificial intelligence-enabled data quality tool deployment.
Within the full-service strategic tier, Thermo Fisher Scientific through its PPD division, IQVIA Holdings Inc, and ICON plc exemplify divergent positioning vectors. Thermo Fisher anchors its offering through laboratory services integration with clinical operations. IQVIA occupies a position defined by commercial data asset linkage to trial outcomes. ICON represents therapeutic depth specialization, particularly in oncology devices and digital health endpoints. These three entities collectively illustrate how scale, data integration, and indication focus constitute distinct competitive moats in sponsor procurement decisions.
| Leading Market Players |
|---|
| Thermo Fisher Scientific (PPD Division) |
| Parexel International |
| IQVIA Holdings Inc |
| ICON plc |
| Syneos Health |
| Fortrea |
| MCRA |
| Labcorp Drug Development (Covance) |
| Charles River Laboratories |
| Others |
Cost & Logistics Intelligence
Frankfurt-to-Boston air freight corridors carry time-sensitive biostatistics deliverables and regulatory submission materials, with per-kilogram rates compressing margins on fixed-fee clinical trial contracts while amplifying price spreads between boutique specialists and volume players.
Pricing Analysis
Next-generation AI-enabled data quality tools command 40-60% fee premiums over legacy manual monitoring approaches, while prior-generation site-based service models face systematic price erosion. Project-based contracting dominates, with pricing differentiation driven by ISO 13485 certification tier and therapeutic specialization depth. Cost compression in standard clinical monitoring services intensifies as sponsors unbundle engagements and benchmark against functional service provider rates. Mid-sized orthopedic device manufacturers exhibit highest price sensitivity, while neuromodulation sponsors prioritize endpoint adjudication expertise over cost.
Supply Chain Analysis
Biostatistics talent feeds from concentrated academic pipelines in Boston, Basel, and Zurich, with specialized regulatory intelligence capacity anchored in Germany and Switzerland. Core lab services for imaging endpoints draw from single-source vendors concentrated in North America and Western Europe. Single-source vulnerability in qualified principal investigator networks creates site access bottlenecks for Class III device trials. Distribution runs through sponsor-direct contracting models with milestone-based payment structures displacing traditional full-time equivalent arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized regulatory intelligence capabilities remain scarce outside established European and North American clusters, constraining sponsor options for EU MDR recertification and dual FDA-NMPA submission strategies.
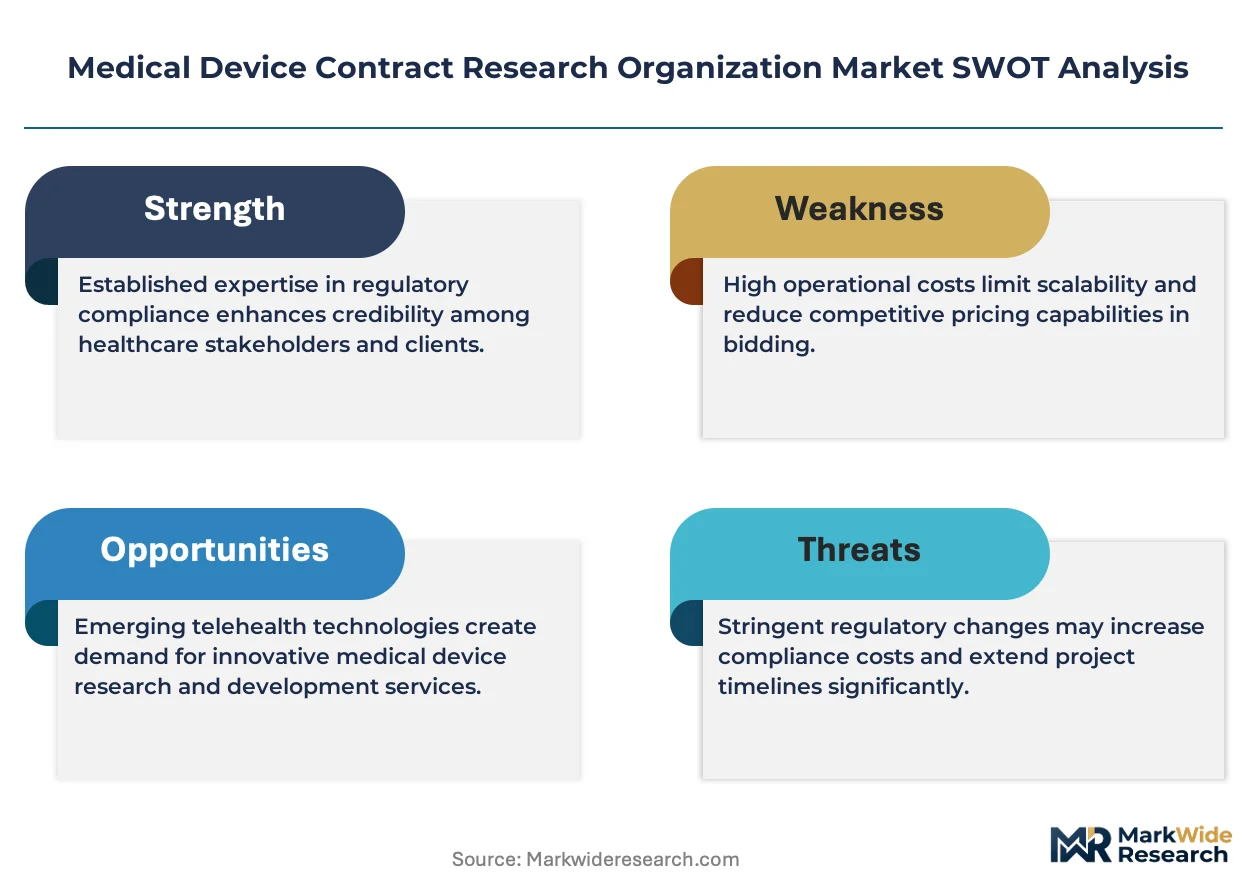
For Market Incumbents: Pre-empt boutique competitors by embedding biostatisticians into sponsor pre-submission meetings and acquiring decentralized trial infrastructure capabilities. ISO 14155 compliance cost inflation threatens margin sustainability without automation investment. Backward integration into electronic data capture platform development secures data interoperability advantages. For New Entrants and Emerging Players: India CDSCO regulatory expansion for imported device trials represents the most penetrable entry point, with Hyderabad and Bangalore clusters offering cost-efficient enrollment for diabetes and surgical device feasibility studies. Digital health endpoint convergence in cardiovascular monitoring creates white-space for technology-native platforms. Direct-to-patient protocol design capabilities differentiate against legacy site-based incumbents. For Investors and Strategic Acquirers: Boutique CROs with therapeutic depth in active implantable devices and established notified body relationships command scarcity premiums. Long-term viability hinges on regulatory intelligence asset accumulation rather than geographic coverage alone. FDA breakthrough device designation pathway volume serves as the critical inflection indicator for specialized service demand.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Capability Buildout | Notified body capacity constraints in Germany compel outsourced technical file expertise. |
| Decentralized Trial Infrastructure Deployment | Direct-to-patient protocols reduce site activation timelines for orthopedic feasibility studies. |
| Dual FDA-NMPA Submission Strategy Development | China sponsor demand for simultaneous global market access drives regulatory intelligence premiums. |
| AI-Enabled Data Quality Tool Integration | Automated monitoring compresses database lock timelines for Class III device studies. |
| Real-World Evidence Collection Service Expansion | FDA 21st Century Cures Act mandates convert post-market surveillance into longitudinal revenue streams. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA premarket submission databases, EU MDR notified body technical documentation filings, and ISO 14155 audit records. Interviews with clinical operations directors, regulatory affairs leads at medical device sponsors, principal investigators with Class III trial experience, and GPO contracts managers informed demand-side dynamics. Bottom-up service line revenue estimates triangulated against top-down market sizing from regulatory filing velocity and CRO contract announcement tracking.
Forecast inputs span service type segmentation across clinical trials, regulatory affairs, data management, and consulting; delivery model configuration from on-site through hybrid to remote; and end-user archetypes spanning medical device companies, pharmaceutical combination product developers, and biotechnology firms. CAGRs derived from enrollment timeline projections, notified body capacity modeling, and sponsor outsourcing propensity indices across the analysis window. EU MDR recertification deadline clustering and FDA breakthrough device designation pathway volume served as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in sponsor R&D budget allocations, air freight rate volatility, or biostatistician wage inflation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway convergence and decentralized trial technology adoption curves. Cross-checking against FDA premarket approval volume trends and notified body capacity expansion announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
Placenta Market
Medical Research
Cancer Mouse Models Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Life Science R&D Infrastructure Outsourcing Market
Medical Research
Global Mice Model Market
Medical Research
PDX Models Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Organoids and Spheroids Market
Medical Research
Europe AMH Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
Malaria Vaccine Market
Medical Research
Mice Model Technologies Market
Medical Research
Preventive Medicine Market
Medical Research
Global Human Liver Models Market