
 Lab Automation in Drug Discovery Market | 2026-2036
Lab Automation in Drug Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Automation in Drug Discovery Market Foresight
Switzerland is narrowing its competitive gap in lab automation through sustained investment in precision robotics manufacturing. Thermo Fisher Scientific leverages its integrated reagent-to-software portfolio to dominate high-throughput screening deployments across North America and Europe. Beckman Coulter anchors its position in liquid handling through proprietary Biomek platform architecture that spans genomic and proteomic workflows. Tecan Group specializes in modular workstation design, allowing biotech firms to scale automation without full platform replacement.
Lab automation in drug discovery encompasses integrated hardware and software systems that execute repetitive laboratory protocols with minimal human intervention, typically achieving throughput rates exceeding 10,000 compounds per day in screening configurations. These systems combine robotic manipulators, precision fluid dispensers, and data management platforms to accelerate hit identification and lead optimization cycles for pharmaceutical development. Liquid handling systems capture the largest installed base among product categories, though AI-integrated platforms represent the fastest-expanding margin pool as machine learning reshapes assay interpretation. High-throughput screening technology leads in transaction volume, while mass spectrometry automation commands premium pricing in target validation workflows where analytical specificity determines program progression.
FDA 21 CFR Part 11 mandates electronic signature and audit trail capabilities for automation software sold to GMP-compliant pharmaceutical operations, elevating validation costs for market entrants. The EPA and OSHA jointly influence laboratory robotics design through chemical exposure limits and ergonomic safety standards that shape enclosure engineering and operator interface specifications. EMA's Annex 11 guidelines extend similar data integrity requirements across European contract research organizations, creating parallel compliance obligations for vendors serving transatlantic clients. Stakeholders must weigh regulatory validation timelines against AI-enabled platform refresh cycles when committing to multi-year automation investments.
Market Dynamics
AI-driven assay interpretation is compressing validation timelines and forcing incumbent automation vendors to re-architect software stacks around machine learning inference rather than static protocol execution. This technology shift is redistributing margin pools from hardware toward predictive analytics modules.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates for GMP-compliant pharmaceutical operations pull validated automation platforms into replacement cycles ahead of hardware end-of-life.
- Contract research organizations:Sponsor demand for accelerated screening timelines drives automated capacity expansion across North American and European CRO footprints.
- Precision robotics manufacturing:Switzerland's sustained capital deployment narrows the competitive gap in high-accuracy liquid handling instrumentation for proteomic workflows.
Market Restraints
- Validation cost inflation:FDA and EMA parallel compliance obligations for electronic signatures and audit trails elevate software development costs for new market entrants.
- Concentrated supply of precision motion components:German and Japanese linear actuator manufacturers control critical feedstock for multi-axis robotic manipulators.
- Technical limitation in complex cellular assays:Three-dimensional spheroid and organoid models resist full automation due to viscosity variability and shear sensitivity.
Strategic Opportunities
- AI-integrated platforms:Convergence of automated liquid handling with real-time computer vision enables adaptive pipetting corrections that reduce compound waste.
- India's pharmaceutical manufacturing expansion:CDSCO quality mandates and PLI scheme incentives create demand for compliant automation in generic API production.
- Modular workstation architecture:Biotech firms scale throughput through component addition rather than full platform replacement, extending vendor recurring revenue.
Industry Challenges
- Cross-disciplinary talent scarcity:Integration of robotics engineering with computational biology expertise remains concentrated in Boston and San Diego clusters.
- Legacy LIMS interoperability:Proprietary data formats from 1990s-era laboratory information management systems resist API-based connectivity with modern cloud-native platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Automation in Drug Discovery Market |
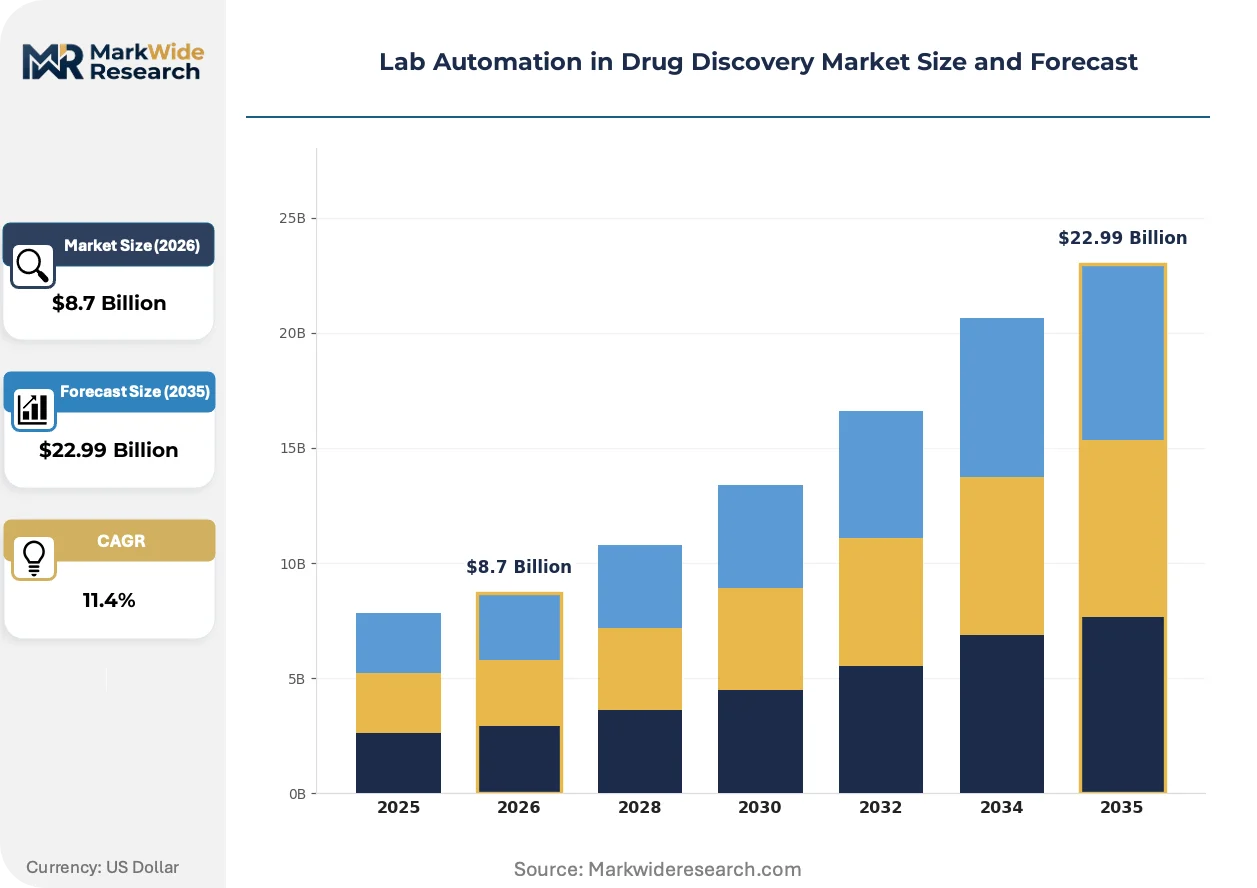
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
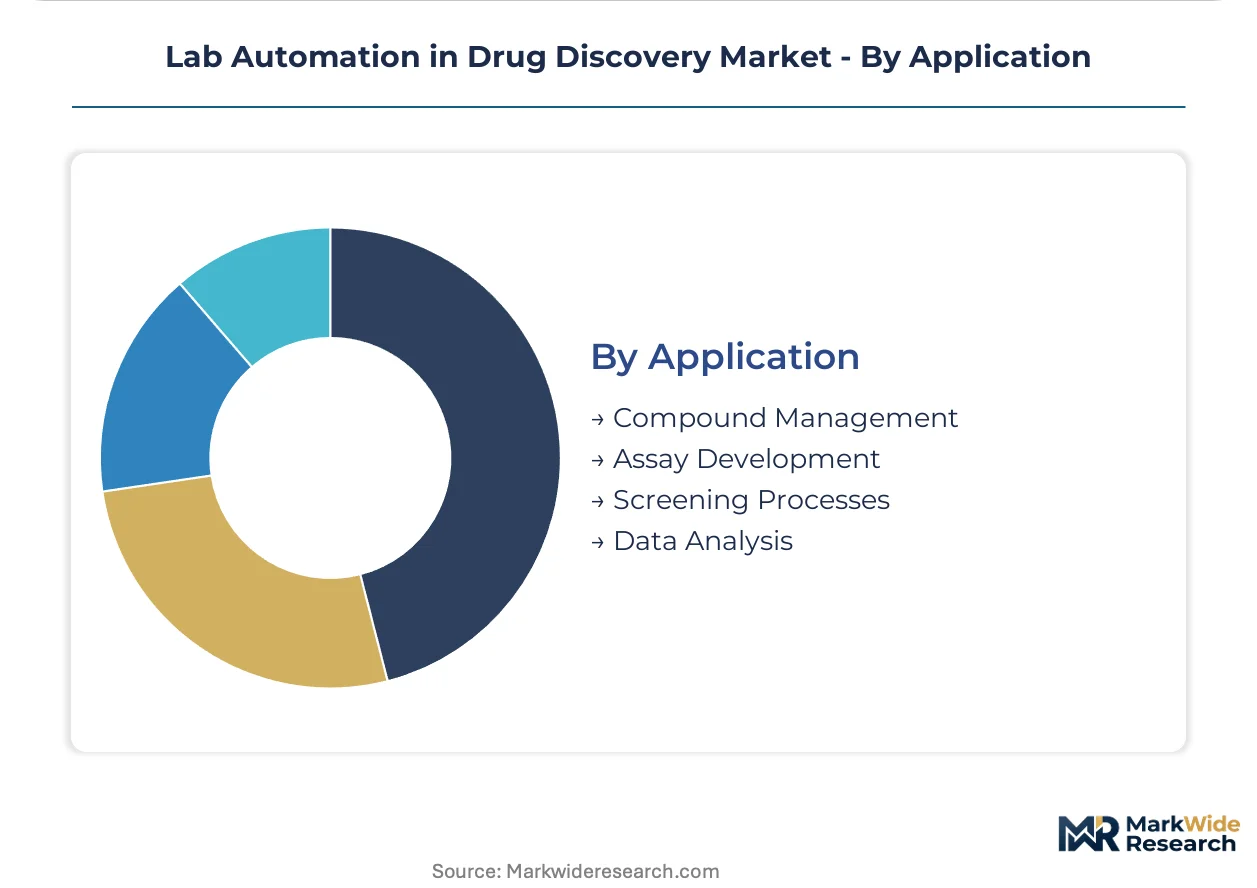
| Segmentation | Product Type: Liquid Handling, Robotics, Automated Workstations, Microplate Readers Technology: AI Integration, Liquid Chromatography, Mass Spectrometry, High-Throughput Screening End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutions Application: Compound Management, Assay Development, Screening Processes, Data Analysis |
| Companies Covered | Thermo Fisher Scientific, Beckman Coulter, Tecan Group, PerkinElmer, Agilent Technologies, Becton Dickinson, Hudson Robotics, Roche Holdings, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Automation in Drug Discovery Market Shifts & Advancements
Machine learning inference at the edge is redefining where analytical decisions occur, shifting value capture from centralized servers to instrument-embedded GPUs. This architectural inversion is reshaping R&D roadmaps across liquid handling and detection subsystems.
Acoustic liquid dispensing is hybridizing precision non-contact transfer with nanoliter-scale volume control, enabling miniaturized assay formats that conserve high-value compound libraries. Mid-tier biotechs in the United States and Germany are adopting this technology eighteen to twenty-four months faster than large pharmaceutical procurement cycles permit. The structural consequence is compression of screening campaign economics, as reagent costs per data point fall below traditional pin-tool thresholds.
EMA's Annex 11 guidelines extend data integrity requirements across European contract research organizations, creating parallel validation obligations with FDA 21 CFR Part 11. Vendors serving transatlantic clients must maintain dual-compliant software architectures, elevating quality assurance headcount as a percentage of R&D spend. Mass spectrometry automation platforms face the steepest compliance burden due to the complexity of raw data file provenance tracking.
Biopharma procurement functions are consolidating vendor relationships around integrated reagent-instrument-software portfolios, displacing best-of-breed component sourcing. This concentration favors suppliers with captive consumables streams and penalizes pure-play hardware manufacturers. The shift is most visible in United States East Coast clusters, where procurement teams negotiate enterprise framework agreements spanning multiple therapeutic areas.
Lab Automation in Drug Discovery Market Segmentation
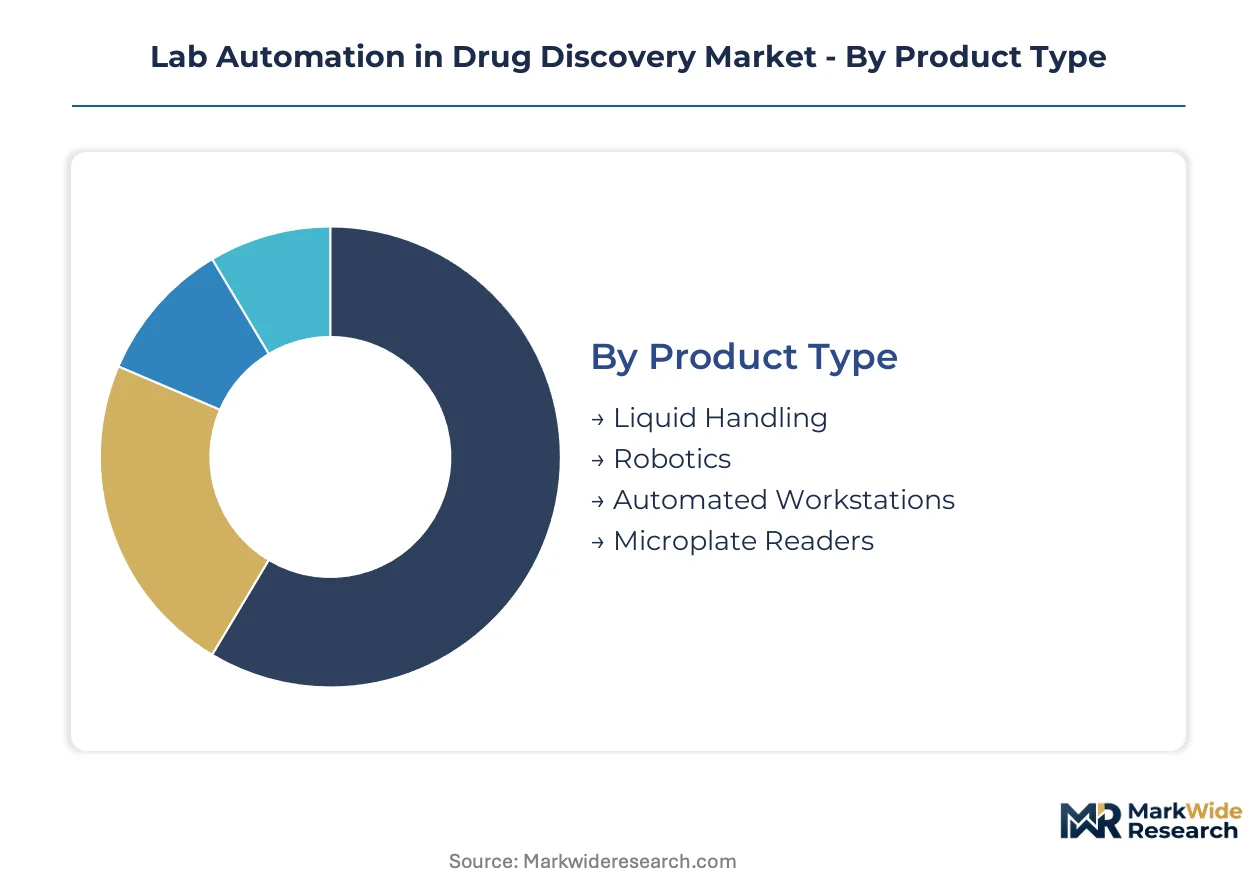
Lab automation procurement decisions hinge on matching technical specifications to workflow complexity, with pharmaceutical buyers weighing throughput requirements against validation burdens. Segmentation reveals where margin pools concentrate and which technology trajectories command capital allocation priority.
Product Type:
Cost tier stratification separates high-capital robotic platforms from modular workstation investments that biotechs scale incrementally.
- Liquid Handling:Precision fluid dispensers achieve nanoliter accuracy through acoustic or air displacement mechanisms. Pharmaceutical companies in the United States deploy these systems for compound library management where FDA 21 CFR Part 11 audit trails are mandatory. The installed base spans single-channel benchtop units to 1,536-well parallel dispensers.
- Robotics:Multi-axis manipulators integrate with enclosure systems to execute plate handling, seal piercing, and centrifuge loading. Boston and San Diego biotech clusters drive demand for collaborative robot configurations that reduce ergonomic risk in 24-hour operations.
- Automated Workstations:Modular architectures allow component addition without platform replacement.
- Microplate Readers:Detection subsystems capture absorbance, luminescence, and fluorescence endpoints.
Liquid Handling holds installed capacity. Automated Workstations is rotating up the share rankings.
Technology:
Application maturity separates established chromatographic methods from emerging AI inference architectures that compress assay timelines.
- AI Integration:Embedded GPUs enable real-time computer vision for adaptive pipetting corrections and anomaly detection. Biotechnology firms in Germany adopt these platforms eighteen to twenty-four months faster than large pharmaceutical procurement cycles permit, driven by reagent cost reduction per data point.
- High-Throughput Screening:Integrated robotic liquid handling with detection subsystems achieves throughput exceeding 10,000 compounds daily. Contract research organizations across North America and Europe expand automated capacity to meet sponsor demands for accelerated hit identification.
- Liquid Chromatography:Separation science underpins analytical method development for pharmacokinetic studies.
- Mass Spectrometry:Target validation workflows command premium pricing where analytical specificity determines program progression.
High-Throughput Screening holds installed capacity. AI Integration is climbing the fastest.
End User:
Customer type dictates procurement authority, with centralized pharmaceutical functions negotiating enterprise frameworks while biotechs prioritize modular scalability.
- Pharmaceutical Companies:GMP-compliant operations mandate validated automation platforms with electronic signature capabilities. FDA 21 CFR Part 11 requirements pull these buyers toward replacement cycles ahead of hardware end-of-life, elevating software assurance spend as a percentage of total cost of ownership.
- Contract Research Organizations:Sponsor demand for compressed screening timelines drives automated capacity expansion across CRO footprints. EMA Annex 11 guidelines create parallel validation obligations for vendors serving transatlantic clients, concentrating procurement among dual-compliant suppliers.
- Biotechnology Firms:Venture-backed companies in Boston and San Diego clusters favor workstation architectures that scale throughput through component addition.
- Academic Institutions:Grant-funded laboratories prioritize capital efficiency over throughput maximization.
Pharmaceutical Companies hold installed capacity. Contract Research Organizations is rotating up the share rankings.
Application:
Volume concentration in screening workflows contrasts with emerging demand for automated data interpretation that reduces manual review bottlenecks.
- Screening Processes:Hit identification and lead optimization cycles consume the majority of automated liquid handling runtime. Miniaturized assay formats enabled by acoustic dispensing conserve high-value compound libraries while maintaining statistical power for structure-activity relationship modeling.
- Data Analysis:Machine learning inference at the edge shifts analytical decisions from centralized servers to instrument-embedded processors. This architectural inversion reshapes R&D roadmaps and redistributes margin pools from hardware toward predictive analytics modules.
- Compound Management:Sample tracking, storage retrieval, and solubilization workflows require integration with laboratory information management systems.
- Assay Development:Protocol optimization demands flexible automation that accommodates iterative parameter adjustment.
Screening Processes holds installed capacity. Data Analysis is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 compliance requirements anchor procurement decisions in the United States, the dominant geography for lab automation demand. Pharmaceutical buyers across North America and Europe face parallel validation obligations from EMA Annex 11 guidelines. Biotech clusters in Switzerland and Germany are narrowing competitive gaps through precision robotics manufacturing investments.
United States
Boston and San Diego biotech clusters drive instrument procurement for high-throughput screening workflows. FDA 21 CFR Part 11 mandates electronic signature and audit trail capabilities for GMP-compliant pharmaceutical operations. Contract research organizations across the Northeast and West Coast expand automated capacity to meet sponsor demands for accelerated hit identification timelines.
Germany
Mid-tier biotechs adopt AI-integrated platforms eighteen to twenty-four months faster than large pharmaceutical procurement cycles permit. EMA Annex 11 guidelines create validation obligations for vendors serving European contract research organizations. The Baden-Württemberg and Bavaria regions concentrate precision engineering expertise for liquid handling instrumentation.
Switzerland
Sustained capital deployment in precision robotics manufacturing narrows the competitive gap in high-accuracy instrumentation. Swissmedic regulations align with EMA data integrity requirements for pharmaceutical automation deployments. The Basel and Zurich metropolitan areas anchor proteomic workflow automation development for contract research applications.
United Kingdom
Academic and biotech research institutions prioritize modular workstation architectures for capital-efficient scaling. MHRA guidelines enforce data integrity standards comparable to FDA and EMA frameworks. The Cambridge and Oxford clusters concentrate computational biology expertise for AI-driven assay interpretation platforms.
India
CDSCO quality mandates and PLI scheme incentives create demand for compliant automation in generic API production. The country's national pharmaceutical regulator enforces quality standards that elevate software assurance requirements. Maharashtra and Gujarat host expanding pharmaceutical manufacturing footprints requiring validated liquid handling systems.
Lab Automation in Drug Discovery Market Competitive Landscape
Integrated reagent-to-software portfolios and modular workstation specialists split the market between enterprise framework suppliers and scalable component vendors. Thermo Fisher Scientific leverages captive consumables streams to dominate high-throughput screening deployments, while Tecan Group anchors the modular tier. Consolidation favors suppliers with validated software architectures capable of dual FDA and EMA compliance. Strategic moves center on portfolio diversification around AI inference capabilities and geographic expansion into India's pharmaceutical manufacturing corridor.
Among diversified life science conglomerates, Thermo Fisher Scientific and Beckman Coulter exemplify the integrated portfolio archetype, combining instrumentation with captive reagent and software revenue streams. Tecan Group occupies a position within the modular specialization tier, enabling biotech firms to scale throughput through component addition rather than full platform replacement. These three entities represent the dominant competitive positioning vectors in North American and European procurement cycles.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Beckman Coulter |
| Tecan Group |
| PerkinElmer |
| Agilent Technologies |
| Becton Dickinson |
| Hudson Robotics |
| Roche Holdings |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's precision engineering cluster anchors linear actuator and motion control component manufacturing, feeding downstream pricing power to German and Japanese robotics vendors who command premium positioning in multi-axis liquid handling systems. This geographic concentration of critical feedstock creates asymmetric leverage, where component scarcity in precision motion hardware translates directly into elevated platform costs for pharmaceutical automation buyers.
Pricing Analysis
Transatlantic price spreads of 15-25% separate North American from European procurement, reflecting FDA 21 CFR Part 11 validation burdens that elevate software assurance costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification depth and after-sales service bundling. Cost compression in the mid-tier instrumentation segment is intensifying because mid-tier biotechs demand modular scalability without enterprise framework pricing. Academic and grant-funded laboratories exhibit highest price sensitivity, while GMP-compliant pharmaceutical operations demonstrate lowest sensitivity due to replacement cycle mandates.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German and Japanese linear actuator manufacturers anchor working capital structures for robotics integrators. Component sourcing concentrates in Germany, Japan, and Switzerland for precision motion hardware, with acoustic dispensing modules drawing from specialized transducer foundries in the United States and Germany. Single-source vulnerability in piezoelectric positioning systems creates supply chain risk exposure for vendors dependent on specific ceramic substrate suppliers. Distribution runs through direct enterprise sales teams for pharmaceutical accounts, with modular workstation specialists utilizing channel partners for biotech market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among contract research organizations is shifting buyer power toward framework-negotiating entities, compressing vendor margins and favoring suppliers with captive consumables streams.
For Market Incumbents: Build switching-cost moats through validated software architectures capable of dual FDA and EMA compliance, deepening data integrity capabilities that resist replacement. Incumbents should anchor position through backward integration into precision motion components, securing supply of linear actuators against Japanese and German supplier concentration. AI-enabled platform refresh cycles threaten hardware-centric revenue models, making predictive analytics module development the critical defensive lever. For New Entrants and Emerging Players: Pursue acoustic liquid dispensing specialization as the most penetrable white-space target, where mid-tier biotech adoption velocity exceeds large pharmaceutical procurement cycle constraints. India's pharmaceutical manufacturing corridor under CDSCO quality mandates offers geographic entry with lower incumbent saturation than United States or European clusters. Go-to-market positioning should emphasize modular workstation architectures that enable throughput scaling through component addition rather than full platform replacement. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-technology play because regulatory validation timelines increasingly determine competitive persistence over raw hardware performance. Acquisition targets should display dual FDA-EMA software certification and recurring consumables revenue attachment above industry averages. The signal to watch is CRO procurement consolidation velocity, as framework agreement concentration will accelerate vendor margin compression and trigger distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| AI Inference Module Development | Embedded GPU architectures capture margin pools shifting from hardware toward predictive analytics in assay interpretation. |
| Dual Compliance Certification Investment | Simultaneous FDA 21 CFR Part 11 and EMA Annex 11 validation opens transatlantic CRO procurement channels. |
| Precision Component Backward Integration | In-house production of linear actuators reduces dependency on German and Japanese supplier concentration. |
| India Manufacturing Corridor Expansion | CDSCO-compliant automation platforms address PLI scheme-driven demand in Maharashtra and Gujarat pharmaceutical clusters. |
| Acoustic Dispensing Technology Licensing | Nanoliter-scale non-contact transfer capabilities enable miniaturized assay formats that conserve high-value compound libraries. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, automation platform engineers, and CRO procurement directors and refined through secondary validation across FDA 510(k) filings, EMA submission databases, laboratory automation trade association reports, and SEC 10-K instrument revenue disclosures. Bottom-up triangulation of installed base estimates with top-down market sizing from pharmaceutical R&D expenditure flows ensured cross-verification of volume and value outputs.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, technology architecture, end-user category, and application workflow. CAGRs were derived from regression analysis of historical procurement patterns and forward projection of regulatory-driven replacement cycles. Forecast inputs incorporated AI integration adoption curves and precision robotics manufacturing capacity expansion in Switzerland and Germany.
Sensitivities concentrate around AI platform refresh velocity, precision component supply disruptions, and regulatory harmonization shifts between FDA and EMA frameworks. Forecasts reflect documented assumptions regarding CRO sponsor demand growth and biotech venture funding availability. Macroeconomic contraction affecting pharmaceutical R&D budgets, regulatory divergence between transatlantic jurisdictions, or breakthrough advances in cell-based assay automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
North America Biobanks Market
Medical Research
Europe AMH Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Metabolomics Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
Life Science R&D Infrastructure Outsourcing Market
Medical Research
Placenta Market
Medical Research
Forensic Medicine Market
Medical Research
Preventive Medicine Market
Medical Research
Epigenetics Market
Medical Research
Cancer Mouse Models Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Mice Model Technologies Market
Medical Research
Global Human Liver Models Market
Medical Research
Health Economics and Outcomes Research (HEOR) Services Market