
 Americas Gerd and Nerd Treatment Market | 2026-2036
Americas Gerd and Nerd Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Gerd and Nerd Treatment Market Outlook
Gastroenterology-trained clinician availability is bifurcating market access between metropolitan centers and underserved peripheries across the Americas. AstraZeneca leverages its established PPI portfolio to sustain formulary dominance in U.S. hospital systems. Takeda Pharmaceutical anchors its position through specialized gastrointestinal R&D operations in North and South American markets. Pfizer competes via broad commercial infrastructure that extends reach into Latin American clinic networks.
Gastroesophageal reflux disease and non-erosive reflux disease treatment encompasses pharmacological interventions that modulate gastric acid secretion through proton pump inhibition, histamine receptor blockade, or mucosal neutralization, primarily to prevent esophageal mucosal injury and manage refractory symptoms. Proton pump inhibitors occupy the largest therapeutic share due to superior healing rates in erosive disease, while H2-receptor antagonists retain niche utility in maintenance regimens and cost-sensitive settings. The oral delivery mode dominates prescribing patterns, though injectable formulations command premium positioning in perioperative and intensive care applications across hospital end users.
The U.S. FDA maintains stringent requirements for long-term safety documentation in acid suppression therapies, directly influencing clinical trial design and label expansion timelines for manufacturers. Health Canada and Brazil's ANVISA apply parallel pharmacovigilance standards that shape regional product registration strategies and post-market surveillance obligations. Stakeholders must monitor evolving reimbursement criteria from CMS and private payers, as value-based contracting for chronic disease management redefines competitive positioning in this therapeutic space.
Market Dynamics
The U.S. FDA's evolving guidance on long-term proton pump inhibitor safety is bifurcating prescribing patterns between chronic maintenance regimens and intermittent symptom control, forcing formulary repositioning across hospital systems and retail pharmacy networks throughout the Americas.
Growth Catalysts
- Private insurance expansion in Brazil:Diagnostic infrastructure investments across São Paulo and Rio de Janeiro state corridors are accelerating endoscopy access and treatment identification rates.
- CMS value-based contracting frameworks:Chronic disease management incentives are extending reimbursement coverage for step-therapy protocols that prioritize acid suppression efficacy metrics.
- Specialty pharmacy channel penetration:Direct-to-patient distribution models are broadening access to branded PPI formulations in Mexican and Colombian urban centers.
Market Restraints
- Generic omeprazole commoditization:Price compression in oral PPI segments limits branded product margin expansion across Latin American retail pharmacy chains.
- Long-term safety documentation requirements:FDA-mandated cardiovascular and renal monitoring protocols extend clinical trial timelines and raise development costs for next-generation acid suppression candidates.
- Histamine receptor antagonist substitution:Famotidine and ranitidine alternatives retain formulary positioning in cost-sensitive maintenance settings, constraining PPI volume growth.
Strategic Opportunities
- Underpenetrated Andean corridor:Peru and Ecuador present whitespace for diagnostic infrastructure buildout and physician education programs targeting refractory symptom populations.
- Injectable formulation premiumization:Hospital perioperative and intensive care segments command higher reimbursement rates for intravenous PPI delivery modes.
- Health Canada pharmacovigilance alignment:Parallel regulatory standards with FDA create streamlined registration pathways for products seeking North American market entry.
Industry Challenges
- Gastroenterology specialist scarcity:Trained clinician concentration in metropolitan centers leaves peripheral Latin American regions dependent on primary care diagnosis with higher misclassification rates.
- Post-market surveillance infrastructure:ANVISA's adverse event reporting requirements demand dedicated pharmacovigilance investments that strain mid-market manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Gerd and Nerd Treatment Market |
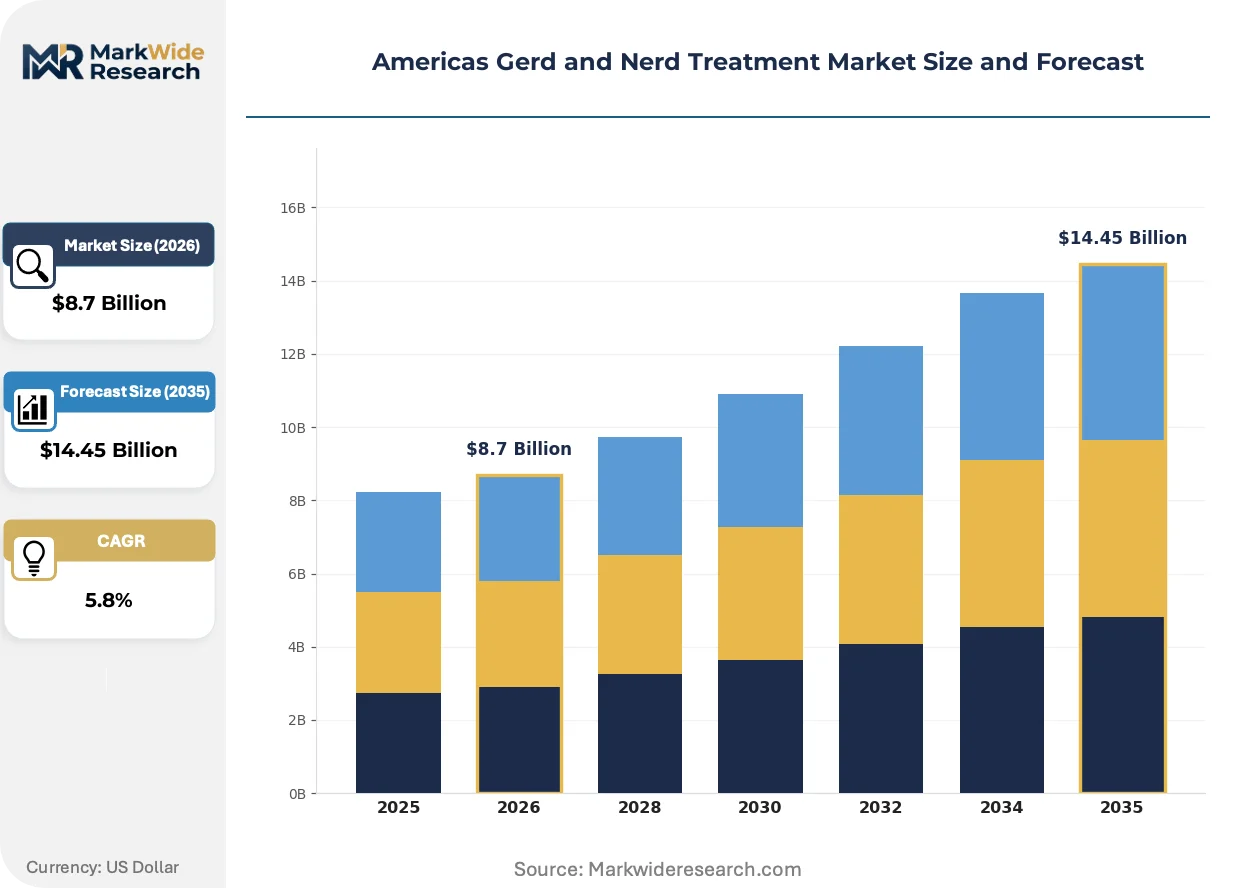
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Pump Inhibitors, H2-Receptor Antagonists, Antacids, Antibiotics End User: Hospital, Clinic, Homecare, Specialty Pharmacy Delivery Mode: Oral, Injectable, Topical, Inhalation Therapy Area: Gastroenterology, Pulmonology, Endocrinology, Nutrition |
| Companies Covered | AstraZeneca, Takeda Pharmaceutical, Pfizer, GlaxoSmithKline, Novartis, Johnson & Johnson, Boehringer Ingelheim, Sanofi, Phathom Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Gerd and Nerd Treatment Market Strategic Shifts
Potassium-competitive acid blockers and novel mucosal protective agents are fragmenting the therapeutic landscape long dominated by proton pump inhibitors, while regulatory pressure on chronic exposure safety and shifting site-of-care preferences reshape commercial priorities.
Potassium-competitive acid blockers such as vonoprazan modulate gastric acid secretion through reversible proton pump inhibition with faster onset kinetics. Academic medical centers in the United States and teaching hospitals in Brazil are piloting these agents for refractory erosive esophagitis cases. This mechanism is fragmenting the chronic therapy market by capturing patients who fail standard PPI induction or require rapid symptom resolution.
Health Canada's tightened requirements for long-term acid suppression safety documentation parallel FDA cardiovascular and fracture risk assessments. Manufacturers must now incorporate renal function monitoring and bone density endpoints into post-approval study commitments. Injectable PPI formulations for hospital end users face the most significant label expansion delays under these standards.
Hospital procurement committees are consolidating acid suppression purchasing through therapeutic class contracts that bundle oral and injectable formulations. Specialty pharmacy distributors in Mexico and Argentina are displacing traditional wholesale channels for chronic maintenance prescriptions. This consolidation is most visible in Brazilian private health networks where diagnostic and therapeutic decisions are increasingly integrated under single payer contracts.
Americas Gerd and Nerd Treatment Market Segmentation
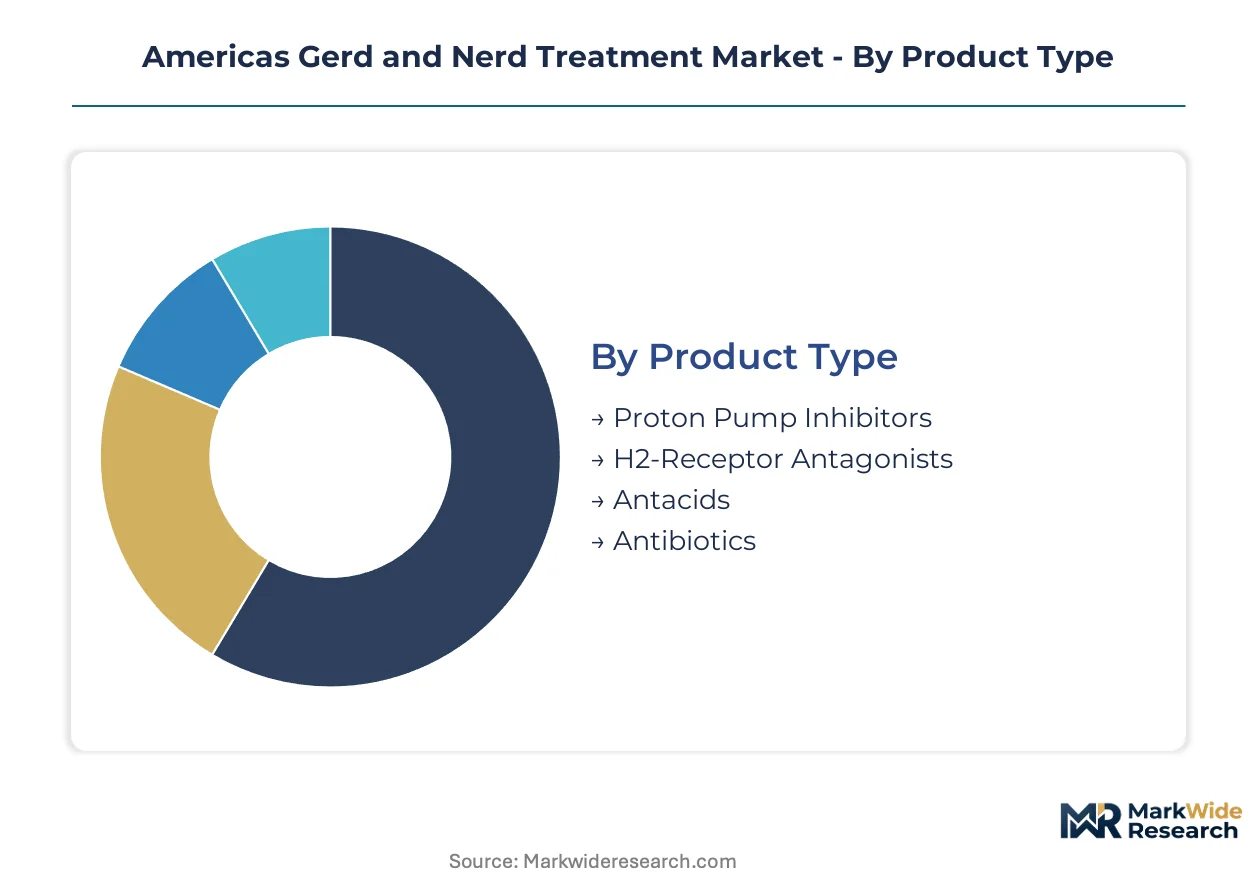
Acid suppression therapies fragment across multiple clinical and commercial dimensions, with reimbursement pathways and site-of-care preferences determining where manufacturers capture sustainable margin. Each segmentation axis reveals distinct competitive dynamics between branded innovators, generic commoditizers, and emerging mechanism specialists.
Product Type:
Margin pools concentrate in chronic maintenance formulations where formulary exclusivity and patent-protected mechanisms command premium pricing against generic substitution pressure.
- Proton Pump Inhibitors:Irreversible hydrogen-potassium ATPase inhibition produces superior healing rates in erosive esophagitis compared to histamine blockade. Demand concentrates in U.S. hospital systems and Brazilian private insurance networks where step-therapy protocols prioritize acid suppression efficacy metrics over acquisition cost.
- H2-Receptor Antagonists:Competitive histamine H2 receptor blockade offers faster tachyphylaxis recovery and lower drug-drug interaction profiles for polypharmacy patients. Famotidine retains formulary positioning in Mexican retail pharmacy chains and Colombian clinic networks where cost-sensitive maintenance regimens dominate prescribing patterns.
- Antacids:Rapid mucosal neutralization through aluminum-magnesium hydroxide combinations addresses breakthrough symptoms without prescription requirements.
- Antibiotics:Helicobacter pylori eradication protocols combine acid suppression with clarithromycin-amoxicillin regimens in refractory cases.
The dominant share belongs to Proton Pump Inhibitors, while Antibiotics is closing the gap fastest through H. pylori resistance-driven combination therapy expansion.
End User:
Procurement consolidation varies sharply across care settings, with integrated delivery networks capturing volume discounts that independent practitioners cannot match.
- Hospital:Perioperative stress ulcer prophylaxis and intensive care acid suppression drive intravenous formulation demand. Injectable PPI procurement committees in São Paulo and Rio de Janeiro teaching hospitals bundle oral and parenteral purchasing through therapeutic class contracts that disadvantage standalone manufacturers.
- Clinic:Outpatient gastroenterology practices in U.S. metropolitan corridors and Mexican urban centers manage refractory symptom populations through diagnostic-therapeutic integration. Endoscopy-equipped facilities capture higher reimbursement rates for procedure-linked prescriptions.
- Homecare:Chronic maintenance therapy distribution through direct-to-patient models expands in Argentine and Colombian markets.
- Specialty Pharmacy:Branded PPI adherence programs and prior authorization management services penetrate Brazilian private health networks.
Hospital channels retain the largest volume concentration, though Specialty Pharmacy is expanding most quickly through chronic disease management contracting.
Delivery Mode:
Formulation technology determines reimbursement tier placement and manufacturing complexity barriers to generic entry.
- Oral:Enteric-coated delayed-release tablets and capsules dominate maintenance prescribing across all Americas markets. Modified-release formulations in U.S. retail pharmacy networks face immediate-release generic substitution pressure that compresses branded margin.
- Injectable:Intravenous pantoprazole and esomeprazole command premium positioning in perioperative and ICU settings where enteral administration is contraindicated. Brazilian hospital procurement committees prioritize vial presentation and stability profiles for high-acuity applications.
- Topical:Mucosal protective suspensions address oropharyngeal reflux manifestations in select Latin American markets.
- Inhalation:Experimental laryngeal reflux delivery mechanisms remain pre-commercial in academic medical center trials.
Oral formulations capture the dominant patient volume, while Injectable delivery is gaining share fastest through hospital consolidation of acid suppression purchasing.
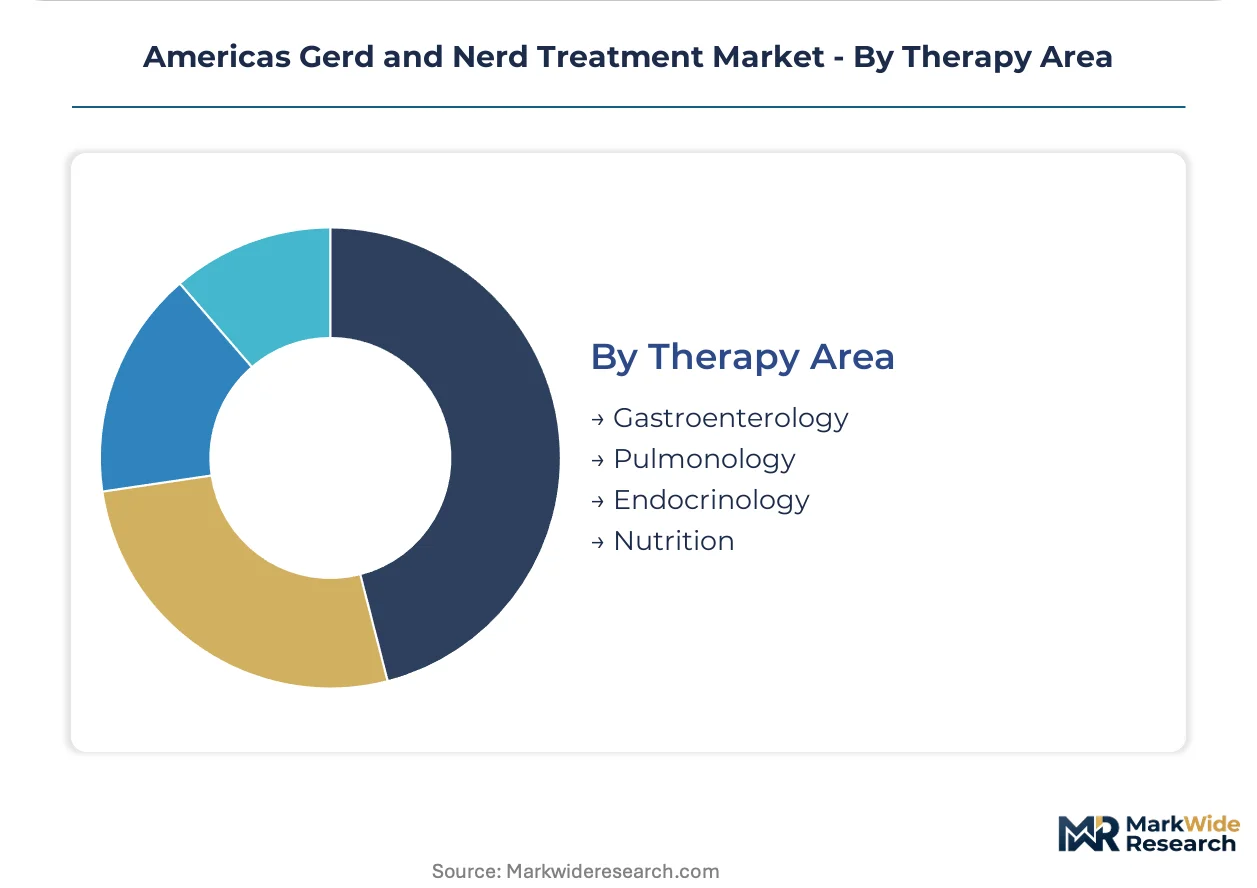
Therapy Area:
Specialist referral patterns and diagnostic coding specificity determine addressable patient populations and reimbursement validation requirements.
- Gastroenterology:Endoscopy-confirmed erosive esophagitis and Barrett's esophagus surveillance drive highest-value prescribing. Trained clinician concentration in U.S. academic medical centers and Brazilian southeastern state corridors leaves peripheral regions dependent on primary care diagnosis with elevated misclassification rates.
- Pulmonology:Chronic cough and asthma-exacerbating reflux presentations expand acid suppression indications beyond traditional GI boundaries. Canadian and U.S. pulmonology practices increasingly co-manage refractory respiratory symptoms with gastroenterology referral.
- Endocrinology:Diabetes-associated gastroparesis and delayed gastric emptying complicate reflux management in metabolic syndrome populations.
- Nutrition:Enteral feeding intolerance and post-surgical reflux prevention address institutional long-term care segments.
Gastroenterology maintains the dominant specialty share, while Pulmonology is climbing the fastest through respiratory-reflux comorbidity recognition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Brazilian private insurance networks while Mexican retail pharmacy chains compress margins through generic substitution. This asymmetry shapes manufacturer resource allocation across the Americas therapeutic landscape.
United States
CMS value-based contracting frameworks and FDA long-term safety documentation requirements dominate strategic planning. The U.S. FDA's evolving guidance on cardiovascular and renal monitoring protocols extends clinical trial timelines for next-generation candidates. Academic medical centers in Boston and the Research Triangle pilot potassium-competitive acid blockers for refractory erosive esophagitis cases.
Brazil
Private insurance expansion across São Paulo and Rio de Janeiro state corridors accelerates endoscopy access and treatment identification rates. ANVISA's adverse event reporting requirements demand dedicated pharmacovigilance investments from market entrants. Diagnostic infrastructure buildout concentrates in the southeastern state corridor where integrated payer contracts bundle therapeutic decisions.
Mexico
Specialty pharmacy distributors displace traditional wholesale channels for chronic maintenance prescriptions in Mexico City and Monterrey urban centers. The national pharmaceutical regulator applies parallel standards to FDA guidance that shape regional registration strategies. Cost-sensitive maintenance regimens dominate prescribing patterns in retail pharmacy chains throughout the metropolitan corridor.
Canada
Health Canada's tightened requirements for long-term acid suppression safety documentation parallel FDA cardiovascular and fracture risk assessments. Provincial reimbursement criteria increasingly prioritize step-therapy protocols with acid suppression efficacy metrics. Pulmonology practices in Toronto and Vancouver co-manage refractory respiratory symptoms with gastroenterology referral networks.
Argentina
Direct-to-patient distribution models expand chronic maintenance therapy access through specialty pharmacy channels in Buenos Aires and Córdoba. Economic volatility constrains branded product penetration despite growing diagnostic awareness. Hospital procurement committees in the capital region consolidate acid suppression purchasing through therapeutic class contracts.
Americas Gerd and Nerd Treatment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Americas GERD and NERD treatment market. Branded innovators with patent-protected mechanisms command premium positioning in hospital systems and private insurance networks. Generic commoditizers capture volume through retail pharmacy chains and cost-sensitive maintenance settings. Emerging mechanism specialists fragment the chronic therapy landscape with novel acid suppression technologies. Competitive moves concentrate on formulary exclusivity negotiations and therapeutic class contract consolidation.
Among established pharmaceutical conglomerates, AstraZeneca, Takeda Pharmaceutical, and Pfizer occupy positions that exemplify distinct strategic archetypes. AstraZeneca represents the legacy PPI portfolio defender with sustained formulary dominance in U.S. hospital systems. Takeda Pharmaceutical anchors the specialized gastrointestinal R&D operator model through dedicated operations in North and South American markets. Pfizer exemplifies the broad commercial infrastructure archetype that extends reach into Latin American clinic networks.
| Leading Market Players |
|---|
| AstraZeneca |
| Takeda Pharmaceutical |
| Pfizer |
| GlaxoSmithKline |
| Novartis |
| Johnson & Johnson |
| Boehringer Ingelheim |
| Sanofi |
| Phathom Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at North American API manufacturing facilities shapes both supply concentration and branded product price floors across the Americas GERD and NERD treatment market. Scale advantages in proton pump inhibitor production concentrate active pharmaceutical ingredient sourcing among established manufacturers, while generic commoditization in oral formulations compresses margins and forces supply chain rationalization decisions.
Pricing Analysis
The customization-premium spread separates injectable hospital formulations from standard oral maintenance therapies across Brazilian and U.S. procurement networks. Contract-based long-term offtake agreements dominate hospital system purchasing, with price differentiation driven by FDA certification tier and vertical integration into sterile manufacturing capabilities. Pricing pressure stems from generic omeprazole commoditization in Latin American retail pharmacy chains. Cost-sensitive maintenance regimens in Mexican clinic networks exhibit highest price sensitivity, while perioperative ICU segments show lowest sensitivity due to enteral contraindication requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate hospital procurement for injectable acid suppression therapies, contrasting with just-in-time inventory management in retail pharmacy distribution. Active pharmaceutical ingredient production concentrates in India, China, and the United States for proton pump inhibitor precursors. Finished formulation manufacturing draws from specialized sterile facilities in Brazil and Mexico for regional hospital supply. Single-source vulnerability in potassium-competitive acid blocker API supply creates structural risk for next-generation product launches. Distribution runs through specialty pharmacy channels in Brazilian private networks and consolidated hospital procurement committees in U.S. metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas GERD and NERD treatment market represents a high-growth disruption as potassium-competitive acid blockers fragment proton pump inhibitor dominance and FDA long-term safety documentation requirements reshape competitive entry barriers.
For Market Incumbents: Compound formulary exclusivity through backward integration into sterile injectable manufacturing capacity in São Paulo and Rio de Janeiro state corridors. Secure therapeutic class contract bundling across oral and parenteral formulations before generic vonoprazan entry erodes premium positioning. Prioritize pharmacovigilance infrastructure investments to meet ANVISA adverse event reporting requirements without margin dilution.
For New Entrants and Emerging Players: Anchor in the underpenetrated Andean corridor, specifically Peru and Ecuador diagnostic infrastructure buildout, where gastroenterology specialist scarcity leaves refractory symptom populations misclassified in primary care settings. Target physician education programs paired with direct-to-patient specialty pharmacy distribution as the most penetrable go-to-market angle for novel mucosal protective agents.
For Investors and Strategic Acquirers: Regional specialty pharmacy operators with captive distribution networks in Brazilian private health networks represent the priority acquisition archetype for exposure to chronic maintenance therapy volume growth. Long-term viability hinges on formulary positioning durability through the analysis window. Watch FDA label expansion timelines for potassium-competitive acid blockers as the inflection indicator for mechanism shift acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA long-term safety documentation requirements extend clinical trial timelines for next-generation acid suppression candidates. |
| Manufacturing Scale-Up | Sterile injectable capacity expansion in Brazilian southeastern state corridors captures perioperative and ICU premium segments. |
| Licensing Agreement | Technology licensing for potassium-competitive acid blockers accelerates market entry against established PPI portfolios. |
| Pipeline Diversification | Novel mucosal protective agents address refractory patient populations failing standard proton pump inhibition. |
| Hospital System Partnership | Integrated payer contracts in São Paulo and Rio de Janeiro bundle diagnostic and therapeutic decisions under single procurement frameworks. |
Study Parameters
Desk research of FDA guidance documents, ANVISA regulatory filings, and hospital procurement databases preceded structured interviews with formulary directors, gastroenterology department heads, specialty pharmacy distribution executives, and payer access specialists across the Americas. Secondary validation drew from ClinicalTrials.gov entries, CMS Medicare reimbursement data, and Brazilian private health network contract disclosures. Bottom-up patient flow modeling and top-down pharmaceutical market sizing were triangulated against manufacturer revenue disclosures.
Variance decomposition across product type, delivery mode, end user, and therapy area segmentation dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from normalized baseline year values and endpoint projections across modeled scenarios. Forecast inputs incorporated FDA label expansion probability assessments and Brazilian private insurance enrollment trajectories as industry-specific demand drivers.
Material uncertainties — regulatory guidance revisions, generic entry timing, and reimbursement policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued proton pump inhibitor formulary dominance and potassium-competitive acid blocker adoption curves. Revision becomes warranted when FDA cardiovascular safety signal thresholds trigger class-wide label modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Chemotherapy Induced Thrombocytopenia Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Global Scleroderma Diagnostics and Therapeutics Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Global Liver Cancer Therapeutics Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Rhabdomyosarcoma Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Cirrhosis Management Market