
 India Computer-Aided Drug Discovery Market | 2026-2036
India Computer-Aided Drug Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
India Computer-Aided Drug Discovery Market Insights
The gap between premium molecular simulation suites and commodity docking tools is broadening as Indian pharmaceutical researchers demand physics-based precision for novel target classes. Syngene International sustains one of India's largest captive computational chemistry divisions, while Piramal Pharma Solutions anchors its Mumbai operations with integrated AI-driven lead optimization. Schrödinger, Inc. competes through specialized software licensing that extends across domestic biotech partnerships.
Computer-aided drug discovery encompasses computational methods that predict molecular binding affinity, optimize pharmacokinetic profiles, and simulate protein-ligand interactions using force-field equations and statistical algorithms. These tools serve the primary commercial purpose of reducing wet-laboratory attrition rates before candidate nomination. Virtual screening leads technology adoption among Indian contract research organizations seeking throughput scalability, while oncology commands the dominant application share as domestic biotech firms prioritize immuno-oncology pipelines. Software-as-a-Service solutions are expanding fastest where smaller biotechnology firms avoid capital-intensive in-house server deployments.
India's CDSCO mandates computational toxicology dossiers for certain new drug applications, while the Department of Biotechnology oversees bioinformatics infrastructure grants that shape domestic capability distribution. BIS standards for software validation in regulated pharmaceutical environments further constrain vendor qualification pathways. Stakeholders must monitor how evolving data localization requirements affect cloud-based platform architectures and cross-border collaboration protocols.
Market Dynamics
Physics-based molecular simulation is displacing empirical scoring functions across Indian pharmaceutical R&D, as domestic biotech firms prioritize target classes where traditional docking algorithms fail.
Growth Catalysts
- PLI scheme for pharmaceuticals:The Production Linked Incentive scheme is accelerating domestic computational infrastructure investment, reducing reliance on offshore cloud processing for sensitive molecular data.
- Hyderabad's biotech corridor:Concentrated contract research clusters in Telangana are anchoring specialized talent pools that attract multinational pharma partnerships.
- Immuno-oncology pipelines:Domestic biotech firms are prioritizing novel biological targets that demand advanced in silico modeling capabilities.
Market Restraints
- GPU compute costs:Molecular dynamics simulations require sustained access to high-performance NVIDIA A100/H100 clusters, where import duties and supply constraints inflate operational expenditure.
- Data localization requirements:Evolving cross-border data transfer restrictions complicate cloud-based platform architectures for multinational collaborations.
- Force-field parameter limitations:Standard Amber and CHARMM parameter sets inadequately capture metal-containing active sites and covalent inhibitor chemistries prevalent in emerging target classes.
Strategic Opportunities
- Maharashtra's CRO density:Mumbai-Pune corridor contract research organizations remain underpenetrated for integrated AI-driven lead optimization services combining generative chemistry with ADMET prediction.
- Software-as-a-Service penetration:Smaller biotechnology firms in Bangalore are bypassing capital-intensive server deployments through subscription-based molecular modeling platforms.
- CDSCO computational toxicology mandates:Regulatory requirements for in silico safety dossiers are creating captive demand for validated prediction models among domestic generic manufacturers.
Industry Challenges
- Computational chemist scarcity:The intersection of quantum chemistry training and pharmaceutical domain expertise remains concentrated among alumni of IISc Bangalore and IIT Bombay, constraining workforce scaling.
- BIS software validation timelines:Certification pathways for regulated pharmaceutical environments extend vendor qualification cycles, delaying deployment of updated algorithm versions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Computer-Aided Drug Discovery Market |
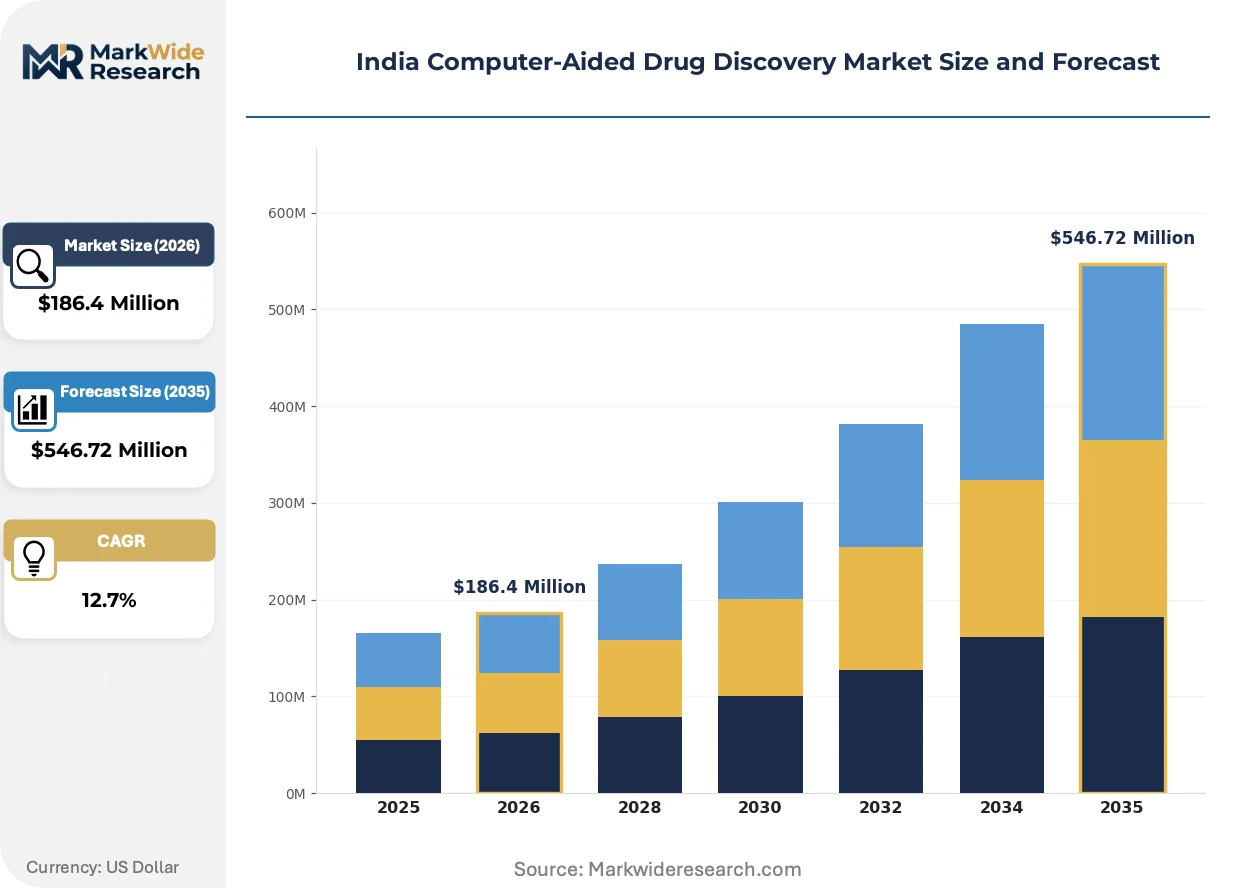
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $546.72 Million |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Molecular Dynamics, Virtual Screening, Quantitative Structure-Activity Relationship Application: Oncology, Neurology, Cardiovascular, Infectious Diseases End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Contract Research Organizations Solution: Software-as-a-Service, In-House Solutions, Outsourced Solutions, Cloud-Based Platforms |
| Companies Covered | Aragen Life Sciences Pvt. Ltd., Syngene International, Piramal Pharma Solutions, Sundia MediTech, Bioduro-Sundia, Schrödinger, Inc., Charles River Laboratories, AstraZeneca, Bayer AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Computer-Aided Drug Discovery Market Trends and Innovations
Generative artificial intelligence is compressing traditional hit-to-lead timelines, forcing restructuring of fee-for-service contract research economics and enabling new pricing models based on candidate quality rather than molecule throughput.
AlphaFold-derived structural models are unifying previously separate workflow stages in Indian drug discovery pipelines. Biotech firms in Hyderabad and Bangalore are adopting these predictions for virtual screening campaigns against targets lacking experimental crystal structures. The technology is unifying structure-based and ligand-based design approaches, reducing the historical premium commanded by specialized crystallography CROs.
CDSCO's expanding computational toxicology requirements are reshaping preclinical documentation standards. Domestic generic manufacturers must now submit QSAR-based mutagenicity predictions alongside traditional Ames test data. Small molecule oncology programs face the steepest compliance burden, driving partnerships with specialized in silico safety providers.
Consolidated platform procurement is displacing point-solution licensing among mid-cap Indian pharmaceutical firms. Mumbai-based formulators increasingly demand integrated environments spanning molecular simulation, property prediction, and regulatory submission tools. This bundling preference is most pronounced among firms with active ANDA filings requiring rapid turnaround on multiple pipeline assets.
India Computer-Aided Drug Discovery Market Segmentation
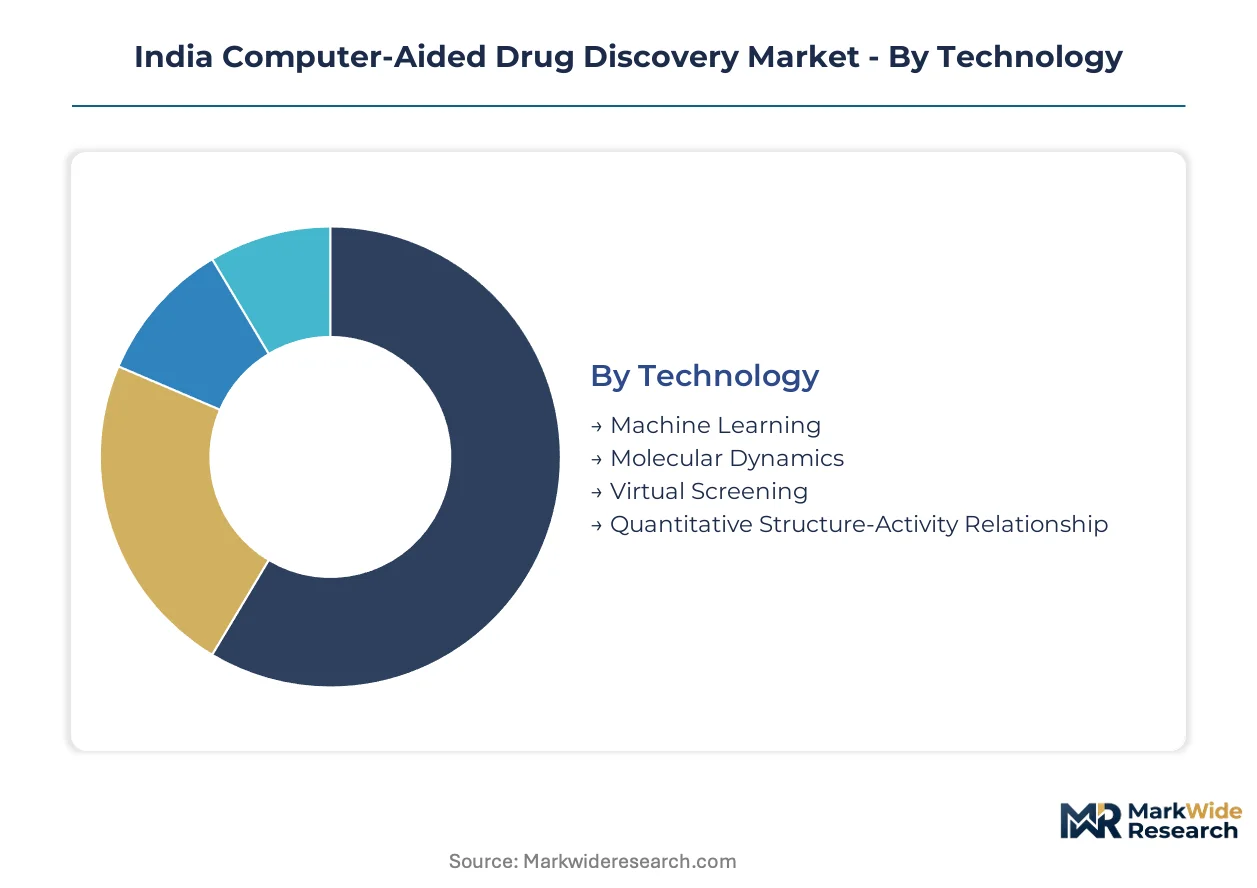
Segmentation in India's computer-aided drug discovery market reveals how regulatory validation requirements, computational infrastructure costs, and talent availability distribute demand across technology categories and customer types. CDSCO submission pathways and BIS software certification standards create divergent compliance burdens that reshape vendor selection criteria for each segment.
Technology:
CDSCO mandates BIS-validated computational toxicology modules for certain new drug applications, concentrating regulatory burden on molecular dynamics and QSAR implementations while virtual screening faces lighter documentation requirements.
- Machine Learning:Neural architectures trained on molecular property datasets predict ADMET profiles and generate novel chemical scaffolds. Demand concentrates among Bangalore biotech firms building proprietary generative chemistry pipelines, constrained by GPU cluster import duties and NVIDIA supply allocation bottlenecks.
- Molecular Dynamics:Physics-based simulation of protein-ligand interactions using force-field equations captures conformational flexibility and binding kinetics. Maharashtra pharmaceutical manufacturers deploy these tools for precise affinity prediction in covalent inhibitor programs, though Amber and CHARMM parameter limitations persist for metal-containing active sites.
- Virtual Screening:High-throughput docking algorithms rank compound libraries against target structures. Telangana contract research organizations leverage this for scalable hit identification.
- Quantitative Structure-Activity Relationship:Statistical models correlating molecular descriptors with biological activity support lead optimization decisions. Domestic generic manufacturers adopt QSAR for CDSCO-mandated mutagenicity predictions.
Leading the category by volume: Virtual Screening. Growing fastest: Machine Learning.
Application:
End-use concentration follows immuno-oncology pipeline investment and the severity of CDSCO preclinical documentation requirements for each therapeutic area.
- Oncology:In silico target validation and lead optimization for kinase inhibitors, immune checkpoint modulators, and antibody-drug conjugates. Hyderabad and Mumbai biotech corridors anchor demand as domestic firms prioritize novel biological targets requiring advanced structural modeling capabilities.
- Neurology:Blood-brain barrier permeability prediction and CNS-targeted library design for neurodegenerative and psychiatric indications. CROs in the Pune cluster develop specialized expertise in this technically demanding segment.
- Cardiovascular:hERG channel liability screening and metabolic stability optimization for chronic disease therapeutics.
- Infectious Diseases:Resistance mechanism modeling and narrow-spectrum antibiotic design addressing AMR priorities.
Oncology commands the dominant revenue share. Neurology exhibits the steepest expansion trajectory as domestic firms diversify beyond oncology concentration.
End User:
Procurement patterns diverge sharply by capital intensity tolerance and captive computational infrastructure ownership.
- Pharmaceutical Companies:Integrated deployment spanning discovery through preclinical phases, with Mumbai-headquartered formulators demanding bundled platforms combining simulation, property prediction, and regulatory submission tools for accelerated ANDA turnaround.
- Biotechnology Firms:Agile adoption of SaaS molecular modeling to bypass server capital expenditure, concentrated in Bangalore's startup ecosystem where venture-backed companies prioritize speed over infrastructure ownership.
- Research Institutes:Academic access to DBT bioinformatics infrastructure grants shapes capability distribution across IISc Bangalore, IIT Bombay, and regional centers.
- Contract Research Organizations:Fee-for-service economics restructuring around candidate quality metrics as generative AI compresses traditional hit-to-lead timelines.
Pharmaceutical companies generate the largest absolute spend. Biotechnology firms are gaining share fastest through SaaS adoption.
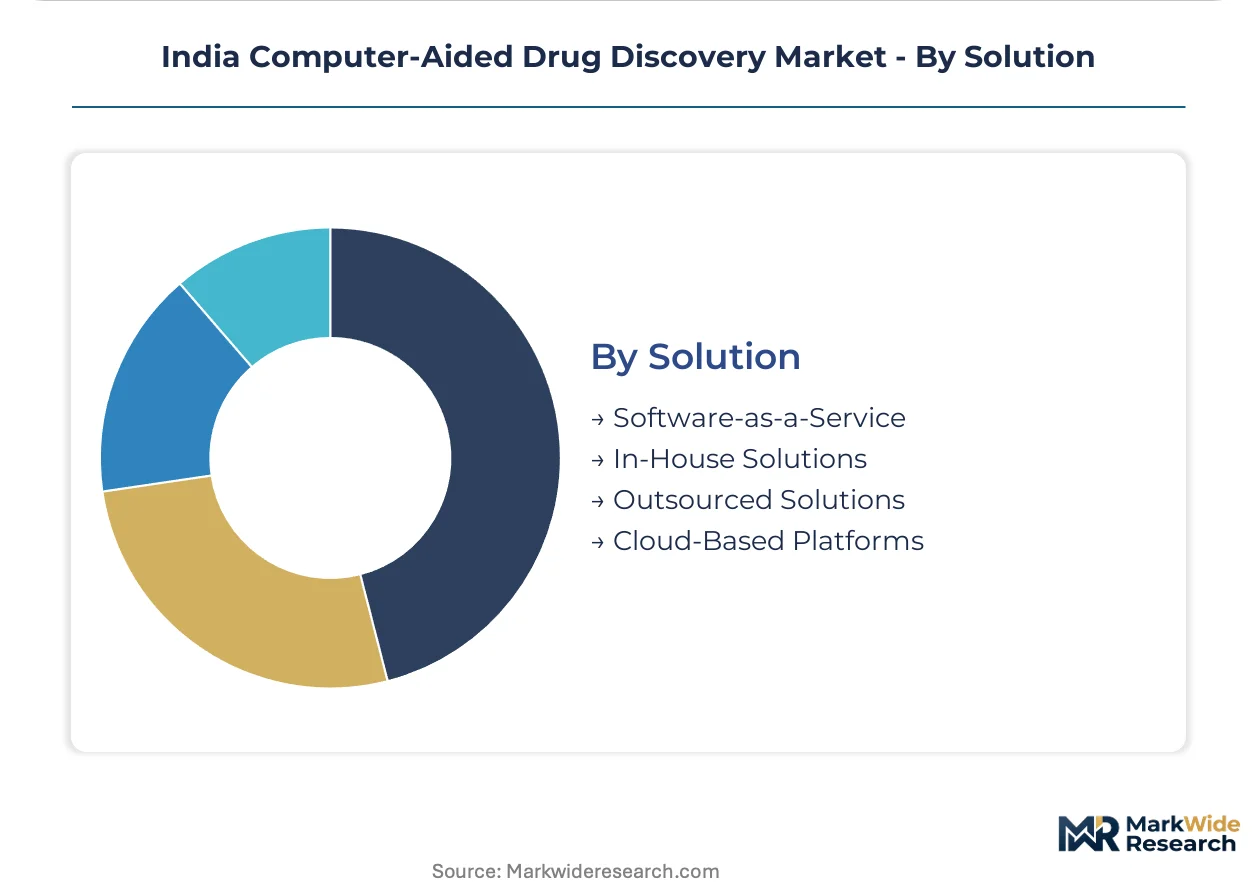
Solution:
Delivery model selection hinges on data localization requirements and cross-border collaboration protocols affecting cloud architecture decisions.
- Software-as-a-Service:Subscription-based access to molecular modeling platforms eliminates server deployment capital requirements. Bangalore's mid-cap biotech sector drives adoption as firms avoid NVIDIA GPU cluster procurement amid import duty inflation.
- In-House Solutions:Captive computational chemistry divisions with dedicated hardware and specialized personnel. Syngene International and Piramal Pharma Solutions anchor this segment with integrated AI-driven lead optimization capabilities.
- Outsourced Solutions:Project-based engagement with specialized computational chemistry providers for discrete modeling tasks.
- Cloud-Based Platforms:Hybrid deployments balancing scalability with data residency compliance for multinational collaborations.
In-House Solutions retain the largest installed base. Software-as-a-Service is climbing the fastest as capital constraints reshape procurement preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad's biotech corridor anchors India's computer-aided drug discovery concentration, with Telangana's Genome Valley hosting specialized contract research clusters that attract multinational pharmaceutical partnerships and domestic computational chemistry investment.
Maharashtra
Mumbai-Pune corridor pharmaceutical manufacturers drive demand for integrated AI-driven lead optimization platforms combining generative chemistry with ADMET prediction. CDSCO's computational toxicology mandates reshape preclinical documentation standards for domestic generic manufacturers filing ANDAs. CRO density in this western corridor remains underpenetrated for bundled simulation and regulatory submission tools.
Telangana
Hyderabad's concentrated contract research clusters anchor specialized talent pools in molecular dynamics and virtual screening capabilities. The state's biotechnology policy frameworks complement central PLI scheme incentives for domestic computational infrastructure. Genome Valley facilities are expanding in silico modeling capabilities to serve immuno-oncology pipelines prioritizing novel biological targets.
Karnataka
Bangalore's venture-backed biotechnology ecosystem favors SaaS molecular modeling platforms that bypass capital-intensive NVIDIA GPU cluster procurement. Department of Biotechnology bioinformatics infrastructure grants shape capability distribution across Indian Institute of Science and regional research centers. Mid-cap firms in this southern hub are adopting subscription-based platforms to avoid server deployment expenditure.
Andhra Pradesh
Visakhapatnam pharmaceutical manufacturing zones are emerging as secondary demand centers for validated QSAR prediction models. State-level life sciences policies support computational chemistry workforce development through university-industry partnerships. Coastal corridor facilities are integrating cloud-based platform architectures to meet evolving data localization requirements for multinational collaborations.
Delhi-NCR
National capital region research institutes access centralized bioinformatics infrastructure grants that shape domestic capability distribution across northern India. Proximity to CDSCO headquarters accelerates regulatory compliance pathways for computational toxicology dossier submissions. Academic centers in this northern cluster are training computational chemists at the intersection of quantum chemistry and pharmaceutical domain expertise.
India Computer-Aided Drug Discovery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the physics-based precision spectrum, with integrated platform providers commanding higher value capture than point-solution vendors. The vendor base stratifies between captive computational chemistry divisions, specialized software licensors, and fee-for-service contract research organizations. Three archetypes dominate: integrated pharmaceutical service providers with in-house simulation capabilities, pure-play software vendors licensing molecular modeling suites, and contract research organizations restructuring economics around generative AI outputs. Competitive moves concentrate on strategic partnerships for GPU cluster access and portfolio diversification into regulatory-compliant prediction modules.
Within the integrated service provider tier, Syngene International and Piramal Pharma Solutions exemplify archetypes combining captive computational chemistry with pharmaceutical manufacturing scale. Schrödinger, Inc. occupies a distinct position as a specialized software licensor extending across domestic biotech partnerships. These three entities represent the structural spectrum from fully integrated in-house solutions to pure-play platform licensing, with each archetype responding differently to CDSCO validation requirements and BIS software certification timelines that constrain vendor qualification pathways.
| Leading Market Players |
|---|
| Aragen Life Sciences Pvt. Ltd. |
| Syngene International |
| Piramal Pharma Solutions |
| Sundia MediTech |
| Bioduro-Sundia |
| Schrödinger, Inc. |
| Charles River Laboratories |
| AstraZeneca |
| Bayer AG |
| Others |
Pricing and Supply Chain Analysis
NVIDIA A100/H100 GPU cluster procurement costs cascade through three distinct pricing tiers for molecular simulation software, with import duty-inflated hardware expenses compressing margins for captive in-house deployments while subscription-based SaaS platforms capture mid-market biotechnology firms seeking to bypass capital expenditure entirely.
Pricing Analysis
Value-based pricing anchored to candidate quality metrics is displacing throughput-based fee structures as generative AI compresses traditional hit-to-lead timelines. Three-tier pricing structure across premium physics-based simulation suites, standard virtual screening platforms, and economy QSAR tools reflects BIS certification grade and computational precision. Cost compression in the economy tier intensifies because domestic generic manufacturers prioritize CDSCO-compliant mutagenicity prediction modules over molecular dynamics fidelity. Biotechnology firms in Bangalore exhibit highest price sensitivity, while integrated pharmaceutical service providers in Mumbai demonstrate lowest sensitivity due to bundled platform procurement preferences.
Supply Chain Analysis
Dual-sourcing requirements for GPU compute infrastructure mandate qualification of both NVIDIA direct channels and authorized distributor networks, though supply allocation bottlenecks constrain actual multi-vendor deployment. Hardware concentration centers on USA and Taiwan for semiconductor fabrication, with final assembly and logistics hubs in China and Malaysia. The supply chain draws from specialized force-field parameter libraries developed in USA and Europe, alongside open-source Amber and CHARMM distributions. Single-source vulnerability persists for H100 cluster availability amid export control restrictions. Distribution runs through direct enterprise licensing for pharmaceutical incumbents, cloud marketplace provisioning for SaaS adopters, and systems integrator channels for hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing downstream control over regulatory-compliant prediction modules to capture CDSCO submission pathway value that standalone software vendors cannot access.
For Market Incumbents: To counter SaaS-based disruption from agile biotechnology entrants, Syngene International and Piramal Pharma Solutions should deepen captive GPU cluster ownership through PLI scheme infrastructure grants, while accelerating BIS certification timelines for proprietary force-field implementations to maintain regulatory moats against pure-play software licensors. For New Entrants and Emerging Players: Cloud-native platform architectures offer the most penetrable entry vector for mid-cap firms in the Maharashtra CRO corridor, where bundled simulation and regulatory submission tools remain underpenetrated. Target the Mumbai-Pune generic manufacturer segment with outcome-based pricing tied to ANDA approval acceleration, leveraging subscription models to bypass incumbent hardware advantages. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized computational toxicology providers with validated QSAR modules in Telangana and Karnataka, where DBT infrastructure grants have created capability clusters without sustainable revenue models. Long-term viability hinges on regulatory submission integration rather than point-solution licensing. Watch CDSCO expansion of computational dossier requirements as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GPU Cluster Captive Ownership | PLI scheme subsidies reduce operational expenditure for molecular dynamics-intensive pipelines. |
| BIS Certification Acceleration | Compressed validation timelines enable faster deployment of updated algorithm versions. |
| Regulatory Submission Integration | CDSCO-compliant toxicology modules capture value inaccessible to standalone simulation vendors. |
| SaaS Platform Migration | Subscription models attract Bangalore biotech firms avoiding NVIDIA import duty exposure. |
| Force-Field Parameter Development | Proprietary metal-site and covalent inhibitor capabilities differentiate physics-based offerings. |
Research Methodology
Document review covered CDSCO regulatory filings, BIS software certification standards, and PLI scheme implementation guidelines, complemented by interviews with computational chemistry division heads at integrated service providers, regulatory affairs leads at domestic generic manufacturers, and platform engineering directors at SaaS molecular modeling vendors. Secondary sources included Department of Biotechnology infrastructure grant disclosures, contract research organization service catalogs, and hyperscaler cloud marketplace provisioning data. Bottom-up triangulation across technology adoption curves and top-down validation against pharmaceutical R&D expenditure patterns anchored market sizing.
Segment-level projections incorporated technology deployment model, end-user capital intensity tolerance, and regional regulatory cluster differentiation across the analysis window. CAGRs derived from fitted growth curves against historical software licensing revenue patterns and infrastructure investment trajectories. Industry-specific inputs included GPU cluster import duty elasticity and CDSCO computational toxicology mandate expansion timelines.
The model holds under stable BIS certification timelines and continued PLI scheme funding; deviation in data localization enforcement stringency or NVIDIA supply allocation restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Malaria Vaccine Market
Medical Research
Mice Model Technologies Market
Medical Research
Clinical Genomics Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
Global Humanized Mouse Model Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Epigenetics Market
Medical Research
North America Biobanks Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
Human Osteoblasts Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
Preventive Medicine Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Global Human Liver Models Market
Medical Research
Organoids and Spheroids Market