
 Precipitated Calcium Carbonate Market | 2026-2036
Precipitated Calcium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Precipitated Calcium Carbonate Market Intelligence
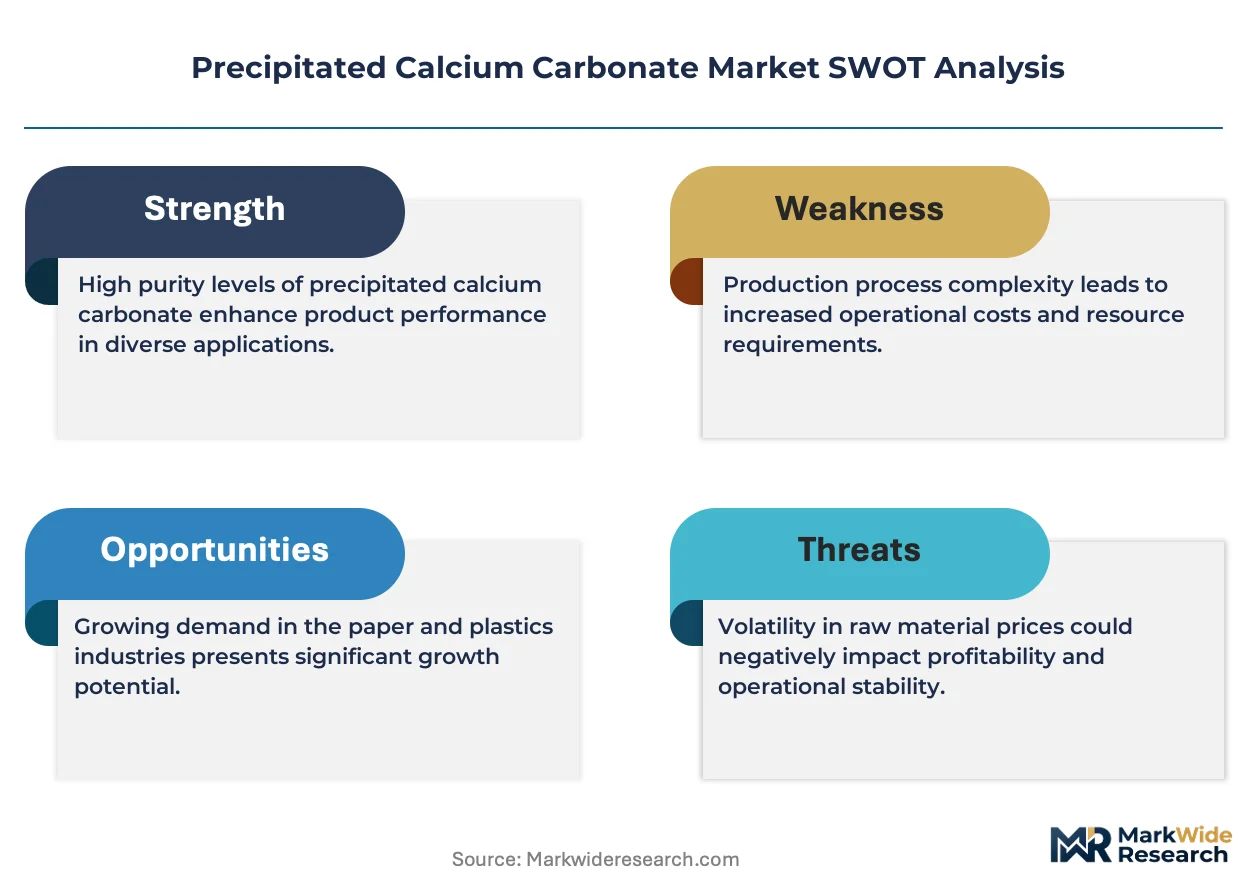
Aftermarket technical service revenue is reshaping margin pools in precipitated calcium carbonate, pulling value from commodity volume contracts toward formulation support and custom particle engineering. Omya AG leverages its global mineral processing network to sustain premium positioning in coated grades for barrier films. Imerys S.A. anchors European supply through integrated limestone-to-PCC operations in Belgium and France. Minerals Technologies Inc. competes via specialized satellite plant installations at paper mill sites, cutting logistics costs and securing offtake.
Precipitated calcium carbonate is a synthetically produced, ultrafine calcium carbonate precipitated from calcium hydroxide and carbon dioxide, typically achieving particle sizes of 0.5–7.0 micrometers and brightness levels exceeding 95 percent for high-grade applications; manufacturers engineer crystal morphology—aragonite, calcite, or vaterite—to tailor opacity, viscosity, and reinforcement in target matrices. Coated PCC dominates pulp and paper applications where surface-treated particles enhance gloss and printability, while micronized grades capture expanding plastics compounding demand as talc and kaolin replacements. Uncoated PCC remains mature in bulk construction filler uses where price sensitivity limits margin expansion, and granulated formats serve agricultural liming with lower processing intensity.
EPA effluent guidelines govern wet-process plant discharge limits in the United States, while REACH registration requirements in Europe mandate full toxicological dossiers for imported PCC, raising compliance costs for non-EU suppliers. FDA food additive regulations and USP monograph standards shape pharmaceutical-grade PCC specifications, filtering market access to certified producers. Stakeholders must monitor evolving ECHA restrictions on nano-scale calcium carbonate classifications and paper industry decarbonization timelines that could redirect investment toward on-site CO2 capture integration at precipitation facilities.
Market Dynamics
Asia-Pacific specialty paper mills are pulling precipitated calcium carbonate demand toward micronized and surface-coated grades as packaging board expansion accelerates and FDA purity mandates tighten for food-contact applications.
Growth Catalysts
- REACH registration requirements:European toxicological dossier mandates filter out non-certified suppliers, consolidating volume toward compliant producers in Belgium and France.
- Bioplastic filler substitution:Compounding lines in India and China replace talc and kaolin with coated PCC to meet biodegradability targets in flexible packaging films.
- Satellite plant installations:On-site precipitation facilities at paper mill locations eliminate logistics costs and lock in offtake agreements through captive supply arrangements.
Market Restraints
- Limestone feedstock volatility:Energy-intensive calcination of calcium carbonate ore exposes margins to natural gas price swings in integrated operations.
- EPA effluent discharge limits:Wet-process precipitation facilities face capital-intensive wastewater treatment upgrades to meet tightened discharge thresholds for suspended solids.
- Ground calcium carbonate substitution:Uncoated GCC grades capture bulk construction filler demand where brightness specifications remain below 90 percent.
Strategic Opportunities
- Pharmaceutical-grade USP certification:Antacid and excipient manufacturers seek precipitated calcium carbonate meeting monograph purity standards for direct compression tablet formulations.
- On-site CO2 capture integration:Precipitation plants co-located with industrial emitters secure low-cost carbon dioxide feedstock while qualifying for EU Green Deal transition financing.
- Agricultural granulated formats:Micronized PCC tailored for soil pH correction captures specialty crop segments requiring precision liming below 100-mesh particle distribution.
Industry Challenges
- Particle morphology engineering talent:Crystal habit control for aragonite versus calcite polymorphs requires specialized precipitation chemists in short supply across mineral processing programs.
- ECHA nano-scale classification uncertainty:Pending restrictions on sub-100-nanometer calcium carbonate particles threaten existing pharmaceutical and cosmetic formulation approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precipitated Calcium Carbonate Market |
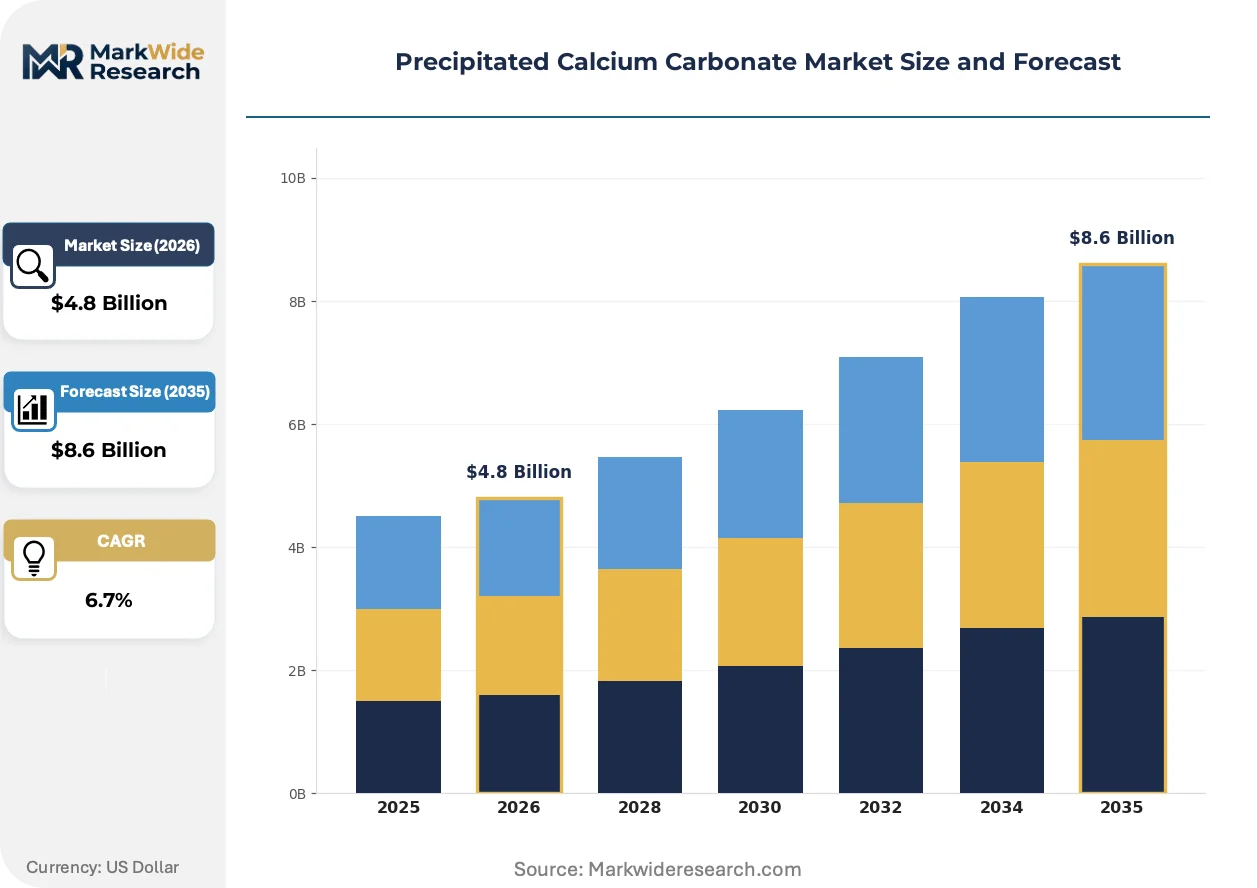
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated, Uncoated, Micronized, Granulated Application: Pulp & Paper, Plastics, Paints, Rubber End User: Construction, Automotive, Consumer Goods, Agriculture Packaging Type: Bulk Bags, Pails, Drums, Sacks |
| Companies Covered | Mississippi Lime Company, Graymont Limited, Omya AG, Nordkalk Corporation, Carmeuse Coordination Center SA, Imerys S.A., Lhoist SA, Huber Engineered Materials, Minerals Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precipitated Calcium Carbonate Market Strategic Shifts & Innovations
Carbon capture integration at precipitation facilities is collapsing the cost structure of synthetic calcium carbonate production while regulatory pressure on packaging recyclability accelerates material substitution cycles across paper and plastics compounding.
Continuous precipitation reactor technology is collapsing batch processing economics in PCC manufacturing. Paper mills in Germany and Japan adopt plug-flow systems that reduce residence time from hours to minutes. This compression of capital intensity per ton is enabling smaller satellite plants at mill sites previously served by distant merchant suppliers.
EU Green Deal carbon border adjustment mechanisms are redirecting import flows toward certified low-carbon precipitation routes. REACH-registered producers with integrated CO2 capture gain preferential access to pharmaceutical and food-grade segments. Belgian and French operations now anchor European supply through verified lifecycle assessments meeting CSRD disclosure requirements.
Buyer consolidation among multinational packaging converters is compressing supplier qualification timelines. Tier-one board producers in India and China unbundle technical service contracts from volume commitments, forcing merchant PCC suppliers to embed formulation support teams at customer R&D centers. This service-layer competition favors processors with global mineral networks over regional commodity traders.
Precipitated Calcium Carbonate Market Segmentation
Crystal morphology and surface treatment specifications determine price realization across precipitated calcium carbonate grades. Segmentation reveals how particle engineering separates commodity volume from premium-margin applications in paper, plastics, and pharmaceutical end-uses.
Product Type:
Mature bulk formats coexist with emerging precision-engineered grades as paper mills and compounders diverge in technical requirements.
- Coated:Surface-treated with fatty acids or silanes to enhance hydrophobicity and dispersion in polymer matrices. Specialty packaging board producers in India and China specify coated PCC to meet FDA food-contact purity mandates for direct food barrier films.
- Micronized:Ultrafine particles below 2.0 micrometers engineered for high-loading plastic compounding where brightness and reinforcement replace talc. Bioplastic manufacturers in Asia-Pacific adopt micronized grades to satisfy biodegradability certification requirements in flexible packaging applications.
- Uncoated:Standard precipitation product serving bulk construction filler demand where brightness thresholds remain below 90 percent and price sensitivity dominates procurement decisions.
- Granulated:Agglomerated format for agricultural liming with controlled dissolution rates; precision crop segments in specialty farming drive specification of sub-100-mesh particle distribution.
Coated PCC retains volume leadership; micronized grades hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity pulp applications from performance-driven plastic and coating segments.
- Pulp & Paper:Dominant consumption channel where PCC functions as filler and coating pigment to enhance opacity, brightness, and printability. Integrated satellite plants at mill sites in Germany and Japan eliminate logistics costs through captive precipitation supply.
- Plastics:Compounding lines specify engineered PCC to reduce density and improve dimensional stability in injection-molded automotive and consumer goods components.
- Paints:TiO2 extension applications leverage PCC brightness and fine particle size to reduce titanium dioxide loading in architectural coatings.
- Rubber:Reinforcement and processing aid functions in tire and industrial rubber manufacturing where particle size distribution affects cure characteristics.
Pulp and paper commands the largest volume position; plastics compounding is climbing the fastest.
End User:
Customer type diversity spans project-based construction procurement to continuous manufacturing in automotive and consumer goods.
- Construction:Bulk filler demand for cement, concrete, and sealant applications where uncoated PCC competes directly with ground calcium carbonate on delivered cost.
- Automotive:Lightweighting initiatives in interior and under-hood components drive specification of coated and micronized grades for thermoplastic polyolefin compounds.
- Consumer Goods:Food packaging, personal care, and pharmaceutical applications requiring REACH-registered or FDA-certified PCC with documented purity dossiers.
- Agriculture:Soil pH correction and animal feed supplement uses where granulated formats reduce dust generation versus powdered alternatives.
Construction absorbs the highest tonnage; consumer goods delivers the strongest margin expansion.
Packaging Type:
Supply concentration in merchant distribution channels shapes packaging format selection for regional versus export markets.
- Bulk Bags:One-ton flexible intermediate bulk containers dominate paper mill and large compounder deliveries where pneumatic handling systems enable direct silo transfer.
- Sacks:Multi-wall paper or woven polypropylene bags for mid-volume customers lacking bulk handling infrastructure; standard unit sizes range from 25 to 50 kilograms.
- Drums:Fiber or steel drums for pharmaceutical and food-grade PCC requiring contamination protection and lot traceability through sealed packaging.
- Pails:Smallest format for laboratory, sampling, and specialty compounding operations where moisture exclusion and handling convenience outweigh unit cost premiums.
Bulk bags retain volume leadership; drums command the highest per-kilogram realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India consume precipitated calcium carbonate through packaging board expansion, while European demand concentrates in pharmaceutical-grade certification and integrated CO2 capture systems. The United States splits consumption between paper mill satellite plants and construction filler applications with divergent purity specifications.
China
Specialty paper mills in Shandong and Jiangsu provinces drive coated PCC consumption for food-contact barrier films. SAMR's tightened GB standards for food packaging materials filter import flows toward REACH-registered suppliers with documented purity dossiers. The Yangtze River Delta hosts precipitation facilities co-located with steel and cement plants capturing industrial CO2 for synthetic carbonate feedstock.
India
Bioplastic compounders in Maharashtra and Gujarat replace talc with micronized PCC to meet FSSAI biodegradability mandates for flexible packaging. The PLI scheme for advanced materials supports domestic precipitation capacity expansion near paper mill clusters. Ahmedabad and Vadodara house formulation support teams from multinational mineral processors embedding technical service at customer R&D centers.
Germany
Continuous precipitation reactor technology at satellite plants in Lower Saxony eliminates logistics costs through captive supply to pulp mills. ECHA's pending nano-scale calcium carbonate classifications pressure pharmaceutical formulators to validate particle size distributions. The Ruhr industrial corridor integrates precipitation facilities with on-site CO2 capture qualifying for EU Green Deal transition financing.
United States
Paper mills in Wisconsin and Alabama operate satellite precipitation plants cutting delivered costs versus merchant supply. EPA effluent guidelines for wet-process discharge limits drive capital-intensive wastewater treatment upgrades at legacy facilities. FDA food additive regulations shape pharmaceutical-grade PCC specifications for antacid and excipient manufacturers in New Jersey and Pennsylvania.
Belgium
Integrated limestone-to-PCC operations anchor European supply for REACH-registered food and pharmaceutical grades. CSRD disclosure requirements favor producers with verified lifecycle assessments meeting EU Green Deal carbon border adjustment mechanisms. The Sambre industrial basin hosts precipitation facilities with captive CO2 from adjacent chemical manufacturing securing low-cost carbon dioxide feedstock.
Precipitated Calcium Carbonate Market Key Industry Players
Capability concentration sits with integrated mineral processors controlling limestone calcination and precipitation chemistry; scale advantage sits with satellite plant operators embedding production at paper mill sites. The vendor base separates into three tiers: multinational mineral networks with global formulation support, regional integrated producers with captive limestone reserves, and merchant suppliers competing on delivered cost to construction filler segments. Dominant competitive moves include backward integration into limestone quarrying and technology licensing for continuous precipitation reactor systems.
Among North American integrated producers, Mississippi Lime Company and Graymont Limited exemplify the limestone-to-carbonate archetype with captive feedstock control. Omya AG occupies a position within the multinational mineral network tier, representing global formulation support capabilities. Imerys S.A. and Minerals Technologies Inc. sit within distinct strategic vectors—European integrated operations versus satellite plant specialization—illustrating how geography and customer proximity shape competitive positioning.
| Leading Market Players |
|---|
| Mississippi Lime Company |
| Graymont Limited |
| Omya AG |
| Nordkalk Corporation |
| Carmeuse Coordination Center SA |
| Imerys S.A. |
| Lhoist SA |
| Huber Engineered Materials |
| Minerals Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Limestone feedstock volatility determines both pricing tier spreads and supply chain shape in precipitated calcium carbonate, as energy-intensive calcination exposes integrated producers to natural gas price swings while forcing merchant suppliers toward long-term offtake structures that lock in volume commitments from paper mills and compounders.
Pricing Analysis
Long-term offtake contracts dominate paper mill procurement, with satellite plant operators securing captive supply agreements that eliminate spot market exposure. Pricing stratifies across pharmaceutical-grade USP certification, food-contact FDA purity tiers, and uncoated construction filler grades. Cost compression in uncoated segments intensifies as ground calcium carbonate substitutes capture bulk applications. Construction buyers exhibit highest price sensitivity; pharmaceutical formulators accept premium realization for documented purity dossiers.
Supply Chain Analysis
REACH registration requirements restrict technology transfer and limit import flows from non-certified suppliers into European pharmaceutical and food-grade segments. Production concentrates in Belgium, France, and China where integrated limestone-to-PCC operations anchor supply. The supply chain draws from high-calcium limestone deposits, carbon dioxide industrial emitters, and fatty acid coating agents. Single-source vulnerability sits with satellite plant operators locked to individual paper mill customers. Distribution runs through bulk bag pneumatic handling systems at mill sites and drum formats for pharmaceutical certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon capture integration at precipitation facilities constitutes a technological inflection reshaping cost structures and regulatory access, positioning early adopters for preferential EU Green Deal financing and pharmaceutical-grade market entry.
For Market Incumbents: Entrench satellite plant networks through captive CO2 supply agreements with adjacent industrial emitters in the Ruhr and Sambre corridors. Deepen backward integration into high-calcium limestone reserves to offset feedstock volatility. Lock in paper mill offtake through embedded formulation support teams that technical service contracts unbundle from pure volume commitments. For New Entrants and Emerging Players: Pursue agricultural granulated formats in specialty crop segments where precision liming below 100-mesh particle distribution commands premium realization absent incumbent concentration. Target micronized grades for bioplastic compounders in Maharashtra and Gujarat seeking talc replacement to satisfy FSSAI biodegradability mandates. Lead with on-site technical service embedding at customer R&D centers rather than commodity volume positioning. For Investors and Strategic Acquirers: Satellite plant specialists with demonstrated CO2 capture integration and REACH registration dossiers present acquisition targets with defendable regulatory moats. Frame long-term viability around pharmaceutical-grade certification expansion and EU carbon border adjustment mechanism compliance. Watch ECHA nano-scale calcium carbonate classification rulings as the signal forcing portfolio repositioning toward verified sub-100-nanometer particle control capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| On-site CO2 Capture Integration | Co-location with steel and cement plants secures low-cost feedstock qualifying for EU Green Deal transition financing. |
| Continuous Precipitation Reactor Deployment | German and Japanese paper mills adopt plug-flow systems collapsing residence time from hours to minutes. |
| Pharmaceutical-Grade USP Certification | Antacid and excipient manufacturers seek documented purity dossiers for direct compression tablet formulations. |
| Satellite Plant Capacity Expansion | On-site precipitation at Wisconsin and Alabama paper mills eliminates logistics costs versus merchant supply. |
| Backward Integration into Limestone Quarries | Captive high-calcium feedstock control offsets natural gas price volatility in integrated calcination operations. |
Research Approach
Desk research of trade flow databases, SEC 10-K filings from listed mineral processors, and ECHA registration dossiers preceded structured interviews with paper mill procurement directors, bioplastic compounder technical leads, pharmaceutical formulation scientists, and precipitation plant operations managers. Primary fieldwork combined with secondary validation from customs records and industry association reports. Bottom-up capacity modeling and top-down demand estimation were triangulated against observed pricing realization across grade tiers.
Assumptions held carbon capture integration timelines and REACH registration compliance rates fixed at observed patterns while varying paper industry decarbonization trajectories and bioplastic substitution elasticities across the projection horizon. Segmentation modeling covered crystal morphology, surface treatment specifications, end-use industry, and regional production hub clusters. CAGRs were derived from installed capacity expansion announcements and downstream demand elasticity estimates. Forecast inputs included natural gas price trajectories affecting calcination economics and FDA purity mandate enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by state-supported Chinese producers or rapid ECHA nano-scale reclassifications would shift outcomes. Material shifts in EU carbon border adjustment mechanism scope or SAMR food packaging standard enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
Global 2-Methylpropene Market
Bulk Chemicals
Ground Calcium Carbonate Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market