
 Furfural Derivatives Market | 2026-2036
Furfural Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Furfural Derivatives Market Analysis
ISO 9001 certification is unwinding competitive access for smaller furfural refiners unable to document continuous quality management. Pennakem, LLC leverages its integrated pine-chemical supply chain to dominate North American furfuryl alcohol output. TransFurans Chemicals bvba anchors European specialty production through dedicated tetrahydrofurfuryl alcohol capacity. Hongye Holding Group Corporation Limited extends its position via captive feedstock from corn cob processing in Shandong Province.
Furfural derivatives comprise furan-ring-based chemicals synthesized from agricultural residues such as corncobs, bagasse, and oat hulls through acid-catalyzed dehydration, serving primarily as bio-based precursors for resins, solvents, and fine chemicals. Furfuryl alcohol leads product type volume due to its entrenched role in foundry binders and corrosion-resistant coatings, while tetrahydrofurfuryl alcohol represents the fastest-expanding category as pharmaceutical formulators substitute it for petroleum-derived polar solvents. Application-wise, solvent-grade derivatives command concentrated margin pools from electronics cleaning and agricultural chemical formulation, whereas intermediate applications compete on scale through bulk supply to polymer resin manufacturers.
EPA industrial chemical oversight and REACH registration requirements in Europe impose purity documentation burdens that favor producers with dedicated analytical laboratories and regulatory affairs staff. China's NMPA and evolving GB standards for chemical intermediates are tightening impurity limits in pharmaceutical-grade furfural acetate, redirecting export-oriented capacity toward higher-specification production. Stakeholders must monitor feedstock cost volatility in corn and sugarcane harvest cycles while evaluating backward integration into agricultural residue collection networks.
Market Dynamics
REACH compliance in Europe is tightening purity thresholds for solvent-grade derivatives, forcing refiners to upgrade analytical infrastructure or exit pharmaceutical supply chains. This regulatory compression is concentrating production among integrated players with captive laboratory capacity.
Growth Catalysts
- Pharmaceutical sector expansion:Bio-based intermediates are displacing petroleum-derived precursors in drug synthesis. Formulators in Germany and Switzerland are qualifying furfural acetate for active pharmaceutical ingredient routes.
- REACH registration momentum:The European Chemicals Agency's substance evaluation program is accelerating documentation for furfuryl alcohol derivatives. Producers with pre-registered dossiers are capturing solvent-grade contracts from electronics cleaners.
- Agrochemical resin demand:Corrosion-resistant furan resins are penetrating pesticide formulation equipment in Shandong Province. Chinese formulators are specifying furfuryl alcohol for tank and pipeline linings exposed to acidic active ingredients.
Market Restraints
- Feedstock cost volatility:Corn cob and bagasse prices fluctuate with North American and Brazilian harvest cycles. Refiners without backward integration into agricultural residue collection face margin compression during drought years.
- Supply concentration risk:Tetrahydrofurfuryl alcohol capacity concentrates in Belgian and Chinese producers. Buyers seeking pharmaceutical-grade material encounter limited qualified supplier pools.
- Substitution pressure from N-methyl-2-pyrrolidone:Electronics cleaners in South Korea are reverting to petroleum-derived polar solvents where furfural derivative purity documentation proves burdensome.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's tightening impurity limits for imported intermediates create first-mover advantage for refiners establishing analytical partnerships with Mumbai and Hyderabad formulators.
- Dual carbon policy alignment:China's MEE carbon intensity targets are redirecting state investment toward bio-based chemical platforms. Furfural derivatives qualify for preferential financing in Shandong and Henan provinces.
- Tetrahydrofurfuryl alcohol-pharma convergence:Solvent substitution programs at Swiss and German contract research organizations are opening specification development partnerships.
Industry Challenges
- ISO 9001 certification timeline:Smaller refiners in Eastern Europe require 18-24 months to document continuous quality management systems. The gap excludes them from electronics and pharmaceutical supply chains.
- Analytical laboratory capex:Gas chromatography-mass spectrometry and inductively coupled plasma equipment for REACH-compliant impurity profiling demands capital allocation exceeding smaller producer balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furfural Derivatives Market |
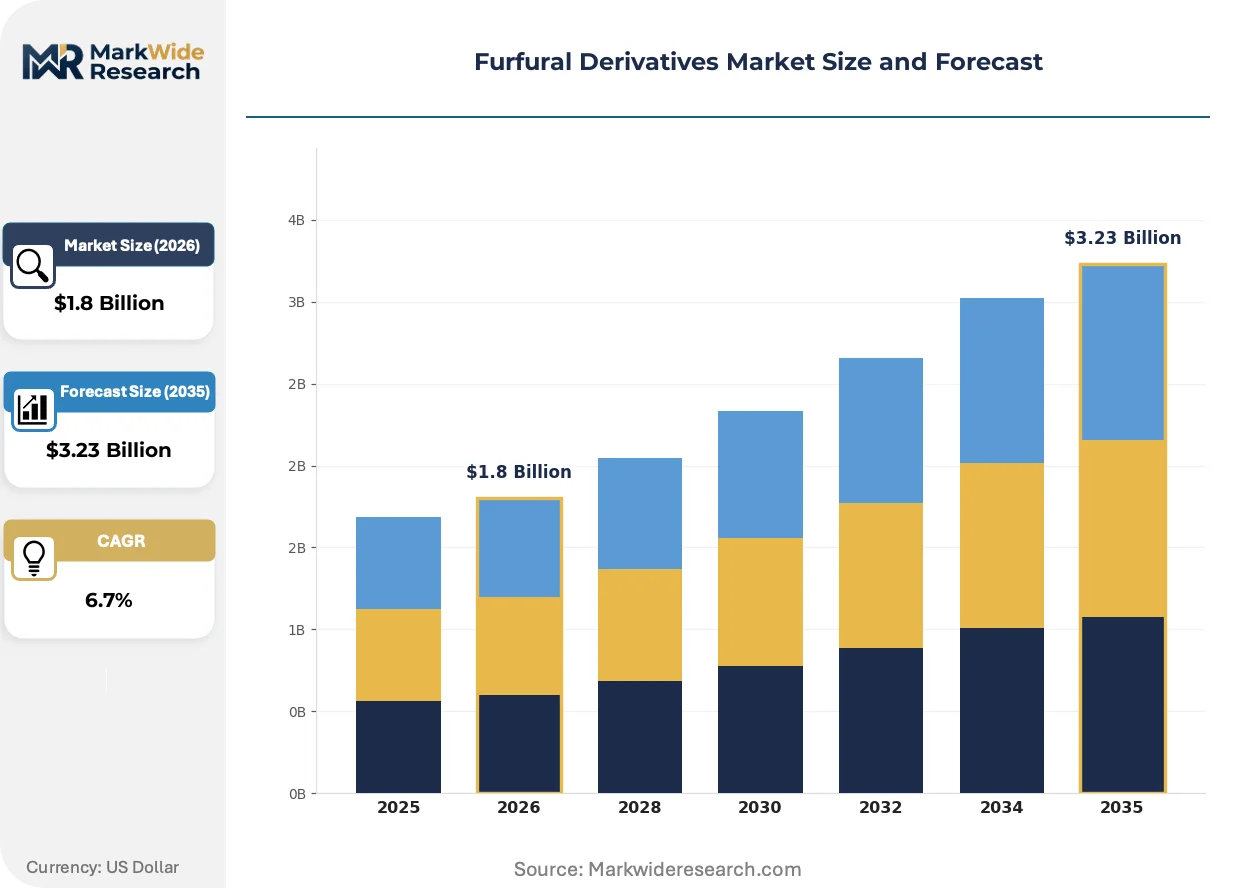
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furfural, Furfuryl Alcohol, Tetrahydrofurfuryl Alcohol, Furfural Acetate Application: Solvent, Intermediate, Reinforcement Agent, Preservative End Use Industry: Chemical, Food & Beverage, Pharmaceutical, Agrochemical Distribution Channel: Direct Sales, Online Retail, Distributors, Exporters |
| Companies Covered | Pennakem, LLC, BASF SE, TransFurans Chemicals bvba, International Furan Chemicals B.V., Hongye Holding Group Corporation Limited, Central Romana Corporation, Ashland, Inc., Silvateam, UBE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furfural Derivatives Market Emerging Trajectories
Process intensification and regulatory chemistry are reshaping competitive capability requirements. Producers are investing in continuous dehydration reactors and closed-loop solvent recovery to meet tightening environmental and purity standards simultaneously.
Continuous acid-catalyzed dehydration reactors are displacing batch furfural production across Chinese and European refineries. Shandong Province operators are retrofitting corncob processing lines with continuous stirred-tank configurations. The technology is displacing legacy batch capacity by cutting steam consumption and enabling real-time impurity monitoring.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone are redirecting electronics cleaning solvent procurement toward tetrahydrofurfuryl alcohol. German and Dutch formulators are submitting downstream user notifications for new supply chain qualifications. The regulation is compressing qualification timelines for pharmaceutical-grade derivative producers with existing ECHA dossiers.
Contract research organizations are unbundling solvent specification development from traditional chemical distribution. Swiss and German pharma service providers are engaging furfural refiners directly for custom purity grades. The pattern is most visible in Basel and Frankfurt clusters where formulation chemistry outsourcing concentrates.
Furfural Derivatives Market Segmentation
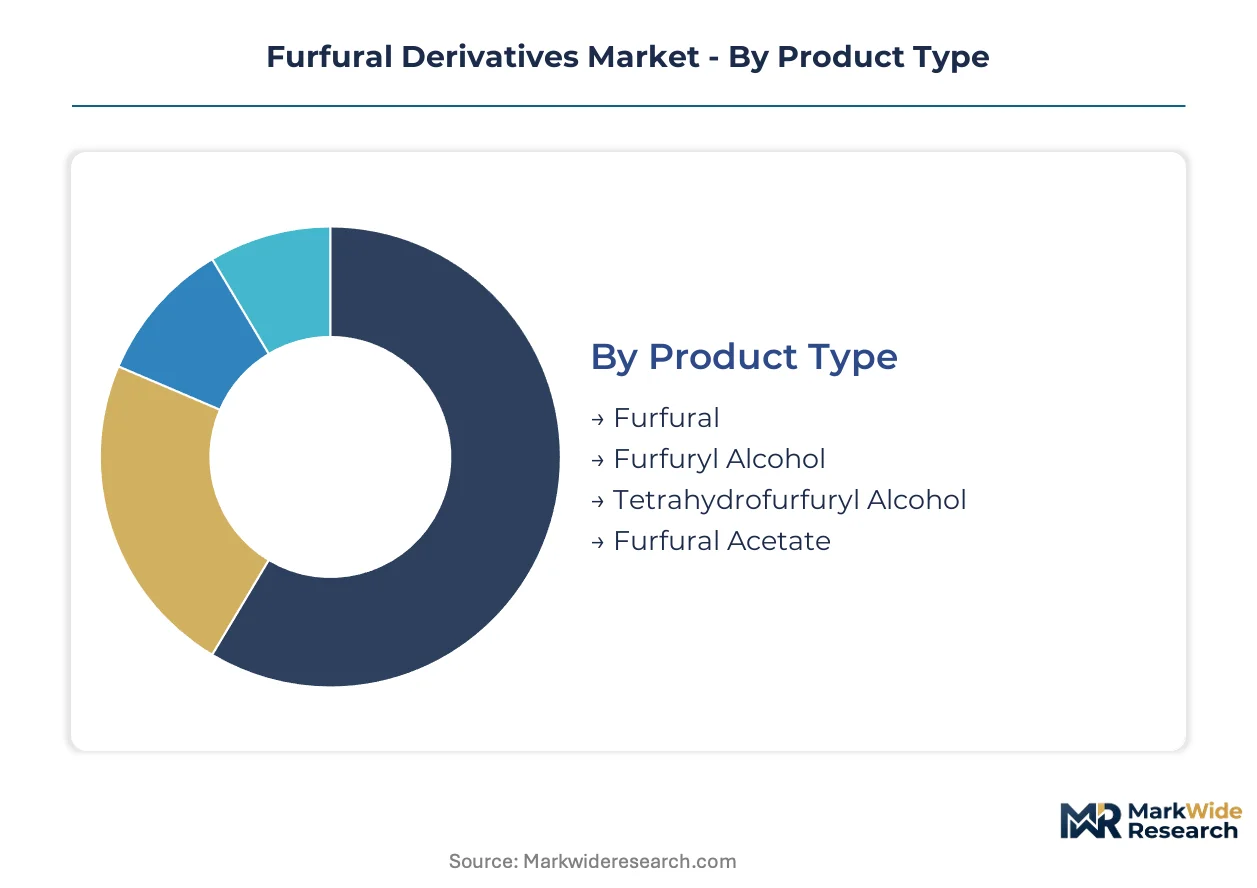
Segmentation in furfural derivatives reveals where bio-based chemistry commands pricing power versus where petroleum substitutes erode margins. Product type stratification separates bulk resin feedstocks from pharmaceutical-grade solvents with tenfold purity documentation cost differentials.
Product Type:
Substitution pressure from N-methyl-2-pyrrolidone and petroleum-derived polar solvents concentrates on lower-purity alcohol grades, while pharmaceutical specifications erect defensive moats around acetate and hydrogenated variants.
- Furfural:The foundational aldehyde extracted from acid-catalyzed dehydration of corncobs and bagasse serves as the primary building block for downstream hydrogenation and acetylation. Chinese agrochemical formulators in Shandong Province source technical-grade material for corrosion-resistant resin synthesis, though solvent applications face displacement by petroleum-derived alternatives where purity documentation costs exceed feedstock savings.
- Furfuryl Alcohol:Hydrogenated furfural yielding the dominant volume segment finds entrenched demand in foundry binder systems and tank linings for acidic pesticide storage. Belgian producers anchor European supply through dedicated continuous reactor capacity, while REACH registration requirements compress qualified supplier pools for electronics cleaning specifications.
- Tetrahydrofurfuryl Alcohol:Complete ring hydrogenation produces the pharmaceutical-grade polar solvent displacing N-methyl-2-pyrrolidone in German electronics cleaning and Swiss drug formulation.
- Furfural Acetate:Esterification product qualified under tightening NMPA impurity limits for active pharmaceutical ingredient intermediates.
Furfuryl alcohol retains volume leadership; tetrahydrofurfuryl alcohol holds the steepest expansion curve.
Application:
Margin architecture across applications reflects the cost tier of downstream customer quality systems, with pharmaceutical and electronics specifications commanding analytical infrastructure investments that exclude commodity refiners.
- Solvent:Electronics cleaning and agricultural chemical formulation drive concentrated margin pools where REACH Annex XVII restrictions on N-methyl-2-pyrrolidone redirect procurement toward tetrahydrofurfuryl alcohol. German and Dutch formulators submit downstream user notifications for new supply chain qualifications, compressing timelines for producers with existing ECHA dossiers.
- Intermediate:Bulk polymer resin supply competes on scale through continuous dehydration reactor economics, with Shandong Province operators retrofitting corncob processing lines to displace legacy batch capacity.
- Reinforcement Agent:Foundry binder applications specify furfuryl alcohol for sand mold strength in ferrous and non-ferrous casting operations.
- Preservative:Food and beverage applications face EFSA safety evaluation thresholds limiting qualified supplier pools.
Solvent applications capture premium pricing tiers; intermediate supply dominates tonnage throughput.
End Use Industry:
Customer maturity across end-use industries determines specification negotiation leverage, with pharmaceutical formulators imposing certificate-of-analysis requirements that smaller refiners cannot satisfy.
- Chemical:Polymer resin manufacturers and specialty solvent blenders constitute the foundational demand base, purchasing furfuryl alcohol and acetate derivatives through long-term offtake agreements tied to agricultural residue harvest cycles.
- Pharmaceutical:CDSCO tightening of impurity limits for imported intermediates creates first-mover advantage for refiners establishing analytical partnerships with Mumbai and Hyderabad formulators.
- Agrochemical:Corrosion-resistant furan resin specifications for pesticide formulation equipment in Shandong Province drive furfuryl alcohol demand for tank and pipeline linings.
- Food & Beverage:Preservative applications navigate EFSA and FDA safety evaluation frameworks with extended approval timelines.
Chemical industry procurement anchors volume; pharmaceutical qualification unlocks margin expansion.
Distribution Channel:
Channel configuration reflects the geographic concentration of qualified production capacity, with direct relationships dominating pharmaceutical supply and distributor networks covering fragmented agrochemical demand.
- Direct Sales:Pharmaceutical-grade and electronics-cleaning specifications require producer-customer analytical partnerships, with Swiss and German contract research organizations engaging refiners directly for custom purity grades.
- Distributors:Regional chemical distributors aggregate demand from fragmented foundry and agrochemical formulators across Eastern Europe and South Asia.
- Exporters:Shandong Province producers ship technical-grade furfuryl alcohol through export traders serving Southeast Asian agrochemical manufacturers.
- Online Retail:Laboratory-scale quantities for research and development procurement.
Direct sales concentrate in pharmaceutical corridors; distributor networks span fragmented industrial demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon policy redirects state investment toward bio-based chemical platforms, while REACH registration requirements in Europe compress qualified supplier pools. Indian pharmaceutical manufacturing expansion creates first-mover openings for analytical partnerships.
China
Shandong Province agrochemical formulators specify furfuryl alcohol for corrosion-resistant tank linings in pesticide equipment. The Ministry of Ecology and Environment's carbon intensity targets qualify furfural derivatives for preferential financing in Henan and Shandong provinces. Corn cob processing clusters in Shandong generate captive feedstock for integrated refiners.
United States
Foundry binder demand in ferrous casting operations sustains furfuryl alcohol consumption across Midwest manufacturing belts. EPA industrial chemical oversight imposes purity documentation burdens favoring producers with dedicated analytical laboratories. Pine-chemical supply chain integration dominates output from Tennessee Valley processing corridors.
Germany
Electronics cleaning formulators submit downstream user notifications for tetrahydrofurfuryl alcohol supply chain qualifications under REACH Annex XVII. The European Chemicals Agency's substance evaluation program accelerates documentation for solvent-grade derivatives. Basel-area contract research organizations engage refiners directly for custom pharmaceutical purity grades.
India
CDSCO tightening of impurity limits for imported intermediates redirects export-oriented capacity toward higher-specification production. Mumbai and Hyderabad pharmaceutical clusters seek analytical partnerships with qualified refiners. Western Maharashtra chemical zones aggregate demand from fragmented agrochemical formulators.
Belgium
TransFurans Chemicals anchors European specialty production through dedicated tetrahydrofurfuryl alcohol capacity. ECHA registration dossiers enable capture of electronics cleaning contracts from Dutch and German formulators. Antwerp-Rotterdam chemical corridor concentration limits qualified supplier pools for pharmaceutical-grade material.
Furfural Derivatives Market Vendor Landscape
Player mix skews toward integrated agrochemical conglomerates with captive feedstock access and specialty chemical refiners with dedicated pharmaceutical-grade capacity. The competitive structure concentrates among producers with backward integration into agricultural residue collection and those with continuous reactor technology. Two strategic archetypes dominate: pine-chemical integrated players leveraging forestry co-product streams, and corn cob processors exploiting China's Shandong feedstock belt. Capacity expansion and REACH dossier pre-registration represent the dominant competitive moves.
Among North American pine-chemical specialists, Pennakem, LLC exemplifies integrated supply chain control. TransFurans Chemicals bvba occupies a position within the European specialty tier, while Hongye Holding Group Corporation Limited represents Chinese agrochemical-integrated production. These three anchors illustrate the geographic and feedstock-based stratification defining competitive positioning.
| Leading Market Players |
|---|
| Pennakem, LLC |
| BASF SE |
| TransFurans Chemicals bvba |
| International Furan Chemicals B.V. |
| Hongye Holding Group Corporation Limited |
| Central Romana Corporation |
| Ashland, Inc. |
| Silvateam |
| UBE Corporation |
| Others |
Supply Flow & Price Mechanics
Continuous reactor scale economies in Shandong Province and the Tennessee Valley compress unit costs for integrated furfural refiners while elevating price floors for batch-dependent competitors. REACH-compliant pharmaceutical-grade specifications command tenfold analytical documentation premiums over technical-grade resin feedstocks, concentrating margin capture among producers with captive laboratory infrastructure.
Pricing Analysis
Certification level creates the primary spread between REACH-registered pharmaceutical grades and technical solvent specifications. Three-tier pricing structure across pharmaceutical-grade, electronics-cleaning, and industrial-resin tiers reflects purity documentation cost differentials. Cost compression in industrial-grade furfuryl alcohol is intensifying because petroleum-derived N-methyl-2-pyrrolidone substitutes regain competitiveness where regulatory documentation proves burdensome. Agrochemical formulators in Shandong Province exhibit highest price sensitivity; Swiss and German contract research organizations show lowest sensitivity due to solvent substitution program mandates.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes disrupt just-in-time deliveries of pharmaceutical-grade tetrahydrofurfuryl alcohol to Basel and Frankfurt clusters. Production concentrates in China, Belgium, and the United States, with Shandong Province corn cob processors and Tennessee Valley pine-chemical operators anchoring respective supply zones. Feedstock supply rests on corncob, bagasse, and oat hull collection networks vulnerable to North American and Brazilian harvest volatility. Single-source vulnerability concentrates in Belgian tetrahydrofurfuryl alcohol capacity serving European electronics cleaners. Distribution runs through direct producer relationships for pharmaceutical specifications and regional chemical distributors for fragmented agrochemical demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate sustained substitution pressure from petroleum-derived polar solvents as REACH documentation burdens compress qualified supplier pools. N-methyl-2-pyrrolidone displacement of lower-purity grades threatens volume positions in electronics cleaning applications.
For Market Incumbents: Shield pharmaceutical-grade margin positions by accelerating ECHA dossier pre-registration for tetrahydrofurfuryl alcohol derivatives before Annex XVII restrictions tighten further. Prioritize backward integration into Shandong Province corn cob collection networks to neutralize harvest-cycle feedstock volatility that erodes batch refiner competitiveness. Continuous reactor upgrades in existing facilities defend cost position against Chinese state-financed greenfield capacity. For New Entrants and Emerging Players: Analytical service partnerships with Mumbai and Hyderabad pharmaceutical formulators represent the most penetrable entry vector as CDSCO impurity limits tighten for imported intermediates. Target specification development contracts with Swiss contract research organizations unbundling solvent qualification from traditional distribution channels. Lead with custom purity grade capabilities rather than commodity volume to bypass incumbent scale advantages in foundry binder and agrochemical resin segments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated refiners with continuous dehydration reactor deployment and captive agricultural residue supply. Acquisition targets should display REACH registration dossiers, ISO 9001 certification, and established analytical laboratory infrastructure. Watch for inflection signals in South Korean electronics cleaner procurement patterns, where N-methyl-2-pyrrolidone reversion rates indicate furfural derivative pricing power erosion or recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Collection | Corn cob and bagasse supply control neutralizes harvest-cycle margin compression for Shandong refiners. |
| REACH Dossier Pre-Registration | ECHA substance evaluation momentum captures electronics cleaning contracts from German formulators. |
| Continuous Reactor Technology Deployment | Steam consumption reductions and real-time impurity monitoring displace legacy batch capacity. |
| Analytical Partnership Development | Direct relationships with Basel CROs unlock custom pharmaceutical-grade specification premiums. |
| Dual Carbon Policy Alignment | China MEE carbon intensity targets qualify bio-based chemical platforms for preferential provincial financing. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with plant managers at Shandong Province refiners, procurement leads at Belgian specialty chemical distributors, regulatory affairs directors navigating ECHA registration timelines, and technical R&D heads at German electronics cleaning formulators. Secondary validation drew from ECHA substance evaluation databases, Chinese customs trade statistics for furfural derivative exports, SEC 10-K filings of pine-chemical integrated players, and Cefic sector reports on bio-based chemical platform economics. Bottom-up capacity utilization estimates and top-down end-use demand aggregation were triangulated to reconcile production and consumption figures.
Across the analysis window, volume and value outputs reflect segmentation by product type, application grade tier, end-use industry maturity, and regional regulatory cluster. CAGRs were derived from production capacity expansion schedules, substitution elasticity estimates for petroleum-derived solvent alternatives, and pharmaceutical formulator procurement qualification timelines. Industry-specific forecast inputs included corn cob harvest yield projections and REACH Annex XVII restriction implementation phasing.
Material uncertainties — regulatory acceleration or delay in ECHA substance evaluation, drought-induced feedstock price spikes, and unanticipated N-methyl-2-pyrrolidone cost reductions — sit outside the modeled envelope. Forecasts reflect assumptions about continuous reactor adoption rates and pharmaceutical-grade qualification timeline compression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Europe Barium Carbonate Market
Bulk Chemicals
Sodium Dicyanamide Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Foundry Coke Market
Bulk Chemicals
Barium Sulfite Market