
 Green Petroleum Coke and Calcined Petroleum Coke Market | 2026-2036
Green Petroleum Coke and Calcined Petroleum Coke Market Size, Share, and Industry Trends Forecast 2026-2036
Green Petroleum Coke and Calcined Petroleum Coke Market Foresight
Petroleum coke processing technology is fragmenting as refiners adopt delayed coking upgrades and integrated calcination units to capture margin from higher-value anode-grade output. Rain Carbon Inc. leverages vertical integration across terminals and calciners to control quality consistency for aluminum customers. Oxbow Corporation anchors North American logistics through its Gulf Coast storage and shipping network. Phillips 66 Company competes on refinery-calciner co-location, reducing intermediate handling costs for electrode manufacturers.
Green petroleum coke is a solid carbonaceous residue from crude oil refining via delayed coking, containing volatile matter of 8-15% and sulfur levels ranging from 1-7% depending on feedstock source; calcined petroleum Coke undergoes high-temperature heat treatment to drive off volatiles and raise carbon purity above 99% for aluminum anodes and graphite electrodes. Calcined petroleum coke dominates value capture in the product type dimension because aluminum smelters pay premiums for low-sulfur, low-metal anode-grade material. Fuel-grade green coke retains volume leadership in power generation and cement kilns where sulfur tolerance runs higher and price sensitivity shapes procurement.
The EPA regulates petcoke storage and combustion emissions under Clean Air Act standards, while the EU F-Gas Regulation and REACH frameworks constrain high-sulfur fuel use in member states. India's CEA and BIS set ash and sulfur thresholds for imported calcined material used in domestic aluminum smelting. Stakeholders must monitor how carbon border tariffs and refinery decarbonization timelines reshape feedstock availability and regional calciner economics.
Market Dynamics
Refinery decarbonization timelines and carbon border tariffs are restructuring feedstock availability, forcing calciners to secure long-term supply contracts ahead of coker unit retirements in North America and Europe.
Growth Catalysts
- Aluminum Smelter Expansion:Middle Eastern smelters are raising calcined coke offtake commitments as new potline capacity comes online in Saudi Arabia and the UAE.
- REACH Framework Tightening:The EU's carbon border adjustment mechanism is redirecting low-sulfur anode-grade material toward European aluminum producers.
- Delayed Coking Upgrades:Integrated refiners in India are installing advanced coking units to capture higher margins from anode-grade green coke output.
Market Restraints
- Crude Sulfur Volatility:Heavy sour crude price swings distort green coke quality predictability and calciner yield economics.
- US Gulf Concentration:Over half of exportable fuel-grade supply loads through Texas and Louisiana terminals, creating hurricane and congestion exposure.
- Natural Gas Substitution:US power generators are switching from petcoke to abundant shale gas under EPA Mercury and Air Toxics Standards.
Strategic Opportunities
- India Domestic Integration:Reliance Industries and public sector refiners are backward-integrating into captive calcination to serve electrode manufacturers.
- Electric Arc Furnace Electrodes:Graphite electrode demand for steel recycling is opening premium calcined coke applications outside aluminum.
- CEA Quality Mandates:India's Central Electricity Authority sulfur thresholds for imported material are creating certified-supplier advantages for compliant calciners.
Industry Challenges
- Calciner Talent Scarcity:High-temperature process engineering expertise is concentrated among retiring specialists in the US and Europe.
- Emissions Control Capex:Sulfur recovery unit upgrades and baghouse installations are absorbing capital that otherwise expands calcination capacity.
- BIS Certification Timelines:India's Bureau of Indian Standards approval delays for imported calcined coke are extending customer qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Petroleum Coke and Calcined Petroleum Coke Market |
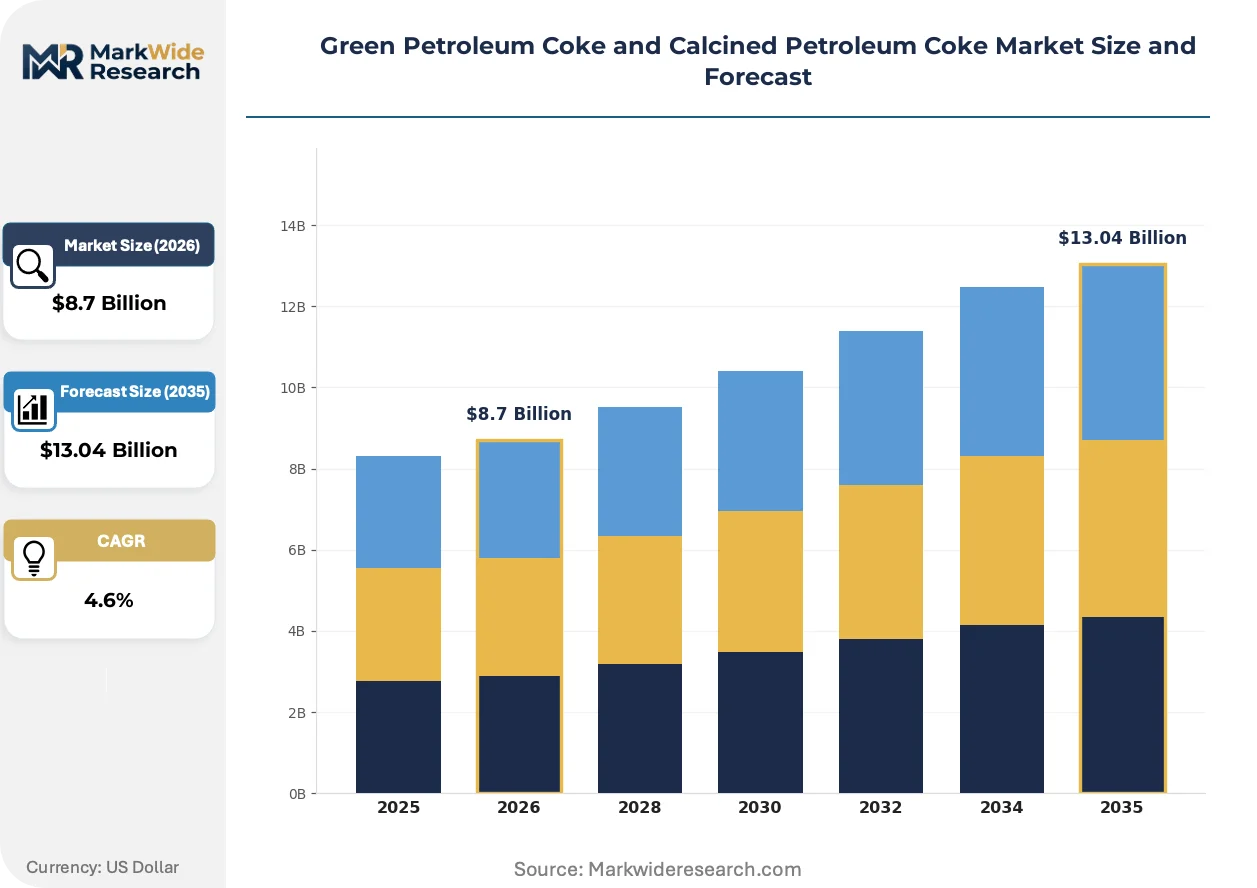
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Petroleum Coke, Calcined Petroleum Coke, Needle Coke, Fuel Grade Coke End User: Aluminum Industry, Steel Manufacturing, Power Generation, Cement Production Application: Electrode Production, Fuel Source, Carbon Additive, Refractory Material Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail |
| Companies Covered | Rain Carbon Inc., Oxbow Corporation, Phillips 66 Company, BP p.l.c, Saudi Aramco, Chevron Corporation, Valero Energy Corp, Marathon Petroleum, Reliance Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Petroleum Coke and Calcined Petroleum Coke Market Shifts & Advancements
Petroleum coke processing is fragmenting as refiners and calciners pursue diverging strategies around sulfur management, carbon purity, and integration depth. Three forces are actively reshaping competitive positioning.
Integrated calcination technology is hybridizing delayed coking and rotary kiln operations into single-site configurations. Aluminum smelters in Bahrain and Iceland are demanding this seamless quality control. The technology is compressing logistics costs and intermediate handling risks for anode manufacturers.
The EU F-Gas Regulation and parallel REACH restrictions on high-sulfur fuel use are eliminating fuel-grade outlets in member states. Cement kilns in Germany and Poland are scrambling to secure compliant feedstock alternatives. Anode-grade calciners with sub-2% sulfur capability are capturing displaced volume premiums.
Long-term offtake contracting is displacing spot market purchasing among electrode manufacturers. Chinese and Indian buyers are locking in five-year supply agreements directly with Gulf Coast refiners. This pattern is most visible in the graphite electrode sector serving electric steelmaking in Turkey and South Korea.
Green Petroleum Coke and Calcined Petroleum Coke Market Segmentation
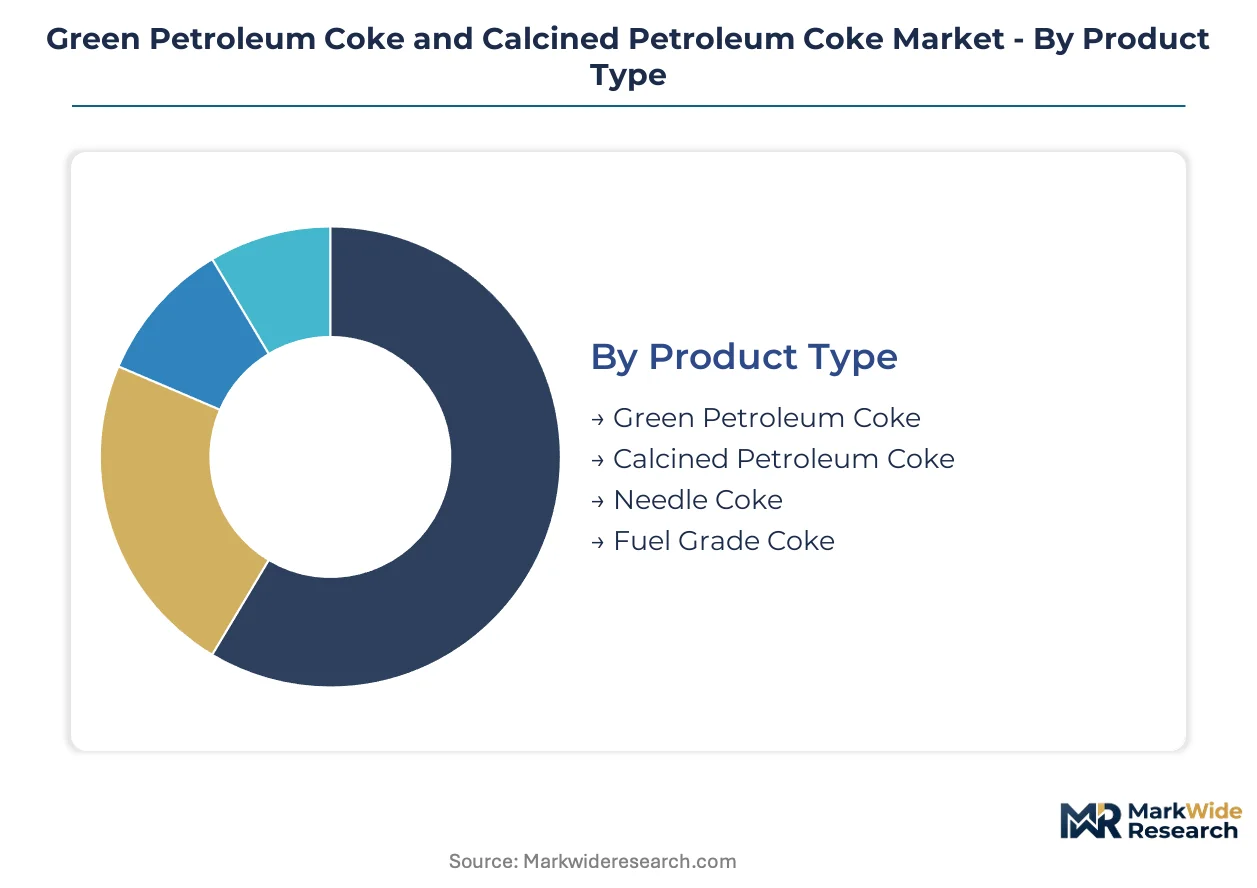
Petroleum coke segmentation reflects divergent quality specifications across aluminum smelting, steel recycling, and energy applications. Refiners and calciners configure output streams around sulfur thresholds, carbon purity requirements, and logistics economics that vary sharply by end-use.
Product Type:
The use-case spectrum spans high-purity anode feedstock to high-sulfur combustion fuel, with processing intensity and margin capture rising through the value chain.
- Green Petroleum Coke:Raw delayed coker output retains 8-15% volatile matter and sulfur levels of 1-7% depending on crude source. Aluminum smelters in Saudi Arabia and the UAE are expanding offtake of low-sulfur green coke for captive calcination as regional capacity rises.
- Calcined Petroleum Coke:High-temperature heat treatment drives volatiles below 0.5% and raises carbon purity above 99% for anode-grade specifications. Demand concentrates in India where Reliance Industries and public sector refiners feed domestic aluminum and electrode growth under tightening BIS quality mandates.
- Needle Coke:Premium low-coefficient thermal expansion variant derived from specific feedstocks for ultra-high-power graphite electrodes. Steel recycling via electric arc furnaces in Turkey and South Korea drives procurement.
- Fuel Grade Coke:High-sulfur material combusted in cement kilns and power generation where emissions tolerance permits. EPA Mercury and Air Toxics Standards and EU F-Gas Regulation are constraining outlets.
Established volume favors Fuel Grade Coke; emerging adoption favors Calcined Petroleum Coke.
End User:
Customer economics range from premium anode-grade contracts to price-sensitive bulk fuel procurement, with margin structure varying by technical qualification requirements.
- Aluminum Industry:Smelters purchase low-sulfur, low-metal calcined coke under long-term offtake agreements with embedded quality consistency clauses. Middle Eastern potline expansions in Bahrain and Iceland are tightening supplier qualification standards.
- Steel Manufacturing:Electric arc furnace operators consume graphite electrodes manufactured from needle coke and premium calcined fractions. Turkish steel recyclers are locking in five-year supply agreements directly with Gulf Coast refiners.
- Power Generation:US generators are switching from petcoke to shale gas under EPA emissions rules, shrinking addressable market.
- Cement Production:Kiln operators in Germany and Poland face REACH restrictions on high-sulfur fuel use, forcing feedstock substitution.
Aluminum Industry contracts command the steepest price premiums; Cement Production faces the sharpest regulatory compression.
Application:
Functional requirements split between structural carbon performance and thermal energy release, with processing depth determining value capture.
- Electrode Production:Demands highest carbon purity and lowest metallic impurities for conductivity and thermal stability in aluminum smelting and steel recycling. Integrated calcination technology is hybridizing delayed coking and rotary kiln operations to meet Bahrain and Iceland smelter specifications.
- Fuel Source:Combustion applications prioritize calorific value over purity, with sulfur content the primary constraint. EU carbon border adjustments are redirecting compliant material toward European industrial users.
- Carbon Additive:Metallurgical processes use calcined coke to adjust carbon content in steel and foundry applications.
- Refractory Material:High-temperature industrial linings employ specific coke fractions for thermal resistance.
Electrode Production captures the highest value per ton; Fuel Source dominates raw volume throughput.
Distribution Channel:
Supply chain configuration varies by customer scale, technical service requirements, and geographic proximity to calcination capacity.
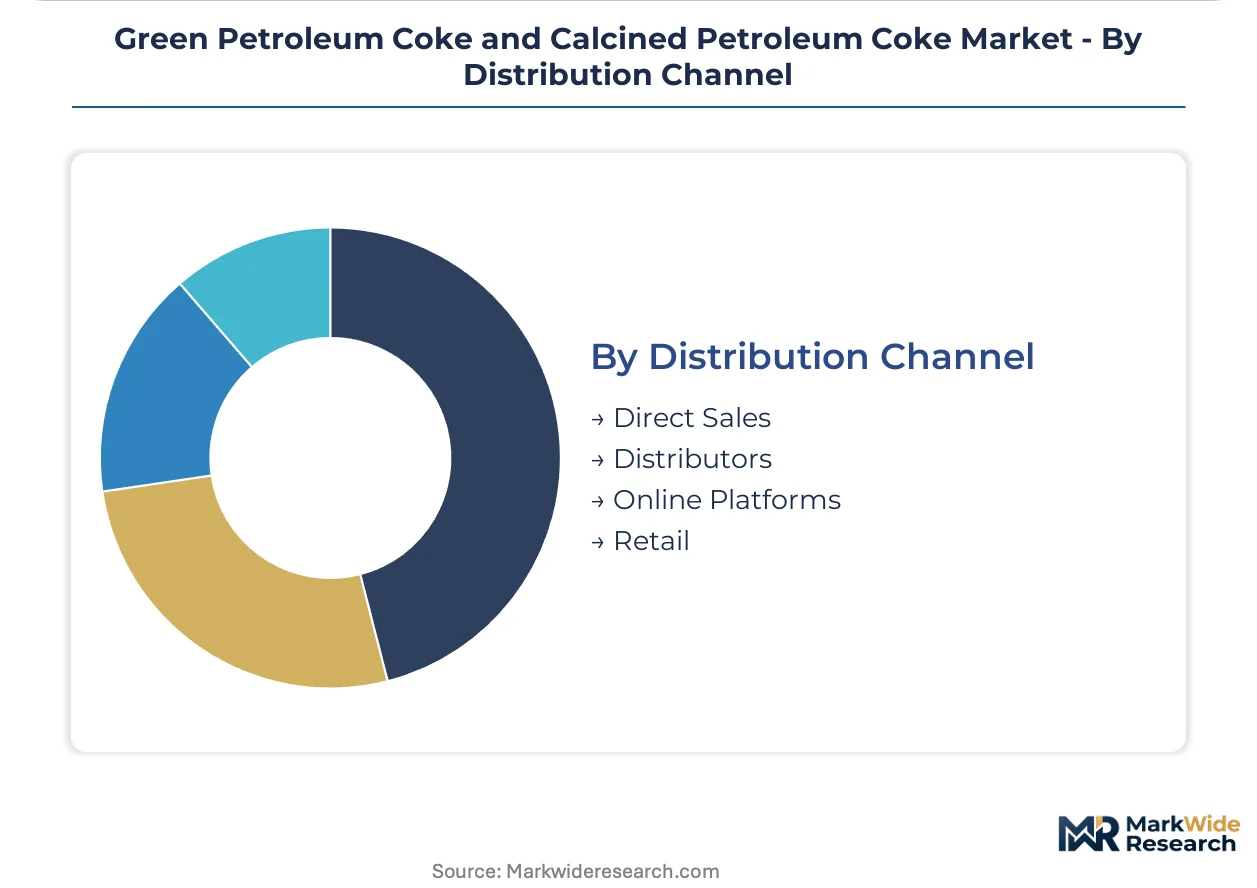
- Direct Sales:Large aluminum smelters and electrode manufacturers contract directly with refiners and calciners for multi-year supply security. Chinese and Indian buyers are displacing spot market purchasing with five-year agreements.
- Distributors:Intermediate handlers aggregate volumes for mid-size consumers lacking procurement scale. Gulf Coast storage and shipping networks anchor North American logistics.
- Online Platforms:Digital procurement channels are emerging for standardized fuel-grade transactions.
- Retail:Small-volume end-users in specialized industrial applications access material through local distributors.
Direct Sales commands the contract value; Distributors handle the fragment of spot and short-cycle demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast terminals in Texas and Louisiana ship fuel-grade green coke to cement kilns in India and power generators in Turkey, while low-sulfur anode-grade material flows from Saudi Arabian refineries to aluminum smelters in Bahrain and Iceland.
United States
EPA Mercury and Air Toxics Standards push power generators toward shale gas substitution, shrinking domestic fuel-grade consumption. Hurricane exposure concentrates at Texas and Louisiana export terminals handling over half of seaborne supply. Oxbow Corporation anchors North American logistics through Gulf Coast storage networks serving international buyers.
India
Reliance Industries and public sector refiners expand captive calcination capacity to feed domestic aluminum smelter growth. BIS certification timelines for imported calcined coke extend customer qualification cycles. Gujarat's refining corridor integrates delayed coking upgrades with electrode manufacturer proximity.
Saudi Arabia
Saudi Aramco leverages heavy crude processing to supply low-sulfur green coke for regional smelter expansion. New potline capacity in Ras Al-Khair Industrial City tightens anode-grade specifications. Domestic calciner investments reduce dependence on imported calcined material.
Germany
EU F-Gas Regulation and REACH frameworks eliminate high-sulfur fuel-grade outlets for cement kilns. Cement operators in Poland and Germany scramble for compliant feedstock alternatives. Ruhr industrial clusters face carbon border adjustment pressures redirecting procurement toward certified low-sulfur suppliers.
China
Steel recycling via electric arc furnaces drives needle coke demand for ultra-high-power graphite electrodes. MIIT dual carbon goals constrain high-emission calciner expansion. Shandong Peninsula petrochemical bases concentrate delayed coking capacity serving electrode manufacturers.
Green Petroleum Coke and Calcined Petroleum Coke Market Competitive Landscape
Channel-controlling players compete with product-specialist players across terminal logistics, refinery integration, and calcination technology tiers. The structure concentrates around refinery-calciner co-location advantages and Gulf Coast storage network dominance. Three archetypes prevail: integrated oil majors with captive coker units, independent calciners with quality-certification capabilities, and logistics aggregators controlling export terminal access. Competitive moves center on backward integration into captive calcination and long-term offtake contracting displacing spot market purchasing.
Within the integrated oil major tier, Saudi Aramco and Chevron Corporation exemplify refinery-calciner co-location strategies. Among independent specialists, Rain Carbon Inc. occupies a position representing vertical control across terminals and calciners. Reliance Industries Ltd anchors the domestic integration archetype in India through captive supply serving electrode manufacturers.
| Leading Market Players |
|---|
| Rain Carbon Inc. |
| Oxbow Corporation |
| Phillips 66 Company |
| BP p.l.c |
| Saudi Aramco |
| Chevron Corporation |
| Valero Energy Corp |
| Marathon Petroleum |
| Reliance Industries Ltd |
| Others |
Supply & Pricing Matrix
Gulf Coast refinery concentration in Texas and Louisiana anchors calciner feedstock access, concentrating margin capture with terminal-controlling logistics aggregators who command export pricing power. Long-term offtake contracting is displacing spot market purchasing as aluminum smelters and electrode manufacturers seek supply security.
Pricing Analysis
Anode-grade calcined coke commands a substantial premium over fuel-grade green coke, with needle coke representing the apex tier for ultra-high-power graphite electrodes. Three-tier pricing structure across premium, standard, and economy levels reflects sulfur content thresholds, carbon purity grades, and BIS certification compliance. Cost compression in fuel-grade tiers is intensifying because US power generators are switching to shale gas under EPA Mercury and Air Toxics Standards. Cement kiln operators exhibit the highest price sensitivity due to REACH-mandated feedstock substitution costs, while aluminum smelters in Bahrain and Iceland show the least sensitivity given embedded quality consistency clauses.
Supply Chain Analysis
Hurricane exposure at Texas and Louisiana terminals dominates supply chain risk for seaborne fuel-grade exports to India and Turkey. Geographic concentration rests on the United States, Saudi Arabia, and India as primary production nodes. Raw material dependencies draw from heavy sour crude feedstocks, delayed coker unit output, and natural gas for calcination energy. Single-source vulnerability concentrates at Gulf Coast storage networks handling over half of exportable supply. Distribution runs through direct sales contracts for large aluminum smelters and electrode manufacturers, with distributors aggregating fragmented spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and quality certification maintenance represent expanding recurring-revenue layers outpacing commodity coke sales growth. After-sales support for anode-grade consistency monitoring and BIS compliance assistance is attaching at premium rates.
For Market Incumbents: Build captive calcination moats through refinery-calciner co-location to lock in feedstock access ahead of North American coker unit retirements. Secure long-term offtake agreements with Middle Eastern aluminum smelters expanding potline capacity. Invest in sulfur recovery unit upgrades to meet tightening EU carbon border adjustment thresholds and preserve European market access. For New Entrants and Emerging Players: Establish a beachhead in India's domestic electrode manufacturing corridor where Reliance Industries and public sector refiners are backward-integrating into captive supply. Target graphite electrode producers serving Turkish and South Korean electric arc furnace steel recycling as the most penetrable segment. Pursue BIS certification early to compress customer qualification cycles and displace incumbent import suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward independent calciners with quality-certification capabilities and terminal access in the US Gulf or Gujarat refining corridor. Long-term viability hinges on securing anode-grade positioning as fuel-grade outlets shrink under emissions regulations. Watch for inflection signals in Indian CEA sulfur threshold enforcement and EU carbon border adjustment implementation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Calcination | Reliance Industries and Saudi Aramco are compressing logistics costs through refinery-calciner co-location. |
| Long-term Supply Agreement | Chinese and Indian electrode manufacturers are locking in five-year contracts directly with Gulf Coast refiners. |
| Quality Certification Investment | BIS approval and CEA compliance create certified-supplier advantages for calciners serving Indian aluminum smelters. |
| Sulfur Recovery Unit Upgrade | EPA emissions rules and EU REACH frameworks mandate capital deployment that preserves market access. |
| Terminal Network Expansion | Oxbow Corporation's Gulf Coast storage and shipping network anchors North American export logistics control. |
Research Methodology
Cross-validation between primary interviews with refinery operations managers, calciner technical directors, aluminum smelter procurement leads, and electrode manufacturer supply chain heads anchors the qualitative findings. Secondary validation draws from EPA emissions filings, EIA petcoke production data, EU ETS carbon border adjustment documentation, and BIS certification registries. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across the analysis window.
Calibration against historical trade flows and announced refinery coker unit investments shapes the projection framework. Segmentation dimensions span product grade tier, end-use industry, sulfur content band, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves and announced capacity expansion timelines. Crude sulfur volatility and calciner yield economics inform scenario bounds.
Sensitivities concentrate around refinery decarbonization timelines, carbon border tariff implementation, and hurricane disruption frequency at Gulf Coast terminals. Forecasts reflect assumptions about coker unit retirement schedules and aluminum smelter expansion completion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
Europe Caustic Soda Market
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Global Acrylic Esters Market
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Ferric Sulfate Market