
 Micronized Color Powder Market | 2026-2036
Micronized Color Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Micronized Color Powder Market Analytics
The gap between premium cosmetic-grade micronized powders and commodity industrial colorants is broadening as particle-size specifications diverge. BASF SE leverages its integrated pigment synthesis network to supply sub-10-micron grades for high-end skincare. Clariant AG anchors European supply through specialized milling operations that meet pharmaceutical-adjacent purity standards. Huntsman Corporation competes in coatings applications with broader particle distributions optimized for dispersion economics rather than tactile performance.
Micronized color powders are finely ground pigments and dyes with controlled particle sizes typically below 25 microns, produced through jet milling or air classification to achieve specific surface areas and opacity levels. These powders serve industrial and commercial markets where uniform dispersion, color consistency, and regulatory compliance determine product performance. Non-toxic pigments lead volume in food and cosmetic applications where migration limits and skin-contact safety govern formulation choices. Synthetic dyes dominate coatings and plastics through cost-efficient tinting strength and batch reproducibility. Natural colorants command premium positioning in clean-label food products and organic-certified cosmetics where consumer preference overrides higher raw material costs.
REACH in Europe, FDA color additive regulations in the United States, and FSSAI standards in India collectively tighten permissible heavy-metal content and labeling requirements for micronized colorants. Compliance costs favor suppliers with in-house analytical laboratories and certified manufacturing facilities, compressing informal producers in wholesale and unbranded channels. Stakeholders must monitor evolving state-level chemical disclosure laws and biobased certification schemes that will reshape qualification criteria for supplier approval programs.
Market Dynamics
REACH compliance thresholds in Europe are compressing supplier margins while redirecting procurement toward certified German and Swiss milling operations, fragmenting the legacy supply base into compliance-tiered tiers.
Growth Catalysts
- Cosmetic-grade particle refinement:Premium skincare formulators in France and Italy now specify sub-10-micron grades for tactile performance, pulling volume from industrial pigment suppliers.
- REACH impurity mandates:ECHA's tightened heavy-metal thresholds disqualify uncertified Asian imports, concentrating European demand on Rhine-Ruhr chemical cluster producers.
- Clean-label food migration:Organic-certified natural colorants command shelf-space premiums in German and Dutch retail channels, overriding synthetic dye cost advantages.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment-grade TiO2 price swings compress milling economics for sub-20-micron production runs.
- Jet milling equipment concentration:Precision air-classification systems are manufactured by a narrow German-Swiss supplier base, creating capex bottlenecks for new entrants.
- Pharmaceutical-adjacent purity requirements:FDA color additive regulations for ingestible applications impose analytical testing burdens that informal producers cannot absorb.
Strategic Opportunities
- Indian pharmaceutical excipient demand:CDSCO's alignment with ICH quality guidelines creates a certified-supplier vacuum for USP-grade micronized pigments in Mumbai-Pune corridors.
- Biobased certification tailwinds:EU Green Deal procurement mandates favor renewable-derived colorants in public-sector food service contracts.
- Direct-to-formulator digital channels:Specialty chemical marketplaces are disintermediating traditional distributor networks for batch-reproducible pigment grades.
Industry Challenges
- Particle-size metrology talent scarcity:Laser diffraction and dynamic light scattering expertise concentrates in Basel and Ludwigshafen analytical service labs, constraining quality scale-up.
- Multi-jurisdiction dossier compilation:Simultaneous REACH, FDA, and FSSAI registration timelines stretch regulatory affairs bandwidth for mid-cap pigment houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micronized Color Powder Market |
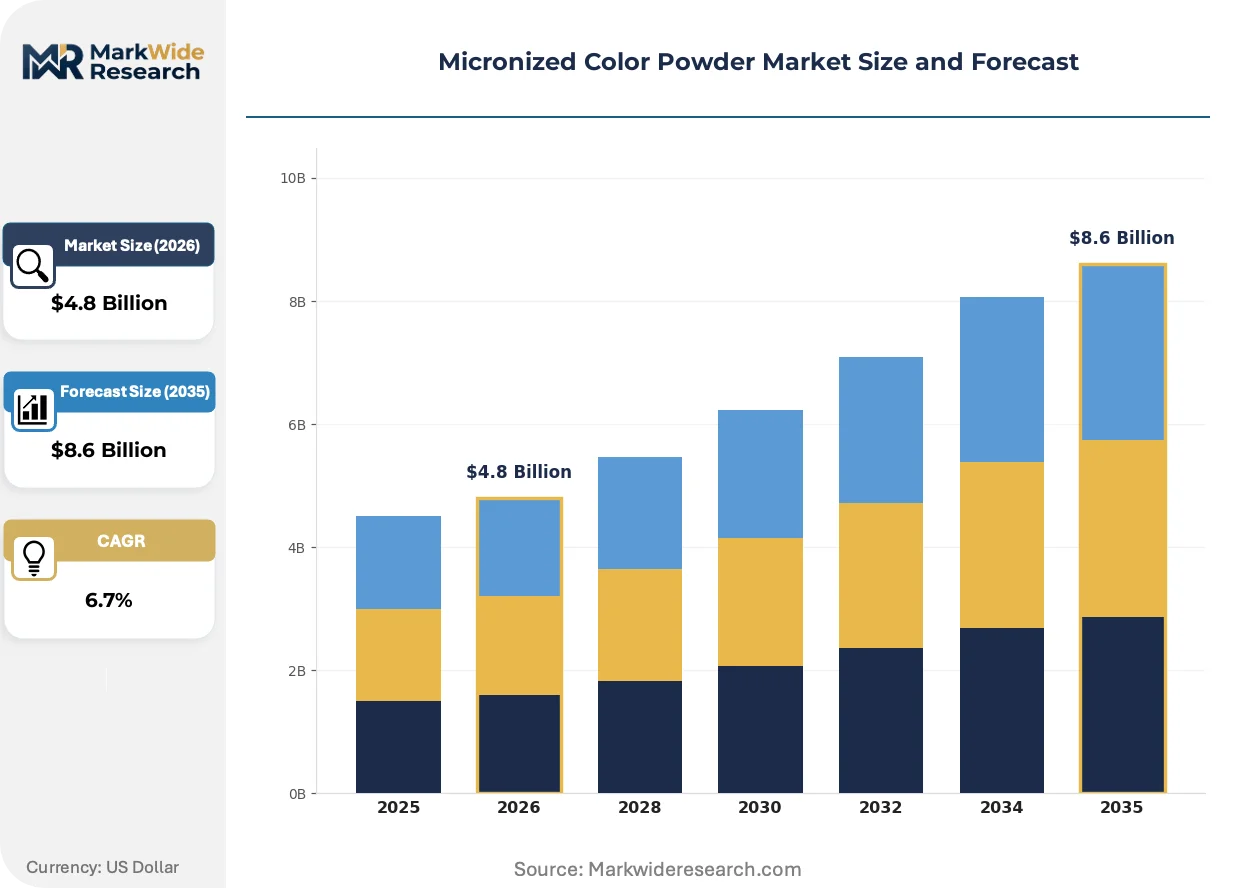
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Toxic Pigments, Synthetic Dyes, Natural Colorants, Transparent Colors Application: Cosmetics, Coatings, Plastics, Food Products Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale End User: Manufacturers, Artisans, DIY Enthusiasts, Commercial Bakers |
| Companies Covered | BASF SE, Clariant AG, Huntsman Corporation, DIC Corporation, Cabot Corporation, Sun Chemical Corporation, GNT Group, Archer Daniels Midland, Sensient Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micronized Color Powder Market Evolving Landscape
Active classification technologies and biobased feedstock substitution are fragmenting the traditional pigment synthesis value chain, enabling new entrants to bypass legacy integrated producers.
Supercritical CO2 milling is rewriting dispersion economics for heat-sensitive natural colorants. Premium chocolate and plant-based dairy formulators in Belgium and Switzerland are adopting these grades within 18-month qualification cycles. The technology is compressing thermal degradation losses that previously limited carotenoid and anthocyanin applications.
EU CSRD supply-chain disclosure rules now mandate Scope 3 emissions reporting for colorant procurement. Coatings manufacturers in the Netherlands and Denmark are requalifying suppliers based on verified carbon footprints. Waterborne architectural coatings segments are absorbing compliance costs fastest, passing premiums through specification-grade tender processes.
Formulator consolidation is compressing supplier switching cycles. Three multinational personal care houses now control majority European volume for cosmetic-grade micronized pigments, consolidating purchase orders into annual framework agreements. German and French procurement teams are demanding locked-in particle-size distributions with quarterly certificate-of-analysis batches, displacing spot-market spot buying.
Micronized Color Powder Market Segmentation
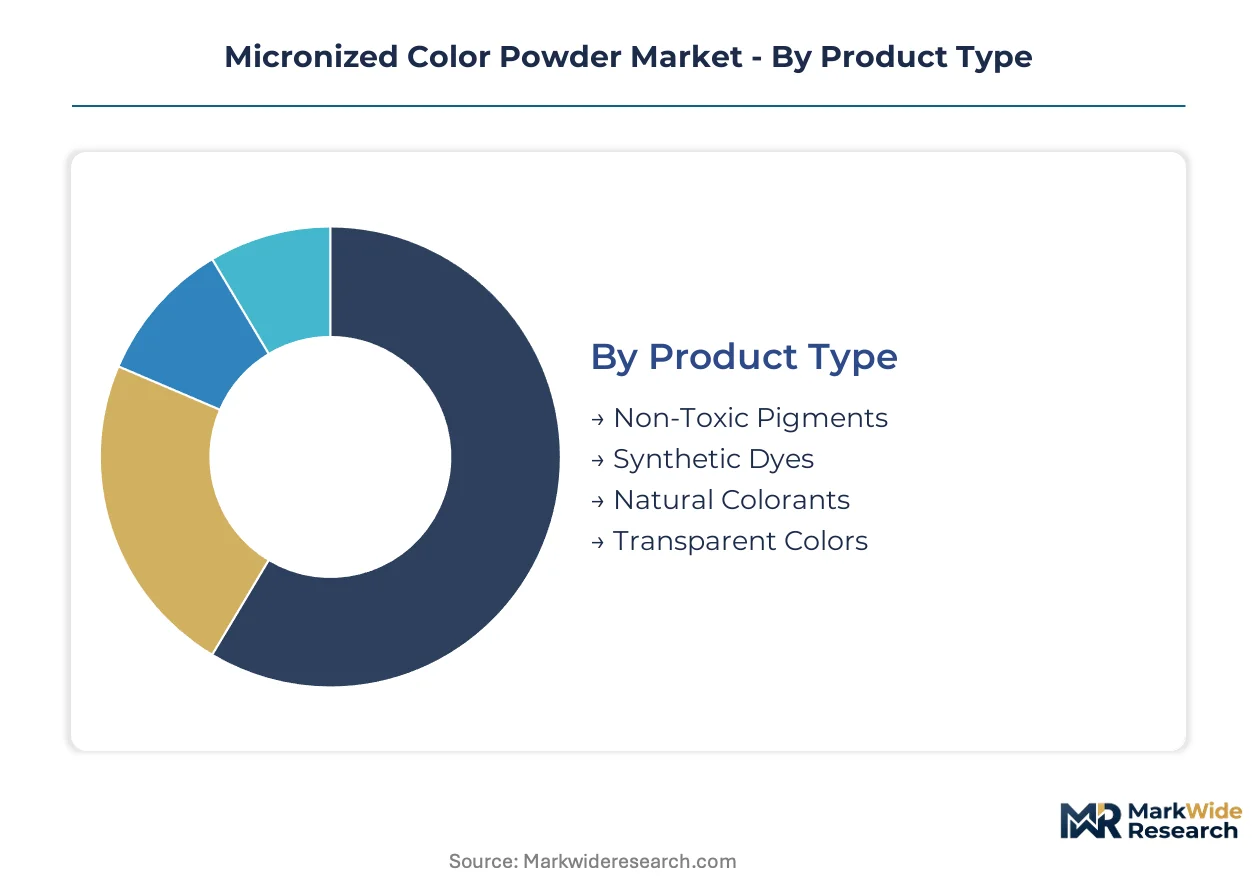
Particle-size specifications and purity tiers fragment the micronized color powder landscape into distinct commercial strata. Each segment carries divergent regulatory burdens, from FDA color additive petitions for ingestible grades to REACH dossier requirements for industrial coatings.
Product Type:
Certification intensity varies sharply across product categories, with pharmaceutical-adjacent pigments requiring USP-grade analytical validation while industrial dyes operate under less stringent purity thresholds.
- Non-Toxic Pigments:Inorganic oxides and lake pigments engineered for skin-contact safety with heavy-metal content below FDA and ECHA migration limits. Demand concentrates in French and Italian premium cosmetics houses specifying sub-10-micron grades for tactile performance in high-end skincare.
- Synthetic Dyes:Azo and anthraquinone compounds produced through controlled diazotization with batch-to-batch tinting strength within Delta E 1.0. Coatings manufacturers in Germany's Rhine-Ruhr cluster absorb the majority volume for architectural and industrial formulations where cost efficiency overrides premium dispersion.
- Natural Colorants:Carotenoid and anthocyanin extracts from botanical sources, often certified organic for clean-label positioning.
- Transparent Colors:Low-refractive-index pigments for glazing and specialty coating effects.
Non-Toxic Pigments sits at the top of the volume ranking, with Natural Colorants climbing the fastest.
Application:
End-use differentiation tracks formulation complexity, with cosmetics commanding the steepest purity premiums and plastics absorbing volume through standardized masterbatch integration.
- Cosmetics:Face powders, lipsticks, and eye formulations requiring particle-size distributions below 15 microns for sensory performance. REACH and FDA dual registration compresses supplier pools to German and Swiss milling operations with in-house analytical laboratories.
- Coatings:Architectural and industrial finishes where broader particle distributions optimize dispersion economics. Dutch and Danish manufacturers now mandate Scope 3 emissions documentation under EU CSRD procurement rules.
- Plastics:Polymer masterbatch tinting with heat-stable pigments for extrusion and injection molding.
- Food Products:Ingestible colorants governed by FSSAI standards in India and FDA color additive regulations in the United States.
Coatings captures the largest volume share, though Cosmetics expands most quickly on per-kilogram value metrics.
Distribution Channel:
Channel selection reflects order-size economics and technical-service requirements, with bulk industrial procurement bypassing traditional distributor markups.
- Online Retail:E-commerce platforms serving artisan and small-batch formulators with certified pigment kits and technical datasheets. German specialty chemical marketplaces are disintermediating legacy distributor networks for batch-reproducible grades.
- Specialty Stores:Physical outlets for professional artists and commercial bakers requiring immediate color matching consultation.
- Direct Sales:Annual framework agreements between multinational personal care houses and integrated pigment producers.
- Wholesale:Bulk volume channels for coatings and plastics manufacturers with established supplier qualification programs.
Direct Sales dominates value concentration, while Online Retail gains share fastest among emerging formulators.
End User:
Customer-type segmentation tracks technical sophistication, from validated manufacturing protocols to unregulated artisan experimentation.
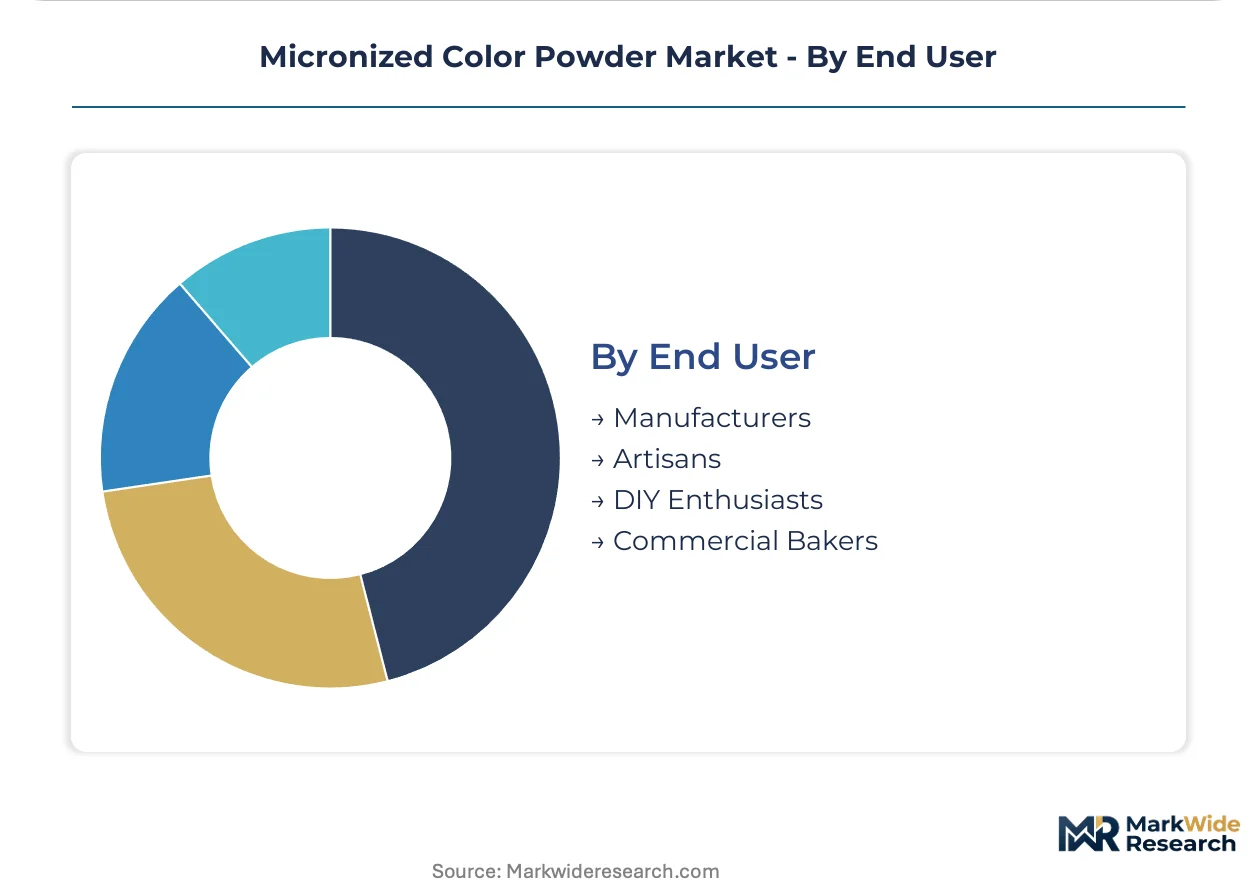
- Manufacturers:Multinational cosmetics, coatings, and food producers with locked-in particle-size specifications and quarterly certificate-of-analysis requirements. Three European personal care houses now control majority procurement volume through consolidated purchase orders.
- Artisans:Independent cosmetic and food crafters sourcing smaller batches through certified distributors.
- DIY Enthusiasts:Hobbyist segment purchasing pre-micronized pigment kits for home formulation.
- Commercial Bakers:Food service operations requiring FSSAI-compliant colorants for decorated products.
Manufacturers anchor absolute volume, with Commercial Bakers showing the steepest expansion trajectory on clean-label natural colorant adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized particle-size metrology talent concentrates in Basel and Ludwigshafen analytical service labs, anchoring European quality infrastructure while Indian pharmaceutical corridors and East Asian coatings clusters compete for certified milling capacity.
Germany
Rhine-Ruhr chemical cluster producers absorb redirected procurement from REACH-disqualified Asian imports. ECHA's tightened heavy-metal thresholds compress supplier margins while concentrating demand on certified German and Swiss milling operations. Specialty chemical facilities in Ludwigshafen and Leverkusen serve coatings and personal care sectors with locked-in particle-size specifications.
United States
Cosmetic-grade sub-10-micron demand from premium skincare formulators pulls volume toward domestic pigment houses. FDA color additive regulations for ingestible applications impose analytical testing burdens that informal producers cannot absorb. New Jersey and Ohio coatings manufacturers now mandate quarterly certificate-of-analysis batches under consolidated purchase agreements.
India
CDSCO's alignment with ICH quality guidelines creates a certified-supplier vacuum for USP-grade micronized pigments in Mumbai-Pune corridors. FSSAI standards for food colorants tighten permissible heavy-metal content, redirecting procurement toward facilities with in-house analytical laboratories. Gujarat and Maharashtra specialty chemical clusters expand pharmaceutical excipient milling capacity.
Switzerland
Precision air-classification systems manufactured by German-Swiss equipment suppliers create capex bottlenecks for new entrants. Supercritical CO2 milling adoption for heat-sensitive natural colorants concentrates in Basel and Zurich premium chocolate and plant-based dairy formulators. Swissmedic-adjacent purity standards anchor European pharmaceutical-grade pigment qualification.
China
Synthetic dye production for coatings and plastics operates under cost-efficient tinting strength economics, with batch reproducibility driving volume absorption. NMPA and GB standards for cosmetic colorants tighten migration limits, compressing informal wholesale channels. Yangtze River Delta pigment synthesis facilities compete on dispersion economics rather than tactile performance specifications.
Micronized Color Powder Market Competitive Landscape
Capital-heavy integrated pigment producers compete with asset-light specialized milling operations, fragmenting the supplier base into compliance-tiered tiers. REACH dossier requirements and multi-jurisdiction registration timelines stretch regulatory affairs bandwidth, favoring established players with captive analytical infrastructure. Three archetypes dominate: integrated chemical conglomerates with backward pigment synthesis control, specialized milling houses with pharmaceutical-adjacent purity certification, and regional distributors disintermediated by direct-to-formulator digital channels. Consolidation manifests through annual framework agreements and locked-in particle-size distribution contracts.
Among integrated chemical conglomerates, BASF SE and Clariant AG occupy positions exemplifying the premium-grade archetype, while Huntsman Corporation anchors the coatings-optimized segment. These entities represent the structural divide between sub-10-micron cosmetic-grade suppliers and broader particle-distribution industrial pigment houses. German and Swiss-origin companies concentrate analytical laboratory infrastructure, while US-based players compete on FDA registration breadth. The competitive dynamic centers on qualification cycle speed and batch reproducibility rather than unit cost alone.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Huntsman Corporation |
| DIC Corporation |
| Cabot Corporation |
| Sun Chemical Corporation |
| GNT Group |
| Archer Daniels Midland |
| Sensient Technologies |
| Others |
Value Network & Pricing Analysis
Backward integration into captive pigment synthesis anchors both supply security and pricing power for Rhine-Ruhr integrated producers serving REACH-compliant European demand. This upstream control over raw material quality and particle-size refinement creates defendable margin positions against milling-only competitors facing titanium dioxide feedstock volatility.
Pricing Analysis
Certified analytical services bundled with pigment supply command premiums over unbundled commodity-grade spot purchases. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade tiers separates USP-validated batches from REACH-registered coatings pigments and uncertified wholesale material. Cost compression in industrial-grade segments is intensifying because titanium dioxide price swings compress sub-20-micron production economics. Coatings manufacturers show highest price sensitivity, while pharmaceutical excipient buyers absorb premiums for locked-in particle-size distributions with quarterly certificate-of-analysis documentation.
Supply Chain Analysis
EU Green Deal domestic-content mandates for public-sector procurement are reshaping sourcing patterns toward verified European milling operations. Supply concentrates in Germany, Switzerland, and India, with Rhine-Ruhr chemical clusters, Basel precision equipment manufacturers, and Mumbai-Pune pharmaceutical corridors anchoring certified capacity. Feedstock dependencies span pigment-grade titanium dioxide, botanical extracts for natural colorants, and specialized jet milling equipment from German-Swiss suppliers. Single-source vulnerability in precision air-classification systems creates capex bottlenecks for capacity expansion. Distribution runs through direct annual framework agreements between multinational formulators and integrated producers, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH dossier requirements and ECHA heavy-metal threshold tightening continuously requalify supplier pools, concentrating procurement on certified milling operations with captive analytical infrastructure.
For Market Incumbents: Anchor compliance-tiered supply positions by locking in multi-jurisdiction registration bandwidth before CDSCO and FDA timelines diverge further. Invest in supercritical CO2 milling capacity for heat-sensitive natural colorants to defend against specialty chemical marketplace disintermediation. Prioritize locked-in particle-size distribution contracts with consolidated multinational personal care houses over spot-market volume. For New Entrants and Emerging Players: Direct-to-formulator digital channels offer the lowest-friction entry path for batch-reproducible pigment grades targeting artisan cosmetic and clean-label food segments. Target Indian pharmaceutical excipient demand where CDSCO alignment with ICH guidelines has created certified-supplier vacuum in Mumbai-Pune corridors. Pursue biobased certification pathways to qualify for EU Green Deal procurement mandates in public-sector food service. For Investors and Strategic Acquirers: Roll-up economics work for specialized milling houses with pharmaceutical-adjacent purity certification because regulatory affairs bandwidth constraints prevent mid-cap pigment houses from scaling multi-jurisdiction dossier compilation independently. Five-to-ten-year viability favors asset-light specialized milling operations over capital-heavy integrated synthesis facilities. Watch for supercritical CO2 milling adoption rates in Belgian and Swiss premium chocolate formulators as inflection indicator for natural colorant technology substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Captive control over sub-10-micron raw material quality locks in REACH compliance margins. |
| Supercritical CO2 Milling Capacity Expansion | Heat-sensitive natural colorant processing opens Belgian premium chocolate and Swiss plant-based dairy segments. |
| Multi-Jurisdiction Dossier Compilation | Simultaneous REACH, FDA, and FSSAI registration compresses competitor pools to analytical-laboratory-equipped producers. |
| Direct-to-Formulator Digital Channel Launch | Specialty chemical marketplaces disintermediate legacy distributor markups for batch-reproducible grades. |
| Biobased Certification Investment | EU Green Deal procurement mandates favor renewable-derived colorants in Dutch and Danish public-sector tenders. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pigment synthesis plant managers, cosmetics procurement leads, coatings technical directors, and specialty chemical distribution channel partners with secondary validation from ECHA REACH dossier databases, FDA color additive petitions, customs trade flow records, and SEC filings from integrated chemical conglomerates. Bottom-up particle-size grade volume estimates triangulated against top-down end-use industry absorption rates.
Comparable-period anchoring linked forward projections to historical qualification cycle timelines and regulatory implementation phases across the analysis window. Segmentation dimensions modeled include product type tier, application purity requirements, distribution channel structure, and regional regulatory cluster. CAGRs derived from slope-log regression across annualized volume points, with forecast inputs incorporating REACH compliance cost trajectories and supercritical CO2 milling adoption curves.
The model assumes a particular technology adoption path; alternative pathways for supercritical CO2 milling scale-up would alter the outlook for natural colorant penetration in heat-sensitive applications. Forecasts reflect assumptions regarding ECHA enforcement intensity, titanium dioxide feedstock price stabilization, and consolidated multinational buyer procurement consolidation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Aluminum Pigments Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Ultramarine Pigments Market
Dyes and Pigments
Cacao Husk Pigment Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Ponceau 4R Colors Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Middle East and Africa Hair Colorants Market
Dyes and Pigments
LAMEA Optical Brighteners Market
Dyes and Pigments
Global Cosmetic Dyes Market
Dyes and Pigments
North America Hair Colorants Market