
 Global Glycine Supplement Market | 2026-2036
Global Glycine Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glycine Supplement Market Foresight
Bioprocess engineering is narrowing the cost gap between fermentation-derived and synthetic glycine, enabling broader pharmaceutical-grade adoption. Ajinomoto Co., Inc. leverages its amino acid fermentation expertise to sustain premium positioning in pharmaceutical-grade supply. Evonik Industries AG anchors European production capacity through its backward integration into precursors. Kyowa Hakko Bio Co., Ltd. differentiates via microbial strain optimization that reduces impurity profiles below compendial thresholds.
Glycine supplements deliver the simplest proteinogenic amino acid, typically formulated at 1-3 gram single-serving doses for collagen synthesis support, sleep quality modulation, and detoxification pathways. Powder formats dominate volume throughput due to bulk manufacturing efficiency and flexible dosing, while capsules command margin pools through convenience premiums in sports nutrition. Sleep aid applications exhibit the steepest trajectory as consumers self-direct toward non-habit-forming alternatives, though cognitive support retains higher price realization per active gram.
FDA cGMP enforcement and EFSA novel food assessments shape ingredient qualification timelines, while Japan's MHLW maintains the most stringent purity specifications for amino acid therapeutics. CSRD supply-chain disclosure requirements in Europe are forcing raw material traceability investments that favor established fermentation houses over commodity traders. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and food-grade specifications as classification decisions determine market access barriers and pricing power.
Market Dynamics
Pharmaceutical-grade glycine demand is bifurcating from commodity supply as FDA cGMP enforcement and EFSA novel food assessments force manufacturers to maintain dual certification tracks for ingredient qualification.
Growth Catalysts
- CSRD supply-chain disclosure:European disclosure mandates are forcing raw material traceability investments that favor established fermentation houses over commodity traders.
- Sports nutrition adoption:Athletes are self-directing toward glycine for muscle recovery and collagen synthesis support, creating pull-through demand for certified ingredient supply.
- Bioprocess engineering advances:Fermentation-derived glycine production costs are narrowing against synthetic alternatives, enabling broader pharmaceutical-grade adoption.
Market Restraints
- Petrochemical feedstock volatility:Synthetic glycine production remains tethered to acetic acid and ammonia pricing, compressing margins during energy price spikes.
- Japanese purity specifications:MHLW maintains the most stringent amino acid therapeutic standards, creating a qualification bottleneck for non-specialized suppliers.
- Peptide substitute encroachment:Collagen peptide supplements are capturing overlapping consumer segments with stronger marketing infrastructure and lower education burden.
Strategic Opportunities
- German pharmaceutical channel:Underpenetrated pharmacy distribution for condition-specific glycine therapeutics offers white space beyond sports nutrition commoditization.
- Sleep aid formulation expansion:Non-habit-forming positioning is capturing consumers exiting melatonin dependency cycles, with glycine's GABA-modulating mechanism.
- Clean-label certification convergence:USDA Organic and Non-GMO Project verification are creating premium tier separation that fermentation-derived supply can exploit.
Industry Challenges
- Dual-track compliance burden:Maintaining simultaneous FDA food-grade and pharmaceutical-grade certifications requires redundant quality systems and documentation.
- Microbial strain IP complexity:Proprietary fermentation organisms for impurity reduction are subject to licensing disputes that delay capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glycine Supplement Market |
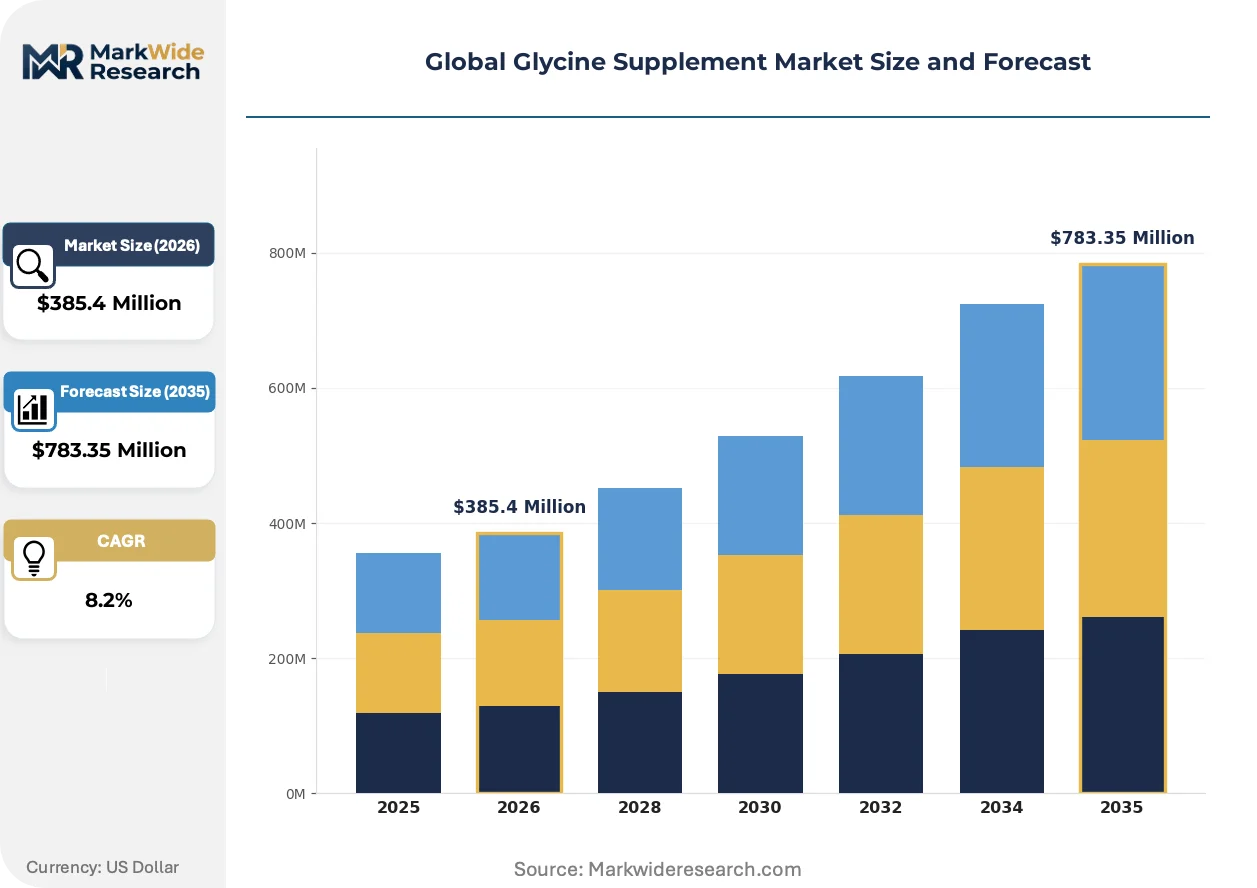
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $783.35 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Tablets, Liquid Concentrate, Effervescent Tablets Application: Sports Nutrition, Cognitive Support, Sleep Aid, Joint Health, Liver Protection End User: Nutritionists, Fitness Enthusiasts, Elderly Consumers, Clinical Researchers, Pharmaceutical Manufacturers Distribution Channel: Online Retailers, Health Food Stores, Pharmacies, Direct Sales, Specialty Clinics |
| Companies Covered | Ajinomoto Co., Inc., Evonik Industries AG, Kyowa Hakko Bio Co., Ltd., Archer Daniels Midland Company, Prinova Group LLC, GEO Specialty Chemicals Inc., Yuki Gosei Kogyo Co., Ltd., Showa Denko KK, Chattem Chemicals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glycine Supplement Market Shifts & Advancements
Fermentation technology maturation and regulatory disclosure mandates are compressing the traditional separation between food-grade and pharmaceutical-grade supply chains. Three developments are reshaping competitive positioning.
Continuous bioprocessing is digitizing glycine manufacturing by replacing batch fermentation with real-time monitoring systems. Pharmaceutical ingredient buyers are adopting these supply lines to reduce lot-to-lot variability. This shift is digitizing quality assurance workflows and compressing certificate-of-analysis turnaround times from weeks to days.
EFSA novel food assessments are tightening amino acid ingredient qualification timelines for non-traditional sources. European supplement brands must now document 25-year consumption history or submit full toxicology dossiers. Sports nutrition distributors are responding by consolidating supplier bases around pre-qualified fermentation houses with established safety files.
Direct-to-consumer subscription models are capturing sleep aid and cognitive support segments that previously flowed through retail pharmacy. Wellness platforms are bundling glycine with biometric tracking, displacing transactional supplement purchases. This behavioral shift is most visible in United States urban markets where telehealth prescribing intersects with personalized nutrition services.
Global Glycine Supplement Market Segmentation
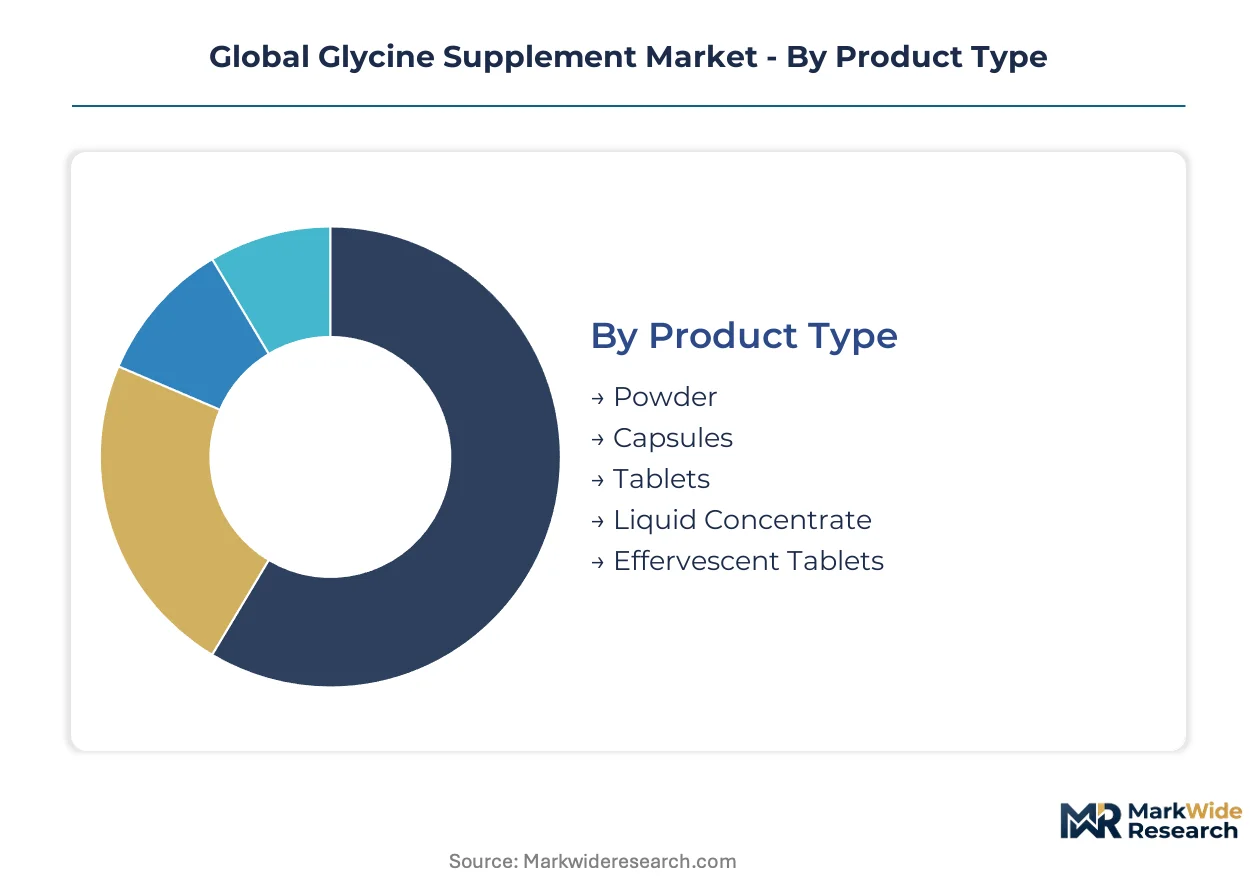
Segmentation in the glycine supplement market reveals distinct margin architectures and supply chain requirements across delivery formats and consumer touchpoints. Product form dictates manufacturing capital intensity, while application focus determines regulatory pathway complexity and pricing power.
Product Type:
After-sales service intensity varies sharply by product form, with liquid concentrates requiring cold-chain logistics support and powder formats demanding minimal post-purchase engagement.
- Powder:Bulk manufacturing efficiency enables flexible dosing protocols and dominates volume throughput across industrial-scale production lines. Demand concentrates in United States sports nutrition channels where athletes self-blend glycine into protein stacks, constrained by moisture-sensitive storage requirements that limit shelf-life in humid climates.
- Capsules:Convenience premiums capture margin pools through unit-dose portability and masking of glycine's characteristic sweetness. Germany's pharmacy distribution channels favor hard-shell gelatin encapsulation for condition-specific therapeutics, driven by precise dosing compliance among elderly consumers managing polypharmacy regimens.
- Tablets:Compression-formed solid dosage suits high-volume, low-margin contract manufacturing for private-label brands.
- Liquid Concentrate:Ready-to-dispense formats target pediatric and geriatric populations with swallowing difficulties.
- Effervescent Tablets:Rapid-dissolve formulations compete in functional beverage adjacencies with sensory-enhanced consumption experiences.
Powder holds the largest share; momentum sits with capsules.
Application:
Cost tier stratification separates commodity sports nutrition from premium therapeutic positioning, with sleep aid formulations commanding the steepest price per active gram.
- Sports Nutrition:Muscle recovery and collagen synthesis support drives athlete self-direction toward certified ingredient supply. United States fitness culture sustains consistent consumption through CrossFit and endurance training communities, constrained by peptide substitute encroachment from hydrolyzed collagen supplements with stronger marketing infrastructure.
- Sleep Aid:Non-habit-forming positioning captures consumers exiting melatonin dependency cycles through glycine's GABA-modulating mechanism. Japan's aging population concentrates demand for amino acid therapeutics, accelerated by MHLW stringent purity specifications that filter out non-specialized suppliers.
- Cognitive Support:Nootropic stacking applications retain higher price realization per active gram through biohacker community adoption.
- Joint Health:Collagen synthesis claims overlap with established glucosamine-chondroitin consumer segments.
- Liver Protection:Detoxification pathway support targets alcohol-conscious consumers and pharmaceutical co-administration protocols.
Sports Nutrition holds the largest share; Sleep Aid is climbing the fastest.
End User:
Customer type determines procurement scale and specification rigor, from individual fitness enthusiasts to pharmaceutical manufacturers requiring compendial-grade documentation.
- Nutritionists:Professional recommendation channels validate glycine for metabolic support and detoxification protocols.
- Fitness Enthusiasts:Self-directed supplementation drives powder format volume through direct-to-consumer platforms.
- Elderly Consumers:Sleep quality and joint health applications concentrate in Japan and Germany pharmacy channels.
- Clinical Researchers:Investigational use demands pharmaceutical-grade supply with full certificate-of-analysis documentation.
- Pharmaceutical Manufacturers:Excipient and active pharmaceutical ingredient procurement requires dual FDA food-grade and pharmaceutical-grade certification tracks.
Fitness Enthusiasts holds the largest share; momentum sits with Elderly Consumers.
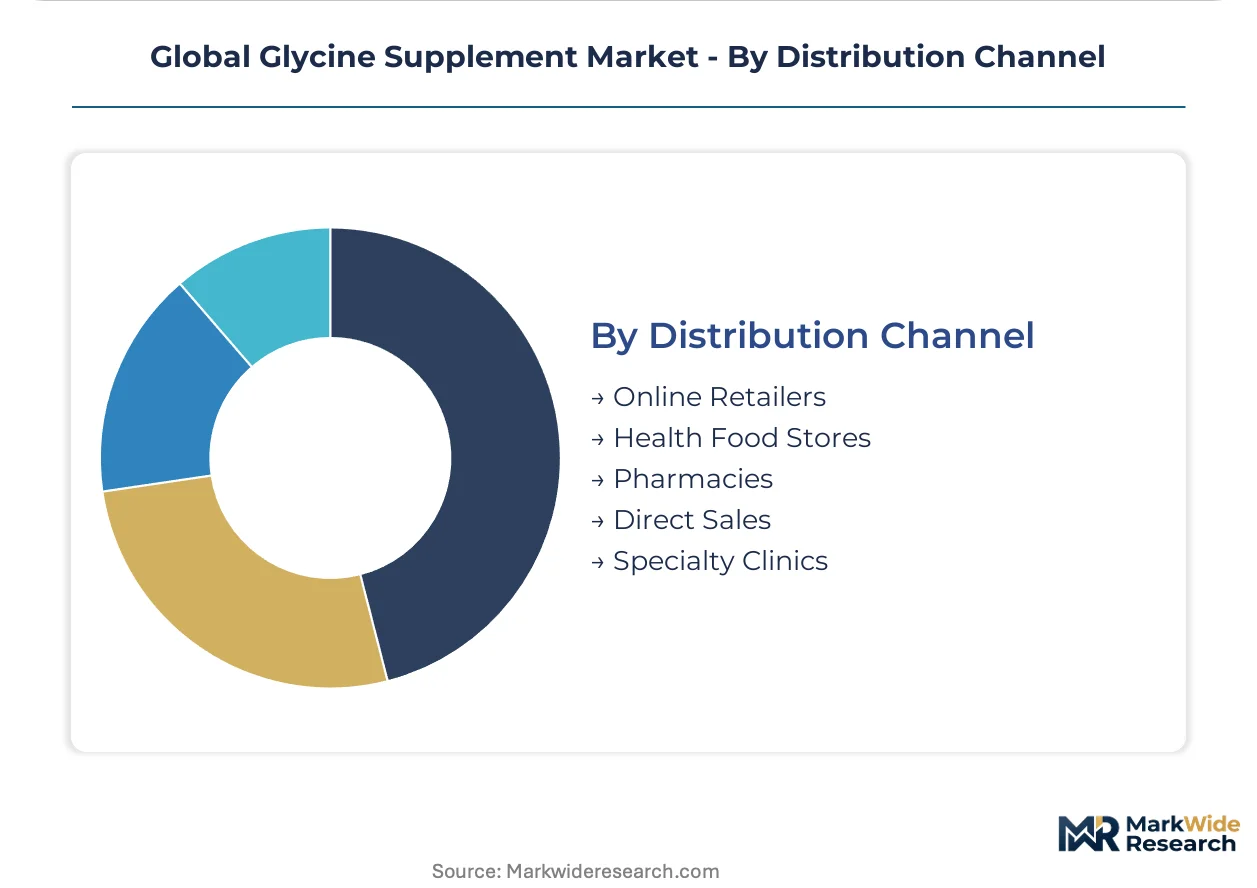
Distribution Channel:
Supply concentration favors established fermentation houses with traceable raw material chains as CSRD disclosure mandates reshape European procurement patterns.
- Online Retailers:Subscription models capture sleep aid and cognitive support segments through wellness platform bundling with biometric tracking.
- Health Food Stores:Clean-label certification convergence drives USDA Organic and Non-GMO Project verification premiums.
- Pharmacies:German pharmaceutical channel offers white space for condition-specific glycine therapeutics beyond sports nutrition commoditization.
- Direct Sales:Practitioner networks validate therapeutic claims through personalized consultation.
- Specialty Clinics:Functional medicine integration supports high-dose protocols for metabolic and neurological applications.
Online Retailers holds the largest share; Pharmacies is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation houses export pharmaceutical-grade glycine to United States sports nutrition distributors and Japanese therapeutic manufacturers, establishing the dominant trade-flow corridor for premium amino acid supply.
United States
FDA cGMP enforcement drives pharmaceutical-grade qualification timelines for domestic supplement brands. CrossFit and endurance training communities sustain powder-format consumption through direct-to-consumer platforms. California's wellness economy incubates subscription-based sleep aid formulations bundled with biometric tracking services.
Germany
EFSA novel food assessments compress ingredient qualification windows for non-traditional glycine sources. Pharmacy distribution channels favor hard-shell gelatin capsules for elderly polypharmacy management. Bavaria's chemical manufacturing belt anchors European fermentation capacity with backward-integrated precursor supply.
Japan
MHLW maintains the most stringent amino acid therapeutic purity specifications globally, filtering non-specialized suppliers from market access. Aging population demographics concentrate sleep aid demand in pharmacy channels. Kanto region's pharmaceutical cluster houses specialized fermentation facilities serving domestic excipient and API procurement.
China
SAMR food-grade and pharmaceutical-grade dual certification requirements reshape domestic supply chain configurations. Synthetic glycine production concentrates in coastal chemical parks with acetic acid feedstock proximity. Yangtze River Delta fermentation houses are narrowing cost gaps against petrochemical-derived alternatives through microbial strain optimization.
Global Glycine Supplement Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered certification tracks. The vendor base organizes around fermentation-derived pharmaceutical-grade supply, synthetic commodity production, and blended ingredient distribution. Three archetypes dominate: amino acid specialists with microbial optimization capabilities, diversified chemical conglomerates with captive raw material access, and ingredient distributors with clean-label certification infrastructure. Competitive moves concentrate on dual-track compliance investments and supply chain traceability documentation for CSRD-aligned European procurement.
Within the amino acid specialist tier, Ajinomoto Co., Inc. and Kyowa Hakko Bio Co., Ltd. represent Japanese fermentation expertise with established pharmaceutical-grade positioning. Evonik Industries AG anchors European production capacity through German chemical manufacturing infrastructure. These three exemplify the premium-tier vector where proprietary microbial strain development and impurity profile management create qualification barriers against commodity traders.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| Kyowa Hakko Bio Co., Ltd. |
| Archer Daniels Midland Company |
| Prinova Group LLC |
| GEO Specialty Chemicals Inc. |
| Yuki Gosei Kogyo Co., Ltd. |
| Showa Denko KK |
| Chattem Chemicals Inc. |
| Others |
Supply & Pricing Matrix
Petrochemical feedstock volatility between synthetic and fermentation-derived production routes determines both pricing tier spreads and supply chain configuration across pharmaceutical-grade and commodity glycine segments. Acetic acid and ammonia cost swings compress margins in synthetic production while bioprocess engineering advances enable fermentation houses to capture premium positioning through impurity profile certification.
Pricing Analysis
The technology-generation pricing gap separates fermentation-derived pharmaceutical-grade glycine from synthetic commodity supply, with microbial strain optimization commanding three-tier pricing structure across premium, standard, and economy levels. Certification grade under FDA cGMP and EFSA novel food assessments drives price differentiation alongside volume scale in contract manufacturing. Cost compression in synthetic tiers is intensifying because energy price spikes transmit directly through petrochemical feedstock costs. Sports nutrition distributors show highest price sensitivity while sleep aid formulations targeting elderly consumers in Japan and Germany exhibit lowest sensitivity due to therapeutic positioning.
Supply Chain Analysis
Tariff exposure between Chinese fermentation houses and United States sports nutrition distributors dominates supply chain risk assessment for pharmaceutical-grade glycine procurement. Production concentrates in China, Germany, and Japan with raw material dependencies on acetic acid, ammonia, and specialized microbial strains. Single-source vulnerability persists for pharmaceutical-grade supply qualified under Japan's MHLW specifications. Distribution runs through direct-to-consumer platforms for sleep aid and cognitive support segments while pharmacy channels handle condition-specific therapeutics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glycine supplement market represents early-cycle expansion as sleep aid applications capture consumers exiting melatonin dependency cycles, with fermentation-derived supply narrowing cost gaps against synthetic alternatives to enable broader pharmaceutical-grade adoption.
For Market Incumbents: Insulate pharmaceutical-grade positioning by deepening backward integration into precursor supply and accelerating microbial strain IP development to maintain impurity profile advantages against commodity traders. CSRD supply-chain disclosure mandates in Europe favor established fermentation houses with traceable documentation systems.
For New Entrants and Emerging Players: Pursue German pharmacy distribution channels for condition-specific glycine therapeutics targeting elderly polypharmacy management, where hard-shell gelatin capsule formats remain underpenetrated relative to sports nutrition commoditization. Clean-label certification convergence around USDA Organic and Non-GMO Project verification offers go-to-market differentiation.
For Investors and Strategic Acquirers: EFSA novel food assessment tightening reshapes the acquisition landscape toward fermentation houses with established 25-year consumption history documentation. Long-term viability centers on dual-track FDA food-grade and pharmaceutical-grade certification infrastructure. The signal to monitor is MHLW qualification timeline acceleration for non-specialized suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Strain Optimization | Proprietary fermentation organisms reduce impurity profiles below compendial thresholds for pharmaceutical-grade access. |
| Dual-Track Certification Investment | Simultaneous FDA food-grade and pharmaceutical-grade quality systems enable market access across supplement and therapeutic segments. |
| CSRD-Aligned Traceability Infrastructure | Raw material chain documentation satisfies European disclosure mandates and filters commodity traders from premium procurement. |
| Sleep Aid Formulation Expansion | Non-habit-forming positioning captures consumers exiting melatonin dependency through glycine's GABA-modulating mechanism. |
| Direct-to-Consumer Subscription Launch | Wellness platform bundling with biometric tracking displaces transactional supplement purchases in United States urban markets. |
Research Methodology
Operator-level perspectives from fermentation plant managers, pharmaceutical procurement leads, sports nutrition brand managers, and pharmacy category buyers anchored the qualitative base for this study. Primary interviews combined with secondary validation from FDA cGMP enforcement records, EFSA novel food assessment filings, MHLW purity specification documentation, and customs trade data. Bottom-up volume modeling across product formats and applications triangulated against top-down market sizing from amino acid production disclosures.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, application focus, end user archetype, and distribution channel. CAGRs derived from historical volume trajectories and adoption curve analysis for sleep aid and sports nutrition segments. Forecast inputs incorporated bioprocess engineering cost curves and regulatory qualification timeline compression.
Sensitivities concentrate around petrochemical feedstock volatility, MHLW specification stringency changes, and peptide substitute marketing investment levels. Forecasts reflect documented assumptions on fermentation cost convergence and dual-track certification adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Anti-Allergic Agent Ingredients Market
Pharmaceutical Ingredients
Biologic Excipients Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market