
 United States Fumaric Acid Market | 2026-2036
United States Fumaric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
United States Fumaric Acid Market Intelligence
Direct procurement channels between fumaric acid producers and food manufacturers is reshaping how bulk chemicals flow into the United States market. Bartek Ingredients leverages its Canadian manufacturing proximity to sustain cross-border supply reliability for North American food processors. Polynt anchors its position through backward integration into maleic anhydride feedstock, controlling critical input costs. Thirumalai Chemicals competes on specialized technical grades for unsaturated polyester resin applications.
Fumaric acid is a dicarboxylic acid with the molecular formula C4H4O4, produced industrially through catalytic isomerization of maleic acid or via fermentation of renewable carbohydrates, and functions primarily as an acidulant, pH modifier, and chemical intermediate across food, pharmaceutical, and industrial applications. Food grade fumaric acid dominates volume flows into the bakery and beverage sectors where it replaces citric acid in certain dry-mix applications due to superior cost economics and stability. Bio-based production routes are gaining structural attention as renewable feedstock technologies mature, though technical grade material still occupies the largest margin pool through chemical synthesis demand.
The FDA governs food-grade fumaric acid under 21 CFR 172.350, setting purity thresholds that directly determine which producers qualify for food-contact applications, while EPA regulations on maleic anhydride precursor emissions shape production economics at domestic manufacturing sites. OSHA process safety standards for chemical handling further constrain operational flexibility at conversion facilities. Stakeholders must monitor evolving FDA guidance on clean label petitions and bio-based certification pathways as these will determine which production technologies secure preferential market access.
Market Dynamics
Cross-border feedstock sourcing from Canadian petrochemical complexes is compressing domestic maleic anhydride margins and forcing Gulf Coast producers to reconfigure their procurement networks. This supply geography shift is redrawing competitive boundaries between integrated and merchant fumaric acid manufacturers.
Growth Catalysts
- Clean label petitions:FDA guidance on bio-based certification pathways is opening preferential market access for fermentation-derived acidulant grades in organic food formulations.
- Midwest chemical infrastructure:Concentrated maleic anhydride production in Texas and Louisiana creates captive feedstock pools that lower conversion costs for regional fumaric acid output.
- Unsaturated polyester resins:Technical grade demand from fiberglass-reinforced plastics manufacturers in the automotive and construction sectors is absorbing excess chemical synthesis capacity.
Market Restraints
- Maleic anhydride price volatility:Benzene and n-butane feedstock swings transmit directly into fumaric acid production economics, squeezing margin predictability for non-integrated producers.
- Canadian supply concentration:Bartek Ingredients' Ontario production base controls a disproportionate share of North American food-grade imports, creating single-source vulnerability for US processors.
- Citric acid substitution:Established acidulant supply chains and lower switching costs in beverage applications limit fumaric acid penetration despite superior dry-mix stability.
Strategic Opportunities
- Great Lakes biorefinery corridor:Corn belt carbohydrate feedstocks and existing ethanol infrastructure create geographic conditions for commercial-scale fermentation route deployment.
- Pharmaceutical excipient expansion:USP-grade fumaric acid for tablet disintegration and enteric coatings remains underdeveloped relative to food and industrial segments.
- OSHA process safety modernization:Updated chemical handling standards are accelerating capital investment in automated handling systems that reduce labor-dependent operational risk.
Industry Challenges
- FDA 21 CFR compliance timelines:Food additive petition processing delays extend qualification periods for new production facilities seeking acidulant certification.
- Dual-grade production complexity:Technical and food-grade switching requirements demand redundant purification trains that inflate capital intensity for multi-segment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Fumaric Acid Market |
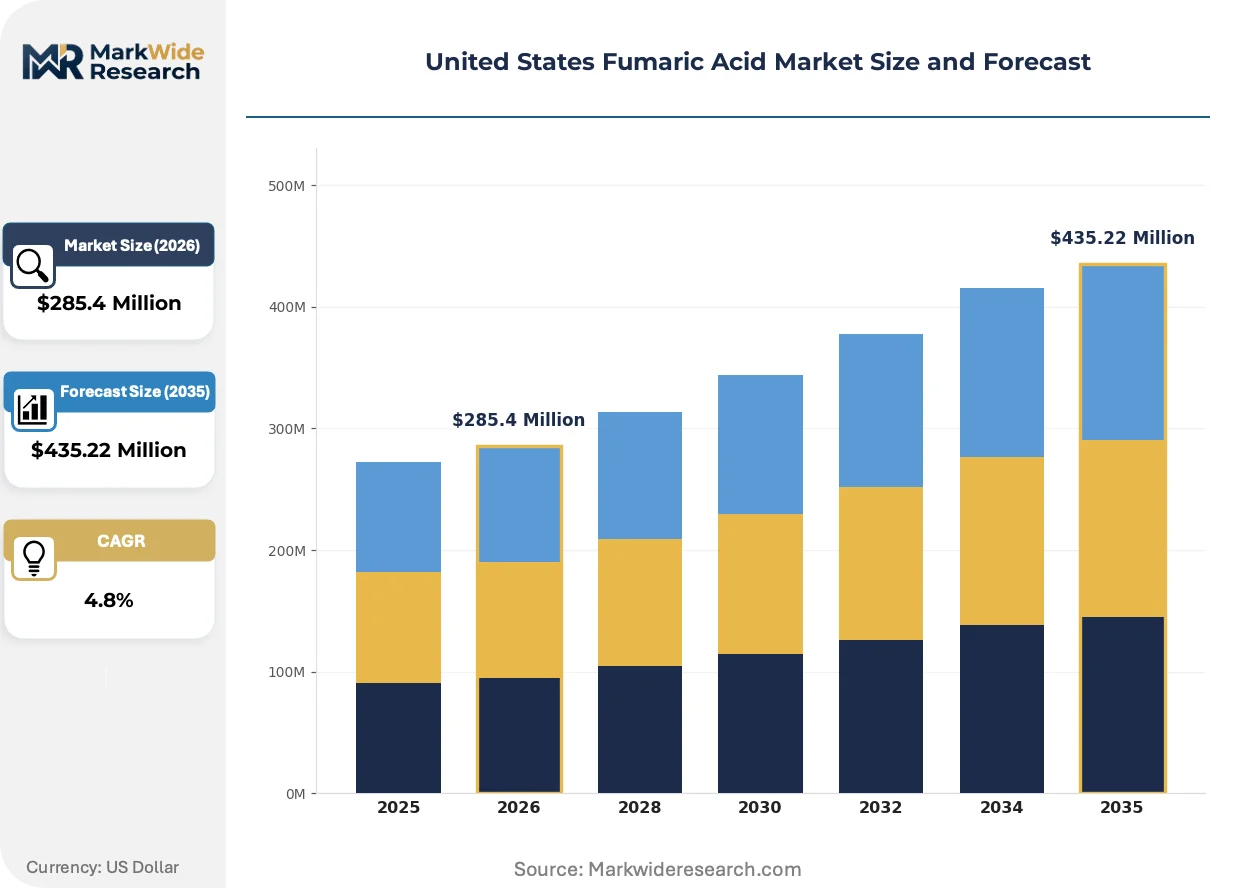
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Technical Grade, Pharmaceutical Grade, Bio-based Application: Food & Beverage, Personal Care, Pharmaceuticals, Chemical Synthesis End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Chemical Producers Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Fuso Chemical Co. Ltd, Merck KGaA, Bartek Ingredients, Anmol Chemicals, Actylis, Thirumalai Chemicals, Changmao Biochemical Engineering Company, NIPPON SHOKUBAI CO. LTD, Polynt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Fumaric Acid Market Strategic Shifts & Innovations
Digital process control systems and renewable feedstock chemistry are converging to transform how fumaric acid manufacturers manage yield variability and regulatory documentation. These shifts are compressing the gap between laboratory-scale bio-based routes and commercial chemical synthesis economics.
Fermentation-based production using engineered Rhizopus oryzae strains is virtualizing the traditional petrochemical value chain by enabling distributed manufacturing closer to carbohydrate feedstock sources. Specialty chemical producers in the Corn Belt are piloting these bioconversion platforms to reduce transportation costs and qualify for USDA bio-preferred procurement programs. The technology is virtualizing asset location decisions that historically favored coastal petrochemical clusters.
EPA regulations on maleic anhydride precursor emissions under the National Emission Standards for Hazardous Air Pollutants are tightening scrubber and thermal oxidizer requirements at domestic conversion facilities. Gulf Coast producers face retrofit capital obligations that favor larger integrated operations with environmental compliance economies of scale. Food-grade manufacturers are responding by segregating technical and acidulant production lines to isolate regulatory exposure.
Direct mill-to-manufacturer contracting is displacing distributor intermediaries in bulk acidulant procurement as food processors seek lot traceability and volume flexibility. Large bakery and beverage conglomerates are negotiating frame contracts with single-source fumaric acid suppliers that embed quality auditing rights and inventory management obligations. This channel compression is most visible in the Midwest, where rail-served chemical terminals enable just-in-time delivery to major processing facilities without warehousing intermediaries.
United States Fumaric Acid Market Segmentation
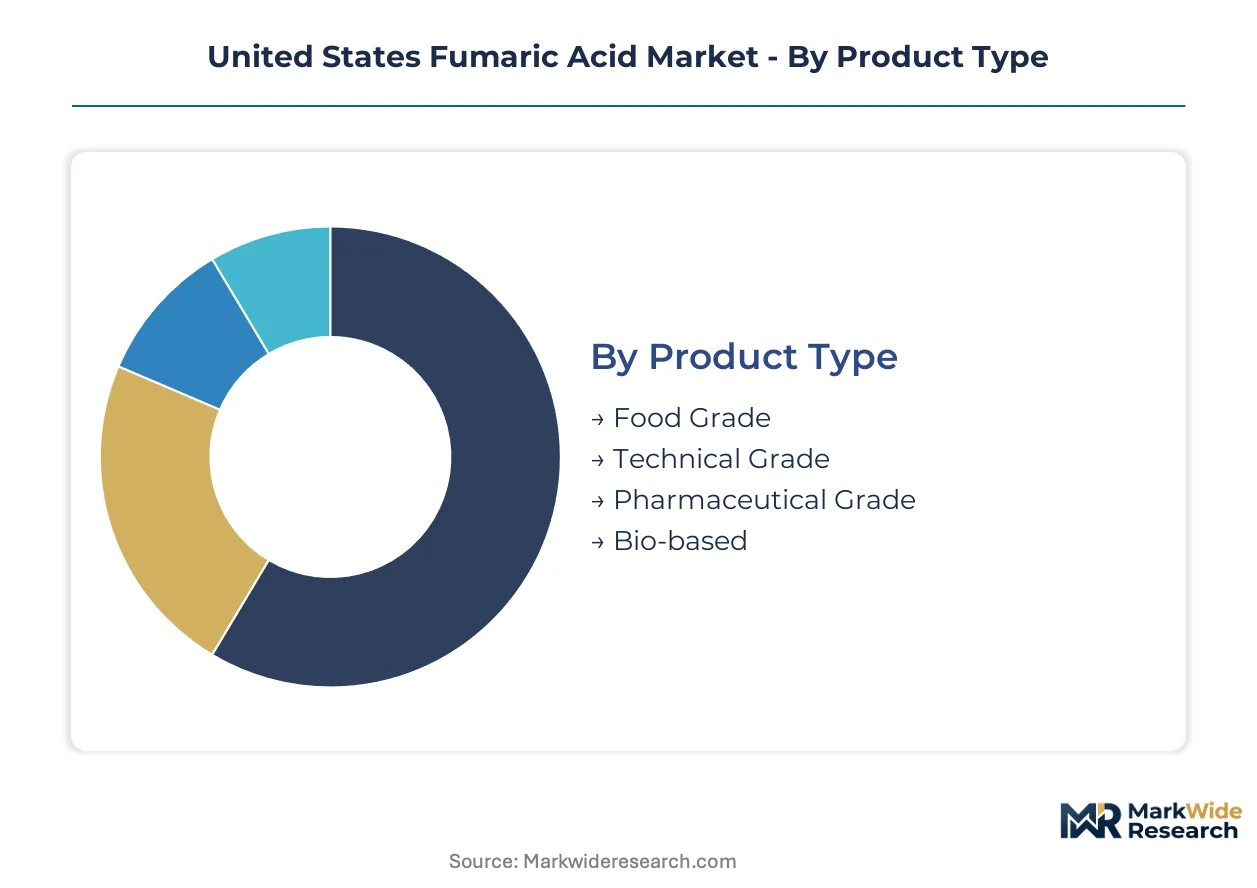
Fumaric acid segmentation in the United States reflects divergent purity requirements and regulatory pathways that reshape procurement economics across food, industrial, and pharmaceutical channels. Understanding grade-specific demand cycles and channel preferences exposes where margin pools concentrate and where switching costs protect incumbent positions.
Product Type:
Cycle times vary dramatically across grades—food-grade lots turn monthly through bakery procurement cycles while technical grade moves in quarterly batches tied to resin production schedules. Pharmaceutical grade operates on annual qualification timelines that freeze supplier relationships.
- Food Grade:Purity thresholds under FDA 21 CFR 172.350 mandate sub-10 ppm heavy metal limits and specific particle size distributions for dry-mix applications. Midwest bakery and beverage processors in Illinois and Ohio drive volume concentration, though FDA petition processing delays constrain new supplier entry and extend incumbent contract durations.
- Technical Grade:Lower purity specifications (98-99% assay) serve unsaturated polyester resin manufacturers in Texas and Louisiana fiberglass operations. Demand concentrates in Gulf Coast chemical clusters where maleic anhydride feedstock integration lowers conversion costs, though benzene price volatility transmits directly into margin compression for non-integrated producers.
- Pharmaceutical Grade:USP-NF compliance with enhanced endotoxin and microbial limits for tablet excipient applications.
- Bio-based:Fermentation-derived material from engineered Rhizopus strains qualifying for USDA BioPreferred procurement preferences.
Technical grade dominates installed base by volume. Bio-based is where expansion concentrates as organic food formulators seek fermentation-derived acidulant alternatives.
Application:
Cost tier stratification separates commodity acidulant uses from premium excipient and specialty chemical applications, with regulatory burden escalating across the value stack.
- Food & Beverage:Acidulant and pH modification functions in powdered drink mixes, baking powders, and fruit-flavored applications where fumaric acid displaces citric acid on cost and stability metrics. Beverage processors in California and Florida represent concentrated demand, constrained by established citric acid supply chains that limit switching despite superior dry-mix economics.
- Chemical Synthesis:Intermediate for alkyd resins, paper sizing agents, and specialty ester production. Demand clusters in Texas and Louisiana petrochemical corridors where downstream integration into coatings and plastics manufacturing creates captive offtake, though EPA NESHAP compliance on maleic anhydride precursors elevates environmental capital requirements.
- Personal Care:pH adjustment and buffering in cosmetic formulations with moderate purity requirements.
- Pharmaceuticals:Tablet disintegrant and enteric coating applications with stringent USP documentation burdens.
Food and beverage anchors volume flows. Pharmaceuticals is climbing the fastest as excipient outsourcing trends expand contract manufacturing demand for USP-grade material.
End User:
Customer type determines contract structure—food manufacturers negotiate frame agreements with embedded auditing rights while chemical producers favor spot-indexed procurement tied to maleic anhydride benchmarks.
- Food Manufacturers:Large bakery and beverage conglomerates procuring bulk acidulant under direct mill-to-plant contracts that displace distributor intermediaries. Rail-served Midwest terminals enable just-in-time delivery without warehousing layers, though single-source concentration with Canadian suppliers creates vulnerability in cross-border disruption scenarios.
- Chemical Producers:Integrated and merchant manufacturers of unsaturated polyester resins and downstream derivatives. Gulf Coast operations leverage captive maleic anhydride supply, while independent converters face margin pressure from feedstock volatility and Canadian import competition.
- Cosmetic Companies:Mid-tier personal care formulators with moderate volume requirements and flexible specification tolerance.
- Pharmaceutical Firms:Dosage form developers and contract manufacturers requiring extended qualification timelines and audit-intensive supplier relationships.
Chemical producers dominate procurement scale. Pharmaceutical firms is where contract value expansion concentrates as excipient outsourcing accelerates.
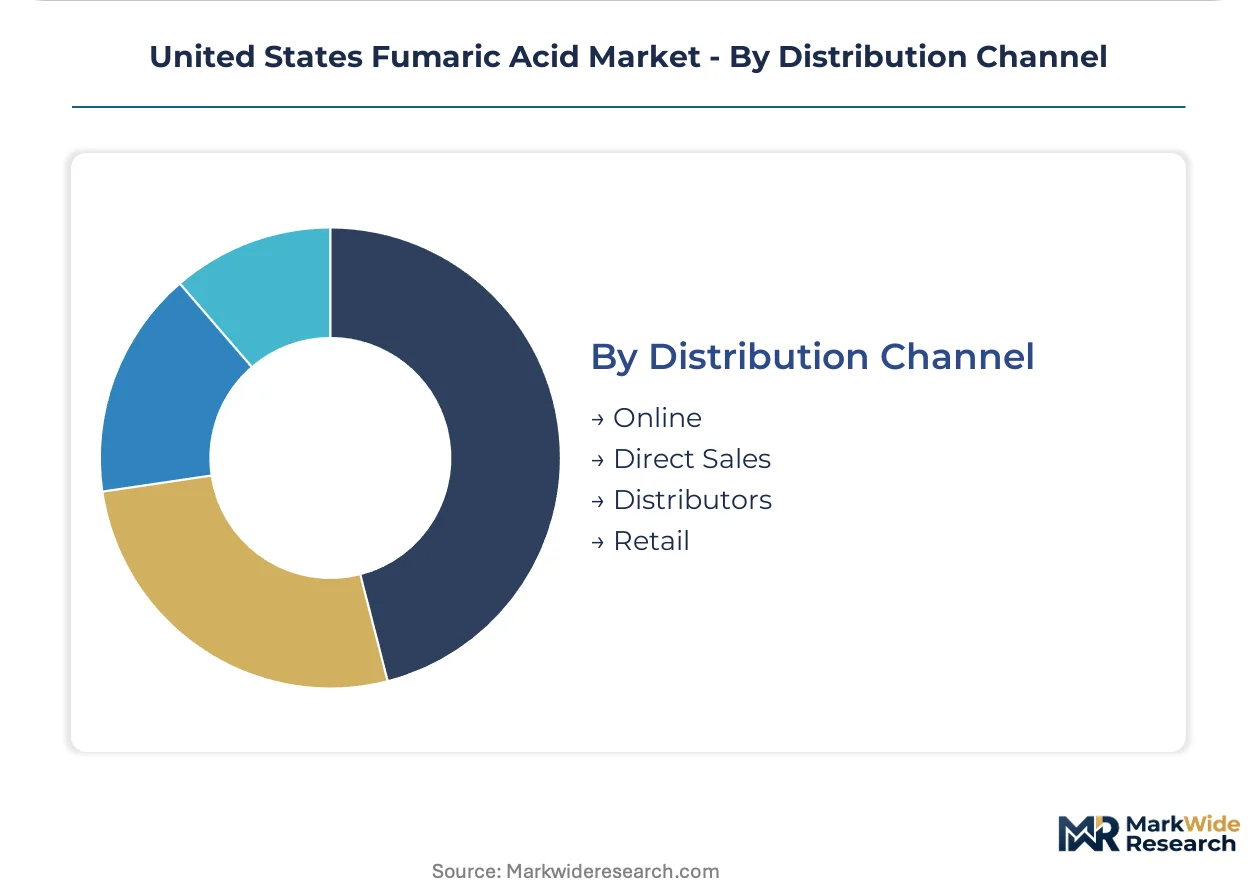
Distribution Channel:
Supply concentration dictates channel efficiency—bulk rail and tanker movements favor direct relationships while fragmented end users sustain distributor relevance.
- Direct Sales:Producer-to-manufacturer contracting for food-grade bulk acidulant with embedded lot traceability, quality auditing rights, and inventory management obligations. Large Midwest processors leverage volume concentration to compress channel margins and secure supply security.
- Distributors:Regional chemical distributors serving smaller food processors and personal care formulators with warehousing and technical support services. Value concentrates in blending and repackaging capabilities that address specification customization.
- Online:E-procurement platforms for sample quantities and small-batch pharmaceutical grade.
- Retail:Limited consumer-facing sales through specialty chemical suppliers.
Direct sales dominates volume throughput. Distributors is where service-based differentiation concentrates for mid-tier account penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage tilts toward Gulf Coast producers with captive maleic anhydride supply, while Midwest processors absorb transport premiums on cross-border Canadian imports. This geographic asymmetry redistributes margin capture between feedstock-integrated and merchant conversion operations.
Texas and Louisiana Gulf Coast
Petrochemical corridor density concentrates maleic anhydride output for captive fumaric acid conversion. EPA National Emission Standards for Hazardous Air Pollutants compliance costs favor larger integrated operations with environmental economies of scale. Houston and Lake Charles host downstream unsaturated polyester resin manufacturers absorbing technical grade volumes.
Illinois and Ohio Midwest
Bakery and beverage processors in Chicago and Columbus drive food-grade acidulant demand through direct mill-to-plant procurement contracts. FDA 21 CFR 172.350 certification requirements extend supplier qualification timelines and freeze incumbent relationships. Rail-served chemical terminals enable just-in-time delivery without distributor warehousing layers.
California and Florida Coasts
Beverage formulation clusters in Los Angeles and Tampa represent concentrated acidulant demand constrained by established citric acid supply chains. State-level environmental regulations on chemical handling exceed federal OSHA baselines and elevate operational compliance costs. West Coast processors face freight disadvantages on Canadian import supply lines.
Great Lakes Corn Belt
Carbohydrate feedstock abundance and existing ethanol infrastructure create conditions for fermentation-based production piloting. USDA BioPreferred procurement preferences incentivize bio-based acidulant qualification for organic food formulations. Iowa and Minnesota biorefinery development targets distributed manufacturing closer to renewable raw material sources.
United States Fumaric Acid Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in feedstock and purification niches. Market structure concentrates around backward-integrated petrochemical operators and specialized acidulant manufacturers with FDA-certified food-grade capabilities. Three archetypes dominate: integrated maleic anhydride converters, cross-border food-grade importers, and fermentation-based bio-alternative developers. Capacity expansion and direct procurement channel compression constitute the primary competitive vectors reshaping supplier relationships.
Among North American food-grade suppliers, Bartek Ingredients occupies a position exemplifying cross-border supply reliability through Canadian manufacturing proximity. Polynt anchors the integrated converter archetype with upstream maleic anhydride control. Thirumalai Chemicals represents specialized technical grade production for industrial resin applications.
| Leading Market Players |
|---|
| Fuso Chemical Co. Ltd |
| Merck KGaA |
| Bartek Ingredients |
| Anmol Chemicals |
| Actylis |
| Thirumalai Chemicals |
| Changmao Biochemical Engineering Company |
| NIPPON SHOKUBAI CO. LTD |
| Polynt |
| Others |
Cost & Logistics Intelligence
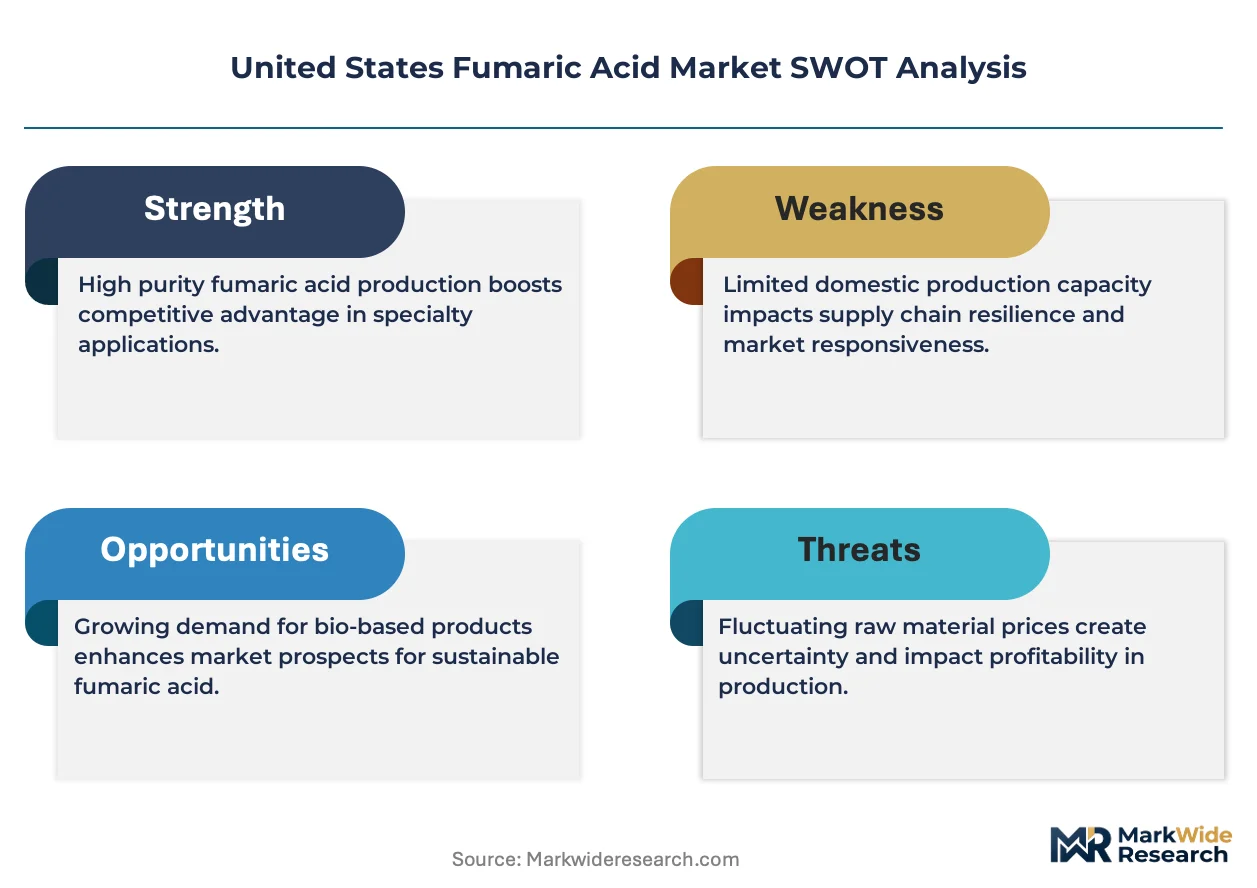
Canadian import concentration determines both pricing tier spreads and supply chain shape, with Bartek Ingredients' Ontario production base creating single-source vulnerability that compresses margins for US processors while elevating premiums on qualified alternative supply. FDA 21 CFR 172.350 certification requirements extend supplier qualification timelines, freezing incumbent relationships and widening the spread between certified food-grade and technical-grade pricing.
Pricing Analysis
Configured-to-order pricing for USP-grade pharmaceutical material commands substantial premiums over standard food-grade acidulant contracts. Three-tier pricing structure across pharmaceutical, food-grade, and technical levels reflects certification burden and purity threshold differentiation. Pricing pressure stems from benzene and n-butane feedstock volatility transmitting through maleic anhydride costs. Chemical producers exhibit highest price sensitivity due to spot-indexed procurement, while pharmaceutical firms accept premium pricing for extended qualification security.
Supply Chain Analysis
Extended payment terms from large Midwest bakery conglomerates are reshaping working capital requirements for acidulant suppliers. Supply concentrates in Canada, Texas, and Louisiana, with maleic anhydride feedstock drawing from Gulf Coast petrochemical complexes and benzene derivatives. Raw material dependencies rest on benzene, n-butane, and renewable carbohydrate streams. Single-source vulnerability on Canadian imports constitutes the dominant structural risk. Distribution runs through direct mill-to-plant rail contracts that displace distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large Midwest food processors negotiating frame contracts with embedded auditing rights, fragmenting supplier leverage and compressing channel margins. Direct procurement channel compression favors volume-scale incumbents while constraining smaller distributors.
For Market Incumbents:Insulate food-grade certification positions through redundant purification train investments that enable rapid technical-to-acidulant grade switching. FDA petition processing delays protect qualified suppliers from new entrant displacement. Backward integration into maleic anhydride feedstock anchors margin control against benzene volatility.
For New Entrants and Emerging Players:Establish a beachhead in pharmaceutical-grade USP-NF material where extended qualification timelines freeze incumbent relationships and limit price competition. Great Lakes biorefinery corridor proximity to corn belt carbohydrate feedstocks offers the most penetrable geography for fermentation-based production. USDA BioPreferred procurement preferences provide a differentiated go-to-market angle for organic food formulators.
For Investors and Strategic Acquirers:FDA guidance on bio-based certification pathways reshapes the acquisition landscape by determining which production technologies secure preferential market access. Five-to-ten year viability favors fermentation-capable assets with distributed manufacturing potential over coastal petrochemical-dependent operations. Target acquisition archetypes include Corn Belt biorefinery platforms with Rhizopus strain engineering capabilities. The signal to watch is clean label petition approval velocity for organic acidulant qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Maleic Anhydride | Captive feedstock supply insulates Polynt and Gulf Coast producers from benzene price volatility. |
| Fermentation Route Scale-Up | USDA BioPreferred qualification opens organic food procurement channels for Corn Belt biorefinery developers. |
| Pharmaceutical Grade Capacity Addition | USP-NF certification addresses underdeveloped excipient demand from tablet disintegrant outsourcing trends. |
| Direct Mill-to-Plant Contracting | Rail-served terminal infrastructure enables just-in-time delivery that displaces distributor intermediaries. |
| Dual-Grade Production Line Segregation | Isolated technical and acidulant trains reduce FDA 21 CFR compliance exposure and regulatory risk. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Primary interviews covered plant managers at maleic anhydride conversion facilities, procurement leads at Midwest bakery and beverage processors, distribution channel partners in regional chemical terminals, and technical R&D directors at fermentation pilot operations. Secondary sources included FDA 21 CFR filings, EPA NESHAP compliance records, USITC trade data, and SEC 10-K disclosures from listed chemical producers. Bottom-up volume estimates triangulated against top-down market sizing.
Forecast inputs considered grade tier segmentation across food-grade, technical-grade, pharmaceutical-grade, and bio-based categories; end-use industry demand cycles in bakery, beverage, resin, and excipient applications; and regional production hub economics across Gulf Coast petrochemical corridors and Great Lakes biorefinery zones. CAGRs derived from regression analysis against maleic anhydride feedstock pricing, FDA certification timeline trajectories, and organic food formulation adoption curves across the projection horizon.
Sensitivities concentrate around benzene price volatility, FDA petition processing delays, and Canadian cross-border disruption scenarios. Forecasts reflect documented assumptions on feedstock cost trajectories and regulatory approval velocities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Ammonium Dichromate Market
Bulk Chemicals
Global Tetrahydrofuran Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Crude Tall Oil Derivative Market
Bulk Chemicals
Global Vanadium Pentoxide Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
North America Starch Derivatives Market
Bulk Chemicals
Ethylene Glycol Market
Bulk Chemicals
Polyferric Sulfate Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
Europe Methyl Acrylate Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
Global Sodium Borohydride Market
Bulk Chemicals
Phosphate Rock Market