
 Sodium Bicarbonate Market | 2026-2036
Sodium Bicarbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Bicarbonate Market Analysis
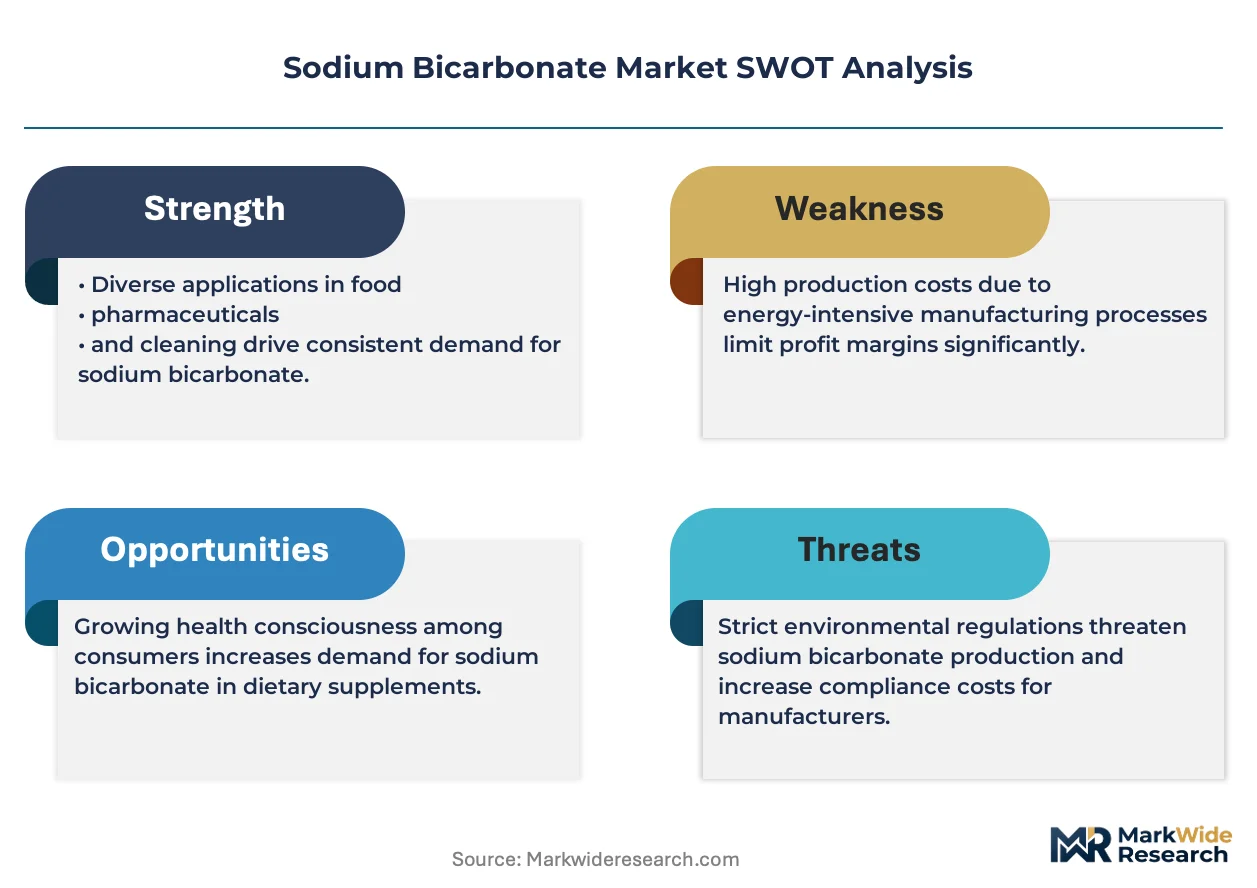
USP-NF monograph compliance for pharmaceutical-grade sodium bicarbonate is redrawing competitive boundaries among producers. Solvay SA leverages its integrated trona mining and refining operations to sustain cost leadership across European supply chains. Tata Chemicals anchors its position through captive soda ash capacity at Mithapur, giving it upstream control over feedstock quality and volume.
Sodium bicarbonate is a white crystalline powder with the chemical formula NaHCO₃, typically manufactured through the Solvay process or extracted from natural trona deposits, and functions primarily as a mild alkaline agent across food, pharmaceutical, and industrial systems. Food-grade material commands the largest volume share given its role as a leavening agent in baked goods, while pharmaceutical-grade carries the highest margin pool due to stringent purity requirements for antacid and dialysis applications. Industrial-grade segments compete primarily on delivered cost for flue gas treatment and chemical processing uses.
The US FDA enforces Current Good Manufacturing Practice standards for pharmaceutical-grade sodium bicarbonate through drug master file reviews, while the EPA regulates its discharge in industrial wastewater under effluent limitation guidelines. India's CDSCO mandates import registration and testing protocols for pharmaceutical raw materials, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards to anticipate shifts in qualification requirements and sourcing flexibility.
Market Dynamics
Pharmaceutical-grade purity requirements are compressing the supplier base as REACH compliance and USP monograph harmonization force capital upgrades among trona-based and synthetic producers. This regulatory tightening favors integrated manufacturers with captive feedstock control over merchant market participants.
Growth Catalysts
- Dialysis solution expansion:Pharmaceutical compounders are expanding sodium bicarbonate buffer capacity in hemodialysis concentrates to serve chronic kidney disease treatment protocols. This end-use pull is accelerating demand for low-heavy-metal grades.
- India PLI scheme:Domestic pharmaceutical manufacturing incentives under India's Production Linked Incentive scheme are accelerating consumption of high-purity sodium bicarbonate for active pharmaceutical ingredient synthesis.
- REACH purity mandates:ECHA enforcement of updated impurity thresholds for pharmaceutical excipients is disqualifying marginal producers and consolidating supply among compliant manufacturers.
Market Restraints
- Trona deposit concentration:Natural sodium bicarbonate feedstock concentrates in Wyoming's Green River Basin, creating geographic supply vulnerability to rail logistics disruptions and energy cost spikes.
- Energy input volatility:Synthetic production via the Solvay process remains exposed to natural gas and electricity price swings that compress margins during feedstock inflation cycles.
- Alternative alkalis:Sodium carbonate and potassium bicarbonate substitute for certain antacid and industrial neutralization applications where purity thresholds permit flexibility.
Strategic Opportunities
- Biopharma fermentation buffers:Cell culture media and monoclonal antibody production processes are adopting pharmaceutical-grade sodium bicarbonate for pH control in single-use bioreactor systems.
- Carbon capture utilization:Direct air capture and point-source carbon mineralization projects are piloting sodium bicarbonate as a stable carbon sequestration product with industrial off-take potential.
- CDSCO import substitution:India's tightening pharmaceutical raw material registration requirements create opening for domestic producers to displace Chinese and European import volumes.
Industry Challenges
- Pharmacopeial harmonization complexity:Divergent heavy metal limits between USP, EP, and IP monographs force producers to maintain separate inventory pools and analytical protocols.
- Cleanroom packaging infrastructure:Pharmaceutical-grade certification requires ISO 8 or better filling environments, demanding seven-figure capital commitments for bagging and containment systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Bicarbonate Market |
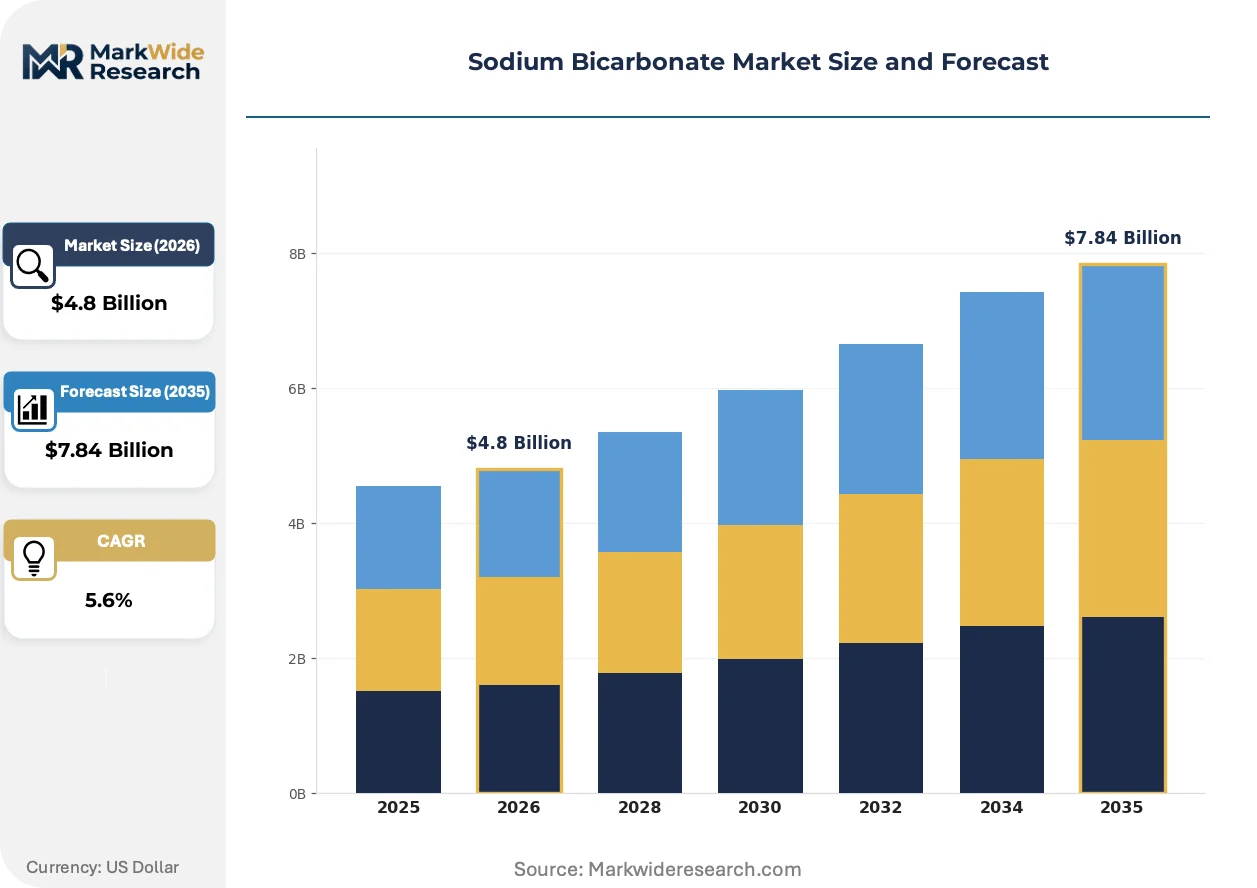
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Technical Grade End User: Food Industry, Pharmaceutical Companies, Cleaning Products, Fire Extinguishing Application: Leavening Agent, Antacid, pH Buffer, Cleaning Agent Packaging Type: Bags, Drums, Bulk Containers, Sachets |
| Companies Covered | Tosoh Corporation, FMC, Solvay SA, NIRMA, Asahi, Tata Chemicals, Natural Soda, Ciner Group, Church & Dwight Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Bicarbonate Market Emerging Trajectories
Continuous processing technology and analytical instrumentation advances are compressing batch cycle times while tightening impurity detection thresholds. These shifts are redrawing capital efficiency curves among integrated and merchant producers.
Membrane electrolysis refinement of sodium bicarbonate crystallization is miniaturizing purification footprints while enabling real-time heavy metal monitoring. Biopharma contract manufacturers are adopting these compact systems to reduce working capital tied to inventory. The technology is compressing the economic advantage of legacy trona-based bulk production for pharmaceutical volumes.
REACH candidate list expansion for microplastic additives is forcing reformulation of anti-caking agents used in sodium bicarbonate grades. Compounders serving European pharmaceutical and food markets are qualifying cellulose-based alternatives ahead of 2026 restriction deadlines. The regulation is accelerating R&D spend among excipient suppliers with European manufacturing exposure.
Direct sourcing from producers is displacing distributor intermediation among large pharmaceutical compounders seeking supply chain transparency. Tier-one drug manufacturers are auditing trona mines and Solvay plants for ESG compliance before qualifying approved supplier lists. This pattern is most pronounced in Germany and Switzerland where CDMO consolidation has concentrated purchasing power.
Sodium Bicarbonate Market Segmentation
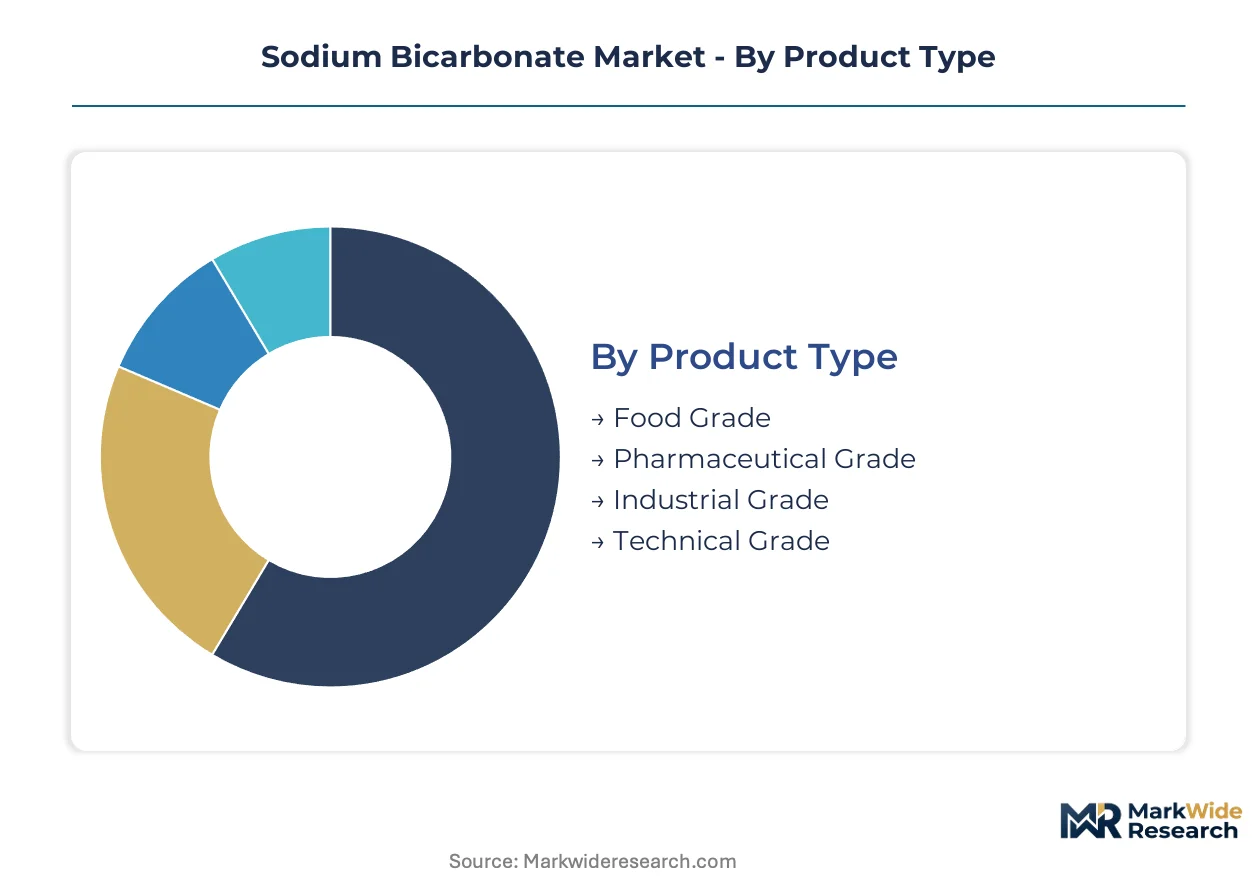
Sodium bicarbonate grades diverge sharply in purity thresholds, packaging requirements, and regulatory burdens. Channel economics favor bulk industrial shipments through direct contracts, while pharmaceutical and food grades command specialized distribution networks with certificate-of-analysis documentation.
Product Type:
Food-grade material moves through FMCG distributors and bakery supply chains, pharmaceutical-grade through audited API suppliers, and industrial grades via chemical distributors and direct mill procurement.
- Food Grade:Complies with FCC and JECFA purity standards for direct human consumption, with residual heavy metal limits below 10 ppm. Demand concentrates in commercial baking operations across India and the United States, where clean-label ingredient sourcing pressures are tightening supplier qualification protocols.
- Pharmaceutical Grade:Meets USP-NF, EP, and IP monograph specifications with endotoxin testing and microbial limits verification. Dialysis concentrate manufacturers in Germany and Switzerland are expanding offtake for hemodialysis buffer solutions, pulling supply toward dedicated pharmaceutical production lines.
- Industrial Grade:Standard purity for flue gas desulfurization and chemical neutralization.
- Technical Grade:Intermediate specification for laboratory reagents and specialty chemical synthesis.
By volume, Industrial Grade leads. By growth pace, Pharmaceutical Grade is climbing the fastest.
End User:
Cost tier stratification separates commodity bulk buyers from premium-grade purchasers, with pharmaceutical and food segments absorbing purity-related price premiums.
- Food Industry:Encompasses commercial bakeries, confectionery manufacturers, and beverage processors using sodium bicarbonate as a leavening agent and pH modifier. Large multinational food manufacturers in the United States are consolidating supplier bases to reduce audit burden, favoring integrated producers with global manufacturing footprints.
- Pharmaceutical Companies:Covers API synthesis, antacid formulation, and dialysis concentrate production. India's CDSCO registration requirements for imported raw materials are accelerating domestic sourcing shifts among formulation manufacturers in Hyderabad and Ahmedabad.
- Cleaning Products:Household and industrial abrasive and deodorizing formulations.
- Fire Extinguishing:Dry chemical suppression systems and specialized aerospace applications.
Food Industry commands the largest volume position. Pharmaceutical Companies show the steepest margin expansion trajectory.
Application:
Customer type segmentation distinguishes between formulation specialists seeking functional performance and processors treating sodium bicarbonate as a commodity input.
- Leavening Agent:Thermal decomposition releases carbon dioxide in dough systems, requiring controlled particle size distribution for consistent rise profiles. Artisan and industrial bakeries in France and Italy are specifying low-sodium variants to meet reformulated product nutrition claims.
- Antacid:Rapid neutralization of gastric acid with effervescent tablet and liquid suspension formulations. OTC pharmaceutical manufacturers in Japan are qualifying new suppliers to meet PMDA post-market surveillance requirements for excipient traceability.
- pH Buffer:Biological and chemical process stabilization across laboratory and production environments.
- Cleaning Agent:Mild abrasive and alkaline degreasing in household and industrial formulations.
Leavening Agent holds volume dominance. Antacid applications are gaining share fastest on dialysis and biopharma fermentation demand.
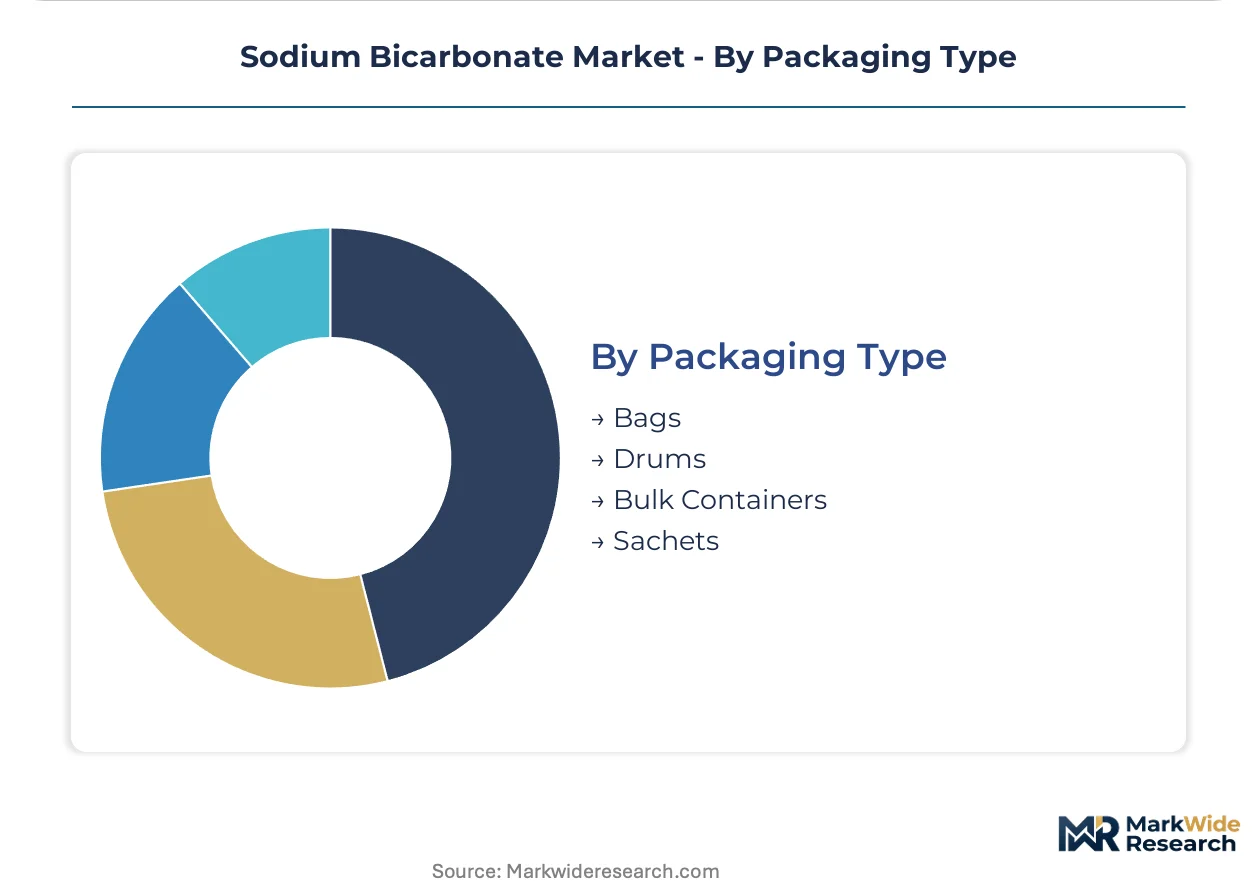
Packaging Type:
Supply concentration shapes packaging infrastructure investment, with pharmaceutical and food grades requiring ISO-certified cleanroom filling capabilities.
- Bags:Multi-layer laminated construction with moisture barriers for food and technical grades, typically 25-50 kg units. Regional distributors in Brazil are consolidating bagging operations to serve ANVISA-registered pharmaceutical compounders with segregated inventory pools.
- Drums:Fiber and steel containment for pharmaceutical-grade material with tamper-evident sealing. Swissmedic-inspected facilities in Basel and Zurich are mandating dedicated drum filling lines to prevent cross-contamination with industrial grades.
- Bulk Containers:Intermediate bulk containers and tanker shipments for industrial-scale consumers.
- Sachets:Unit-dose packaging for retail antacid and baking powder applications.
Bags dominate shipment volumes. Drums are expanding most quickly on pharmaceutical-grade certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for pharmaceutical manufacturing is redrawing procurement patterns for high-purity sodium bicarbonate across Asia-Pacific supply chains. Regulatory tightening in Europe and North America is compressing the qualified supplier base while concentrating volume among integrated producers with captive feedstock control.
United States
Pharmaceutical compounders in New Jersey and North Carolina are expanding dialysis concentrate production lines to serve chronic kidney disease treatment protocols. The FDA enforces Current Good Manufacturing Practice standards through drug master file reviews that disqualify marginal producers. Wyoming's Green River Basin hosts the dominant natural trona mining operations that supply feedstock for domestic pharmaceutical-grade refining.
Germany
Dialysis solution manufacturers in Baden-Württemberg and Bavaria are pulling supply toward dedicated pharmaceutical production lines with endotoxin verification. ECHA enforcement of REACH purity mandates for pharmaceutical excipients is consolidating procurement among compliant manufacturers. The Rhine-Ruhr industrial corridor maintains synthetic production capacity exposed to natural gas price volatility.
India
Formulation manufacturers in Hyderabad and Ahmedabad are accelerating domestic sourcing shifts under CDSCO import registration requirements for pharmaceutical raw materials. The Production Linked Incentive scheme is expanding active pharmaceutical ingredient synthesis capacity that consumes high-purity sodium bicarbonate. Gujarat's Mithapur complex anchors captive soda ash production that feeds downstream bicarbonate refining.
Japan
OTC pharmaceutical manufacturers are qualifying new suppliers to meet PMDA post-market surveillance requirements for excipient traceability. The Kanto region around Tokyo concentrates antacid and effervescent tablet formulation operations. Osaka-based compounders are adopting membrane electrolysis refinement systems to compress batch cycle times for biopharma fermentation buffers.
Switzerland
Swissmedic-inspected facilities in Basel and Zurich mandate dedicated drum filling lines to prevent cross-contamination with industrial grades. Contract manufacturing organizations are auditing trona mines and Solvay plants for ESG compliance before qualifying approved supplier lists. The country's pharmaceutical cluster represents concentrated purchasing power that is displacing distributor intermediation.
Sodium Bicarbonate Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory certification dimensions. The supplier base compresses toward integrated manufacturers with captive trona mining or soda ash capacity as REACH compliance and USP monograph harmonization force capital upgrades. Three archetypes dominate: trona-based natural producers with geographic feedstock concentration, synthetic Solvay process operators with energy cost exposure, and regional specialists serving protected domestic markets. Consolidation proceeds through backward integration into feedstock control and cleanroom packaging infrastructure investment.
Among the trona-based natural producers, Solvay SA and Ciner Group occupy positions exemplifying integrated supply chain control from mine to pharmaceutical-grade refining. Tata Chemicals represents the synthetic-captive archetype with upstream soda ash capacity at Mithapur feeding downstream bicarbonate production. These three companies anchor the competitive structure that regulatory tightening is reinforcing.
| Leading Market Players |
|---|
| Tosoh Corporation |
| FMC |
| Solvay SA |
| NIRMA |
| Asahi |
| Tata Chemicals |
| Natural Soda |
| Ciner Group |
| Church & Dwight Company |
| Others |
Supply Flow & Price Mechanics
Sixty-day pharmaceutical-grade inventory cycles in European distribution hubs concentrate pricing power among REACH-compliant manufacturers with captive Wyoming trona feedstock. This lead-time compression amplifies margin premiums for USP-certified material while forcing merchant producers toward industrial-grade commoditization.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical and industrial grades. Three-tier pricing structure across pharmaceutical, food, and industrial levels reflects endotoxin testing, cleanroom packaging, and heavy metal verification burdens. Cost compression in technical grades intensifies because synthetic Solvay producers absorb natural gas volatility without feedstock integration. Pharmaceutical compounders in Germany and Switzerland show least price sensitivity; industrial bulk buyers in flue gas treatment exhibit highest elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Europe lanes extend inbound logistics costs for Indian pharmaceutical manufacturers sourcing Wyoming trona. Supply concentrates in the United States, India, and Belgium, with feedstock anchored in Wyoming's Green River Basin. Synthetic production draws from soda ash, natural gas, and ammonia inputs. Single-source vulnerability to rail logistics disruptions from Wyoming threatens just-in-time dialysis concentrate supply. Distribution runs through audited API suppliers for pharmaceutical grades and chemical distributors for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane electrolysis refinement is compressing batch cycle times for biopharma fermentation buffers, creating a regulatory-technology inflection that rewards capital investment in real-time heavy metal monitoring.
For Market Incumbents: Secure captive trona mining positions or synthetic soda ash integration to defend against merchant market margin erosion. ECHA REACH candidate list expansion for microplastic additives threatens anti-caking agent formulations, requiring cellulose-based R&D redirection. Backward integration into Wyoming feedstock control remains the priority defensive lever. For New Entrants and Emerging Players: Anchor in India's CDSCO import substitution opportunity as domestic pharmaceutical manufacturing accelerates under PLI incentives. Biopharma fermentation buffers for monoclonal antibody production represent the most penetrable white space. Direct sourcing partnerships with Hyderabad and Ahmedabad formulation manufacturers bypass entrenched distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized pharmaceutical-grade cleanroom packaging infrastructure. Five-to-ten year viability hinges on pharmacopeial harmonization completion between USP, EP, and IP standards. Watch for ESG audit failures at Wyoming trona mines as the inflection signal for supply requalification waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trona Mining | Wyoming feedstock control insulates Solvay process margins from synthetic energy volatility. |
| Cleanroom Packaging Infrastructure Investment | ISO 8 certification enables Swissmedic-inspected drum filling for dialysis concentrate suppliers. |
| Membrane Electrolysis Technology Adoption | Real-time heavy metal monitoring compresses working capital for biopharma contract manufacturers. |
| Cellulose-Based Anti-Caking Agent Qualification | REACH 2026 microplastic restrictions force reformulation ahead of European pharmaceutical deadlines. |
| Direct Sourcing Partnership Development | Tier-one drug manufacturers in Basel audit trona mines for ESG compliance before supplier qualification. |
Methodological Framework
A standing panel of pharmaceutical procurement managers, dialysis concentrate formulators, trona mining operations directors, and CDSCO regulatory affairs specialists provided ongoing calibration against secondary validation. Primary interviews combined with customs trade data, ECHA REACH registration databases, USP monograph revision notices, and SEC chemical sector filings enabled bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation modeling incorporated grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derived from historical consumption patterns and projected dialysis solution expansion, with biopharma fermentation buffer adoption and India's PLI scheme penetration as key forecast inputs.
Underlying assumptions cover REACH compliance timelines, Wyoming rail logistics stability, and natural gas price normalization, with deviation risk concentrated in pharmacopeial harmonization delays and ESG audit failures at feedstock sources. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Trona Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
Global Persulfates Market
Bulk Chemicals
Barite Market
Bulk Chemicals
Triazine Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
Sorbic Acid Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
United States Lime Market