
 Magnesium Sulfate Market | 2026-2036
Magnesium Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Sulfate Market Intelligence
Technical-grade specification consulting is broadening what producers monetize beyond bulk commodity sales. ICL sustains vertical integration from Dead Sea brine extraction through pharmaceutical-grade refining. K+S Aktiengesellschaft anchors European supply with potash-coproduction economics at its German operations. Sinomagchem dominates magnesite-based manufacturing through captive ore reserves in Liaoning province.
Magnesium sulfate is a magnesium salt of sulfuric acid, commercially produced through thermal decomposition of magnesite or neutralization of magnesium oxide with sulfuric acid, yielding heptahydrate crystals containing seven water molecules per formula unit. The compound functions primarily as a fertilizer amendment correcting magnesium deficiency in oil palm and citrus orchards, and as an osmotic laxative and eclampsia treatment in pharmaceutical formulations. Heptahydrate material captures the largest volume share across product types due to its lower production energy intensity and direct agricultural applicability. Pharmaceutical-grade anhydrous material commands the strongest margin pool among product types, driven by USP and EP certification requirements. Tablet and solution forms within the pharmaceutical application segment are expanding faster than powder and granule formats, reflecting finished-dosage manufacturer preferences for supply-chain simplicity.
EPA registration requirements under FIFRA govern agricultural-grade magnesium sulfate distribution in the United States, while REACH registration and classification obligations constrain European import volumes and purity documentation. China's GB standards and MIIT industrial guidelines set baseline specifications for domestic production and export eligibility, with NMPA oversight applying to pharmaceutical-grade output. India's CDSCO and FSSAI maintain parallel tracks for drug and food-additive approvals, creating multi-jurisdictional compliance burdens for integrated suppliers. Stakeholders must monitor divergence between pharmacopeial standards and agricultural tolerance limits, as regulatory arbitrage opportunities narrow with tightening cross-border certification reciprocity.
Market Dynamics
Fertilizer-grade heptahydrate procurement from emerging cultivation zones is compressing traditional supply hierarchies, forcing established producers to recalibrate purity documentation and logistics networks for agricultural buyers.
Growth Catalysts
- Oil palm expansion in Southeast Asia:Magnesium-deficient soils across Indonesia and Malaysia are accelerating bulk heptahydrate offtake for foliar application programs.
- REACH purity benchmarks:Tighter ECHA registration obligations for pharmaceutical-grade material are filtering out substandard imports and consolidating compliant supplier rosters.
- Eclampsia treatment protocols:WHO Essential Medicines List inclusion for injectable magnesium sulfate is expanding procurement from national health ministries across sub-Saharan Africa.
Market Restraints
- Dead Sea brine concentration risk:ICL's integrated extraction operations face water level volatility that threatens consistent pharmaceutical-grade feedstock availability.
- Sulfuric acid cost spikes:Neutralization-route producers absorb input cost volatility from sulfur processing, squeezing margin on standard-grade material.
- Potash coproduction economics:K+S Aktiengesellschaft's German operations tie magnesium sulfate output to potassium chloride demand cycles, creating volume inflexibility.
Strategic Opportunities
- Tablet formulation growth:Finished-dosage manufacturers in India are bypassing powder procurement in favor of direct-compressible granules, opening contract manufacturing niches.
- Food-grade certification arbitrage:FSSAI additive approvals for fortified beverages are outpacing EU EFSA harmonization, creating temporary premium windows for early certifiers.
- Brine-to-pharma integration:Dead Sea and Liaoning basin operators can capture margin pools currently lost to third-party refiners by installing USP-grade crystallization capacity.
Industry Challenges
- Pharmacopeial testing capacity:USP and EP heavy metal assay requirements exceed analytical capabilities at most agricultural-grade facilities, forcing outsourcing or capital deployment.
- Cross-border documentation friction:Divergent GB standard, REACH, and FIFRA purity thresholds create batch-splitting complexity for exporters serving multiple regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Sulfate Market |
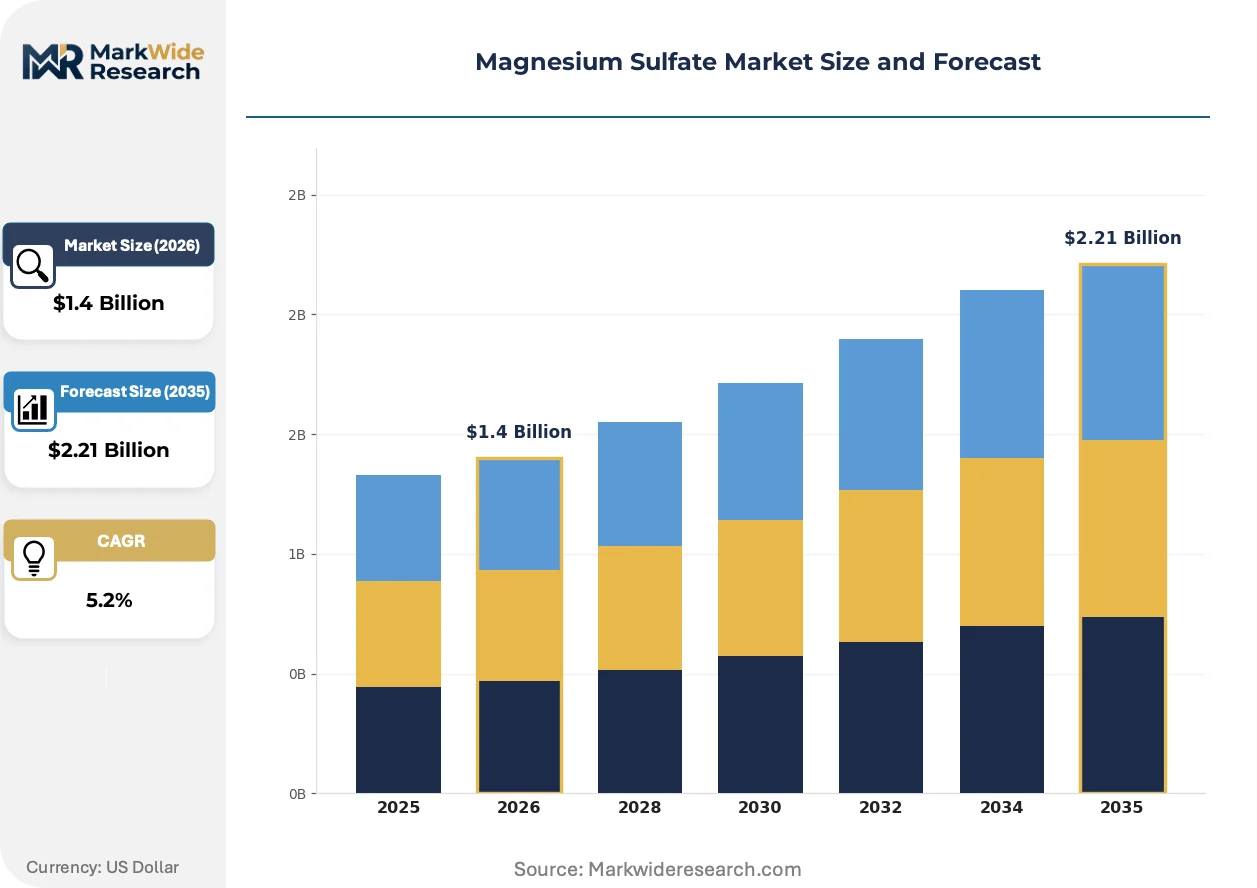
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous Magnesium Sulfate, Heptahydrate, Epsom Salt, Granular Magnesium Sulfate End Use Industry: Agriculture, Pharmaceuticals, Food & Beverage, Personal Care Application: Fertilizer, Laxative, Anticonvulsant, Nutritional Supplement Form: Powder, Granules, Solution, Tablets |
| Companies Covered | Industrias Peñoles, ICL (Israel Chemicals Ltd.), K+S Aktiengesellschaft, Zibo Jinxing Chemical Co., Ltd., Weifang City Huakang Magnesium Sulphate Factory, PQ Corporation, Mani Agro Chem, UMAI Chemical Co., Ltd., Sinomagchem (Yingkou Magnesite Chemical Ind. Group Co., Ltd.), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Sulfate Market Strategic Shifts & Innovations
Process intensification and regulatory digitization are compressing certification timelines while crystallization advances unlock new product morphology options for formulation scientists.
Spray-dried agglomerated heptahydrate is expanding into direct-compression tablet manufacturing by eliminating downstream granulation steps. European and North American contract manufacturers are adopting this morphology for eclampsia and laxative formulations. The technology is expanding into markets previously served by conventional crystalline powder, compressing supply chain stages and reducing handling losses.
REACH registration dossier automation through IUCLID cloud migration is accelerating compliance documentation for mid-tier suppliers. ECHA's phased IT modernization reduces submission preparation labor for substance characterization data. Pharmaceutical-grade importers into the EU are responding by pre-positioning third-party representative structures ahead of 2026 deadline pressures.
Consolidated procurement by national fertilizer distributors is displacing fragmented dealer networks across Brazilian and Indonesian agricultural markets. State-owned input suppliers now tender annual magnesium sulfate volumes through centralized e-procurement platforms. This concentration is most visible in Mato Grosso soy operations and Sumatran palm estates, where volume commitments override brand preferences.
Magnesium Sulfate Market Segmentation
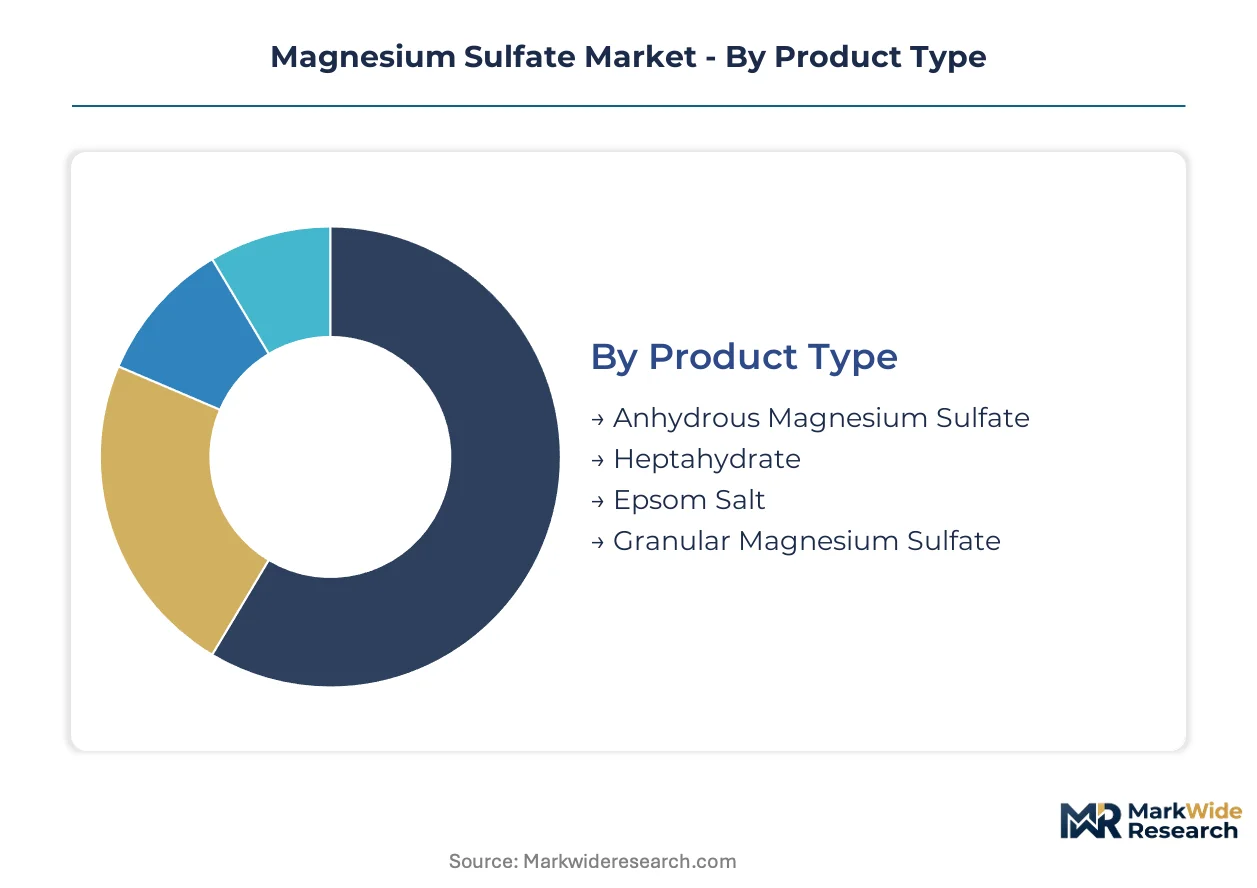
Magnesium sulfate's chemical versatility creates distinct value pools across hydration states and purity grades. Buyers prioritize thermal stability, solubility profiles, and certification tiers when selecting between product types for agricultural, pharmaceutical, or industrial deployment.
Product Type:
Cost tier separates commodity agricultural buyers from premium pharmaceutical purchasers, with energy intensity and crystallization precision driving price stratification.
- Heptahydrate:Crystals contain seven water molecules per formula unit, produced through magnesite thermal decomposition or magnesium oxide neutralization with sulfuric acid. Agricultural procurement across Indonesian oil palm estates and Brazilian soy operations favors this grade for foliar feeding programs, with fertilizer distributors tendering annual volumes through centralized e-procurement platforms.
- Anhydrous Magnesium Sulfate:Water-free composition demands higher calcination energy but delivers superior thermal stability for pharmaceutical tablet manufacturing and moisture-sensitive formulations. USP and EP certification requirements concentrate compliant supply among Dead Sea brine operators and Chinese magnesite refiners with dedicated crystallization capacity.
- Epsom Salt:Coarse crystalline heptahydrate variant marketed for personal care and home gardening applications, with retail packaging driving margin through brand positioning rather than technical specification.
- Granular Magnesium Sulfate:Engineered particle size distribution for mechanized fertilizer spreading equipment, reducing dust generation and improving field application uniformity across large-scale cultivation zones.
Volume sits with Heptahydrate; growth tilts toward Anhydrous Magnesium Sulfate.
End Use Industry:
Application maturity determines margin capture, with established agricultural channels competing against regulated pharmaceutical pathways for producer attention.
- Agriculture:Dominant consumption channel addressing magnesium deficiency in oil palm, citrus, and soybean cultivation. Fertilizer-grade procurement from emerging cultivation zones in Indonesia and Malaysia is compressing traditional supply hierarchies and forcing purity documentation recalibration.
- Pharmaceuticals:WHO Essential Medicines List inclusion for injectable magnesium sulfate in eclampsia treatment is expanding procurement from national health ministries across sub-Saharan Africa. Tablet and solution forms are expanding faster than powder formats, reflecting finished-dosage manufacturer preferences for supply-chain simplicity.
- Food & Beverage:Nutritional fortification applications in fortified beverages are gaining FSSAI additive approvals ahead of EU EFSA harmonization, creating temporary premium windows for early certifiers in the Indian market.
- Personal Care:Bath salt and cosmetic formulations leverage epsom salt positioning, with retail channel distribution masking commodity underlying chemistry through consumer wellness branding.
Revenue concentration favors Agriculture; margin expansion tilts toward Pharmaceuticals.
Application:
Functional specificity separates bulk commodity offtake from certified therapeutic deployment, with regulatory burden intensity defining supplier qualification thresholds.
- Fertilizer:Soil amendment and foliar feeding programs across magnesium-deficient tropical soils. State-owned input suppliers in Brazil and Indonesia now tender annual volumes through centralized platforms, displacing fragmented dealer networks.
- Laxative:Osmotic bowel preparation for medical and over-the-counter use. Spray-dried agglomerated heptahydrate is expanding into direct-compression tablet manufacturing, eliminating downstream granulation steps for contract manufacturers.
- Anticonvulsant:Injectable magnesium sulfate for eclampsia seizure prevention and control. CDSCO and WHO prequalification requirements govern procurement for national health programs in India and sub-Saharan Africa.
- Nutritional Supplement:Magnesium bioavailability enhancement in fortified foods and dietary supplements. FSSAI and FDA GRAS status determinations create multi-jurisdictional compliance burdens for integrated suppliers.
Shipment volume clusters in Fertilizer; therapeutic premium capture concentrates in Anticonvulsant.
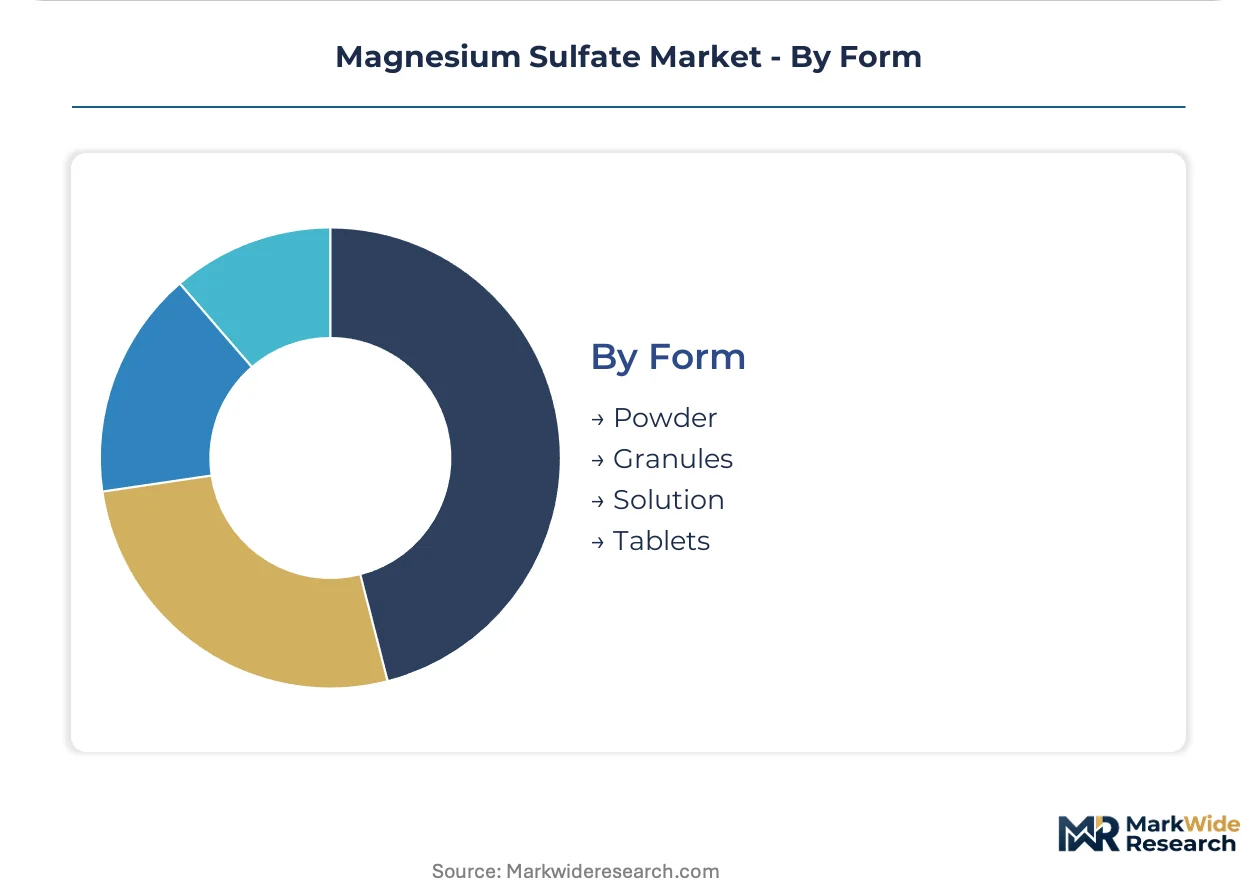
Form:
Customer handling preferences and downstream processing economics determine morphology selection, with finished-dosage manufacturers driving format evolution.
- Tablets:Direct-compressible granules and spray-dried agglomerates bypass powder procurement for Indian finished-dosage manufacturers, opening contract manufacturing niches with simplified supply chains.
- Solution:Ready-to-use injectable and oral liquid formulations for hospital and clinical settings. WHO Essential Medicines List positioning drives procurement standardization for eclampsia treatment protocols.
- Powder:Conventional crystalline material for agricultural blending and pharmaceutical compounding. Handling losses and dust generation limit expansion in automated manufacturing environments.
- Granules:Intermediate particle size for fertilizer bulk blending and selective pharmaceutical applications. Mechanical spreading performance and flowability specifications govern agricultural acceptance.
Traditional volume rests with Powder; formulation preference is shifting fastest toward Tablets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of global magnesium sulfate output from magnesite reserves in Liaoning province, while the United States and Europe remain net importers dependent on Dead Sea brine and domestic neutralization capacity. This production-consumption divide shapes trade flows and regulatory compliance burdens across major demand centers.
United States
Oil palm and citrus cultivation in Florida and California drives agricultural-grade procurement, with EPA FIFRA registration governing fertilizer distribution. FDA oversight applies to pharmaceutical-grade imports for eclampsia treatment protocols. Gulf Coast chemical processors maintain neutralization capacity tied to sulfuric acid supply chains from regional refineries.
China
Zibo and Yingkou industrial clusters anchor global supply through captive magnesite reserves and thermal decomposition routes. NMPA pharmaceutical-grade certification and MIIT industrial guidelines set export eligibility benchmarks. Liaoning basin operators are installing dedicated USP-grade crystallization capacity to capture margin pools from third-party refiners.
Germany
K+S Aktiengesellschaft's potash coproduction economics at domestic operations supply European agricultural demand. ECHA REACH registration obligations filter substandard imports and consolidate compliant supplier rosters. The country's national pharmaceutical regulator maintains EP certification alignment for pharmaceutical-grade material.
India
FSSAI additive approvals for fortified beverages are outpacing EU EFSA harmonization, creating temporary premium windows for early certifiers. CDSCO and FSSAI maintain parallel tracks for drug and food-additive approvals. Finished-dosage manufacturers in Maharashtra and Gujarat are bypassing powder procurement in favor of direct-compressible granules.
Brazil
Magnesium-deficient soils across Mato Grosso soy operations accelerate bulk heptahydrate offtake for foliar application programs. State-owned input suppliers tender annual volumes through centralized e-procurement platforms, displacing fragmented dealer networks. ANVISA pharmaceutical regulations govern import documentation for therapeutic-grade material.
Magnesium Sulfate Market Key Industry Players
Capital-heavy producers compete with asset-light distributors across the magnesium sulfate value chain. The market structures around three tiers: integrated brine-to-pharma operators with captive raw material access, regional neutralization-route producers exposed to sulfuric acid cost volatility, and formulation-focused specialists serving finished-dosage manufacturers. Consolidation pressures concentrate among mid-tier agricultural-grade suppliers facing purity documentation upgrades. Dominant competitive moves include backward integration into crystallization capacity and geographic expansion through third-party representative structures ahead of 2026 REACH deadlines.
Within the integrated brine-extraction archetype, ICL and K+S Aktiengesellschaft exemplify vertical control from raw material through pharmaceutical-grade refining. Among magnesite-based manufacturers, Sinomagchem occupies a position representing captive ore reserve economics in Liaoning province. These three anchors illustrate the strategic divide between Dead Sea brine dependence and Chinese magnesite thermal processing routes.
| Leading Market Players |
|---|
| Industrias Peñoles |
| ICL (Israel Chemicals Ltd.) |
| K+S Aktiengesellschaft |
| Zibo Jinxing Chemical Co., Ltd. |
| Weifang City Huakang Magnesium Sulphate Factory |
| PQ Corporation |
| Mani Agro Chem |
| UMAI Chemical Co., Ltd. |
| Sinomagchem (Yingkou Magnesite Chemical Ind. Group Co., Ltd.) |
| Others |
Cost & Logistics Intelligence
Spray-dried agglomerated heptahydrate adoption is compressing downstream processing costs while concentrating margin capture among crystallization-capable producers. This morphology shift simultaneously reduces granulation expenses for Indian tablet manufacturers and reinforces pricing power for Liaoning basin operators with dedicated USP-grade capacity.
Pricing Analysis
Margin tightening in pharmaceutical-grade material reflects REACH registration cost absorption and heavy metal assay outsourcing burdens. Three-tier pricing structure across USP-certified, technical-grade, and agricultural-grade levels separates premium anhydrous material for eclampsia formulations from commodity heptahydrate for oil palm foliar programs. Cost-down pressure on standard-grade heptahydrate accelerates because Indonesian state-owned fertilizer distributors tender through centralized e-procurement platforms. Agricultural buyers exhibit highest price sensitivity, while WHO Essential Medicines List procurement for sub-Saharan Africa health ministries shows lowest elasticity.
Supply Chain Analysis
Pharmacopeial certification gating concentrates compliant pharmaceutical-grade supply among Dead Sea brine operators, Liaoning magnesite refiners, and German potash coproduction facilities. Raw material dependencies span captive magnesite reserves, sulfuric acid from regional refinery operations, and Dead Sea brine concentration infrastructure. Single-source vulnerability threatens ICL's integrated extraction given water level volatility. Distribution runs through national fertilizer distributors in Brazil and Indonesia, third-party refiners for pharmaceutical-grade upgrading, and direct contracts with Indian finished-dosage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards producers securing upstream crystallization capacity and downstream formulation relationships. The race centers on capturing margin pools currently lost to third-party USP-grade refiners.
For Market Incumbents: Anticipate sulfuric acid cost volatility by anchoring long-term offtake agreements with Gulf Coast chemical processors. Consolidate position through backward integration into spray-dried agglomeration capacity, neutralizing the threat from Indian contract manufacturers bypassing powder procurement. Prioritize REACH registration dossier automation ahead of ECHA deadline pressures. For New Entrants and Emerging Players: National health ministries in sub-Saharan Africa present the most penetrable procurement channel given WHO Essential Medicines List standardization. Food-grade certification arbitrage through FSSAI additive approvals offers temporary premium windows ahead of EU EFSA harmonization. Partner with Maharashtra and Gujarat finished-dosage manufacturers seeking direct-compressible granule supply. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier magnesite-based manufacturers installing USP-grade crystallization capacity given pharmaceutical margin pool expansion. Long-term viability favors operators with captive ore reserves and brine-to-pharma integration pathways. Watch for Dead Sea water level stabilization agreements as inflection signal for ICL feedstock reliability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into USP-Grade Crystallization | Liaoning basin operators capture margin pools from third-party pharmaceutical refiners. |
| Long-Term Supply Agreement with State Fertilizer Distributors | Brazilian and Indonesian e-procurement platforms displace fragmented dealer networks. |
| REACH Registration Dossier Automation | ECHA IUCLID cloud migration accelerates compliance timelines for mid-tier suppliers. |
| Joint Venture with Indian Finished-Dosage Manufacturers | Maharashtra and Gujarat tablet producers seek direct-compressible granule sourcing. |
| Capacity Expansion in Spray-Dried Agglomeration | Eliminates downstream granulation steps for eclampsia and laxative formulations. |
Research Approach
Document review covered customs and trade databases, ECHA registration filings, and SEC 10-K disclosures, complemented by interviews with plant managers at magnesite refiners, procurement leads at Indonesian fertilizer distributors, pharmaceutical regulatory affairs specialists, and hospital procurement managers in sub-Saharan Africa. Secondary validation drew from WHO Essential Medicines List documentation, FSSAI additive approval records, and MIIT industrial guidelines. Bottom-up volume modeling triangulated against top-down value estimates.
Output metrics span tonnage and value projections across the analysis window, segmented by hydration state, certification tier, end-use industry, and regional production hub. CAGRs derive from regression against historical trade flows and capacity expansion announcements. Key inputs include sulfuric acid price indices, Dead Sea water level monitoring data, and pharmaceutical import statistics from CDSCO and ANVISA.
Caveats apply where sulfuric acid cost spikes, Dead Sea brine concentration disruption, or REACH-GB standard divergence could materially shift the outlook. Forecasts reflect assumptions around state fertilizer distributor procurement consolidation and WHO prequalification pathway standardization. A model refresh is warranted upon material change in ECHA registration enforcement timelines or Indonesian palm estate foliar program adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
Valeric Acid Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Global Basic Chemicals Market
Bulk Chemicals
Furfural Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Sodium Perborate Market
Bulk Chemicals
North America Lactic Acid Market