
 Epoxy Silanes Market | 2026-2036
Epoxy Silanes Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Silanes Market Analysis
Multi-source procurement among adhesive formulators is realigning supply relationships across the epoxy silanes value chain. Momentive Performance Materials leverages its integrated siloxane backbone production to sustain cost advantages in North American supply. Wacker Chemie AG anchors European demand through specialized high-purity grades for electronics applications. Dow Inc. competes on manufacturing scale across multiple regional production hubs.
Epoxy silanes are organofunctional silicon compounds bearing both hydrolyzable alkoxy groups and reactive epoxy terminal functionality, typically manufactured through hydrosilylation of allyl glycidyl ether with trichlorosilane followed by alcoholysis. These bifunctional molecules serve primarily as adhesion promoters between inorganic substrates and organic polymer matrices, enabling covalent bridging at interphase boundaries. The adhesives application commands the largest volume share due to structural bonding requirements in automotive lightweighting and electronics miniaturization, while the aerospace end-user segment represents the fastest-growing margin pool driven by thermoset composite qualification cycles. Silyl-terminated polymers within the product-type spectrum occupy a maturing niche with slower growth but stable replacement demand in construction sealants.
EPA oversight under the Toxic Substances Control Act and REACH registration requirements through ECHA impose purity thresholds and substance-volume reporting obligations that directly shape product formulation standards and market access conditions for epoxy silane suppliers. China's MEE enforces dual carbon goals that constrain chlorosilane precursor emissions, redirecting investment toward cleaner hydrosilylation catalyst systems. Stakeholders must monitor evolving fluoropolymer substitution trends and bio-based epoxy precursor developments that could disrupt conventional silane coupling agent demand structures.
Market Dynamics
REACH registration requirements through ECHA and EPA oversight under the Toxic Substances Control Act are forcing purity upgrades across the epoxy silanes supply base, compressing margins for non-compliant producers while rewarding integrated manufacturers with captive chlorosilane supply.
Growth Catalysts
- Advanced Semiconductor Packaging:Die-attach adhesives for heterogeneous integration require ultra-low ionic content epoxy silanes. Electronics manufacturers in Taiwan and South Korea are qualifying new coupling agent grades for fan-out wafer-level packaging.
- REACH SVHC Thresholds:Substances of very high concern screening drives formulators toward high-purity epoxy silane alternatives. European adhesive producers are reformulating to eliminate residual chlorosilane precursors.
- Thermoset Composite Qualification:Aerospace OEMs specify silyl-modified epoxy systems for primary structural bonding. Hydrosilylation catalyst improvements are reducing cure cycle times for out-of-autoclave processing.
Market Restraints
- Chlorosilane Precursor Volatility:Silicon metal and methyl chloride pricing swings transmit directly to epoxy silane cost structures. Chinese MEE emission constraints on chlorosilane production are tightening precursor availability.
- Platinum Catalyst Concentration:Hydrosilylation chemistry depends on platinum group metal supply concentrated in South Africa and Russia. Geopolitical friction creates input cost unpredictability for specialty silane manufacturers.
- Bio-Based Epoxy Substitution:Lignin-derived and vegetable oil-based epoxy resins are displacing conventional bisphenol-A systems in non-structural applications. Reduced silane coupling agent loading in these formulations threatens volume demand.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme incentives for semiconductor and display fabrication are creating new adhesive demand. Domestic epoxy silane supply remains underdeveloped relative to projected fab capacity additions.
- Dual Carbon Alignment:China's MEE enforcement of carbon intensity targets favors cleaner hydrosilylation processes. Suppliers with low-emission production routes gain preferential access to state-backed electronics projects.
- Fluoropolymer Displacement:Perfluorinated adhesion promoters face regulatory pressure under EU F-Gas Regulation and state-level restrictions in the US. Epoxy silanes with comparable thermal stability are capturing specification share in wire and cable applications.
Industry Challenges
- Organosilicon Synthesis Expertise:Hydrosilylation catalyst selection and alkoxy group control require specialized chemical engineering talent. The talent pool for silane process development concentrates in Germany, Japan, and select US industrial clusters.
- Aerospace Qualification Cycles:OEM specification changes for thermoset composites require 18-36 month validation protocols. Epoxy silane suppliers must fund extended testing programs before volume adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Silanes Market |
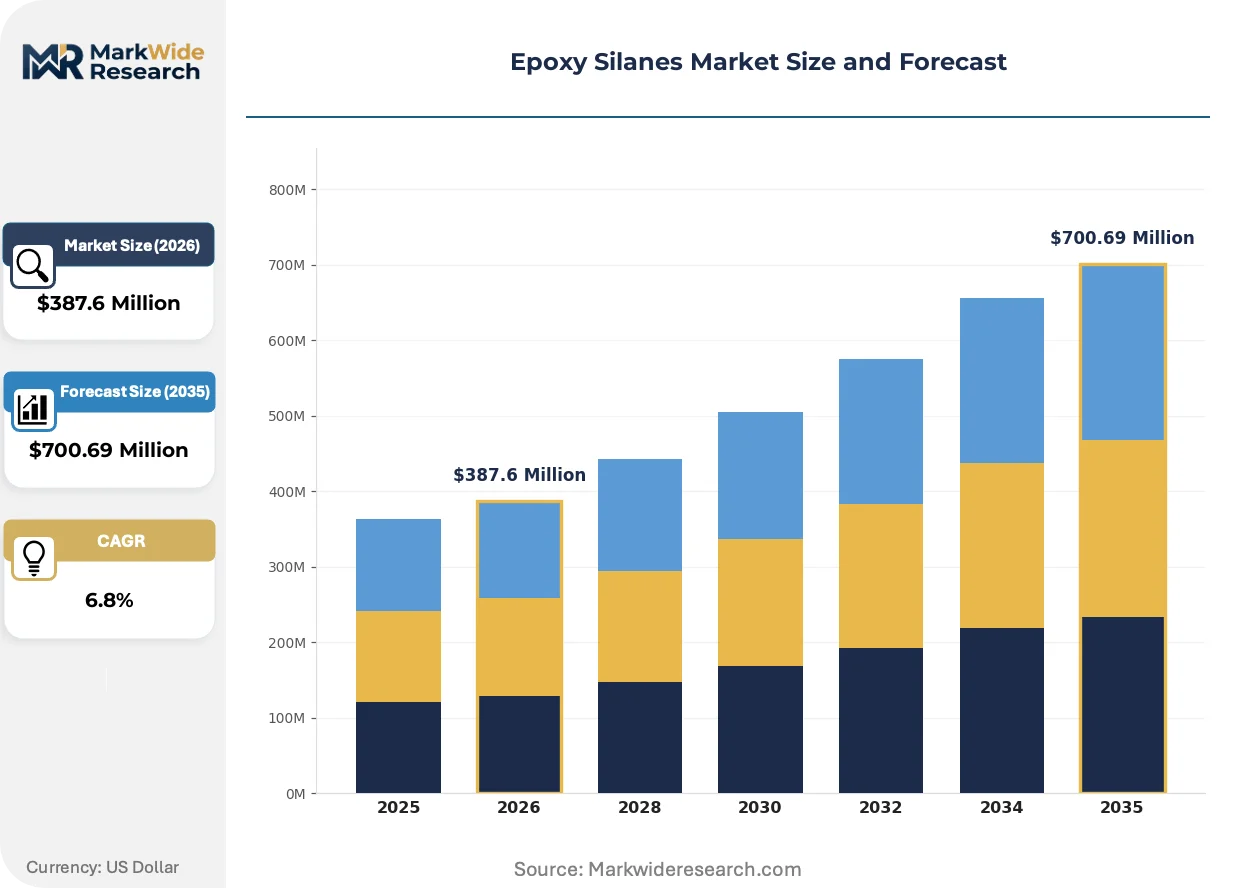
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Silanes, Epoxy Silanes, Vinyl Silanes, Silyl-terminated Polymers Application: Adhesives, Coatings, Sealants, Composites End User: Construction, Automotive, Electronics, Aerospace Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Momentive Performance Materials Inc., OCI Company Ltd, Wacker Chemie AG, Nanjing Union Silicon Chemical Co. Ltd., KCC Corporation, Evonik Industries AG, Shin-Etsu Chemical Co. Ltd, Nanjing Shuguang Silane Chemical Co. Ltd., Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Silanes Market Emerging Trajectories
Silane chemistry is converging with advanced polymer architectures as electronics miniaturization and composite lightweighting impose stricter interphase engineering requirements. Formulators are demanding coupling agents with narrower molecular weight distributions and lower volatile organic compound footprints.
Waterborne epoxy silane dispersions are absorbing specification share from solvent-based systems in automotive OEM coatings and electronics conformal coatings. Tier-1 adhesive suppliers in Germany and Japan are accelerating qualification of aqueous silyl-terminated polymer systems. The shift is absorbing capital investment formerly directed toward solvent recovery infrastructure, redirecting R&D toward dispersion stability and shelf-life extension.
REACH authorization procedures for chlorosilane intermediates are compelling downstream producers to document full substance volume chains. ECHA's SCIP database requirements for articles containing SVHCs above threshold concentrations are forcing electronics assemblers to demand detailed epoxy silane composition disclosures. High-purity grades with comprehensive analytical certification are commanding preference share in European medical device and automotive supply chains.
Consolidated procurement among North American automotive OEMs is compressing supplier bases for structural adhesives. Tier-2 formulators are losing direct specification influence as Ford, General Motors, and Stellantis centralize materials engineering decisions. The concentration is visible in Michigan and Ohio engineering centers where adhesive selection committees now mandate epoxy silane coupling agents from pre-qualified supplier lists with integrated analytical capabilities.
Epoxy Silanes Market Segmentation
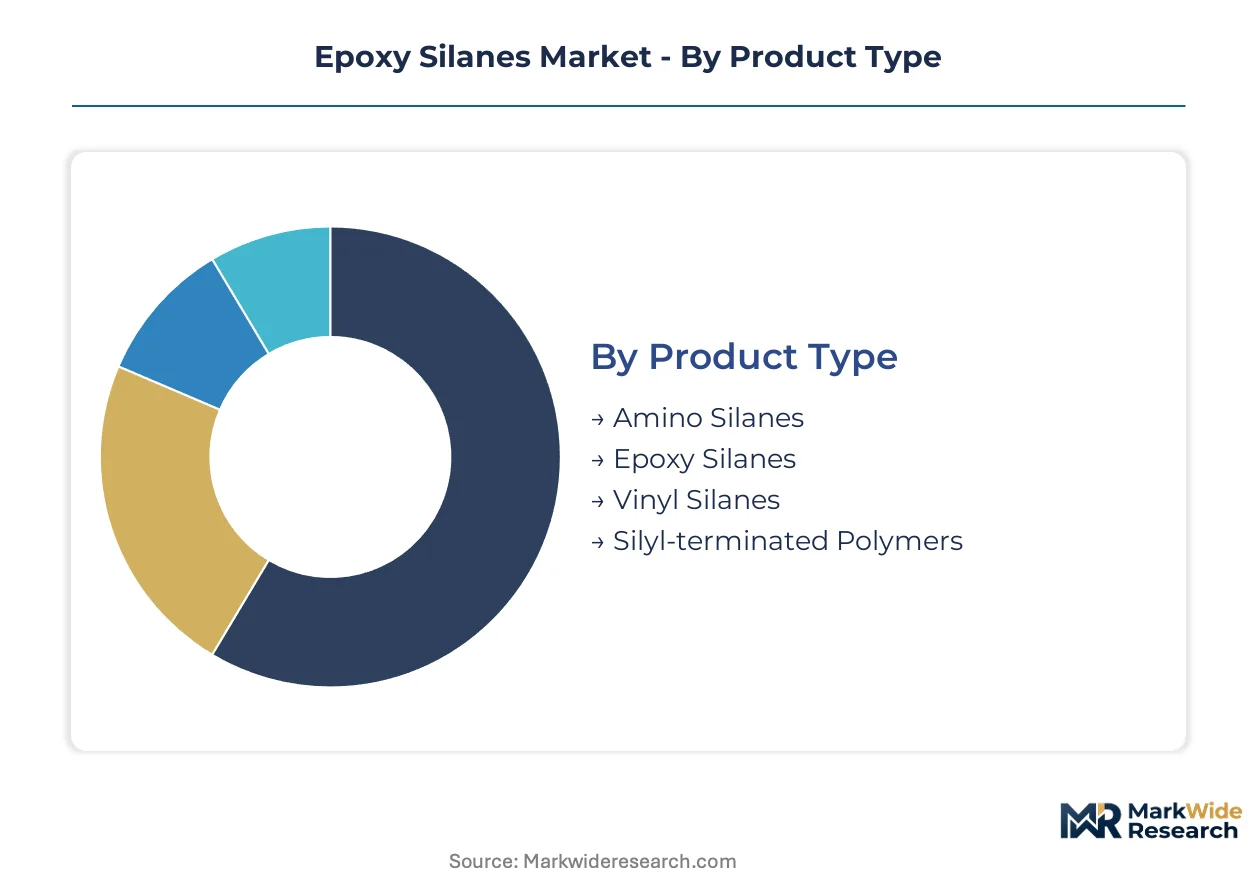
Epoxy silane manufacturers configure production assets around distinct purity grades and functional specifications that align with end-use qualification requirements. Segmentation reveals where capital deployment concentrates and which customer tiers command premium pricing.
Product Type:
Capital intensity escalates with functional complexity and purity thresholds, particularly for electronics-grade materials requiring sub-ppm ionic contamination control.
- Epoxy Silanes:Bifunctional molecules bearing hydrolyzable alkoxy groups and terminal epoxy functionality manufactured via platinum-catalyzed hydrosilylation. Electronics packaging applications in Taiwan and South Korea absorb the highest-purity grades as fan-out wafer-level packaging expands. REACH SVHC screening accelerates substitution toward certified low-residual grades.
- Silyl-terminated Polymers:Moisture-curable silane-modified polyurethane backbones serving construction sealant and elastic adhesive formulations. German and Japanese tier-1 suppliers are qualifying aqueous dispersion variants to replace solvent-based systems under tightening VOC regulations.
- Amino Silanes:Primary and secondary amine-functional silanes competing with epoxy variants in glass-reinforced thermoset applications.
- Vinyl Silanes:Crosslinking agents for polyethylene wire and cable compounds, peroxide-initiated grafting chemistry.
Epoxy silanes absorb the bulk of installed capacity; silyl-terminated polymers are expanding most quickly in waterborne construction applications.
Application:
Application selection determines formulation complexity and the regulatory burden carried through the supply chain.
- Adhesives:Structural bonding formulations for automotive lightweighting and electronics die-attach requiring controlled rheology and thermal stability. Michigan and Ohio automotive engineering centers centralize materials qualification, compressing supplier bases to pre-qualified lists with integrated analytical capabilities.
- Composites:Silyl-modified epoxy systems for aerospace primary structures demanding 18-36 month OEM validation cycles. Out-of-autoclave processing improvements are reducing cure cycle times through advanced hydrosilylation catalyst selection.
- Coatings:Conformal and protective layers for electronics and industrial substrates, shifting toward waterborne epoxy silane dispersions.
- Sealants:Elastic joint fillers in construction and transportation, a maturing segment with stable replacement demand.
Adhesives command the largest formulation volume; composites are climbing the fastest on aerospace thermoset qualification momentum.
End User:
End-user concentration shapes regional production placement and the intensity of regulatory compliance investment.
- Electronics:Advanced semiconductor packaging and display manufacturing requiring ultra-low ionic content for heterogeneous integration. China's MEE dual carbon enforcement favors suppliers with cleaner hydrosilylation processes for state-backed fab projects.
- Aerospace:Primary structural bonding specifications with extended qualification protocols and exacting batch consistency requirements.
- Automotive:Structural adhesives for multi-material body-in-white construction, procurement consolidating among North American OEMs.
- Construction:Sealant and coating applications with slower specification turnover but volume scale in infrastructure and residential markets.
Electronics absorbs the bulk of high-purity capacity investment; aerospace is gaining share fastest on margin pool expansion.
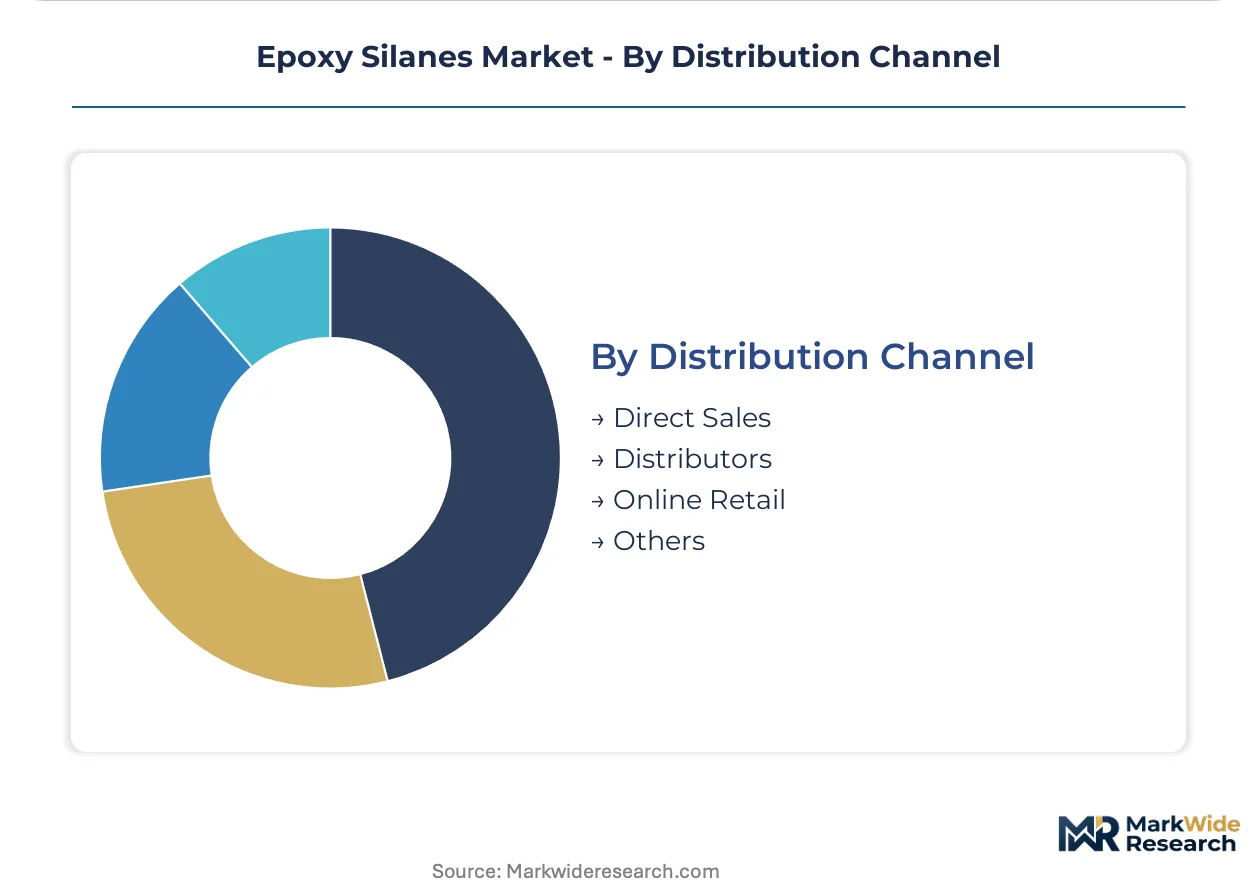
Distribution Channel:
Channel structure reflects customer technical support requirements and the value of formulation expertise embedded in transactions.
- Direct Sales:Long-term supply agreements with tier-1 adhesive formulators and composite manufacturers demanding technical service integration. Momentive Performance Materials and Dow Inc. leverage direct relationships for high-volume automotive and electronics accounts.
- Distributors:Regional chemical distributors serving mid-tier formulators with inventory management and just-in-time delivery.
- Online Retail:Small-volume specialty chemical platforms for research quantities and prototype formulation.
- Others:Agent-based representation in markets with limited supplier presence.
Direct sales captures the bulk of revenue value; distributor channels are expanding most quickly in underpenetrated regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for epoxy silanes clusters in electronics manufacturing corridors and automotive engineering centers across five countries. China, Japan, South Korea, the United States, and Germany absorb the bulk of high-purity grades for semiconductor packaging and composite bonding applications.
China
State-backed semiconductor fabs in Jiangsu and Shanghai are qualifying ultra-low ionic content epoxy silanes for advanced packaging. MEE enforcement of dual carbon goals constrains chlorosilane precursor emissions, redirecting investment toward cleaner hydrosilylation catalyst systems in the Yangtze River Delta.
Japan
Aerospace OEMs in Nagoya and composite manufacturers in Osaka specify silyl-modified epoxy systems for primary structural bonding. METI industrial standards for chemical substances impose purity documentation requirements that favor suppliers with integrated analytical capabilities.
South Korea
Memory and logic chip producers in Gyeonggi Province are expanding fan-out wafer-level packaging capacity requiring die-attach adhesives. MFDS chemical substance regulations align with REACH thresholds, driving formulators toward certified low-residual coupling agent grades.
United States
Automotive OEMs in Michigan and Ohio centralize materials engineering decisions, compressing adhesive supplier bases to pre-qualified lists. EPA oversight under the Toxic Substances Control Act imposes substance-volume reporting obligations that shape formulation standards for structural bonding applications.
Germany
Tier-1 adhesive suppliers in Bavaria and North Rhine-Westphalia are accelerating qualification of aqueous silyl-terminated polymer systems. ECHA REACH authorization procedures for chlorosilane intermediates compel downstream producers to document full substance volume chains.
Epoxy Silanes Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated manufacturers scale hydrosilylation assets to capture electronics-grade demand. The vendor base organizes around three strategic archetypes: siloxane backbone integrators with captive chlorosilane supply, regional specialists focused on high-purity grades, and diversified chemical conglomerates with multi-regional production hubs. Geographic expansion and portfolio diversification represent the two dominant competitive moves, with suppliers establishing technical service proximity to Taiwanese and South Korean electronics clusters while broadening from adhesives into coatings and sealant formulations.
Within the integrated siloxane tier, Momentive Performance Materials and Dow Inc. exemplify manufacturers leveraging backward control over precursor supply. Wacker Chemie AG occupies a position among European specialists anchoring demand through certified high-purity grades. Nanjing Union Silicon Chemical Co. Ltd. and Nanjing Shuguang Silane Chemical Co. Ltd. represent Chinese specialists serving regional electronics manufacturing growth.
| Leading Market Players |
|---|
| Momentive Performance Materials Inc. |
| OCI Company Ltd |
| Wacker Chemie AG |
| Nanjing Union Silicon Chemical Co. Ltd. |
| KCC Corporation |
| Evonik Industries AG |
| Shin-Etsu Chemical Co. Ltd |
| Nanjing Shuguang Silane Chemical Co. Ltd. |
| Dow Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Jiangsu and Shandong provinces anchor chlorosilane precursor supply, translating upstream cost discipline into downstream pricing power for electronics-grade epoxy silane tiers. Their concentrated ownership structures enable rapid capacity adjustments that buffer platinum catalyst volatility while maintaining margin buffers against REACH-driven purity investments.
Pricing Analysis
Volume-grade epoxy silanes for construction sealants trade on thin margins while electronics-grade ultra-low ionic variants capture substantial premiums. Price differentiation hinges on ECHA REACH SVHC certification status and semiconductor fab qualification tier, with automotive OEM consolidated procurement in Michigan and Ohio compressing mid-tier supplier margins. Cost compression in standard-grade formulations is intensifying because Chinese MEE emission constraints on chlorosilane precursors are tightening feedstock availability. Tier-1 adhesive formulators exhibit lowest price sensitivity due to qualification lock-in, while construction sealant distributors remain highly sensitive to per-kilogram differentials.
Supply Chain Analysis
Epoxy silane supply rests on chlorosilane production concentrated in China, Germany, and Japan, with platinum group metal catalyst sourcing anchored in South Africa and Russia. Key inputs span silicon metal, methyl chloride, and allyl glycidyl ether, each transmitting volatility through hydrosilylation cost structures. Geopolitical friction around platinum group metal supply creates persistent input cost unpredictability for specialty manufacturers. Distribution runs through direct long-term agreements with tier-1 adhesive formulators and composite manufacturers, supplemented by regional chemical distributors serving mid-tier construction and industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epoxy silanes sector sits at a technology-transition inflection as waterborne silyl-terminated polymer systems displace solvent-based formulations across automotive OEM and electronics conformal coating specifications.
For Market Incumbents: To counter bio-based epoxy substitution in non-structural applications, Momentive Performance Materials and Dow Inc. should deepen backward integration into chlorosilane precursor production to sustain cost advantages against REACH-driven purity investments. Certification investment in ECHA SCIP database compliance and ultra-low ionic analytical capabilities will defend specification share in European medical device and automotive supply chains. For New Entrants and Emerging Players: The gap between premium electronics-grade and economy construction-grade pricing creates entry space for mid-purity specialists targeting Indian electronics manufacturing under PLI scheme incentives. Domestic epoxy silane supply remains underdeveloped relative to projected semiconductor fab capacity additions in Gujarat and Karnataka. A technical service partnership model with Taiwanese packaging houses offers the most penetrable go-to-market angle for qualification-heavy die-attach adhesive segments. For Investors and Strategic Acquirers: South Korean memory chip producers expanding fan-out wafer-level packaging capacity is the leading indicator that high-purity epoxy silane demand will outpace general industrial growth. Over a five-to-ten-year horizon, integrated siloxane backbone producers with captive chlorosilane supply and established semiconductor fab relationships present the strongest acquisition profile. Watch for Chinese MEE enforcement actions that redirect state-backed electronics project procurement toward cleaner hydrosilylation process suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Precursors | Captive silicon metal and methyl chloride supply buffers platinum catalyst volatility for integrated manufacturers. |
| Waterborne Formulation Qualification | Aqueous silyl-terminated polymer systems capture automotive OEM coating specifications under tightening VOC regulations. |
| Semiconductor Fab Technical Service Proximity | On-site analytical support accelerates die-attach adhesive qualification cycles in Taiwan and South Korea. |
| ECHA SCIP Database Compliance Investment | Full substance volume chain documentation secures European medical device and automotive supply chain access. |
| Cleaner Hydrosilylation Process Development | Low-emission production routes gain preferential access to Chinese state-backed electronics projects under MEE dual carbon enforcement. |
Methodological Framework
Independent corroboration across plant managers at chlorosilane production facilities, procurement leads at tier-1 adhesive formulators, distribution channel partners in European construction chemicals, and technical R&D directors at semiconductor packaging houses underwrites the qualitative findings in this study. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from diversified chemical conglomerates, and ECHA REACH registration databases. Bottom-up capacity and demand modeling triangulates against top-down macroeconomic and end-use industry growth trajectories.
Historical reference periods spanning pre-pandemic baseline, supply disruption years, and normalization phases anchor the forecast window across the analysis window. The analytical framework models segmentation dimensions including purity grade tier, end-use industry, and regional production hub clustering. CAGRs derive from elasticity-adjusted demand projections incorporating semiconductor packaging technology roadmaps, aerospace thermoset composite qualification cycles, and automotive lightweighting content-per-vehicle trends.
Underlying measurement precision varies by segment; electronics-grade ultra-low ionic epoxy silanes carry tighter precision than construction sealant grades due to concentrated end-user visibility. Forecasts reflect assumptions around platinum group metal supply stability, REACH authorization timelines for chlorosilane intermediates, and Chinese MEE emission enforcement intensity. A small set of triggers warrants ongoing watch: South Korean memory chip capital expenditure announcements, ECHA SVHC list expansions, and Indian PLI scheme fab commissioning schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Thiochemicals Market
Chemical Intermediates
Global Textile Finishing Chemicals Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
Global Iron Chelates Market