
 Saudi Arabia Formic Acid Market | 2026-2036
Saudi Arabia Formic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Formic Acid Market Intelligence
Green chemistry process innovation is fragmenting traditional methyl formate-based production pathways across Saudi Arabia's chemical sector. BASF SE leverages its European technical heritage to sustain premium-grade supply relationships with Kingdom-based distributors. Al-Jubail Petrochemical Company anchors methanol-to-formic acid integration within the Jubail industrial cluster. Saudi Basic Industries Corporation competes through backward integration into feedstock supply, controlling cost structures at scale.
Formic acid is a colorless, pungent liquid with the chemical formula HCOOH and a minimum purity threshold of 85 percent for industrial applications; manufacturers synthesize it primarily via methyl formate hydrolysis or, increasingly, through carbon dioxide hydrogenation pathways for bio-based variants. The compound functions as a preservative, pH regulator, and reducing agent across leather processing, silage treatment, and pharmaceutical intermediate synthesis. Industrial Grade output dominates volume flows given its role in textile dyeing and leather tanning operations, while Bio-based supply represents the fastest-expanding category as carbon capture utilization gains traction among Saudi producers seeking to differentiate on sustainability credentials. Laboratory Grade commands concentrated margin pools from pharmaceutical quality-assurance protocols and analytical reagent demand.
The Saudi Food and Drug Authority (SFDA) enforces chemical substance registration and labeling standards that govern formic acid distribution into food-contact and pharmaceutical channels, while the Royal Commission for Jubail and Yanbu mandates environmental discharge thresholds for manufacturing facilities within industrial cities. These frameworks elevate compliance costs for importers while creating structural advantages for domestic producers with certified in-house testing capabilities. Stakeholders must monitor feedstock cost volatility and regulatory alignment between SFDA requirements and EU REACH-equivalent standards as Gulf chemical trade integration deepens.
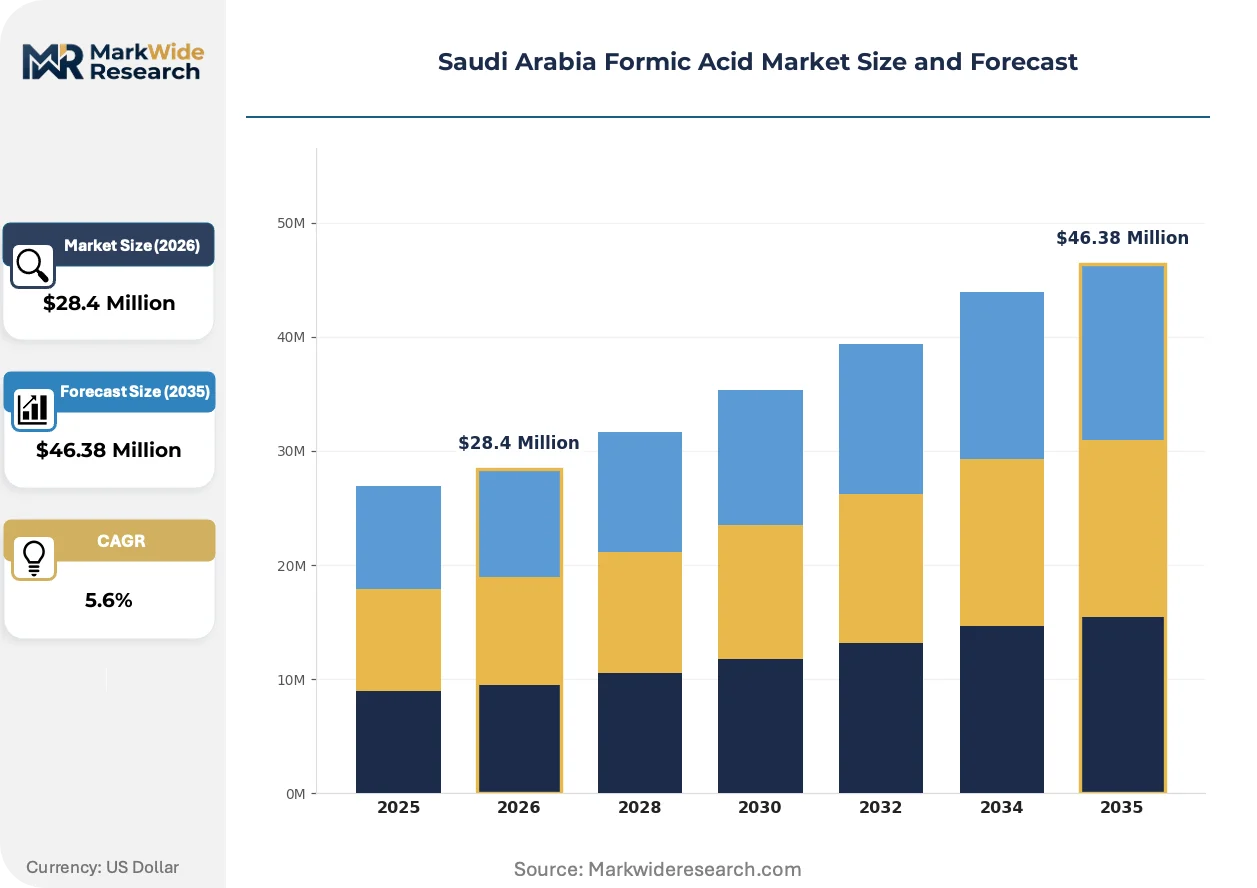
Market Dynamics
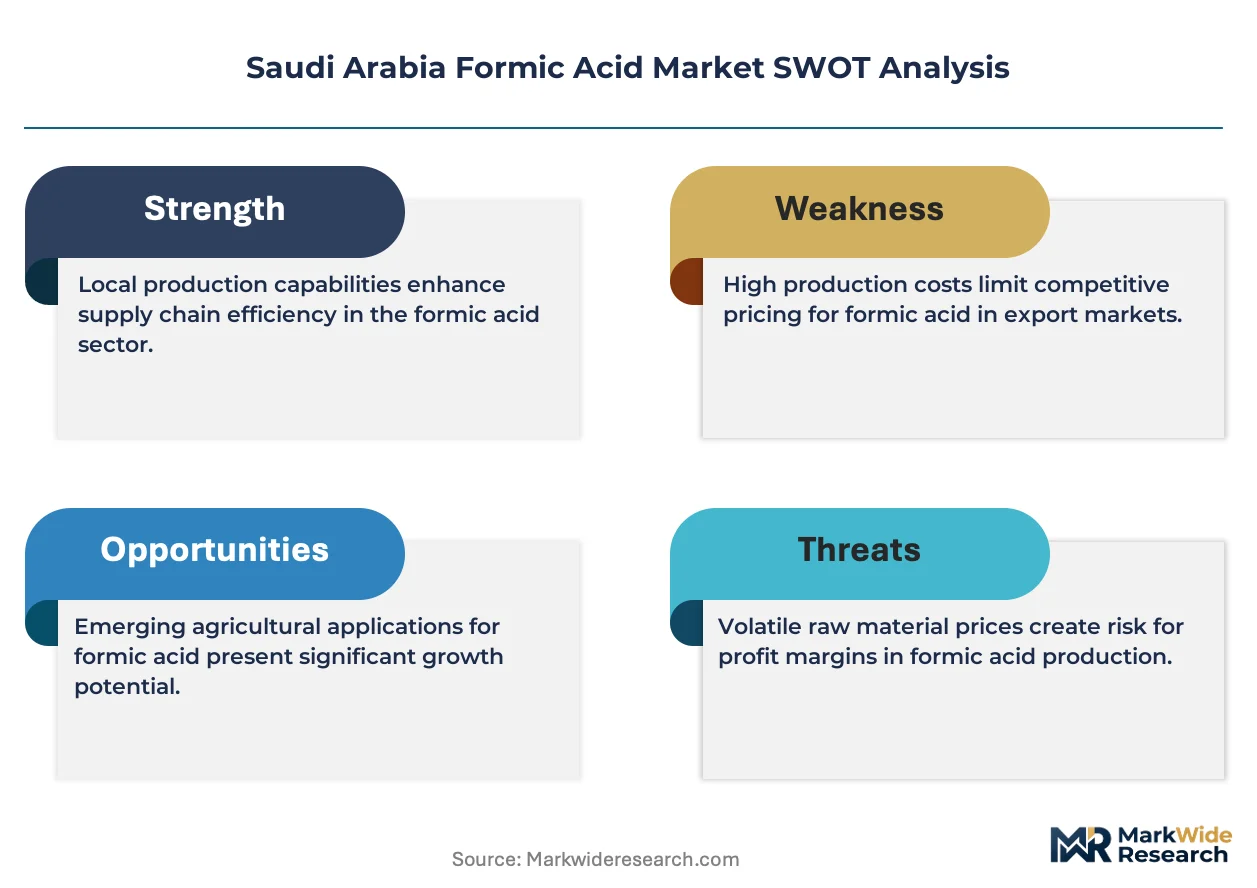
Green chemistry process innovation fragments methyl formate-based production pathways across Saudi Arabia's chemical sector, reshaping cost structures and competitive positioning among domestic producers.
Growth Catalysts
- Leather Tanning Demand:Rising consumption in hide preservation and chrome-free tanning processes drives volume expansion across Eastern Province industrial zones.
- SFDA Registration Pathways:Chemical substance registration requirements for food-contact and pharmaceutical channels create certified supply advantages for compliant domestic manufacturers.
- Carbon Capture Utilization:Bio-based production via carbon dioxide hydrogenation gains traction among Saudi producers seeking sustainability differentiation in export markets.
Market Restraints
- Methanol Feedstock Volatility:Fluctuating natural gas and methanol input costs compress margins for integrated and non-integrated producers alike.
- Import Concentration Risk:Premium-grade supply dependence on European technical heritage limits domestic substitution flexibility for specialized applications.
- Substitution Pressure:Citric acid and other organic acids displace formic acid in select food preservation and cleaning applications.
Strategic Opportunities
- Jubail-Yanbu Corridor Expansion:Royal Commission infrastructure investments enable capacity scaling within the Kingdom's primary petrochemical cluster.
- Pharmaceutical Intermediate Synthesis:Laboratory-grade demand from quality-assurance protocols opens concentrated margin pools for certified producers.
- Gulf Chemical Trade Integration:Alignment between SFDA requirements and emerging regional standards creates export pathway advantages into UAE and neighboring markets.
Industry Challenges
- Specialized Process Engineering Talent:Scarcity of carbon capture hydrogenation expertise constrains bio-based production scaling timelines.
- SFDA-EU REACH Alignment Complexity:Divergent substance registration timelines create dual compliance burdens for exporters seeking European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Formic Acid Market |
| Market Size in 2026 | $28.4 Million |
| Market Size in 2035 | $46.38 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Bio-based, Laboratory Grade, Technical Grade Application: Textile Industry, Leather Tanning, Agriculture, Pharmaceuticals Packaging Type: Drum, IBC Container, Bottle, Bulk Tank End User: Chemical Manufacturers, Agriculture Providers, Food Industry, Textile Distributors |
| Companies Covered | Advanced Petrochemical Company, Al-Jubail Petrochemical Company, BASF SE, Gujarat Narmada Valley Fertilizers & Chemicals Limited, Shandong Acid Technology Co., Ltd., Petroliam Nasional Berhad (PETRONAS), National Industrialization Company, Huanghua Pengfa Chemical Co., Ltd., Saudi Basic Industries Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Formic Acid Market Strategic Shifts & Innovations
Process digitization and regulatory harmonization reshape production economics across Saudi Arabia's formic acid value chain. Three developments command strategic attention.
Carbon dioxide hydrogenation technology is digitizing process control systems across pilot and commercial-scale facilities. Al-Jubail Petrochemical Company and SABIC affiliates deploy sensor networks and predictive analytics to optimize catalyst performance and yield consistency. This convergence of green chemistry and industrial IoT is digitizing quality assurance workflows, compressing batch-to-batch variation and accelerating bio-based certification timelines.
SFDA chemical substance registration requirements are tightening labeling and traceability mandates for food-contact and pharmaceutical-grade distribution. The framework elevates in-house testing capabilities as a competitive differentiator while creating structural friction for import-dependent distributors. Domestic producers with certified laboratories capture preferential positioning as registration renewal cycles compress.
Leather processors are consolidating procurement relationships around integrated suppliers offering bundled formic acid and tanning auxiliary packages. This specification-driven bundling displaces spot-market purchasing across Yanbu and Jeddah industrial zones. Tanneries in the Western Region exhibit the fastest adoption of long-term supply agreements with technical service attachments.
Saudi Arabia Formic Acid Market Segmentation
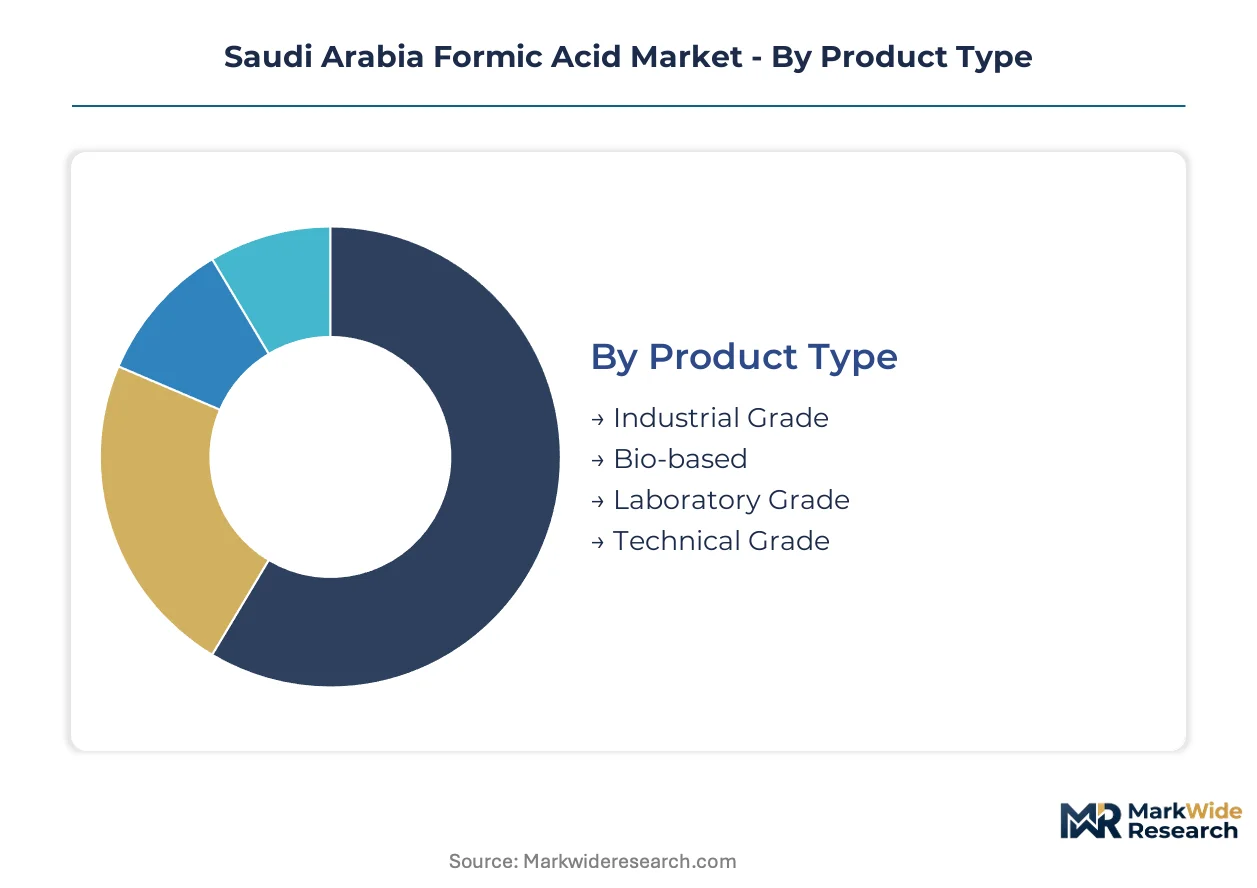
Formic acid procurement patterns across Saudi Arabia diverge sharply by purity threshold and end-use certification requirements. Understanding these segment boundaries enables suppliers to align capacity investments with margin concentration points.
Product Type:
Mature commodity grades dominate tonnage flows while emerging sustainability-certified variants capture expanding price premiums.
- Industrial Grade:Minimum 85 percent purity specification serves leather tanning and textile dyeing operations across Jubail and Yanbu industrial corridors. Tanneries in the Eastern Province account for the dominant share of offtake volume as chrome-free processing standards tighten.
- Bio-based:Carbon dioxide hydrogenation pathways yield formic acid with renewable feedstock credentials. SABIC affiliates and Al-Jubail Petrochemical Company pilot commercial-scale production targeting export markets with EU-equivalent sustainability mandates.
- Laboratory Grade:Ultra-high purity for analytical reagent and pharmaceutical intermediate synthesis. SFDA registration requirements elevate domestic testing capabilities as a procurement differentiator.
- Technical Grade:Intermediate purity tier for general chemical manufacturing and industrial cleaning applications. Price-sensitive buyers in non-regulated channels drive spot-market liquidity.
Industrial Grade retains volume leadership; Bio-based holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-intensive pharmaceutical demand from commodity leather and textile offtake.
- Textile Industry:pH regulation and dye fixation in synthetic and natural fiber processing. Mills in Jeddah industrial zones concentrate procurement around drum-packaged supply with just-in-time logistics attachments.
- Leather Tanning:Hide preservation and chrome-free tanning agent serving tanneries across the Eastern Province and Western Region. Rising hide processing volumes support tonnage expansion.
- Agriculture:Silage preservation and livestock feed additive applications. Agriculture Providers in central Saudi Arabia drive seasonal demand spikes aligned with harvest cycles.
- Pharmaceuticals:Active pharmaceutical intermediate synthesis and quality-assurance reagent demand. SFDA chemical substance registration creates certified supply advantages for compliant domestic manufacturers.
Leather Tanning anchors volume concentration; Pharmaceuticals delivers the highest margin realization per kilogram.
Packaging Type:
Customer type and order frequency dictate container selection across spot-contract procurement spectrum.
- Drum:Standard 200-liter steel packaging for mid-volume textile and leather processors. Eastern Province distributors maintain drum-filling infrastructure for just-in-time delivery.
- IBC Container:Intermediate bulk packaging for chemical manufacturers with integrated formic acid consumption. Yanbu-based petrochemical clusters favor IBC logistics for reduced handling costs.
- Bottle:Laboratory-scale packaging for analytical reagent and pharmaceutical quality-control applications. SFDA-registered distributors control bottle-format certification pathways.
- Bulk Tank:Dedicated tanker supply for large-scale tanneries and integrated chemical producers. Royal Commission infrastructure investments enable bulk unloading facilities at Jubail industrial city.
Bulk Tank captures the largest single-transaction volumes; Bottle commands the highest unit price realization.
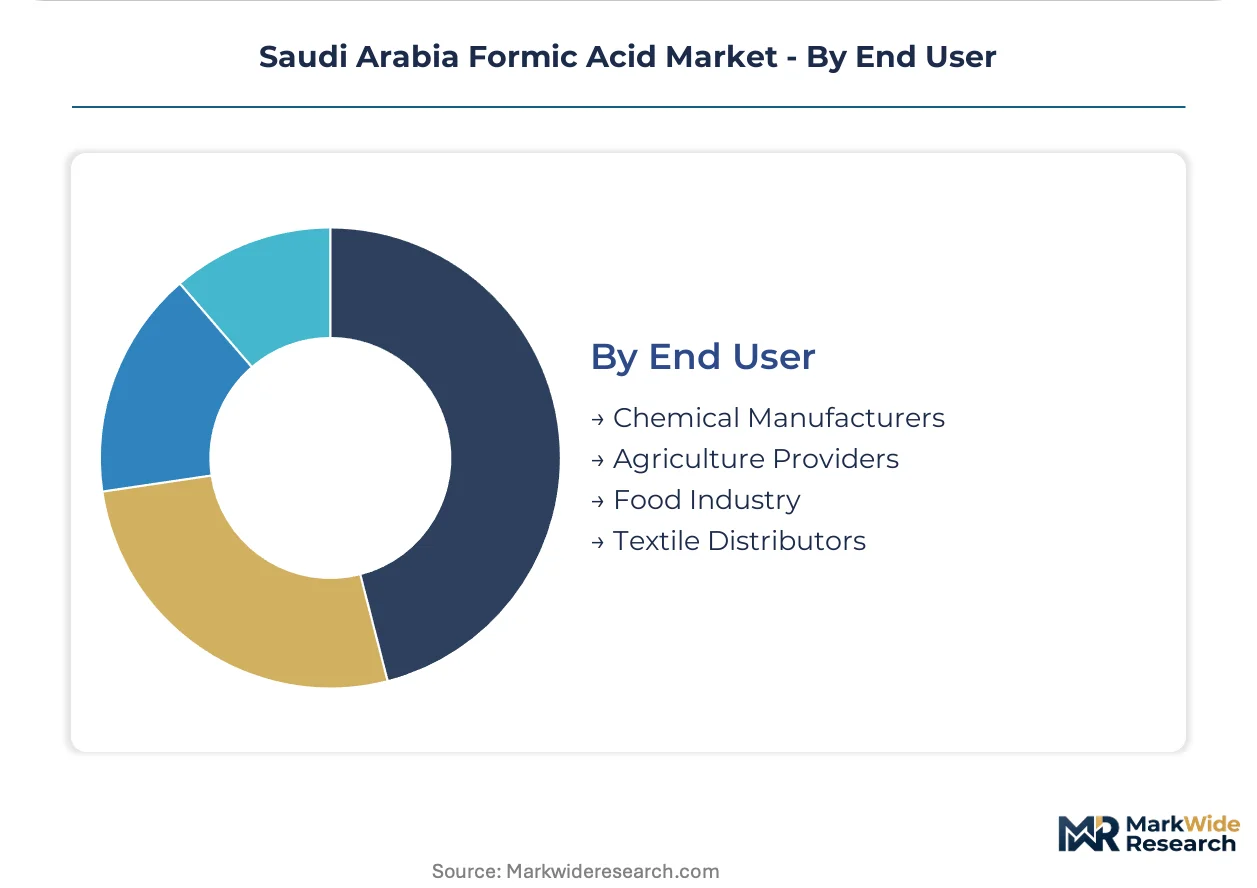
End User:
Geography clusters procurement relationships around Eastern Province petrochemical infrastructure versus Western Region consumer goods manufacturing.
- Chemical Manufacturers:Integrated and merchant producers consuming formic acid as feedstock for derivative synthesis. SABIC network affiliates anchor demand concentration within Jubail industrial cluster.
- Agriculture Providers:Silage additive distributors and livestock nutrition specialists. Central Saudi Arabia cooperatives drive seasonal procurement patterns.
- Food Industry:Preservative and pH control applications in food-contact packaging. SFDA registration requirements limit qualified supplier pools for this channel.
- Textile Distributors:Chemical trading houses supplying dye houses and finishing mills. Jeddah commercial hubs concentrate textile distributor procurement relationships.
Chemical Manufacturers dominate absolute tonnage offtake; Food Industry presents the tightest supplier qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tanneries and chemical manufacturers concentrate procurement in the Eastern Province industrial corridor, while pharmaceutical-grade buyers cluster around Riyadh and Jeddah regulatory hubs.
Eastern Province
Leather tanning operations and petrochemical feedstock integration drive formic acid consumption across Jubail and Yanbu industrial cities. The Royal Commission for Jubail and Yanbu enforces environmental discharge thresholds for manufacturing facilities. Al-Jubail Petrochemical Company anchors methanol-to-formic acid production within the Kingdom's primary chemical cluster.
Riyadh
Pharmaceutical intermediate synthesis and quality-assurance laboratory demand concentrate in the central region's medical manufacturing zone. SFDA chemical substance registration requirements elevate certified domestic suppliers above import-dependent distributors. Riyadh-based distributors control bottle-format certification pathways for analytical reagent supply.
Western Region
Textile dye houses and Jeddah commercial trading hubs concentrate mid-volume drum-packaged procurement with just-in-time logistics requirements. Hide processors in Yanbu and Jeddah industrial zones exhibit the fastest adoption of bundled supply agreements. Western Region tanneries are consolidating procurement around integrated suppliers with technical service attachments.
Central Saudi Arabia
Agricultural cooperatives drive seasonal silage preservation demand aligned with harvest cycles. The Ministry of Environment, Water and Agriculture oversees livestock feed additive safety standards. Qassim and Riyadh agricultural zones concentrate bulk tank deliveries for large-scale silage treatment operations.
Saudi Arabia Formic Acid Market Key Industry Players
Channel-controlling players compete with product-specialist players across three distinct tiers. Domestic petrochemical conglomerates with backward integration into methanol supply anchor the scale-driven tier, while European technical heritage suppliers occupy the premium-grade certification segment. Chinese manufacturers compete on standard-grade volume exports. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers seek to secure Royal Commission infrastructure allocations.
Within the integrated domestic tier, Al-Jubail Petrochemical Company and Saudi Basic Industries Corporation exemplify scale-driven positioning through captive methanol feedstock access. BASF SE represents the European technical heritage archetype, sustaining premium-grade supply relationships through distributor networks. Among Asia-Pacific volume exporters, Shandong Acid Technology Co., Ltd. occupies a position within the standard-grade export tier serving spot-market procurement channels.
| Leading Market Players |
|---|
| Advanced Petrochemical Company |
| Al-Jubail Petrochemical Company |
| BASF SE |
| Gujarat Narmada Valley Fertilizers & Chemicals Limited |
| Shandong Acid Technology Co., Ltd. |
| Petroliam Nasional Berhad (PETRONAS) |
| National Industrialization Company |
| Huanghua Pengfa Chemical Co., Ltd. |
| Saudi Basic Industries Corporation |
| Others |
Cost & Logistics Intelligence
Methanol feedstock concentration in Saudi Arabia's Eastern Province petrochemical corridor directly determines where margin pools accumulate downstream. Integrated producers with captive methanol supply capture structural cost advantages over import-dependent distributors serving pharmaceutical and food-contact channels.
Pricing Analysis
Cost-plus contracts with methanol indexation dominate procurement relationships across the Kingdom's formic acid value chain. Pricing stratifies across premium, standard, and economy tiers based on SFDA certification status and volume scale. Pricing pressure stems from citric acid substitution in food preservation applications. Spot-market buyers in textile dyeing exhibit the highest price sensitivity, while SFDA-registered pharmaceutical channels tolerate premium positioning.
Supply Chain Analysis
Export control regimes on carbon capture hydrogenation catalyst technology constrain technology transfer into Saudi production facilities. Supply concentrates in Germany, China, and Saudi Arabia itself for differentiated grade tiers. Production draws from methanol, carbon dioxide feedstock, and specialized catalyst inputs. Single-source vulnerability runs through European technical heritage suppliers for laboratory-grade certification. Distribution runs through Royal Commission-sanctioned logistics corridors within Jubail and Yanbu industrial cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's formic acid sector approaches a platform-economics inflection as SFDA registration systems interoperate with emerging Gulf chemical trade standards, creating certified-supply network effects for early movers.
For Market Incumbents: Build certification moats through in-house SFDA-registered testing laboratories. Al-Jubail Petrochemical Company and SABIC affiliates should deepen backward integration into bio-based carbon capture feedstocks. Defensive moves must counter citric acid substitution in food channels and Chinese standard-grade import pressure.
For New Entrants and Emerging Players: Pursue white-space opportunities in laboratory-grade analytical reagent supply to Riyadh pharmaceutical clusters. The Central Region's quality-assurance laboratory segment offers the most penetrable entry point. A go-to-market angle anchored to SFDA registration compliance services differentiates against commodity importers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with European technical heritage suppliers holding premium-grade distributor relationships in the Kingdom. Five-to-ten year viability hinges on carbon capture utilization scaling timelines. The signal to watch is Royal Commission infrastructure allocation announcements for bio-based production capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Feedstock | Captive supply from Jubail petrochemical complexes insulates margin structures from natural gas volatility. |
| SFDA Registration Certification Investment | In-house testing capabilities create preferential positioning in pharmaceutical and food-contact distribution channels. |
| Carbon Capture Utilization Scale-Up | Bio-based production pathways align with EU-equivalent sustainability mandates for export market access. |
| Long-term Supply Agreement with Tanneries | Technical service bundling displaces spot-market purchasing across Yanbu and Jeddah industrial zones. |
| Joint Venture for Green Chemistry Technology | Partnerships with catalyst technology holders bypass export control restrictions on hydrogenation process IP. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SABIC affiliate disclosures, and SFDA regulatory filings. Interviews with plant managers at Jubail industrial facilities, procurement leads at Eastern Province tanneries, distribution channel partners, and technical R&D directors informed demand-side calibration. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down production capacity assessments across the Kingdom's petrochemical corridor.
Forecast inputs include grade-tier segmentation, end-use industry demand curves, packaging format logistics costs, and regional production hub capacity utilization. Modeled dimensions span industrial, bio-based, laboratory, and technical grade tiers across leather tanning, pharmaceutical, textile, and agricultural applications. CAGRs derive from regression analysis against feedstock cost trajectories and regulatory compliance cost escalations.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing and methanol feedstock costs would shift the trajectory. Forecasts reflect assumptions about SFDA-EU REACH alignment timelines and carbon capture technology transfer permissions. Material shifts in Royal Commission environmental discharge thresholds or Gulf chemical trade integration pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
Sulfur Palletized Plant and Granulator Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Zinc Carbonate Market