
 Ground Calcium Carbonate Market | 2026-2036
Ground Calcium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Ground Calcium Carbonate Market Analytics
Maintenance-linked performance contracts is decoupling equipment ownership from material supply in the GCC value chain. Omya AG leverages its captive quarry network across Europe to sustain long-term offtake agreements with paper mills. Imerys anchors its position through deep vertical integration into marble reserves and downstream micronization capacity. Mississippi Lime Company specializes in high-purity food-grade production, differentiating against commodity filler suppliers.
Ground calcium carbonate consists of mechanically pulverized limestone or marble with particle sizes typically ranging from 1 to 50 microns and brightness values above 90 ISO; manufacturers employ dry or wet grinding followed by air classification to achieve targeted fineness distributions for use as a functional filler, extender, and cost-reducing additive across industrial formulations. The uncoated product type dominates volume flows into paper and plastics where cost minimization outweighs surface modification benefits, while coated variants command margin premiums in paints and rubber applications demanding improved dispersion and polymer compatibility. Specialty grades represent the fastest-expanding segment as pharmaceutical and food-grade certifications require ultrafine milling and contaminant control that standard industrial specifications do not address.
EPA regulations under the Clean Air Act influence limestone mining permits and processing emissions, while FDA food additive standards and USP monographs define purity thresholds for ingestible and injectable grades. ISO 3262 and ASTM C25 provide international benchmarks for particle size distribution and chemical composition that govern cross-border trade acceptance. Stakeholders must monitor evolving ECHA substance evaluations and emerging state-level carbon accounting rules that could restructure quarry-to-plant logistics economics.
Market Dynamics
Maintenance-linked performance contracts are decoupling equipment ownership from material supply across the GCC value chain, forcing quarries to bundle micronization services with multi-year offtake commitments rather than selling raw material alone.
Growth Catalysts
- Infrastructure spending in India:National highway expansion and urban housing projects sustain domestic quarry output for construction-grade filler applications.
- REACH compliance thresholds:Tightened purity requirements for food and pharmaceutical grades in Europe create certified supply scarcity that premium producers exploit.
- Wet grinding technology:Advanced air classification systems enable sub-micron particle production that meets specialty coating specifications for automotive paints.
Market Restraints
- Energy cost volatility:Limestone calcination and grinding operations face margin compression from natural gas price swings in European processing hubs.
- Quarry concentration in Vietnam:Export-dependent supply chains concentrate in coastal provinces vulnerable to monsoon logistics disruptions.
- Precipitated calcium carbonate substitution:Synthetic PCC variants displace GCC in high-brightness paper coating segments where surface area requirements exceed mechanical milling limits.
Strategic Opportunities
- Underpenetrated Indonesia:Packaging board mills in Java and Sumatra lack local ultrafine grinding capacity, creating import substitution potential for integrated quarry-to-powder operators.
- Bioplastic compounding:Polylactic acid and PHA formulations require mineral fillers with controlled particle size distributions that GCC producers can tailor through modified air classification.
- EU Green Deal carbon accounting:Scope 3 emissions disclosure rules favor regional quarry networks with short-haul delivery routes to paper and plastics converters.
Industry Challenges
- Certification timeline compression:USP and food-grade validations require 18-24 month contaminant testing cycles that delay specialty grade commercialization.
- Legacy grinding asset retrofit:Dry mills built for 20-micron paper filler specifications cannot economically achieve sub-5-micron pharmaceutical grades without complete classifier replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground Calcium Carbonate Market |
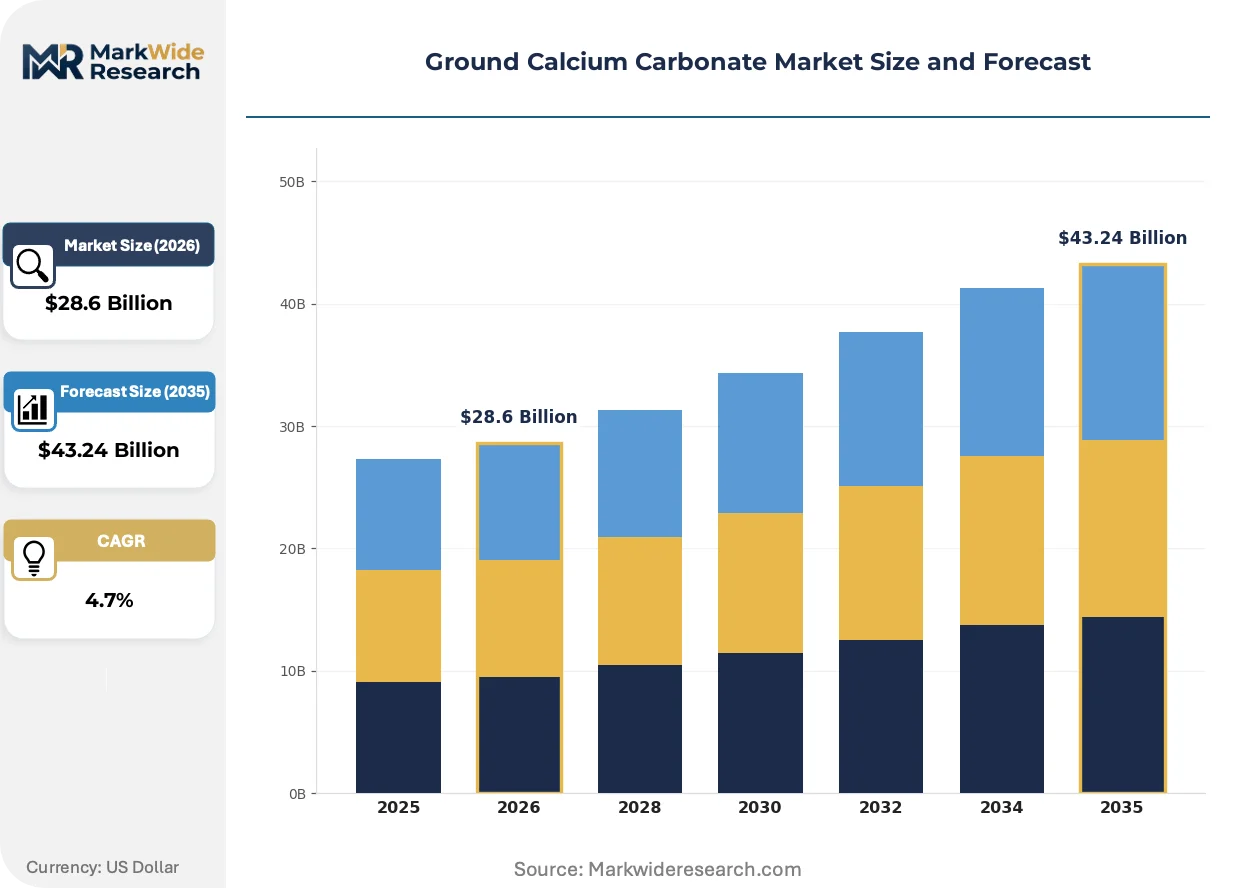
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated, Uncoated, Specialty, Granular End Use Industry: Plastics, Paints, Paper, Rubber Grade: Standard, Food, Pharmaceutical, Industrial Application: Filler, Extender, Additive, Catalyst |
| Companies Covered | Huber Engineered Materials, Lhoist, Omya AG, Sibelco, Carmeuse, Imerys, SCHAEFER KALK GmbH & Co. KG., Mississippi Lime Company, Minerals Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground Calcium Carbonate Market Evolving Landscape
Surface modification chemistry and precision classification technology are compressing the performance gap between commodity filler grades and engineered mineral additives, reshaping procurement criteria across paper, plastics, and coatings formulations.
Ultrafine wet grinding with ceramic media is absorbing energy costs that once made sub-2-micron production uneconomical for mid-scale quarries. Paper mills in Germany and Japan are adopting these grades for lightweight coated paper where brightness and opacity specifications tightened. The technology is absorbing market share from precipitated calcium carbonate in segments where cost sensitivity outweighs absolute performance thresholds.
EPA enforcement of Clean Air Act New Source Review rules for limestone processing plants is tightening particulate emission limits below 0.03 grains per dry standard cubic foot. Operators in Kentucky and Alabama face retrofit deadlines for baghouse and scrubber installations. Food-grade GCC production in these regions is consolidating toward facilities with existing environmental compliance infrastructure rather than greenfield expansion.
Buyers in the plastics compounding sector are consolidating supplier relationships around quarries offering certified carbon footprint data and chain-of-custody documentation. Tier-1 automotive suppliers in Michigan and Bavaria now require Scope 1-3 emissions declarations for mineral fillers in interior and under-hood applications. This behavioral shift favors vertically integrated quarry networks with captive grinding and logistics assets over merchant traders.
Ground Calcium Carbonate Market Segmentation
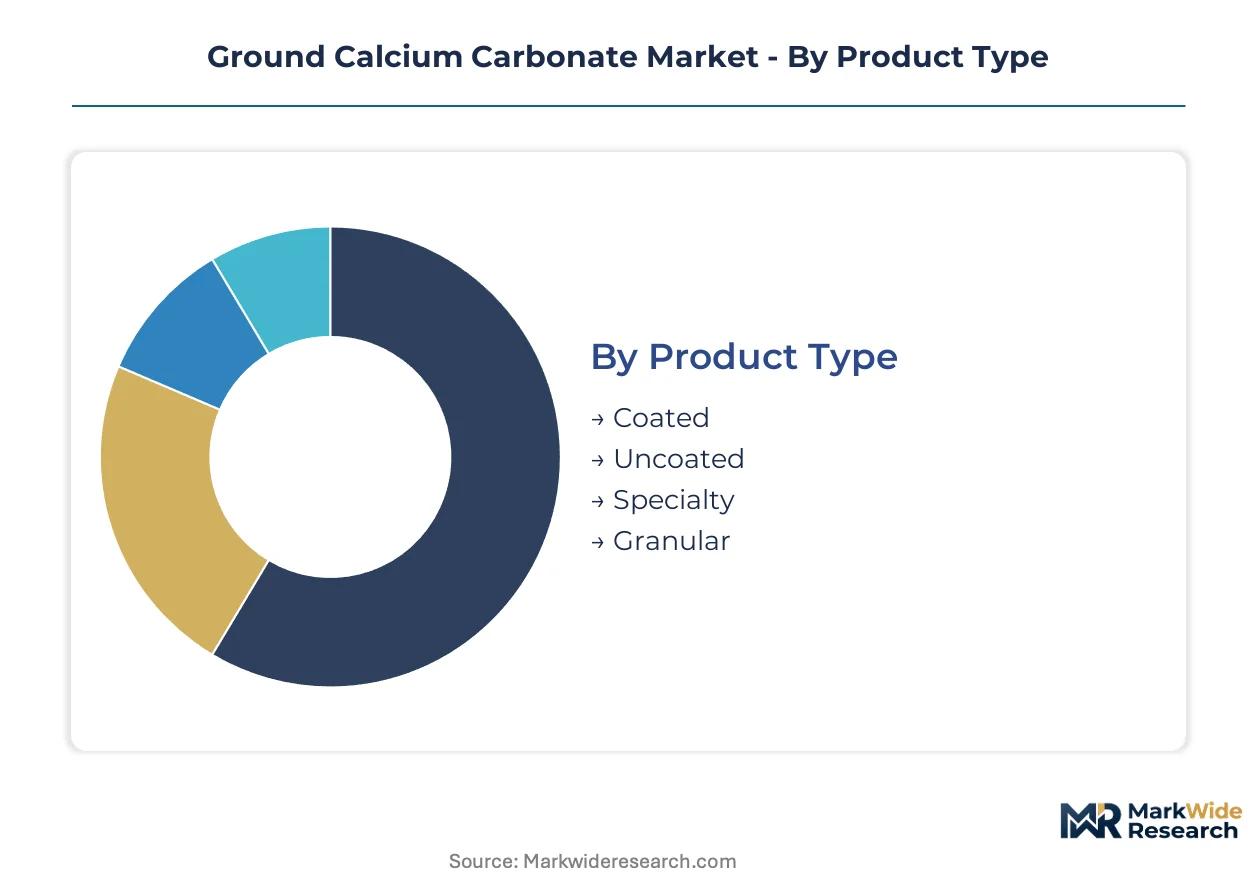
Product differentiation in ground calcium carbonate hinges on certification burden and particle engineering precision. Each segment carries distinct regulatory thresholds that reshape procurement economics across paper mills, pharmaceutical formulators, and food compounders.
Product Type:
Coated variants demand REACH food-contact approvals and FDA indirect additive clearances, while uncoated grades operate under standard industrial chemical registrations. Specialty and granular forms trigger USP monograph compliance or construction material certifications respectively.
- Coated:Surface-treated with stearic acid or calcium stearate to enhance polymer dispersion and hydrophobicity. Paper mills in Germany and Japan absorb these grades for lightweight coated paper where brightness specifications tightened beyond raw GCC capabilities.
- Uncoated:Mechanically pulverized limestone without surface modification, typically 1-50 microns with brightness above 90 ISO. Volume concentrates in India where packaging board expansion and infrastructure filler applications prioritize cost minimization over performance engineering.
- Specialty:Ultrafine sub-2-micron grades requiring USP or food-grade validation cycles spanning 18-24 months.
- Granular:Coarse fractions above 50 microns for construction and agricultural liming with minimal processing overhead.
Uncoated sits at the top of the volume ranking, with Specialty climbing the fastest.
End Use Industry:
Cost tier stratification separates commodity filler buyers from premium coating formulators. Paper and plastics procurement teams negotiate on volume scale, while paints and rubber compounders absorb margin premiums for engineered particle distributions.
- Plastics:Polypropylene and PVC compounding demands controlled particle size distributions for impact strength and dimensional stability. Tier-1 automotive suppliers in Michigan and Bavaria now require Scope 1-3 emissions declarations, favoring quarries with captive grinding and short-haul logistics.
- Paints:Architectural and automotive coatings specifications drive sub-micron production through wet grinding with ceramic media. Advanced air classification systems enable opacity performance that absorbs market share from precipitated calcium carbonate in cost-sensitive segments.
- Paper:Uncoated grades dominate filler applications while coated variants serve lightweight coated paper segments.
- Rubber:Elastomer reinforcement applications require surface-modified grades for polymer compatibility.
Paper commands the largest volume position, with Plastics gaining share fastest on bioplastic compounding requirements.
Grade:
Application maturity determines validation intensity. Food and pharmaceutical grades face compressed certification timelines and contaminant testing protocols that industrial and standard specifications bypass entirely.
- Standard:General-purpose filler meeting ISO 3262 and ASTM C25 benchmarks for particle size and chemical composition. Cross-border trade acceptance hinges on these international standards rather than sector-specific registrations.
- Food:FSSAI, FDA, and EFSA compliance for direct and indirect food contact. Mississippi Lime Company and similar specialists anchor positioning through high-purity production infrastructure that commodity suppliers cannot replicate.
- Pharmaceutical:USP monograph adherence for ingestible and injectable applications with 18-24 month validation cycles.
- Industrial:Construction, agriculture, and basic manufacturing applications with minimal purity thresholds.
Industrial occupies the volume apex, with Pharmaceutical expanding most steeply on certified supply scarcity.
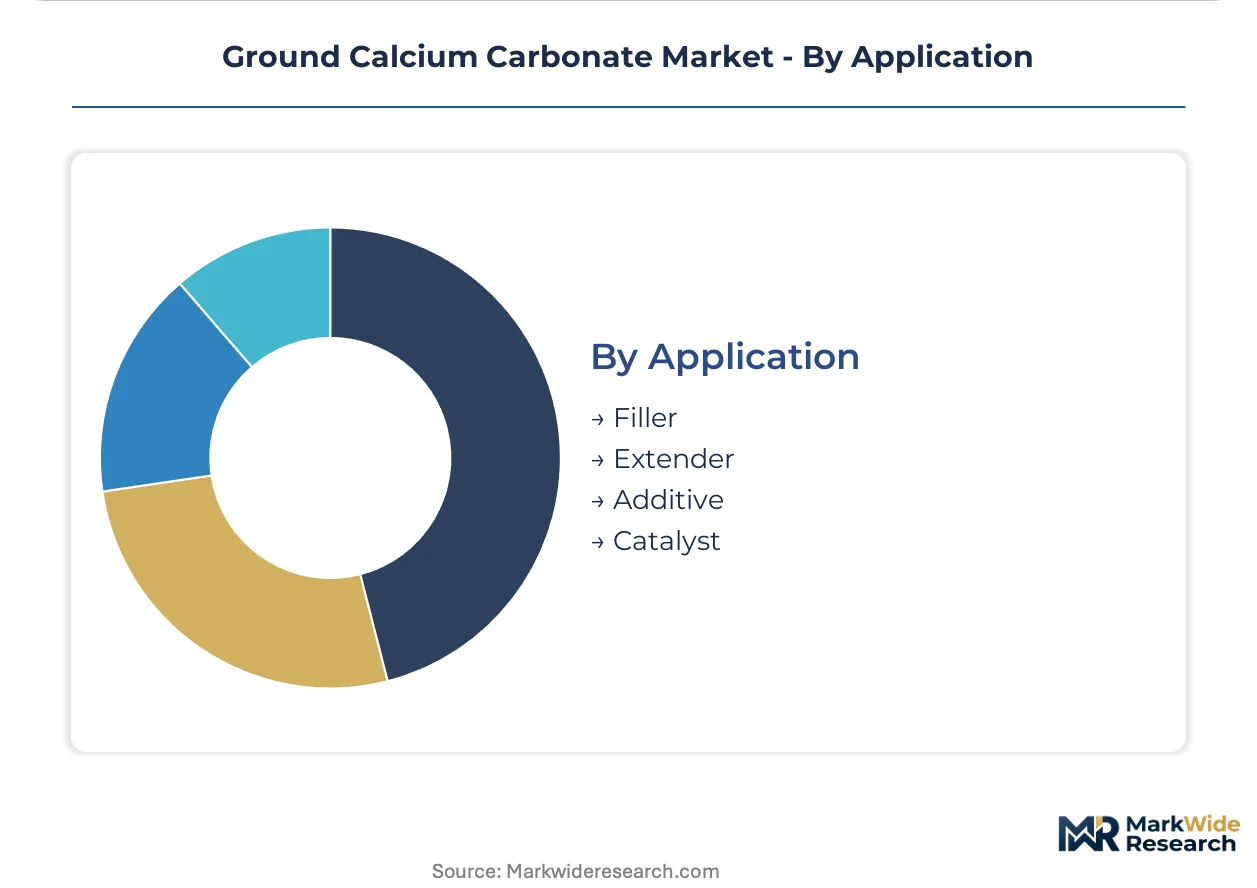
Application:
Supply concentration aligns with functional role. Fillers and extenders flow through merchant distribution, while additives and catalysts demand direct technical service relationships with integrated quarry operators.
- Filler:Volume-loaded into plastics, paper, and rubber to reduce resin or pulp consumption. Demand concentrates in India where national highway expansion and urban housing projects sustain domestic quarry output for construction-grade applications.
- Extender:Partial replacement for titanium dioxide and other expensive pigments in paints and coatings. Paper mills in Germany adopt these grades where brightness and opacity specifications tightened without absorbing full TiO2 cost premiums.
- Additive:Functional modification of polymer rheology or curing behavior in specialty compounding.
- Catalyst:Niche chemical processing applications requiring high surface area and controlled porosity.
Filler leads volume rankings, with Extender ascending fastest on pigment substitution economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India absorbs larger GCC volumes than Vietnam despite starting from a smaller industrial base, while European demand tightens around certified food-grade specifications that Asian quarries struggle to match.
United States
Paper mills in the Southeast and automotive suppliers in Michigan drive consumption of coated and uncoated grades. EPA enforcement of Clean Air Act New Source Review rules tightens particulate emission limits below 0.03 grains per dry standard cubic foot for Kentucky and Alabama processing plants. Mississippi Lime Company anchors high-purity food-grade production in the Midwest, consolidating output toward facilities with existing environmental compliance infrastructure.
Germany
Lightweight coated paper manufacturers adopt ultrafine wet-ground GCC where brightness specifications tightened beyond raw mineral capabilities. REACH compliance thresholds for food-contact applications create certified supply scarcity that premium producers exploit. Paper mills in the Rhine-Ruhr cluster absorb these advanced grades, displacing precipitated calcium carbonate in cost-sensitive segments.
India
National highway expansion and urban housing projects sustain domestic quarry output for construction-grade filler applications. FSSAI compliance requirements for food-grade production compress certification timelines for local processors. Packaging board mills in Gujarat and Maharashtra lack local ultrafine grinding capacity, creating import substitution potential for integrated quarry-to-powder operators.
Japan
Automotive coatings specifications drive sub-micron GCC production through wet grinding with ceramic media. METI industrial standards govern particle size distribution benchmarks for cross-border trade acceptance. Tier-1 automotive suppliers in the Chubu region around Nagoya require Scope 1-3 emissions declarations for mineral fillers in interior applications.
Vietnam
Export-dependent supply chains concentrate in coastal provinces vulnerable to monsoon logistics disruptions. The country's national environmental regulator tightens mining permit requirements for limestone extraction in northern quarry belts. Processing clusters near Haiphong face margin compression from natural gas price swings affecting calcination operations.
Ground Calcium Carbonate Market Competitive Landscape
Top-tier vendors anchor the premium certified-grade tier, while commodity filler suppliers compete on quarry proximity and grinding scale. The vendor base stratifies across three functional layers: integrated quarry-to-powder operators with captive reserves, regional grinding specialists serving single industries, and merchant traders distributing standard grades. Dominant competitive moves include backward integration into marble reserves and capacity expansion in underpenetrated packaging board markets.
Among Europe-based integrated operators, Omya AG and Imerys occupy positions exemplifying the captive quarry network archetype, while SCHAEFER KALK GmbH & Co. KG represents the specialized high-purity processing tier. Mississippi Lime Company anchors North American food-grade positioning. These named entities illustrate how geographic concentration of reserves and certification infrastructure shapes competitive differentiation rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Huber Engineered Materials |
| Lhoist |
| Omya AG |
| Sibelco |
| Carmeuse |
| Imerys |
| SCHAEFER KALK GmbH & Co. KG. |
| Mississippi Lime Company |
| Minerals Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between USP-validated pharmaceutical tiers and standard industrial filler specifications manifests in contract structures that bundle multi-year offtake commitments with grinding services, while commodity uncoated grades trade on spot indices tied to quarry proximity and energy input costs. Paper mills in Germany and India negotiate divergent price floors based on brightness specifications and REACH compliance burdens that Asian quarries struggle to match.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for uncoated construction-grade material, forcing European producers to defend margin position through specialty-grade certification investments. Three-tier pricing structure across pharmaceutical, food-grade, and industrial levels separates buyers by validation burden and particle size precision. Cost compression in standard filler tiers intensifies because wet grinding technology transfers to mid-scale quarries. Packaging board mills in India exhibit highest price sensitivity, while automotive coatings formulators in Japan absorb premiums for sub-micron specifications.
Supply Chain Analysis
Direct-to-mill channels handle hyperscale paper and plastics buyer demand, bypassing merchant traders for integrated quarry-to-powder operators with captive logistics assets. Production gravity centers on Vietnam, India, and Germany, with raw material dependencies on high-brightness limestone reserves, natural gas for calcination, and ceramic grinding media. Single-source vulnerability concentrates in northern Vietnamese coastal provinces exposed to monsoon logistics disruptions. Distribution runs through long-term offtake contracts with maintenance-linked performance guarantees rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ground calcium carbonate hinges on ultrafine grinding technology transfer that collapses production costs for sub-2-micron grades, while REACH and FDA compliance scarcity sustains premium-tier pricing power for validated pharmaceutical suppliers.
For Market Incumbents: Deploy captive quarry network extensions to defend position against precipitated calcium carbonate substitution in paper coating segments. Backward integration into marble reserves in Turkey and Greece secures brightness consistency for automotive coatings specifications. Maintenance-linked performance contracts lock in multi-year offtake commitments that merchant traders cannot replicate. For New Entrants and Emerging Players: Enter via packaging board mill relationships in Indonesia's Java and Sumatra regions where local ultrafine grinding capacity remains underdeveloped. Target construction-grade filler applications tied to India's national highway expansion. Position around wet grinding technology licensing partnerships that shortcut legacy asset retrofit timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where food-grade certification infrastructure concentrates among fewer than five integrated operators with USP and FDA validation capabilities. Quarry-to-powder operators with Scope 1-3 emissions disclosure systems represent acquisition targets with defensive moats against EU Green Deal carbon accounting rules. Watch for wet grinding technology cost curves flattening as inflection signal for specialty-grade margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marble Reserves | Imerys and Omya AG anchor European brightness specifications through captive high-purity deposits. |
| Wet Grinding Technology Licensing | Sub-micron production capability transfers to mid-scale quarries in Vietnam and Indonesia. |
| Long-term Supply Agreement | Paper mills in Germany and Japan lock in multi-year offtake with maintenance-linked performance terms. |
| Green Manufacturing Transition | EU Green Deal Scope 3 disclosure rules favor regional quarry networks with short-haul delivery routes. |
| Capacity Expansion in Underpenetrated Markets | Integrated quarry-to-powder operators target Indonesia's packaging board mill demand gap. |
Research Methodology
Coverage spans India, Vietnam, Germany, Japan, and the United States, with primary inputs from each market cluster combining interviews with quarry operations managers, paper mill procurement directors, plastics compounding technical leads, coatings formulators, and regulatory affairs specialists at food-grade producers. Secondary validation draws from customs and trade data, EPA and ECHA substance evaluation filings, SEC 10-K disclosures by listed mineral processors, and ISO 3262 certification registries. Bottom-up volume estimates triangulate against top-down industry consumption benchmarks.
Rate-of-change decomposition separates volume growth drivers by grade tier, end-use industry, particle size specification, and regional regulatory cluster across the analysis window. CAGRs derive from segmented demand modeling that weights infrastructure spending cycles, packaging board capacity additions, and automotive coatings specification tightening. Forecast inputs include natural gas price trajectories for European calcination economics and FSSAI compliance timeline compression for Indian food-grade processors.
Inputs from quarry operators and paper mill procurement teams were available through the study window; gaps in real-time energy cost pass-through data introduce uncertainty bands for European processing margin forecasts. Forecasts reflect assumptions about REACH enforcement consistency and wet grinding technology adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Calcium Carbonate Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Global Cyclohexylbenzene Market
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
Phosphorus and Derivatives Market
Bulk Chemicals
Global Hexamethylenediamine Market
Bulk Chemicals
Magnesium Phosphate Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Global Ethylene Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Castor Oil Derivatives Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Antimony Trioxide Market