
 Sodium Bisulfite Market | 2026-2036
Sodium Bisulfite Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Bisulfite Market Analytics
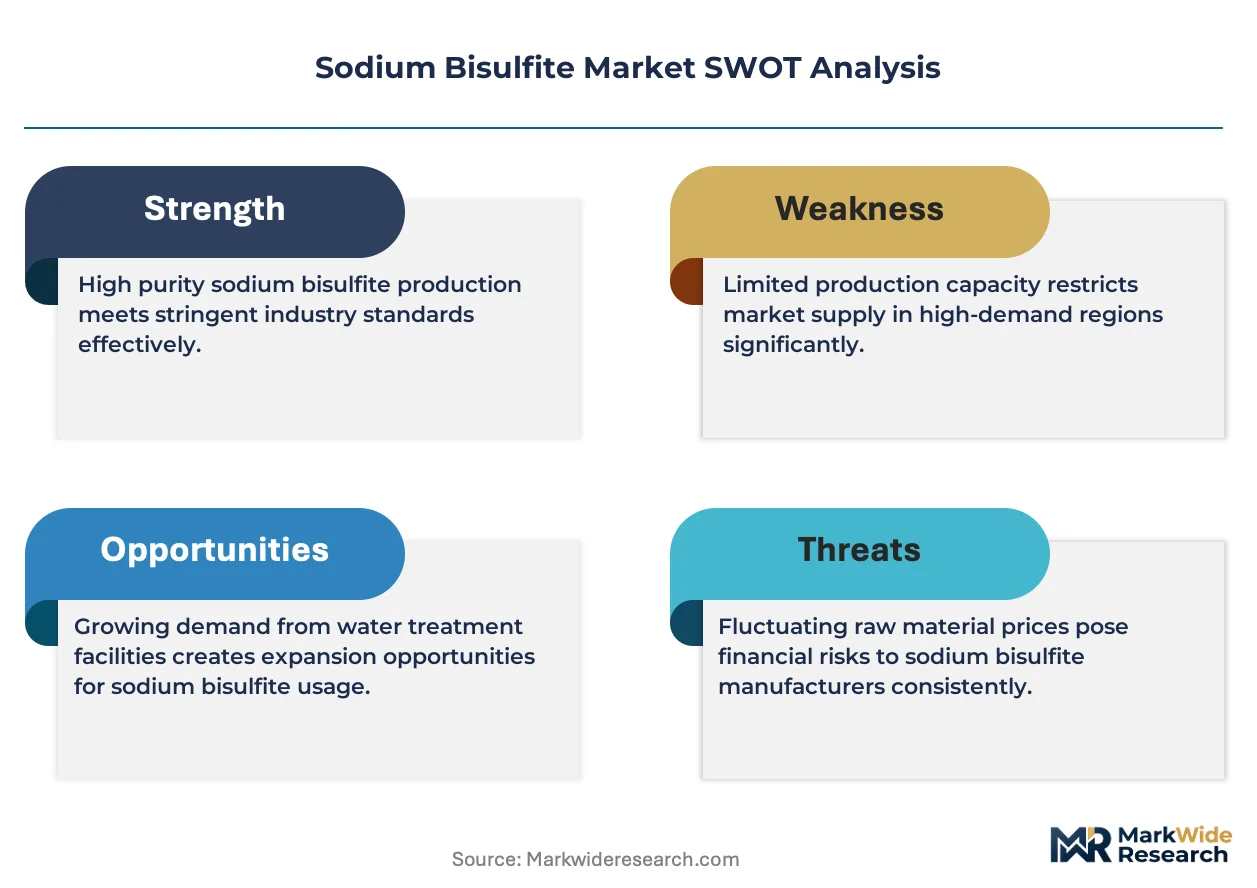
Buyer concentration among municipal water utilities is hardening across North America and Western Europe. BASF SE leverages its integrated sulfur dioxide supply chain to maintain cost positions in bulk liquid deliveries. Solvay S.A. anchors European demand through dedicated manufacturing assets in Belgium and Italy. Chemtrade Logistics Inc. competes on regional distribution density, operating a network of rail-served terminals across the Great Lakes and Midwest corridors.
Sodium bisulfite is an inorganic salt with the chemical formula NaHSO₃, typically manufactured by reacting sulfur dioxide with sodium carbonate or sodium hydroxide to yield a solution containing approximately 25-40% active ingredient by weight; it functions primarily as a reducing agent, oxygen scavenger, and antimicrobial preservative across industrial processes. Water treatment applications dominate volume consumption, as liquid form deliveries integrate directly into utility dosing systems with minimal handling. Crystalline powder grades command margin premiums in pharmaceutical and food preservation segments where purity specifications exceed industrial grades. Pulp & paper end use remains structurally mature in North America, while mining applications in copper and gold flotation show faster growth trajectories in South American and Australian markets.
EPA effluent guidelines under the Clean Water Act and EU Drinking Water Directive shape product specifications and compliance documentation burdens for suppliers seeking utility contracts. FDA food additive regulations and REACH registration requirements in Europe govern purity thresholds and trace contaminant limits, creating divergent certification costs for manufacturers serving multiple geographies. Stakeholders must monitor evolving PFAS testing protocols and sulfur dioxide emissions controls, as these frameworks threaten to restrict feedstock availability or impose additional treatment obligations at production facilities.
Market Dynamics
EPA discharge standards under the Clean Water Act are tightening residual chlorine limits, compelling municipal water utilities across the United States to upgrade dechlorination systems and expand chemical procurement volumes.
Growth Catalysts
- Clean Water Act compliance deadlines:Municipal utilities in the United States face enforceable effluent limits that mandate sodium bisulfite installation for dechlorination, creating immediate procurement pull.
- Copper-gold flotation chemistry:Mining operations in Chile and Peru deploy sodium bisulfite as a selective depressant in sulfide ore processing, expanding industrial consumption outside traditional water treatment.
- Aging infrastructure replacement cycles:Water treatment facilities in the Great Lakes and Midwest corridors are replacing legacy chlorination-dechlorination trains, driving chemical system upgrades.
Market Restraints
- Sulfur dioxide feedstock volatility:Sodium bisulfite production depends on sulfur dioxide availability from petroleum refining and smelting operations, exposing margins to energy sector cyclicality.
- European sulfur emissions controls:REACH registration requirements and industrial emissions directives impose compliance documentation burdens that restrict small-scale producer participation.
- Alternative dechlorination chemists:Activated carbon systems and sodium thiosulfate compete for utility contracts in regions with less stringent residual chlorine monitoring.
Strategic Opportunities
- Pharmaceutical-grade crystalline powder:FDA-regulated drug manufacturing requires high-purity sodium bisulfite as an antioxidant excipient, commanding margin premiums over industrial liquid grades.
- Australian mining expansion:Gold and copper operations in Western Australia are adopting sodium bisulfite flotation chemistry, opening geographic white space beyond established South American demand.
- Rail-served terminal networks:Bulk liquid distribution through dedicated chemical terminals reduces handling costs and secures long-term utility supply contracts.
Industry Challenges
- PFAS testing protocol evolution:Emerging analytical standards for per- and polyfluoroalkyl substances in chemical products threaten to impose additional certification timelines and laboratory costs.
- Legacy dosing system integration:Municipal utilities operate chlorination-dechlorination infrastructure from multiple decades, requiring customized engineering to accommodate sodium bisulfite feed rates and compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Bisulfite Market |
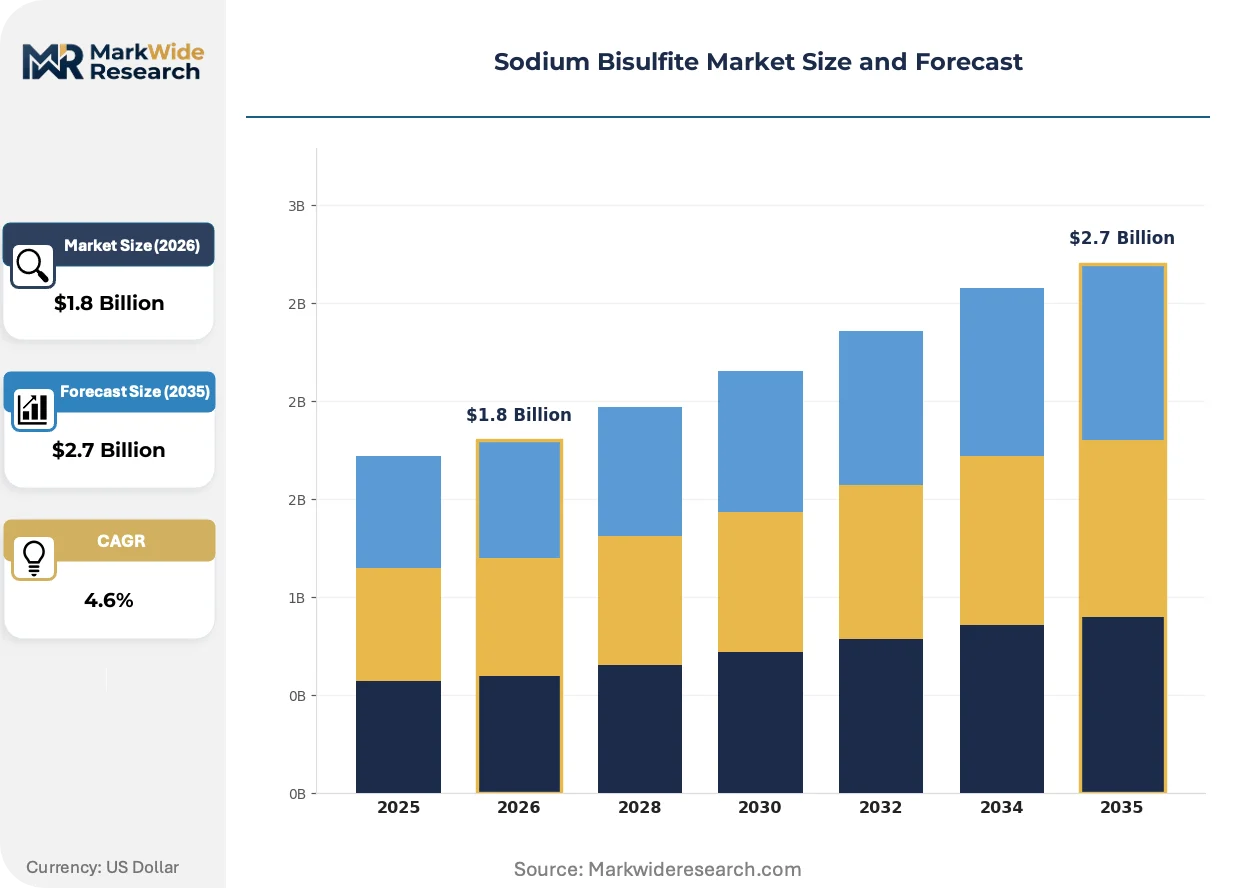
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Food Preservation, Water Treatment, Textile Processing, Pharmaceuticals Product Type: Liquid Form, Crystalline Powder, Granules, Pellets End Use Industry: Food & Beverage, Chemical Manufacturing, Mining, Pulp & Paper Delivery Mode: Bulk Shipping, Bagged, Drum, Cylinder |
| Companies Covered | BASF SE, Solvay S.A., Aditya Birla Chemicals, Chemtrade Logistics Inc., Esseco USA LLC, Hawkins Inc., INEOS Calabrian Corporation, Grillo-Werke AG, Kemira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Bisulfite Market Evolving Landscape
Digital dosing control systems and automated residual monitoring are transforming how utilities manage dechlorination chemistry, reducing manual sampling and enabling real-time compliance verification.
Membrane electrolysis technology for on-site sodium bisulfite generation is unifying chemical production with consumption at large water treatment facilities. Metropolitan utilities in California and Texas are piloting these systems to eliminate bulk liquid transport and storage liabilities. This distributed manufacturing model is compressing traditional chemical distribution margins while capturing value through service contracts.
EPA effluent limitation guidelines under the Clean Water Act are mandating lower residual chlorine concentrations in treated wastewater discharges. Industrial facilities in the Ohio River basin and Chesapeake Bay watershed must install continuous monitoring and automated dosing systems. Chemical suppliers are responding with technical service packages that bundle product supply with compliance documentation.
Utility procurement departments are consolidating chemical contracts under multi-year framework agreements that bundle sodium bisulfite with coagulants and pH adjusters. Regional water authorities in the Upper Midwest are displacing spot purchasing with integrated supply contracts that transfer inventory risk to distributors. This concentration of buying power is most visible in the Great Lakes states where municipal aggregation has reduced supplier counts.
Sodium Bisulfite Market Segmentation
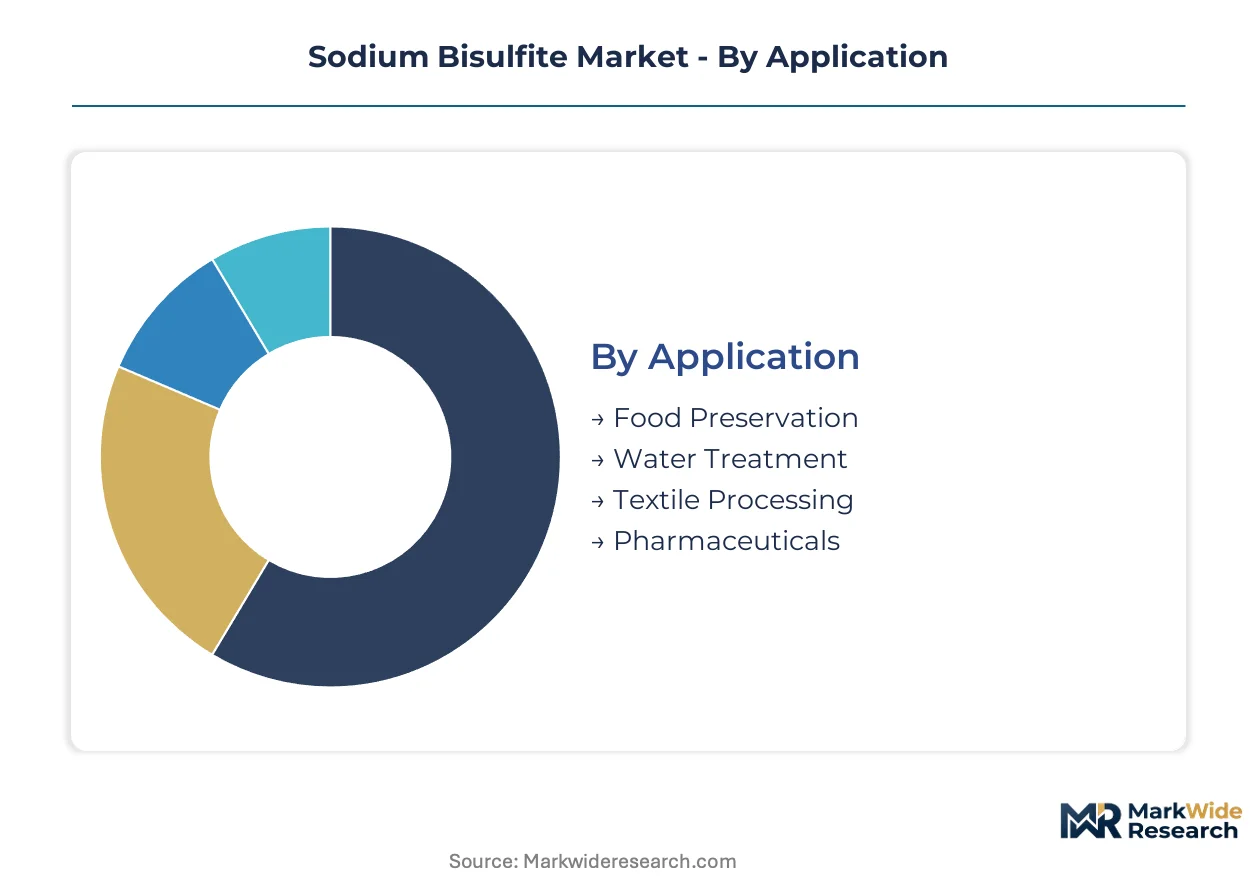
Sodium bisulfite procurement patterns diverge sharply across certification tiers and handling requirements. Utility buyers prioritize bulk liquid contracts with EPA compliance documentation, while pharmaceutical and food-grade purchasers demand batch-specific purity certificates and trace contaminant testing.
Application:
Certification burdens concentrate in food and pharmaceutical applications where FDA regulations govern maximum sulfur dioxide residuals and antioxidant labeling requirements. Water treatment utilities operate under EPA discharge permits with less stringent product purity thresholds but stricter documentation of dechlorination performance.
- Water Treatment:Municipal utilities consume sodium bisulfite in 25-40% liquid solution form for chlorine neutralization in wastewater effluent. Procurement concentrates in the Great Lakes and Midwest corridors where aging infrastructure replacement drives system upgrades under tightening EPA residual chlorine limits.
- Food Preservation:FDA-regulated applications require crystalline powder grades meeting Food Chemicals Codex specifications for sulfur dioxide content and heavy metal limits. Wineries and dried fruit processors in California's Central Valley represent concentrated demand for antioxidant and antimicrobial preservation.
- Textile Processing:Bleach neutralization and dye reduction applications in North Carolina's textile belt utilize technical-grade liquid deliveries with minimal certification overhead.
- Pharmaceuticals:USP-grade crystalline material serves as an antioxidant excipient in parenteral drug formulations with mandatory elemental impurity testing under ICH Q3D guidelines.
Water Treatment sits at the top of the volume ranking, with Pharmaceuticals climbing the fastest.
Product Type:
Physical form dictates supply chain economics and margin structure across customer tiers. Liquid solutions capture utility volume through direct-feed compatibility, while solid forms command premiums in precision-dosing applications.
- Liquid Form:Aqueous solutions containing 25-40% sodium bisulfite by weight dominate municipal procurement through rail-served terminal networks. BASF SE and Chemtrade Logistics Inc. compete on bulk distribution density across the Midwest and Great Lakes corridors.
- Crystalline Powder:High-purity solid grades require multi-stage crystallization and drying processes to meet pharmaceutical and food-grade specifications. Solvay S.A.'s Belgian and Italian manufacturing assets anchor European supply for regulated applications.
- Granules:Intermediate particle size offers handling advantages in mining flotation circuits where dust control matters but powder dissolution rates are unnecessary.
- Pellets:Compressed solid form reduces airborne exposure during manual handling in small-scale textile and food processing operations with limited automation.
Liquid Form captures the largest share of tonnage moved, though Crystalline Powder generates the steepest margin expansion.
End Use Industry:
Industry verticals separate by technical service intensity and contract duration. Mining and pulp operations favor spot purchasing of technical grades, while food and chemical manufacturers lock in multi-year supply agreements with audit rights.
- Food & Beverage:Wineries, breweries, and processed fruit manufacturers deploy sodium bisulfite for microbial stabilization and antioxidant protection. FDA food additive regulations require supplier certification of sulfur dioxide residuals and labeling compliance.
- Chemical Manufacturing:Reducing agent applications in organic synthesis and chemical intermediates production consume technical-grade liquid deliveries with specification flexibility.
- Mining:Copper-gold flotation operations in Chile and Peru utilize sodium bisulfite as a selective depressant in sulfide ore processing, opening geographic white space beyond established North American water treatment demand.
- Pulp & Paper:Bleach neutralization and brightness stabilization applications in the Southeast United States represent mature consumption with limited growth trajectory.
Food & Beverage leads in contract value concentration, with Mining expanding most quickly on a percentage basis.
Delivery Mode:
Packaging configuration aligns with customer scale and automation infrastructure. Bulk systems minimize unit costs for high-volume consumers, while smaller formats serve distributed operations with limited storage capacity.
- Bulk Shipping:Rail tank cars and dedicated chemical terminals serve metropolitan utilities and large industrial facilities with continuous dosing systems. Chemtrade Logistics Inc. operates terminal networks across the Great Lakes and Midwest to capture this volume.
- Bagged:25-50 kg multi-wall paper bags suit mid-scale food processors and textile mills with manual handling capabilities and moderate consumption rates.
- Drum:200-liter polyethylene drums serve pharmaceutical manufacturers and specialty chemical operations requiring controlled dispensing and lot traceability.
- Cylinder:Pressurized gas cylinders deliver sulfur dioxide feedstock for on-site sodium bisulfite generation systems piloted in California and Texas metropolitan utilities.
Bulk Shipping dominates tonnage delivered, with Cylinder gaining traction fastest among early adopters of distributed manufacturing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineers and water treatment technicians concentrate in the Great Lakes industrial corridor, anchoring North American sodium bisulfite demand.
United States
Municipal utilities in the Great Lakes and Midwest corridors drive bulk liquid procurement for dechlorination system upgrades. EPA effluent guidelines under the Clean Water Act mandate lower residual chlorine limits in wastewater discharges. Metropolitan water authorities in Chicago, Cleveland, and Detroit are replacing legacy chlorination infrastructure with automated sodium bisulfite dosing systems.
Germany
Industrial chemical manufacturers consume technical-grade sodium bisulfite as a reducing agent in organic synthesis and specialty intermediates production. REACH registration requirements and the EU Industrial Emissions Directive impose compliance documentation burdens on suppliers. The Rhine-Ruhr industrial cluster hosts integrated chemical complexes where captive sulfur dioxide feedstock supports derivative production.
China
Pulp and paper mills in Shandong and Jiangsu provinces utilize sodium bisulfite for bleach neutralization and brightness stabilization. GB standards for industrial chemical quality and the Ministry of Ecology and Environment's sulfur emissions controls shape product specifications. The Yangtze River Delta chemical manufacturing belt concentrates domestic production capacity for technical-grade liquid deliveries.
Chile
Copper-gold mining operations in the Atacama Desert deploy sodium bisulfite as a selective depressant in sulfide ore flotation circuits. The country's national mining regulator oversees chemical handling protocols in extractive operations. Antofagasta and Calama host concentrated mining chemical consumption that extends South American demand beyond traditional water treatment applications.
Australia
Gold and copper operations in Western Australia are adopting sodium bisulfite flotation chemistry for sulfide ore processing. The Therapeutic Goods Administration and state environmental protection agencies govern chemical import and handling standards. The Kalgoorlie-Boulder mining district represents emerging geographic white space for industrial-grade procurement.
Sodium Bisulfite Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the sodium bisulfite value chain. The market structure tilts toward consolidated supply in bulk liquid utilities contracting, while crystalline powder segments retain specialist participation. Three archetypes dominate: integrated sulfur dioxide producers with captive feedstock, regional distributors operating rail-served terminal networks, and pharmaceutical-grade purity specialists serving regulated applications. Capacity expansion and backward integration into sulfur dioxide supply represent the dominant competitive moves.
Among integrated chemical producers, BASF SE and Solvay S.A. occupy positions exemplifying the feedstock-integrated archetype. BASF SE leverages its sulfur dioxide supply chain for bulk liquid distribution density across European and North American corridors. Solvay S.A. anchors regulated-application supply through Belgian and Italian manufacturing assets. Chemtrade Logistics Inc. represents the regional distribution specialist model, competing on terminal network coverage rather than backward integration.
| Leading Market Players |
|---|
| BASF SE |
| Solvay S.A. |
| Aditya Birla Chemicals |
| Chemtrade Logistics Inc. |
| Esseco USA LLC |
| Hawkins Inc. |
| INEOS Calabrian Corporation |
| Grillo-Werke AG |
| Kemira |
| Others |
Value Network & Pricing Analysis
Specialized chemical engineers and water treatment technicians concentrated in the Great Lakes industrial corridor anchor labor-cost differentials that widen pricing-tier spreads between bulk liquid utility contracts and precision-dosed pharmaceutical grades.
Pricing Analysis
Bundled technical service packages versus unbundled commodity spot purchasing splits the pricing landscape. Three-tier pricing structure across pharmaceutical-grade crystalline powder, food-grade crystalline, and industrial liquid separates premium antioxidant excipient supply from standard dechlorination chemistry. Price differentiation rests on FDA certification overhead and volume-scale procurement. Cost compression in bulk liquid utility contracts is intensifying because municipal aggregation concentrates buying power. Municipal water authorities exhibit highest price sensitivity; pharmaceutical manufacturers demonstrate lowest sensitivity due to regulatory switching costs.
Supply Chain Analysis
Single-source vulnerability sits with sulfur dioxide feedstock derived from petroleum refining and smelting operations concentrated in the United States, Germany, and China. Sodium bisulfite production draws from sulfur dioxide, sodium carbonate, and sodium hydroxide inputs. Supply chain risk centers on energy sector cyclicality exposing margins to feedstock volatility. Distribution runs through rail-served terminal networks across the Great Lakes and Midwest corridors for bulk liquid utility delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sodium bisulfite market functions as a regulatory compounder where EPA Clean Water Act effluent deadlines drive sustained municipal procurement pull.
For Market Incumbents: Anticipate membrane electrolysis on-site generation systems piloted in California and Texas metropolitan utilities compressing traditional chemical distribution margins. Defend position by deepening captive sulfur dioxide supply through backward integration into petroleum refining partnerships. Secure long-term framework agreements bundling sodium bisulfite with coagulants and pH adjusters to lock in utility procurement concentration.
For New Entrants and Emerging Players: EPA Clean Water Act compliance deadlines in the United States open a window for regional distribution specialists competing on terminal network density rather than backward integration. Target Australian mining expansion in Western Australia's Kalgoorlie-Boulder district where gold-copper flotation chemistry adoption outpaces established supply relationships. Pursue technical service bundling as the primary go-to-market angle, wrapping compliance documentation with product supply.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors operating rail-served terminal networks without captive feedstock integration. Long-term viability over a five-to-ten-year window favors assets with EPA compliance documentation capabilities and municipal contract concentration. Monitor PFAS testing protocol evolution as the critical inflection signal threatening additional certification timelines and laboratory cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Dioxide Supply | Captive feedstock from petroleum refining operations insulates margins against energy sector cyclicality. |
| Rail-Served Terminal Network Expansion | Bulk liquid distribution density across Great Lakes corridors secures long-term municipal utility contracts. |
| Pharmaceutical-Grade Crystalline Capacity Addition | USP-grade antioxidant excipient production captures FDA-regulated drug manufacturing margin premiums. |
| Membrane Electrolysis On-Site Generation Partnerships | California and Texas metropolitan pilots compress traditional distribution while capturing service contract value. |
| Australian Mining Chemical Supply Agreement | Western Australia gold-copper flotation chemistry adoption extends demand beyond established South American markets. |
Research Methodology
Bottom-up water treatment utility consumption modeling reconciled against top-down sulfur dioxide feedstock tracking forms the analytical core. Primary interviews with municipal procurement managers, chemical plant engineers, distribution channel partners, and mining operations metallurgists combined with secondary validation from EPA effluent guideline filings, customs trade data, ACC chemical industry reports, and SEC 10-K disclosures. Triangulation between demand-side utility contract analysis and supply-side manufacturing capacity assessment anchors volume estimates.
Input-output matrices map sodium bisulfite production across grade tier, end-use industry, physical form, and regional production hub dimensions. CAGRs derive from segment-level growth rate reconciliation against macro drivers across the projection horizon. Forecast inputs incorporate EPA compliance deadline enforcement intensity, mining flotation chemistry adoption curves, and membrane electrolysis technology diffusion rates.
Revisions become necessary when PFAS testing protocols impose additional certification burdens, sulfur dioxide feedstock availability contracts due to emissions controls, or municipal procurement aggregation accelerates beyond modeled concentration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Precipitated Calcium Carbonate Market
Bulk Chemicals
Crude Tall Oil Derivative Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Linear Alkylbenzene (LAB) Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Propionaldehyde Market
Bulk Chemicals
Global Silica Flour Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Elemental Sulfur Market