
 Power Sports Aftermarket Market | 2026-2036
Power Sports Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Power Sports Aftermarket Market Intelligence
EPA small-engine emissions standards is repositioning the cost-of-entry calculus for aftermarket manufacturers seeking compliance with catalytic converter and evaporative control mandates. Polaris Inc leverages its captive distribution network to sustain parts availability across North American dealer channels. BRP Inc anchors its aftermarket strategy through proprietary fitment systems that lock in repeat purchases from Can-Am and Sea-Doo owners. Honda Motor Co Ltd competes on engineering density, offering replacement components that match original equipment durability specifications.
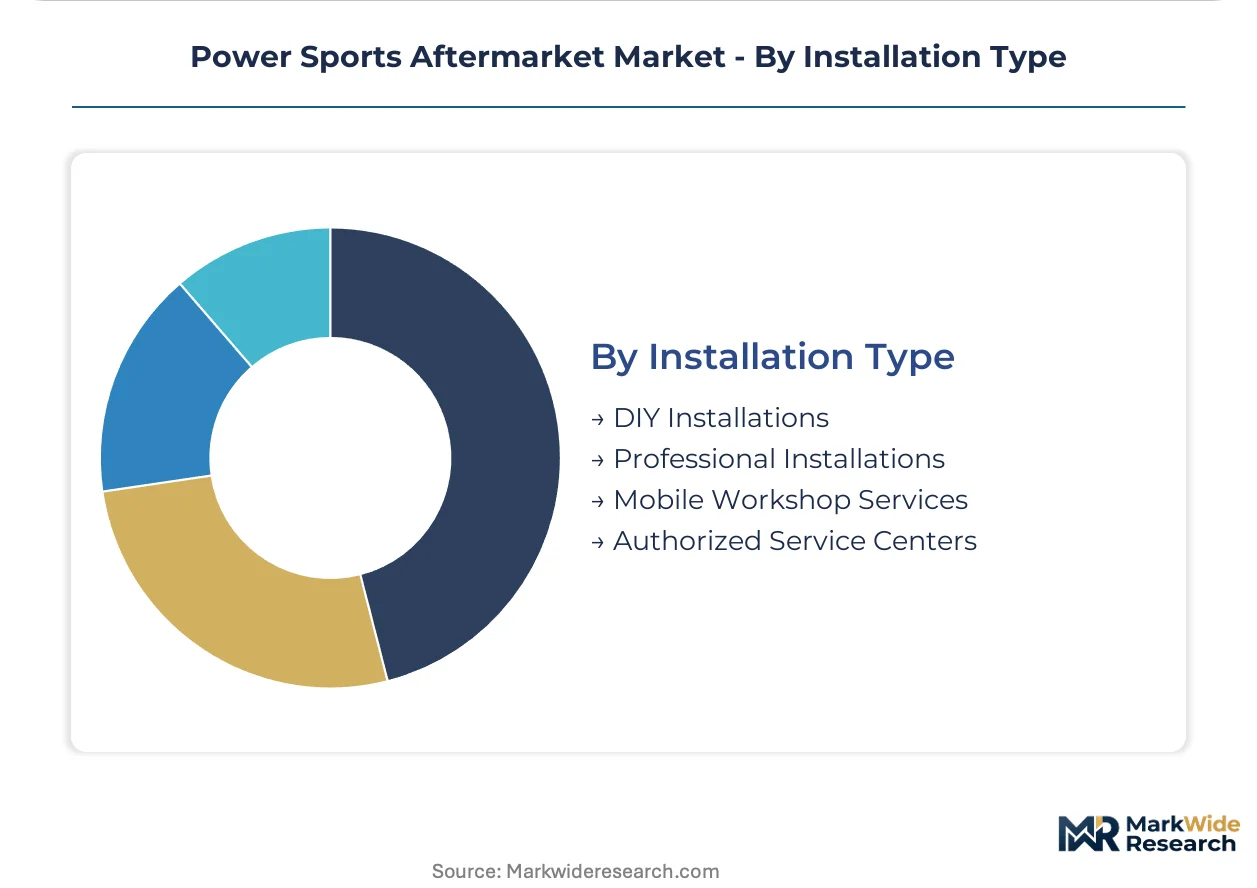
The Power Sports Aftermarket encompasses replacement parts, performance upgrades, and aesthetic modifications for all-terrain vehicles, side-by-sides, snowmobiles, and personal watercraft, typically manufactured from hardened aluminum alloys, composite polymers, and stainless steel substrates rated for extreme vibration and moisture exposure. Engine Components and Exhaust Systems dominate current revenue flows as wear-item replacement cycles compress under heavier recreational usage patterns. Suspension Kits represent the fastest-growing product category as lifted and long-travel configurations spread from desert racing into consumer trail applications. The Installation Type dimension reveals structural bifurcation: DIY Installations capture value-conscious hobbyists while Authorized Service Centers command premium labor rates for complex electronic integrations.
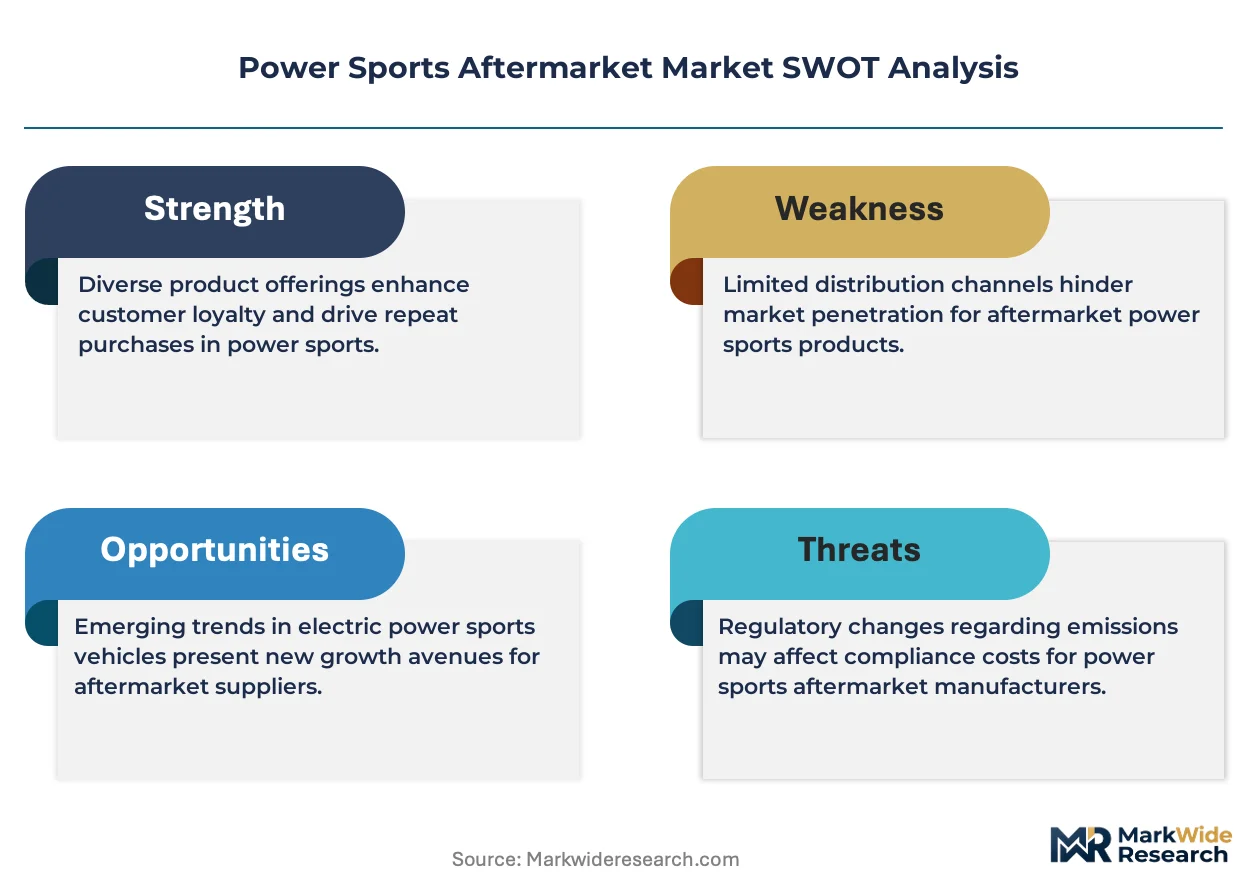
FCC equipment authorization rules govern lighting and audio accessories that integrate with vehicle CAN bus architectures, while NHTSA safety recalls periodically remove non-compliant aftermarket products from commerce. EPA enforcement of evaporative emission standards is forcing reformulation of fuel system components and restricting certain performance chip calibrations that alter combustion parameters. Stakeholders must monitor regulatory preemption battles between federal standards and emerging state-level restrictions on modified exhaust systems that threaten to fragment product legality across jurisdictions.
Market Dynamics
EPA evaporative emission mandates are compressing product development cycles for fuel system components while simultaneously elevating material costs for catalytic converter substrates across the aftermarket supply base.
Growth Catalysts
- Emissions Compliance Retrofit Demand:EPA small-engine standards are generating replacement cycles for pre-2020 ATVs and side-by-sides requiring upgraded fuel caps, charcoal canisters, and sealed tank systems to maintain trail access permits.
- Composite Suspension Component Adoption:Long-travel desert racing configurations are migrating to consumer trail applications, expanding addressable demand for hardened aluminum A-arms and polymer skid plates rated for extreme vibration.
- United States Trail Access Expansion:State-level OHV registration programs in Utah, Arizona, and Colorado are formalizing trail networks that sustain premium parts consumption through organized event calendars and permit-based access systems.
Market Restraints
- Palladium-Rhodium Cost Volatility:Catalytic converter substrate pricing fluctuates with precious metal spot markets, compressing margin predictability for exhaust system manufacturers serving the compliant aftermarket segment.
- Chinese Magnesium Alloy Concentration:Die-cast wheel and chassis component supply concentrates in Henan and Shaanxi provinces, exposing North American distributors to freight cost spikes and tariff uncertainty.
- CAN Bus Integration Complexity:Modern power sports vehicle architectures restrict plug-and-play electrical accessory installation, limiting addressable market for lighting and audio upgrades without dealer-level programming tools.
Strategic Opportunities
- Underpenetrated Australian Desert Touring Segment:Simpson Desert and Outback track networks lack established aftermarket distribution, creating first-mover positioning for long-range fuel tank and suspension kit specialists.
- Digital-First Direct Distribution:Fitment-configurator platforms with VIN-specific compatibility engines are bypassing traditional dealer channels, capturing margin from DIY installers seeking real-time inventory visibility.
- EU F-Gas Regulation Tailwind:Phasedown of hydrofluorocarbon refrigerants is accelerating demand for retrofit air conditioning kits in side-by-side applications across Mediterranean and Alpine recreational zones.
Industry Challenges
- Embedded Software Calibration Expertise Gap:EPA-compliant engine control module tuning requires specialized firmware engineering talent that concentrates at OEM captive development centers, constraining independent performance parts suppliers.
- Homologation Timeline Compression:NHTSA safety recall protocols and FCC equipment authorization cycles now overlap with seasonal product launch windows, forcing inventory risk-taking ahead of regulatory clearance.
- Legacy Carburetor Inventory Stranding:Pre-EPA Tier 3 fuel system component stocks face accelerated obsolescence as state trail authorities deny registration to non-compliant vehicles, creating write-down exposure for distributors with aged warehouse positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Sports Aftermarket Market |
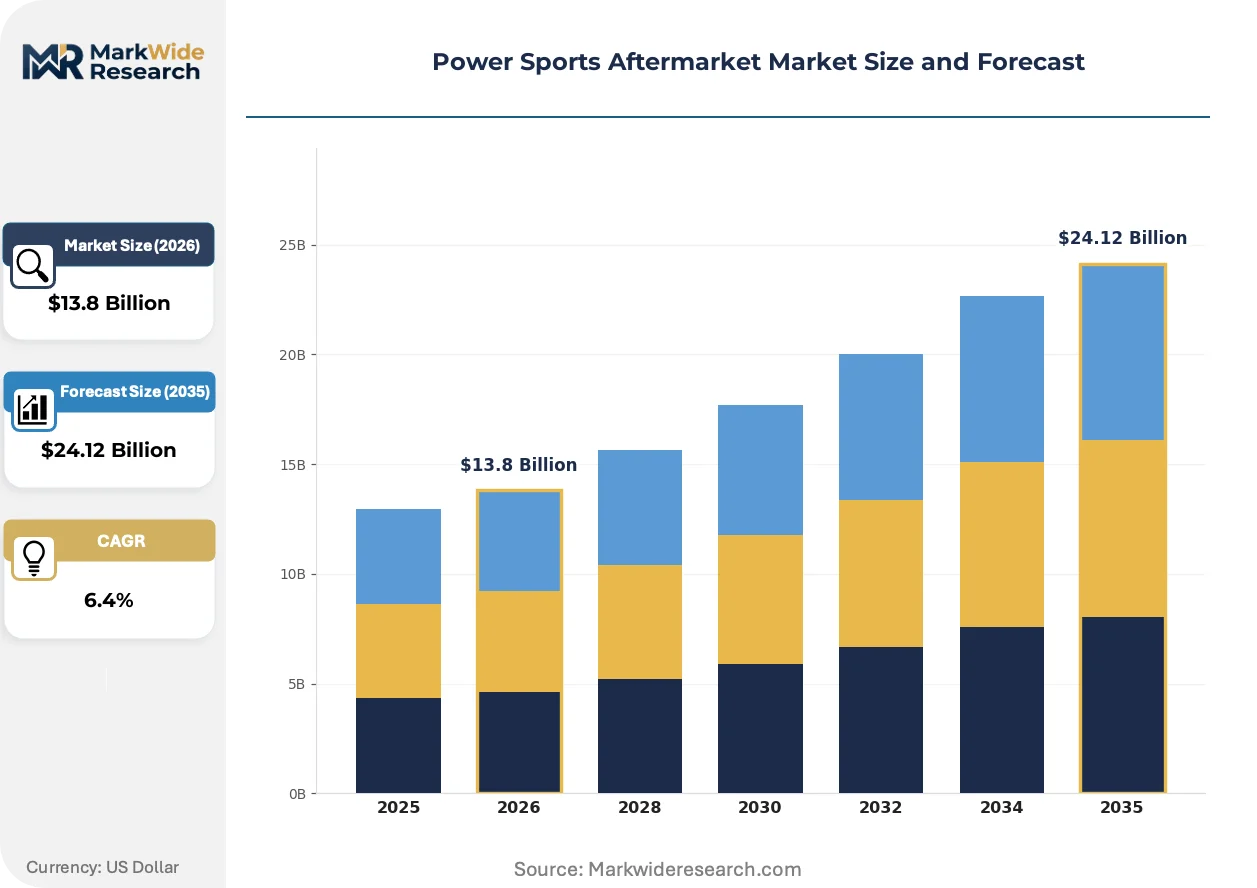
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Exhaust Systems, Suspension Kits, Lighting Accessories, Audio Systems, Performance Chips End User: Motorsports Enthusiasts, Vehicle Customizers, Dealership Service Centers, Repair Shops, Racing Teams, Hobbyists Distribution Channel: Specialty Retailers, Online Marketplaces, Direct Manufacturer Sales, Auto Parts Stores, Mobile Installers, Chain Stores Installation Type: DIY Installations, Professional Installations, Mobile Workshop Services, Authorized Service Centers |
| Companies Covered | Polaris Inc, BRP Inc, Honda Motor Co Ltd, Yamaha Motor Co Ltd, Kawasaki Heavy Industries Ltd, Harley-Davidson, Textron Inc, Arctic Cat Inc, Suzuki Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Sports Aftermarket Market Strategic Shifts & Innovations
Connected vehicle architectures and additive manufacturing are converging to reshape how aftermarket components are designed, validated, and distributed across fragmented enthusiast segments.
Carbon fiber reinforced polymer (CFRP) suspension links and protective body panels are overtaking traditional fiberglass and ABS thermoformed alternatives in high-impact applications. Desert racing teams and dune park operators in the southwestern United States are specifying woven pre-preg layups for weight reduction and crash damage tolerance. The shift is compressing replacement cycle economics and elevating repair skill requirements across authorized service networks.
EPA enforcement of evaporative emission standards is forcing reformulation of fuel system elastomers and sealing technologies for small displacement engines. Aftermarket manufacturers must now validate permeation rates below 1.5 grams per square meter per day to maintain product legality. California Air Resources Board (CARB) executive orders have become the de facto national compliance benchmark, creating a single-gateway certification bottleneck for exhaust and fuel component suppliers.
Enthusiast buyers are consolidating parts purchases around integrated build packages rather than incremental single-component transactions. Online configurators bundling suspension, wheels, and protection accessories are displacing traditional catalog-based dealer orders. This pattern concentrates most visibly in the Rocky Mountain states where seasonal preparation cycles compress decision windows ahead of spring trail openings.
Power Sports Aftermarket Market Segmentation
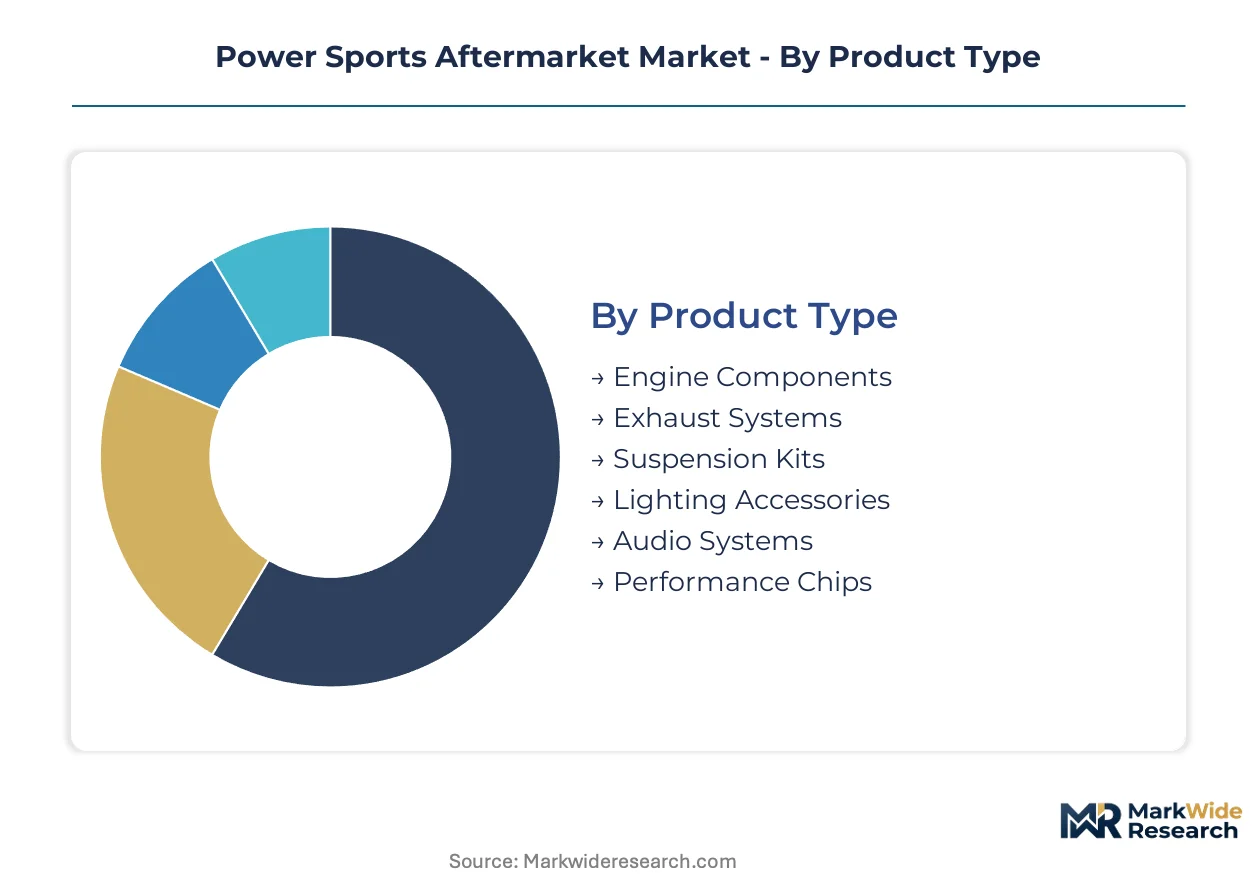
Segmentation in the Power Sports Aftermarket reveals how enthusiast spending bifurcates between wear-item replacement cycles and discretionary upgrade investments. Each dimension exposes distinct margin structures, regulatory exposure profiles, and channel control points that determine competitive positioning.
Product Type:
Customization intensity varies dramatically across this category, from mandatory emissions-compliant replacements to purely aesthetic modifications.
- Engine Components:Pistons, cylinders, and gaskets manufactured from hardened aluminum alloys and composite polymers face compressed replacement cycles under heavier recreational usage. Demand clusters in United States desert racing circuits and Rocky Mountain trail systems where thermal stress accelerates wear.
- Suspension Kits:Long-travel A-arms, coilover assemblies, and lift configurations fabricated from aircraft-grade aluminum and chromoly steel are migrating from competitive racing into consumer trail applications. Utah and Arizona OHV registration growth sustains premium kit consumption through organized event calendars.
- Exhaust Systems:Catalytic converter-equipped headers and mufflers must balance EPA evaporative emission compliance with enthusiast sound preferences.
- Lighting Accessories:LED light bars and pod systems integrating with vehicle CAN bus architectures require FCC equipment authorization.
- Audio Systems:Weather-resistant speaker enclosures and amplifier packages face moisture exposure ratings for extreme environments.
- Performance Chips:Engine control module calibrations face EPA restrictions on combustion parameter alterations.
Leading the category by volume: Engine Components. Growing fastest: Suspension Kits.
End User:
Margin capture potential tracks inversely with price sensitivity and directly with technical sophistication requirements.
- Motorsports Enthusiasts:High-frequency purchasers of performance upgrades with deep technical knowledge and brand loyalty to specific fitment systems. Colorado and California trail permit holders sustain premium parts consumption through seasonal preparation cycles.
- Vehicle Customizers:Buyers consolidating purchases around integrated build packages rather than incremental transactions, concentrating spending in Rocky Mountain states ahead of spring trail openings.
- Dealership Service Centers:Captive channels for proprietary fitment systems and warranty-compliant installations.
- Repair Shops:Independent facilities seeking EPA-compliant replacement components at volume pricing.
- Racing Teams:Professional operators specifying carbon fiber reinforced polymer components for weight reduction.
- Hobbyists:Value-conscious DIY installers utilizing online fitment configurators for real-time inventory visibility.
Highest margin capture: Motorsports Enthusiasts. Fastest volume expansion: Vehicle Customizers.
Distribution Channel:
Channel selection determines inventory risk allocation and technical support obligations across the aftermarket supply chain.
- Specialty Retailers:Staffed by enthusiast personnel providing fitment guidance and installation referrals, commanding premium positioning in Utah and Arizona desert racing corridors.
- Online Marketplaces:VIN-specific compatibility engines and real-time inventory visibility are displacing traditional catalog-based dealer orders.
- Direct Manufacturer Sales:Captive distribution networks sustaining parts availability across North American dealer channels.
- Auto Parts Stores:Generalist retailers with limited power sports technical expertise.
- Mobile Installers:On-site service providers for complex electronic integrations requiring dealer-level programming tools.
- Chain Stores:Volume-focused operators with standardized product assortments.
Dominant by transaction volume: Specialty Retailers. Expanding most quickly: Online Marketplaces.
Installation Type:
Technical complexity thresholds create structural bifurcation between self-service and professional service capture.
- DIY Installations:Plug-and-play components for value-conscious hobbyists with mechanical aptitude, limited by CAN bus integration complexity for modern vehicle architectures.
- Professional Installations:Independent shops handling complex mechanical assemblies without OEM authorization constraints.
- Mobile Workshop Services:On-location specialists serving remote trailheads and event venues in southwestern United States dune parks.
- Authorized Service Centers:Dealer-level facilities with proprietary programming tools for electronic accessory integration, commanding premium labor rates.
Largest addressable base: DIY Installations. Steepest expansion trajectory: Authorized Service Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax-advantaged enterprise zones in Arizona and Utah concentrate aftermarket distribution infrastructure near trail access corridors, creating specialized logistics hubs that serve desert racing circuits and Rocky Mountain recreation clusters.
United States
State-level OHV registration programs in Utah, Arizona, and Colorado formalize trail networks that sustain premium parts consumption through permit-based access systems. EPA small-engine emissions standards drive replacement cycles for pre-2020 ATVs requiring upgraded fuel caps and charcoal canisters. Moab and St. George anchor desert racing component demand through organized event calendars.
Canada
Provincial trail permit systems in British Columbia and Alberta sustain seasonal parts consumption through organized snowmobile and ATV federations. Transport Canada safety regulations align with NHTSA protocols for vehicle modification compliance. Calgary and Edmonton cluster aftermarket distribution serving Rocky Mountain recreational zones.
Australia
Simpson Desert and Outback track networks lack established aftermarket distribution, creating first-mover positioning for long-range fuel tank and suspension kit specialists. Australian Design Rules govern vehicle modification standards for remote touring applications. Alice Springs and Darwin anchor emerging demand for desert touring configurations.
Germany
KBA vehicle type approval requirements restrict aftermarket exhaust and engine modifications for street-legal power sports vehicles. EU F-Gas Regulation phasedown accelerates demand for retrofit air conditioning kits in side-by-side applications. Munich and Stuttgart concentrate OEM captive development centers with specialized firmware engineering talent.
Japan
METI industrial standards govern small-engine manufacturing specifications for export markets including North American aftermarket applications. JIS certification requirements for hardened aluminum alloys and composite polymers influence material sourcing patterns. Hamamatsu and Tokyo anchor engineering density for replacement component durability specifications.
Power Sports Aftermarket Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into OEM-affiliated parts operations, independent performance specialists, and mass-market distributors. Three strategic archetypes dominate: captive distribution networks leveraging proprietary fitment systems, engineering-intensive manufacturers matching original equipment specifications, and digital-first platforms bypassing traditional dealer channels. Competitive moves concentrate on M&A for fitment database assets and geographic expansion into underpenetrated trail access corridors.
Within the captive distribution tier, Polaris Inc and BRP Inc exemplify proprietary channel control strategies. Honda Motor Co Ltd anchors the engineering-density archetype. These three companies represent distinct competitive positioning vectors—captive network leverage, proprietary fitment lock-in, and specification-matching durability—without implying equivalent scale or market presence.
| Leading Market Players |
|---|
| Polaris Inc |
| BRP Inc |
| Honda Motor Co Ltd |
| Yamaha Motor Co Ltd |
| Kawasaki Heavy Industries Ltd |
| Harley-Davidson |
| Textron Inc |
| Arctic Cat Inc |
| Suzuki Motor Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up specialty distributors anchor North American aftermarket parts distribution, concentrating procurement leverage while compressing margin buffers for independent manufacturers facing palladium-rhodium cost volatility. Their ownership structure rewards inventory velocity over supplier relationship depth, reshaping how exhaust system and suspension component producers negotiate annual contract renewals.
Pricing Analysis
Premium pricing for short lead times dominates transactional dynamics, with spot inventory from Arizona and Utah warehouse clusters commanding discounts against forward-contracted seasonal shipments. Three-tier pricing structure across premium CARB-certified, standard EPA-compliant, and economy pre-Tier 3 clearance tiers reflects certification investment recovery timelines. Cost compression in catalytic converter substrates is intensifying because precious metal spot markets swing on automotive sector demand. Hobbyist DIY installers exhibit highest price sensitivity, while desert racing teams absorb premiums for crash-damage tolerance specifications.
Supply Chain Analysis
Single-source vulnerability sits with Henan and Shaanxi province magnesium alloy die-casters supplying hardened aluminum wheel and chassis components to North American distributors. Raw material flows draw from Australian bauxite refineries, Chilean copper smelters, and domestic steel mills, while component fabrication rests on Taiwanese electronics for CAN bus integration modules. Tariff exposure on Chinese-origin castings threatens margin stability for suspension kit assemblers. Distribution runs through captive dealer networks for proprietary fitment systems, with digital-first platforms capturing growing DIY share through VIN-specific compatibility engines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into catalytic converter substrate supply and captive distribution infrastructure defines the vertical-integration race, as EPA compliance costs concentrate margin capture with upstream-controlled players.
For Market Incumbents: Acquire fitment database assets and proprietary calibration software capabilities to lock in repeat purchases from Can-Am and Sea-Doo owners. Expand captive warehousing capacity in Utah and Arizona enterprise zones to compress lead times against emerging digital distributors. Channel control investments defend against direct-to-consumer platforms bypassing traditional dealer networks. For New Entrants and Emerging Players: Additive manufacturing for carbon fiber reinforced polymer suspension links offers technology-first entry into desert racing component supply where woven pre-preg layup expertise concentrates at incumbent racing teams. Target Australian Simpson Desert touring configurations with long-range fuel tank and suspension kit bundles through Alice Springs distribution partnerships. Digital fitment configurators with real-time inventory visibility anchor the go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent exhaust system manufacturers with stranded pre-EPA Tier 3 carburetor inventory in Rocky Mountain distributor warehouses. Five-to-ten-year viability hinges on CARB certification pathway execution and evaporative emission elastomer reformulation capabilities. Watch NHTSA safety recall frequency as inflection indicator for non-compliant aftermarket product removal velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Fitment Database Acquisition | Proprietary VIN-specific compatibility engines lock in repeat purchases from vehicle owners. |
| CARB Certification Investment | California Air Resources Board executive orders establish de facto national compliance benchmarks for exhaust suppliers. |
| Desert Racing Team Partnership | Carbon fiber reinforced polymer component validation through competitive racing accelerates consumer trail adoption. |
| Digital-First Distribution Buildout | Real-time inventory visibility platforms bypass traditional dealer channels capturing DIY installer margin. |
| Australian Distribution Establishment | Simpson Desert and Outback track networks lack established aftermarket infrastructure creating first-mover positioning. |
Research Approach
Multi-period observation of EPA enforcement patterns, state-level OHV registration growth, and precious metal spot market volatility anchored the trend analysis, supplemented by interviews with aftermarket distributor procurement directors, desert racing team mechanics, CARB certification consultants, suspension kit manufacturers, and dealer network operations managers. Secondary validation drew from EPA regulatory filings, NHTSA safety recall databases, state trail authority permit statistics, and customs trade records for magnesium alloy and aluminum component flows. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-weighting across product type, end user archetype, distribution channel, and installation complexity dimensions structured the analytical framework across the projection horizon. CAGRs derived from fitted growth curves applied to replacement cycle compression rates and discretionary upgrade penetration patterns. Industry-specific forecast inputs incorporated EPA Tier 3 and Tier 4 compliance timeline assumptions, plus carbon fiber reinforced polymer adoption elasticity from competitive racing into consumer applications.
Several conditions sit outside the modeled scope, including potential federal preemption of state-level modified exhaust restrictions, abrupt palladium-rhodium supply disruptions from South African mining operations, and rapid OEM software lockout of aftermarket electronic accessory integration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Rowing Machine Market
Sports Equipment
Winter Sports Equipment Market
Sports Equipment
Baseball Shoes Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Gym Bag Market
Sports Equipment
Global Sporting Goods Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Backboard Market
Sports Equipment
Agility Ladders Market
Sports Equipment
Cycling Helmet Market
Sports Equipment
Surfboard Market
Sports Equipment
Winter Sporting Goods Market