
 Global Sporting Goods Market | 2026-2036
Global Sporting Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sporting Goods Market Outlook
Aftermarket service revenue is reconfiguring profit pools across the sporting goods value chain as connected footwear and wearable-integrated apparel create recurring data and replacement opportunities. Nike leverages direct-to-consumer digital platforms to capture higher margins and first-party consumer data. Adidas sustains competitive pressure through its Speedfactory automation and localized micro-manufacturing networks. Under Armour specializes in performance analytics layering, embedding biometric tracking into compression wear to differentiate beyond commodity fabric competition.
Global sporting goods encompass engineered footwear, technical apparel, and specialized equipment designed for athletic performance, physical training, and recreational movement, typically incorporating advanced polymers, woven synthetics, and biomechanically optimized geometries to enhance endurance, protection, or precision. The primary commercial purpose spans professional competition, institutional sports programs, and individual fitness maintenance across demographic segments. Footwear commands the largest value share due to material complexity and brand premiumization, while equipment segments face margin compression from private-label alternatives. Online retail channels are accelerating fastest as virtual fitting tools and subscription replenishment models reduce friction for repeat athletic apparel purchases.
The US Consumer Product Safety Commission enforces flammability and chemical exposure standards for athletic textiles, while REACH in Europe restricts hazardous substances in synthetic dyes and rubber compounds, elevating compliance costs for cross-border suppliers. China's GB standards and SAMR oversight mandate domestic testing for imported sporting equipment, creating non-tariff barriers that favor local production partnerships. ISO performance certification for protective gear increasingly determines institutional procurement eligibility in team sports and educational programs. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and North America that will reshape material sourcing decisions and reverse logistics infrastructure.
Market Dynamics
Hybrid workout models are fragmenting traditional retail channels as fitness enthusiasts demand seamless integration between digital coaching platforms and physical equipment ecosystems, forcing manufacturers to rebuild distribution architectures around direct engagement.
Growth Catalysts
- EU Green Deal textile mandates:Circular production protocols are compelling synthetic material reformulation across European supply chains, opening premium positioning for compliant manufacturers.
- Home-based training equipment:Compact connected devices are capturing space-constrained urban households in China and Germany, expanding addressable market beyond commercial gym contracts.
- Biomechanical optimization:Advanced polymer research is enabling mass-customized footwear geometries that adapt to individual gait patterns through 3D-printed midsole lattices.
Market Restraints
- Petrochemical input volatility:EVA foam and synthetic rubber costs fluctuate with crude oil derivatives, compressing margins for mid-tier athletic footwear producers.
- REACH compliance burden:European chemical exposure standards require extensive third-party testing for dyes and adhesives, extending product development timelines by 4-6 months.
- Natural fiber substitution:Merino wool and organic cotton blends are displacing synthetic performance fabrics in premium outdoor segments, threatening petroleum-based textile demand.
Strategic Opportunities
- India's institutional sports procurement:National fitness campaigns and school infrastructure programs are creating bulk equipment contracts previously dominated by informal local suppliers.
- Extended producer responsibility frameworks:EU and North American take-back mandates are enabling reverse logistics revenue streams through certified refurbishment and material recovery services.
- Wearable-apparel convergence:Embedded biometric sensors in compression garments are generating recurring data subscription revenue beyond one-time hardware sales.
Industry Challenges
- ISO 20345 certification timelines:Protective footwear testing protocols for institutional procurement eligibility require 12-18 month validation cycles, delaying market entry for new suppliers.
- Legacy ERP integration:Direct-to-consumer digital platforms must synchronize with existing wholesale inventory systems, creating data architecture complexity for established manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sporting Goods Market |
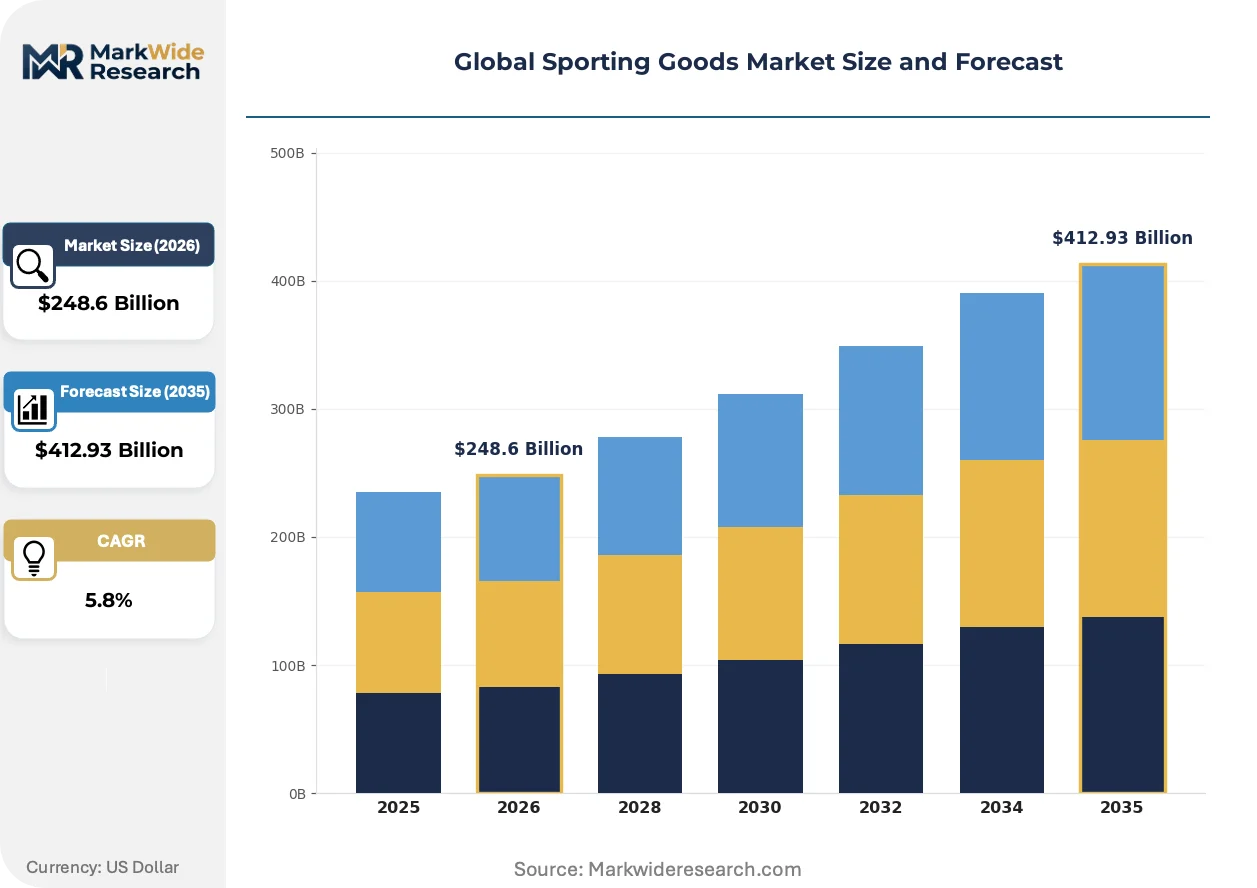
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $412.93 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footwear, Apparel, Equipment, Accessories End User: Professional Athletes, Fitness Enthusiasts, Casual Users, Kids Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale Price Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | Nike, Inc., Adidas AG, Puma SE, Under Armour, Inc., Decathlon SA, Anta Sports, ASICS Corporation, Amer Sports, Lululemon Athletica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sporting Goods Market Strategic Shifts
Digital fabrication and biomaterial science are converging to dismantle century-old manufacturing paradigms in athletic equipment, replacing standardized mass production with adaptive, localized, and regenerative production systems.
Generative design algorithms paired with selective laser sintering are rendering obsolete traditional injection-molded midsole tooling. Marathon runners and professional triathletes in Japan and the Netherlands are adopting lattice-structured cushioning at 3x the rate of recreational users. This shift is collapsing minimum order quantities and compressing new product introduction cycles from 18 months to 6 weeks.
REACH authorization requirements for per- and polyfluoroalkyl substances are eliminating water-repellent coatings from European outdoor apparel lines. Manufacturers are pivoting to bio-based membrane alternatives or accepting reduced performance specifications. The trail running and mountaineering segments face the steepest reformulation costs, with several suppliers exiting waterproof categories entirely.
Athletic departments and corporate wellness programs are unbundling equipment procurement from maintenance contracts, treating footwear and wearables as consumable subscriptions rather than capital expenditures. University systems in Australia and Brazil are piloting per-athlete monthly fees covering replacement, cleaning, and performance analytics. This reclassification is redirecting budget authority from facilities managers to chief wellness officers and data analytics teams.
Global Sporting Goods Market Segmentation
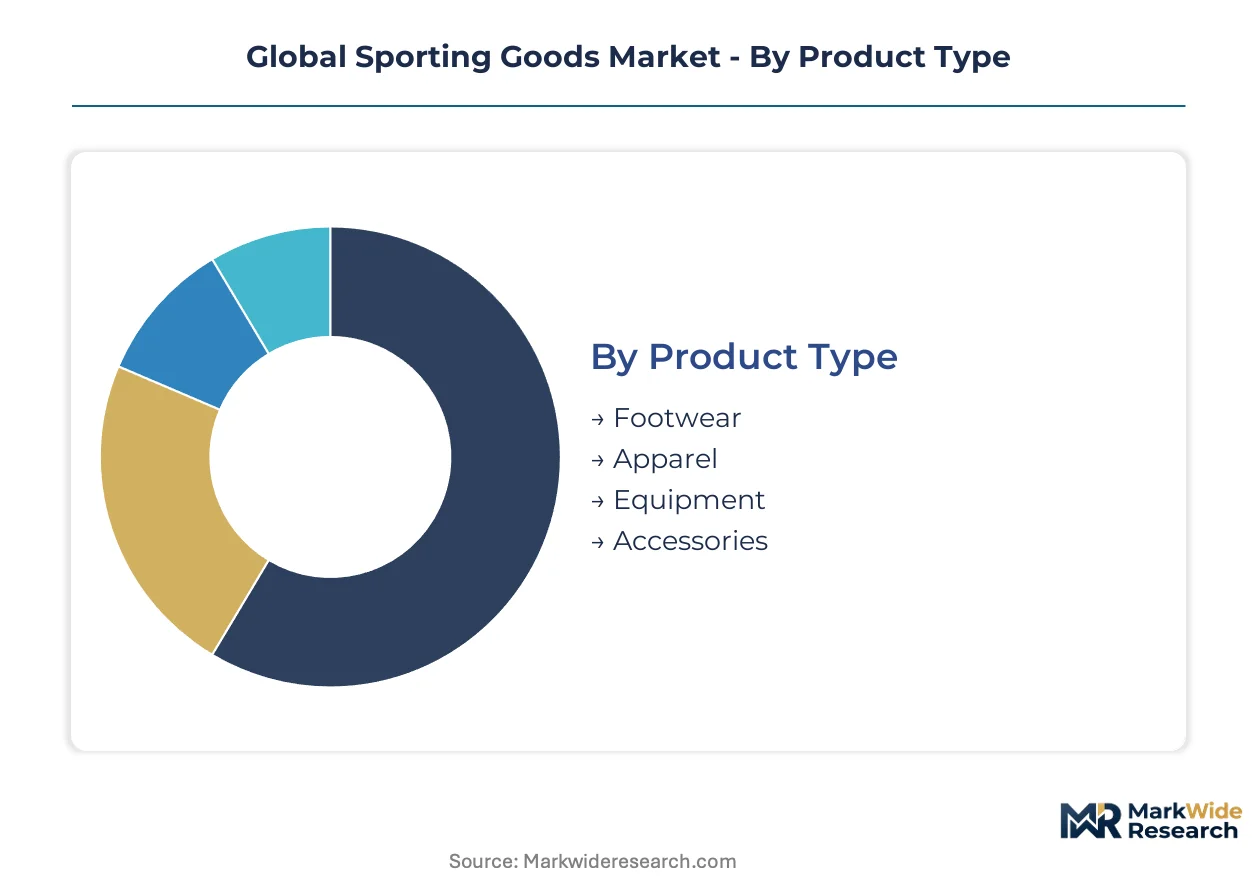
Sporting goods manufacturers deploy granular segmentation to align material specifications, channel economics, and pricing architecture with divergent performance requirements across athlete cohorts. Category boundaries blur as connected footwear and biometric apparel force traditional product taxonomies to accommodate hybrid functionality.
Product Type:
Mature segments dominate revenue concentration while emerging categories exploit biomechanical customization and circular material science.
- Footwear:Engineered polymers and 3D-printed midsole lattices enable mass-customized gait adaptation. Demand concentrates among marathon runners in Japan and the Netherlands adopting lattice-structured cushioning at triple the rate of recreational users, driven by generative design algorithms collapsing product introduction cycles from 18 months to 6 weeks.
- Apparel:Technical textiles incorporate woven synthetics and bio-based membrane alternatives replacing per- and polyfluoroalkyl substance coatings banned under REACH authorization. Trail running and mountaineering segments in Europe face steepest reformulation costs as several suppliers exit waterproof categories entirely.
- Equipment:Compact connected devices capture space-constrained urban households in China and Germany, expanding addressable market beyond commercial gym contracts.
- Accessories:Embedded biometric sensors generate recurring data subscription revenue beyond one-time hardware sales, with university systems in Australia piloting per-athlete monthly fees.
Footwear retains volume leadership; Accessories holds the steepest expansion curve.
End User:
Application intensity separates high-frequency professional users from intermittent recreational purchasers with divergent replacement cycles and margin sensitivity.
- Professional Athletes:Institutional procurement eligibility under ISO performance certification determines team sports and educational program access. Athletic departments in Australia and Brazil unbundle equipment from maintenance contracts, treating footwear as consumable subscriptions.
- Fitness Enthusiasts:Home-based training and hybrid workout models gain traction as this cohort expands fastest, demanding seamless integration between digital coaching platforms and physical equipment ecosystems.
- Casual Users:Virtual fitting tools and subscription replenishment models reduce friction for repeat athletic apparel purchases through online retail channels.
- Kids:School infrastructure programs in India create bulk equipment contracts previously dominated by informal local suppliers under national fitness campaigns.
Professional Athletes command premium pricing power; Fitness Enthusiasts climbs fastest in absolute user additions.
Distribution Channel:
Channel economics fragment as direct-to-consumer digital platforms capture higher margins and first-party consumer data while legacy wholesale relationships require ERP synchronization.
- Online Retail:Direct-to-consumer digital platforms accelerate fastest as manufacturers rebuild distribution architectures around direct engagement, though legacy ERP integration creates data architecture complexity.
- Specialty Stores:Biomechanical fitting services and localized micro-manufacturing networks sustain competitive positioning through Speedfactory automation and technical consultation.
- Supermarkets:Private-label alternatives compress margins in equipment segments, displacing branded offerings in price-sensitive casual user categories.
- Wholesale:Institutional procurement through athletic departments and corporate wellness programs redirects budget authority from facilities managers to chief wellness officers.
Online Retail captures margin expansion; Specialty Stores defends positioning through technical service differentiation.
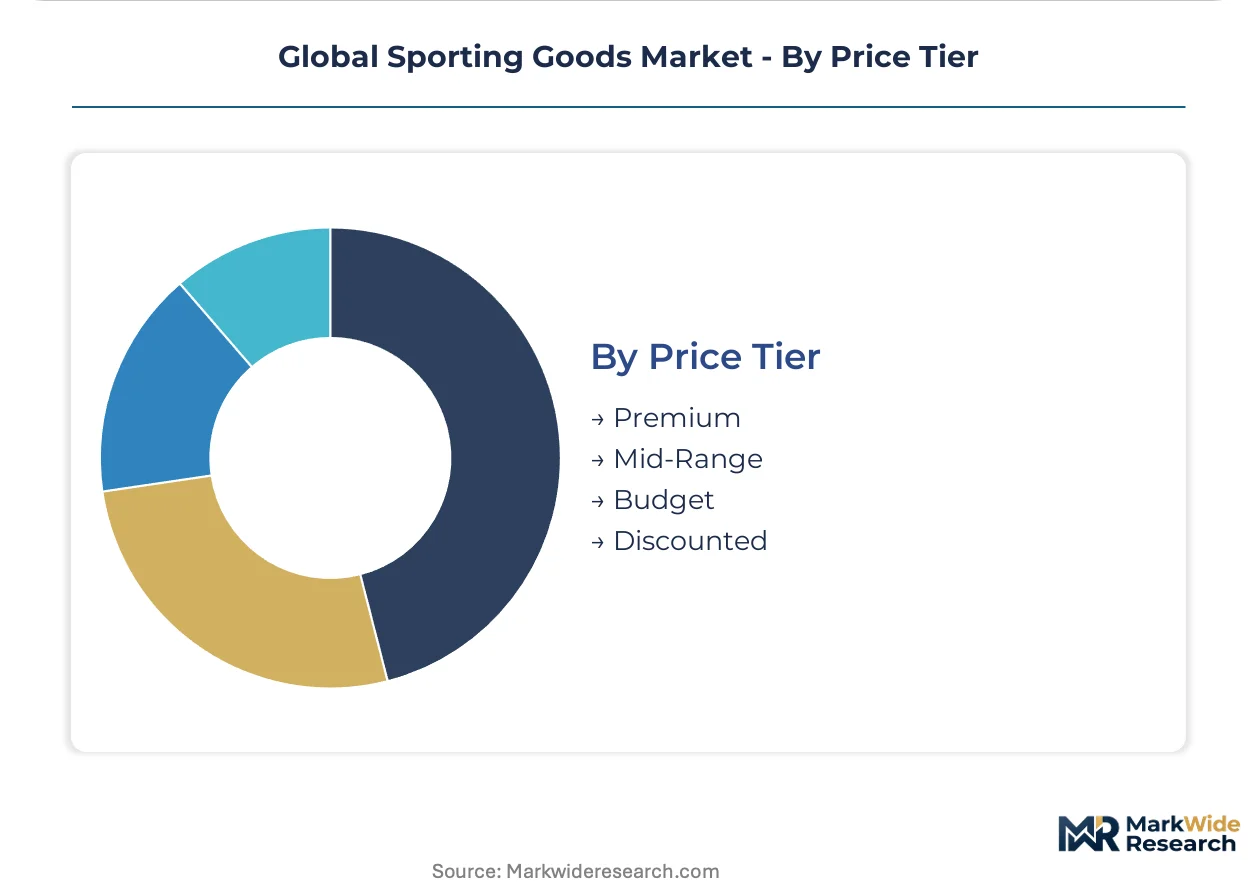
Price Tier:
Cost stratification aligns material complexity and certification grade with end-user performance requirements and replacement frequency.
- Premium:Advanced polymer research and ISO 20345 certification timelines for protective footwear require 12-18 month validation cycles, creating procurement barriers for new suppliers.
- Mid-Range:EVA foam and synthetic rubber input costs fluctuate with crude oil derivatives, compressing margins for producers caught between premium innovation and budget private-label competition.
- Budget:Merino wool and organic cotton blends displace synthetic performance fabrics in premium outdoor segments, though petroleum-based textiles retain cost advantage at volume.
- Discounted:Extended producer responsibility frameworks in the EU and North America reshape material sourcing decisions, with certified refurbishment and material recovery services enabling reverse logistics revenue streams.
Premium commands brand premiumization returns; Discounted faces structural pressure from circular economy compliance costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply chains for engineered athletic footwear and technical apparel concentrate in China, Germany, and the United States, with secondary manufacturing nodes emerging in Vietnam and Indonesia as labor costs and tariff exposure reshape sourcing decisions.
United States
Nike and Under Armour anchor domestic demand through direct-to-consumer digital platforms capturing first-party data. The Consumer Product Safety Commission enforces flammability standards for athletic textiles. Oregon and Maryland host concentrated R&D clusters developing biomechanical optimization algorithms for mass-customized footwear geometries.
Germany
Adidas sustains competitive pressure through Speedfactory automation and localized micro-manufacturing networks. REACH authorization requirements for per- and polyfluoroalkyl substances eliminate water-repellent coatings from outdoor apparel lines. Bavaria and Baden-Württemberg concentrate advanced polymer research facilities enabling 3D-printed midsole lattice production.
China
Anta Sports and domestic rivals capture market share through localized design and Olympic sponsorship strategies. GB standards and SAMR oversight mandate domestic testing for imported sporting equipment, creating non-tariff barriers favoring local production partnerships. Fujian and Guangdong provinces dominate manufacturing clusters for synthetic rubber compounds and woven technical textiles.
Japan
METI promotes advanced material science partnerships between athletic brands and chemical conglomerates. JIS standards for protective gear determine institutional procurement eligibility in school sports programs. Tokyo and Osaka metropolitan areas concentrate marathon runner demand adopting lattice-structured cushioning at triple the rate of recreational users.
India
National fitness campaigns and school infrastructure programs create bulk equipment contracts previously dominated by informal local suppliers. BIS certification requirements for imported sporting goods elevate compliance barriers for foreign entrants. Maharashtra and Karnataka host emerging manufacturing zones targeting domestic procurement under the PLI scheme.
Global Sporting Goods Market Competitive Environment
Vertically integrated sportswear conglomerates and specialized performance-technology developers split the market between scale-driven brand ecosystems and niche biomechanical innovation. Consolidation pressure intensifies as direct-to-consumer platforms disintermediate wholesale relationships. Three archetypes dominate: heritage athletic brands with Olympic sponsorship assets, digitally native vertical retailers, and materials-science specialists. Capacity expansion in Southeast Asian manufacturing zones and strategic partnerships with generative design software vendors constitute the dominant competitive moves.
Among heritage athletic conglomerates, Nike, Inc. and Adidas AG occupy positions exemplifying the scale-archetype, while Anta Sports represents the localized-design challenger model gaining traction through domestic Olympic partnerships. These three entities anchor the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| Puma SE |
| Under Armour, Inc. |
| Decathlon SA |
| Anta Sports |
| ASICS Corporation |
| Amer Sports |
| Lululemon Athletica |
| Others |
Value Chain & Pricing Dynamics
Petrochemical input volatility determines both pricing tier spreads and supply chain shape across the sporting goods value chain, compressing mid-range footwear margins while forcing manufacturers toward backward integration into synthetic rubber compounding or bio-based material alternatives to escape crude oil derivative exposure.
Pricing Analysis
REACH authorization requirements dictate the pricing tier structure across European markets, separating premium ISO-certified protective footwear from mid-range EVA foam products and budget private-label alternatives. Price differentiation rests on certification grade and vertical integration depth, with biomechanical customization commanding brand premiumization. Cost compression in the mid-tier is intensifying because synthetic rubber and EVA foam costs fluctuate with crude oil derivatives. Casual users exhibit the highest price sensitivity, while professional athletes and institutional buyers prioritize performance certification over unit economics.
Supply Chain Analysis
Crude oil derivatives and advanced polymer feedstocks anchor upstream material sourcing for engineered footwear and technical apparel production. Manufacturing concentrates in China, Vietnam, and Indonesia, drawing from synthetic rubber compounds, woven technical textiles, and 3D-printing resin inputs. Single-source vulnerability persists around specialized polymer formulations and generative design software licensing. Distribution runs through direct-to-consumer digital platforms, specialty retail with biomechanical fitting services, and institutional procurement channels serving athletic departments and corporate wellness programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sporting goods market sits at a technology-led disruption inflection as generative design algorithms and 3D-printed midsole lattices collapse product development cycles from 18 months to 6 weeks, rendering traditional injection-molded tooling obsolete.
For Market Incumbents: Harden supply chain resilience through backward integration into synthetic rubber compounding and localized micro-manufacturing networks that reduce tariff exposure and petrochemical input volatility. Deepen certification moats around ISO 20345 protective footwear validation cycles that delay competitor market entry by 12-18 months. Prioritize direct-to-consumer platform investments to capture first-party biometric data and subscription replenishment revenue streams. For New Entrants and Emerging Players: Establish a beachhead in India's institutional sports procurement segment, where national fitness campaigns and school infrastructure programs are displacing informal local suppliers with bulk equipment contracts. Target the accessories category for wearable-apparel convergence, embedding biometric sensors in compression garments to generate recurring data subscription revenue beyond one-time hardware sales. Pursue white-label partnerships with university systems piloting per-athlete monthly fee models in Australia and Brazil. For Investors and Strategic Acquirers: The market sits at an early-maturity phase that favors materials-science specialists with captive polymer research capabilities and generative design software partnerships. Long-term viability over the next decade hinges on circular economy compliance and reverse logistics infrastructure for extended producer responsibility frameworks. Watch for inflection signals in EU Green Deal textile mandate enforcement timelines and REACH authorization expansion to per- and polyfluoroalkyl substance replacements.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Nike and Under Armour capture first-party biometric data and subscription revenue through owned digital channels. |
| Speedfactory Automation Expansion | Adidas sustains competitive pressure through localized micro-manufacturing networks reducing lead times. |
| Biometric Sensor Integration | Embedded sensors in compression garments generate recurring data subscription revenue beyond hardware sales. |
| Circular Production Protocol Adoption | EU Green Deal textile mandates compel synthetic material reformulation and certified refurbishment services. |
| Generative Design Algorithm Deployment | 3D-printed midsole lattices enable mass-customized gait adaptation collapsing product cycles to 6 weeks. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with footwear brand managers, category buyers at sporting goods retailers, supply chain planners, and biomechanical R&D directors; and secondary validation through customs and trade data, SEC 10-K filings, EU ECHA REACH authorization databases, and athletic department procurement records. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against retail audit metrics and institutional contract disclosures.
Forecast inputs considered product type segmentation across footwear, apparel, equipment, and accessories; end-user stratification by professional, fitness enthusiast, casual, and kids categories; distribution channel evolution through online retail, specialty stores, supermarkets, and wholesale; and price tier dynamics spanning premium, mid-range, budget, and discounted levels. CAGRs were derived from regression analysis of historical shipment volumes against macroeconomic indicators and regulatory enforcement timelines, incorporating petrochemical price indices and synthetic material substitution rates.
Stress conditions across crude oil derivative volatility, REACH compliance timeline extensions, and tariff exposure on Southeast Asian manufacturing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around hybrid workout model adoption rates and circular economy mandate implementation schedules. Material shifts in EU extended producer responsibility framework enforcement or breakthrough bio-based membrane performance parity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Squash Equipment Market
Sports Equipment
France Artificial Turf Market
Sports Equipment
Bowling Lane Panels Market
Sports Equipment
Skydiving Equipment Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Football Equipment Market
Sports Equipment
Sports Equipment Market
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Rowing Machine Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
Smart Boxing Gear Market