
 Winter Sports Equipment Market | 2026-2036
Winter Sports Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Winter Sports Equipment Market Outlook
Carbon fiber is hardening its grip on premium ski and snowboard construction as manufacturers trade heavier fiberglass laminates for lighter, torsional-stiff prepregs. Salomon leverages its Chamonix engineering center to refine automated layup processes that cut waste. Atomic anchors its Austrian production with captive carbon weaving partnerships that insulate margin pools from resin price swings. Fischer Sports competes through wood-core hybrid architectures that blend ash and poplar with carbon stringers for dampening.
Winter sports equipment encompasses engineered goods designed for snow and ice locomotion, typically featuring laminated composite shells with steel edges, P-tex bases, and binding interfaces calibrated to DIN release standards. Skis and snowboards dominate value generation, with carbon fiber variants commanding premium positioning as athletes and affluent recreational users prioritize reduced swing weight. The distribution channel structure tilts toward specialty stores for fitting-intensive categories like boots and bindings, while online retail captures replacement accessories and apparel where sizing tolerance widens.
The EU Green Deal and REACH frameworks constrain volatile organic compound emissions in Austrian and French manufacturing zones, compelling resin system reformulation. The EPA oversees perfluorinated compound phase-outs affecting base material glide treatments in US-bound products. ASTM F1063 and ISO 9462 binding standards govern release mechanics across North American and European markets, creating compliance cost barriers for new entrants. Stakeholders must track bio-resin scale-up timelines and regional enforcement variance to calibrate sourcing footprints against certification lag.
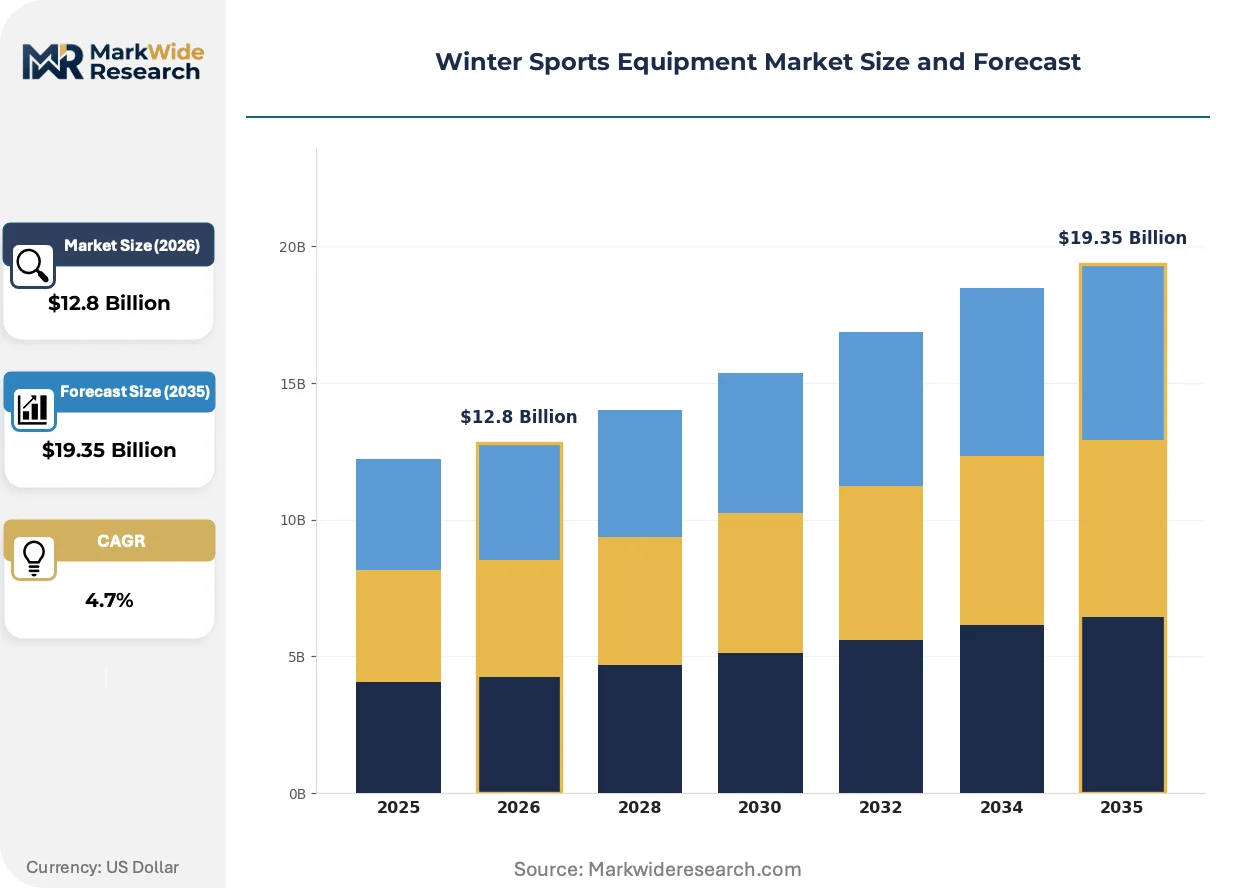
Market Dynamics
Carbon fiber prepreg adoption is compressing traditional fiberglass supply chains as alpine manufacturers retool layup automation to meet EU F-Gas Regulation timelines for solvent-free resin systems.
Growth Catalysts
- Alpine tourism infrastructure renewal:Austrian and French resorts are modernizing rental fleets with lighter composite equipment to reduce operational fuel costs for grooming fleets.
- F-Gas Regulation compliance:The EU mandate on fluorinated greenhouse gases is redirecting R&D budgets toward bio-based binding adhesives and water-based base treatments.
- Automated fiber placement:Robotics-enabled tape laying is cutting material scrap rates in Chamonix and Innsbruck production facilities.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations are squeezing margin pools for composite laminators dependent on bisphenol-A derived systems.
- Tyrol supplier concentration:Austrian carbon weaving capacity bottlenecks are creating 14-18 week lead times for premium ski manufacturers.
- REACH substance restrictions:ECHA candidate list updates on isocyanate hardeners are forcing reformulation of polyurethane core bonding agents.
Strategic Opportunities
- Nordic backcountry expansion:Norway and Sweden's hut-to-hut touring networks are driving demand for ultralight randonee bindings and collapsible poles.
- Digital fitting platforms:3D foot scanning integrated with CNC boot molding is opening direct-to-consumer channels bypassing specialty retail.
- CSRD reporting alignment:The EU Corporate Sustainability Reporting Directive is creating first-mover advantage for manufacturers with verified Scope 3 carbon accounting.
Industry Challenges
- Composite repair technician scarcity:Ski service departments lack trained personnel for carbon fiber delamination and edge replacement.
- DIN certification backlog:ISO 9462 binding release testing queues at TÜV and SGS facilities are extending product launch timelines.
- Legacy P-tex glide treatment phase-out:Perfluorinated compound elimination is forcing reformulation of base wax compatibility across rental fleet maintenance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Winter Sports Equipment Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skis, Snowboards, Snowshoes, Ice Skates Material: Carbon Fiber, Aluminum, Polypropylene, Wood End User: Athletes, Recreational Users, Professional Teams, Tourists Distribution Channel: Online Retail, Specialty Stores, Sports Outlets, Wholesale |
| Companies Covered | K2 Sports, Salomon, Rossignol Group, Head NV, Burton Snowboards, Amer Sports, Atomic, Black Diamond Equipment, Fischer Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Winter Sports Equipment Market Strategic Shifts
Equipment manufacturing is pivoting from petroleum-derived composites toward bio-sourced architectures as regulatory chemistry constraints tighten and athlete performance demands intensify.
Bio-based flax fiber hybrids are expanding into structural ski layers as manufacturers blend cellulose reinforcements with carbon stringers to maintain torsional rigidity while cutting cradle-to-gate emissions. Racing teams and high-mileage recreational users are piloting these laminates in World Cup and regional circuits. The material substitution is expanding into premium price tiers previously reserved for aerospace-grade prepregs.
The EU F-Gas Regulation is banning hydrofluorocarbon blowing agents in ski boot liner foams, compelling Austrian molders to adopt CO2-based physical expansion processes. Manufacturers in Kufstein and Montebelluna are retooling injection systems to meet the 2027 phase-down milestones. Alpine racing boot suppliers face the steepest compliance curves given thermal insulation performance requirements.
Rental fleet operators are consolidating procurement through seasonal lease-to-own structures that shift inventory risk to manufacturers. French and Swiss resort groups are bundling equipment, maintenance, and digital booking platforms into multi-year service agreements. This contracting evolution is most advanced in the Portes du Soleil and Arlberg regional networks where vertical integration between lift operators and equipment suppliers has compressed vendor counts.
Winter Sports Equipment Market Segmentation
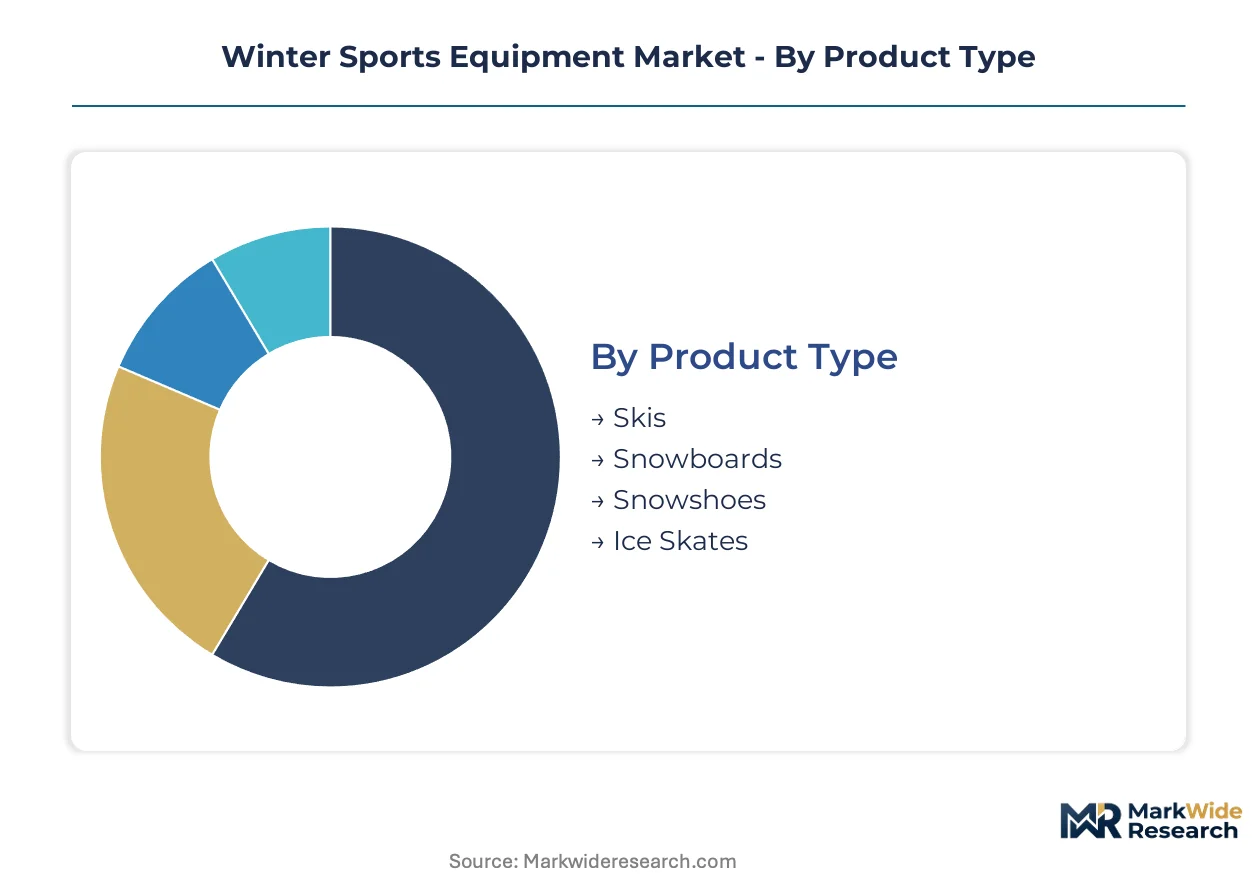
Equipment segmentation in winter sports tracks divergent performance requirements across competitive and leisure applications. Material specifications and distribution economics create distinct margin architectures that manufacturers calibrate against regional regulatory timelines and resort procurement cycles.
Product Type:
Structural engineering demands separate alpine disciplines by load-bearing geometry and binding interface standards.
- Skis:Laminated composite shells integrate steel edges, P-tex bases, and DIN-standard binding plates. Austrian Tyrol manufacturers concentrate production for rental fleet modernization across French and Swiss alpine zones.
- Snowboards:Directional and twin-tip geometries employ fiberglass or carbon prepregs over wood cores with sidewall construction. North American terrain parks and Japanese powder tourism drive specification diversity.
- Snowshoes:Aluminum or composite decking with crampon traction systems serves backcountry access and Nordic hut-to-hut networks.
- Ice Skates:Hardened steel blades mounted to thermoplastic or leather boots address figure skating, hockey, and recreational pond skating segments.
Skis lead on scale; snowboards lead on momentum.
Material:
Raw material selection determines weight-to-stiffness ratios and regulatory compliance pathways across EU manufacturing zones.
- Carbon Fiber:Aerospace-grade prepregs deliver torsional rigidity at reduced swing weight for racing and premium recreational tiers. REACH-compliant resin systems from Austrian suppliers face ECHA scrutiny on isocyanate hardeners.
- Aluminum:Extruded and cast alloys form ski binding components, snowboard edges, and snowshoe frames. Kufstein molders source secondary billet for boot hardware to manage epoxy price volatility exposure.
- Polypropylene:Injection-molded cores and boot liners employ CO2-based physical expansion to meet EU F-Gas Regulation phase-down milestones for hydrofluorocarbon blowing agents.
- Wood:Ash and poplar cores with carbon stringer reinforcement provide vibration dampening for Fischer Sports hybrid architectures in Austrian production clusters.
Carbon fiber commands margin premiums; polypropylene faces the steepest reformulation compliance curves.
End User:
Performance calibration and purchase frequency diverge sharply between institutional procurement and individual replacement cycles.
- Athletes:FIS-compliant equipment with certified release mechanics and World Cup circuit validation requirements. DIN certification backlogs at TÜV and SGS facilities extend product launch timelines for this segment.
- Recreational Users:Weekend and seasonal skiers prioritizing rental fleet access over ownership. Portes du Soleil and Arlberg resort networks consolidate procurement through lease-to-own structures.
- Professional Teams:National ski federations and sponsored athletes with custom specification contracts and direct manufacturer relationships.
- Tourists:Destination skiers dependent on resort rental inventory with standardized binding adjustments and fleet maintenance protocols.
Recreational users generate volume concentration; athletes drive specification premiums.
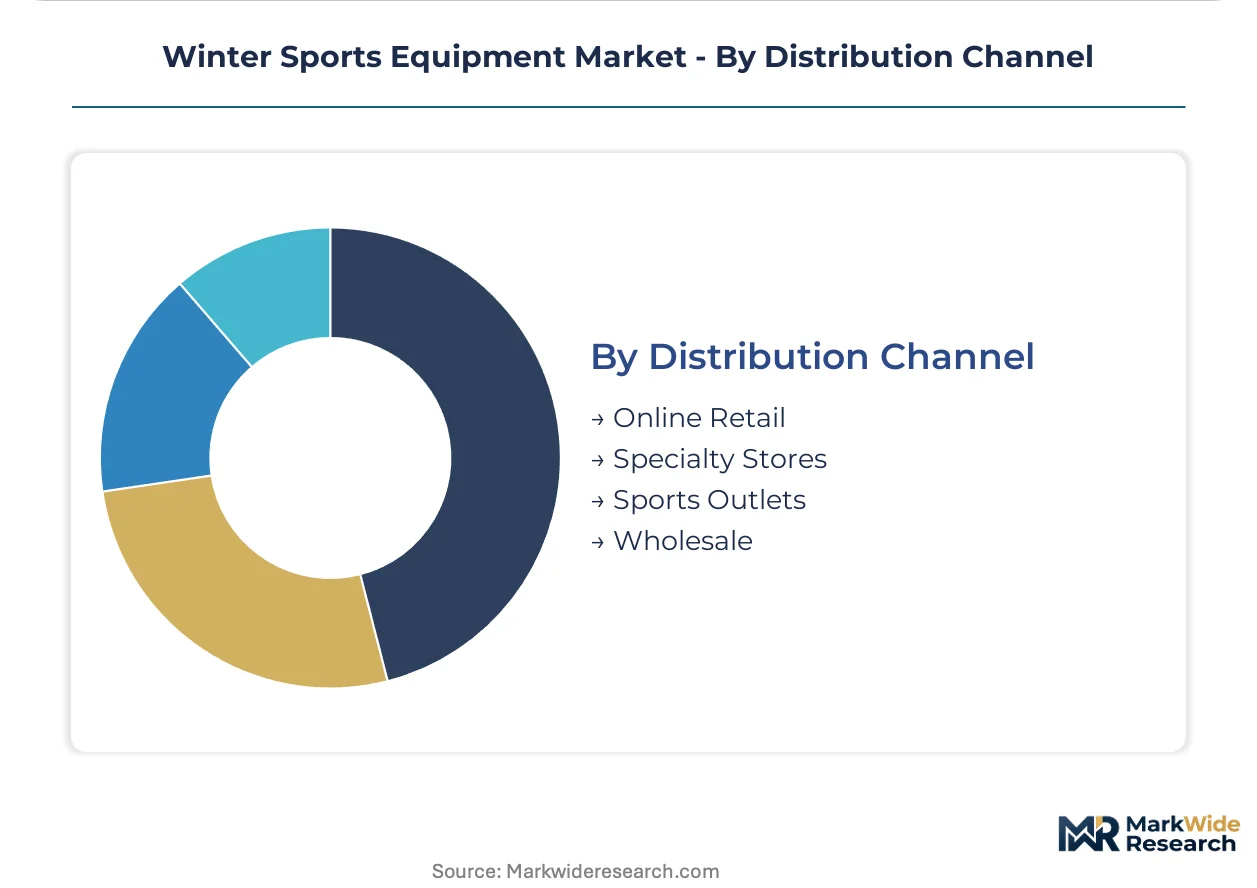
Distribution Channel:
Channel economics reflect fitting complexity, inventory carrying costs, and digital penetration variance across equipment categories.
- Online Retail:Replacement accessories, apparel, and pre-sized equipment where tolerance widens. 3D foot scanning integration is opening direct-to-consumer boot channels bypassing specialty fitting.
- Specialty Stores:Boot and binding fitting with certified technicians and DIN release calibration. Composite repair technician scarcity constrains service capacity for carbon fiber delamination.
- Sports Outlets:Mid-tier equipment and seasonal promotions targeting casual participants in urban proximity to mountain access.
- Wholesale:Resort fleet procurement and regional distributor networks serving rental operations across alpine tourism zones.
Specialty stores anchor fitting-intensive revenue; online retail captures replacement velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Austrian Tyrol manufacturing cluster anchors European winter sports equipment production, with Innsbruck and Kufstein serving as primary hubs for composite ski fabrication and binding assembly. Alpine tourism infrastructure across Austria, France, and Switzerland drives fleet renewal cycles, while North American terrain parks and Japanese powder tourism diversify specification requirements. Regulatory pressure from the EU F-Gas Regulation and EPA perfluorinated compound restrictions is reshaping material sourcing footprints across all major production zones.
United States
Colorado and Utah resort networks drive rental fleet modernization with lightweight composite equipment to reduce grooming fuel consumption. The EPA oversees perfluorinated compound phase-outs affecting base material glide treatments for domestic-bound products. Denver-Boulder corridor distributors serve as consolidation points for Rocky Mountain and Pacific Northwest retail channels.
Austria
Tyrol region manufacturers concentrate carbon fiber prepreg production for premium ski and snowboard tiers serving alpine tourism zones. The EU F-Gas Regulation mandates hydrofluorocarbon blowing agent elimination from ski boot liner foams by 2027, compelling Kufstein molders to adopt CO2-based physical expansion. Innsbruck engineering centers refine automated fiber placement to cut material scrap rates.
France
Chamonix engineering facilities develop automated layup processes for carbon fiber ski construction targeting competitive and recreational segments. REACH framework constraints on isocyanate hardeners force polyurethane core bonding agent reformulation across Auvergne-Rhône-Alpes manufacturing zones. Portes du Soleil resort networks consolidate procurement through multi-year lease-to-own equipment service agreements.
Japan
Hokkaido powder tourism and Nagano region alpine resorts drive demand for specialized powder ski geometries and backcountry touring equipment. METI industrial standards govern binding release mechanics alongside ISO 9462 certification requirements. Domestic manufacturers face import competition from Austrian and North American premium tiers while serving Asia-Pacific distribution hubs.
Switzerland
Swissmedic regulatory alignment with EU MDR frameworks streamlines equipment certification for alpine racing and recreational categories. Zürich and Geneva distribution nodes serve as logistics consolidation points for Central European rental fleet procurement. Arlberg regional networks advance vertical integration between lift operators and equipment suppliers, compressing vendor counts across Swiss-Austrian border zones.
Winter Sports Equipment Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers retool Austrian and French production facilities for automated fiber placement and bio-resin system scale-up. The vendor base concentrates around three tiers: integrated alpine equipment conglomerates with captive carbon weaving capacity, specialized ski and snowboard fabricators focused on premium recreational segments, and regional boot and binding specialists serving rental fleet procurement. M&A activity and strategic partnerships represent the primary competitive moves, with manufacturers acquiring automated layup technology providers and forming captive resin supply agreements to insulate margin pools from petrochemical price volatility.
Within the integrated equipment tier, Amer Sports and Rossignol Group exemplify multi-brand portfolio strategies spanning skis, snowboards, boots, and bindings across competitive and recreational price tiers. Among specialized fabricators, Atomic anchors Austrian production with Tyrol-based carbon weaving partnerships, while Fischer Sports occupies a position emphasizing wood-core hybrid architectures that blend traditional materials with composite reinforcement. Burton Snowboards represents the North American terrain park and freestyle specialization archetype, with distribution structures calibrated to Pacific Northwest and Rocky Mountain retail networks.
| Leading Market Players |
|---|
| K2 Sports |
| Salomon |
| Rossignol Group |
| Head NV |
| Burton Snowboards |
| Amer Sports |
| Atomic |
| Black Diamond Equipment |
| Fischer Sports |
| Others |
Value Chain & Pricing Dynamics
Epoxy resin price indices cascading from petrochemical feedstock volatility compress margin pools for Austrian and French composite laminators, forcing tiered pricing structures that separate carbon fiber prepregs from fiberglass alternatives across premium and rental fleet procurement channels.
Pricing Analysis
Input-cost pass-through from bisphenol-A derived epoxy systems stratifies pricing across premium, standard, and economy tiers. Certification grade for DIN-standard binding interfaces and carbon fiber content percentage serve as primary price differentiation drivers. Pricing pressure intensifies in standard tiers as Tyrol weaving capacity bottlenecks extend lead times for premium manufacturers. Rental fleet operators exhibit highest price sensitivity, while World Cup circuit athletes prioritize performance specifications over unit cost.
Supply Chain Analysis
Alpine freight corridors linking Austrian Tyrol manufacturing clusters to French and Swiss resort networks absorb elevated logistics costs from seasonal demand surges. Raw material sourcing draws from German petrochemical suppliers for epoxy resins, Japanese carbon fiber producers for aerospace-grade prepregs, and domestic Austrian timber operations for ash and poplar cores. Single-source vulnerability concentrates in Tyrol carbon weaving partnerships, where captive supply agreements insulate integrated manufacturers from spot market volatility. Distribution runs through specialty retail channels for fitting-intensive categories, with wholesale networks serving consolidated resort procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Winter Sports Equipment Market represents a late-cycle quality story as recreational users migrate toward lighter composite specifications and alpine tourism infrastructure renewal sustains replacement demand.
For Market Incumbents: Deepen captive resin supply agreements with Austrian petrochemical processors to insulate margin pools from feedstock volatility. Expand automated fiber placement capacity in Innsbruck engineering centers before ECHA isocyanate hardener restrictions tighten. Backward integration into carbon weaving partnerships remains essential as Tyrol supplier concentration creates procurement bottlenecks for non-integrated competitors. For New Entrants and Emerging Players: Begin with Nordic backcountry segments in Norway and Sweden, where hut-to-hut touring networks drive ultralight randonee binding demand with limited incumbent specialization. Digital fitting platforms integrated with CNC boot molding offer direct-to-consumer penetration without specialty retail infrastructure. White-space exists in composite repair technician training services, addressing scarcity that constrains carbon fiber delamination service capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with automated layup technology providers serving Chamonix and Innsbruck production facilities, as EU F-Gas Regulation compliance timelines accelerate retooling cycles. Long-term viability over the coming decade hinges on bio-resin scale-up capabilities and verified Scope 3 carbon accounting alignment with CSRD reporting frameworks. Monitor ECHA candidate list updates on polyurethane core bonding agents as inflection indicators for reformulation cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Weaving | Captive supply partnerships in Tyrol insulate margin pools from Austrian capacity bottlenecks. |
| Automated Fiber Placement Scale-Up | Robotics-enabled tape laying cuts scrap rates in Chamonix and Innsbruck composite facilities. |
| Bio-Resin System Development | REACH-compliant solvent-free formulations address ECHA scrutiny on isocyanate hardeners. |
| Digital Fitting Platform Launch | 3D foot scanning with CNC boot molding bypasses specialty retail for direct-to-consumer channels. |
| CSRD Reporting Alignment | Verified Scope 3 carbon accounting creates first-mover advantage in EU procurement cycles. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ski manufacturing executives, alpine resort procurement directors, composite materials R&D leads, and DIN certification specialists at TÜV and SGS facilities with secondary validation from EU F-Gas Regulation filings, ECHA candidate list updates, SEC disclosures by listed equipment manufacturers, and alpine tourism infrastructure investment databases. Bottom-up segment sizing and top-down macroeconomic triangulation anchored value projections.
Segment-weighting approaches distributed value across product type, material specification, end user performance tier, and distribution channel dimensions throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, resort fleet modernization timelines, and regulatory compliance cost modeling. Industry-specific inputs included carbon fiber prepreg adoption curves, automated layup penetration rates, and bio-resin commercialization milestones.
Several conditions sit outside the modeled scope, including abrupt EU Green Deal enforcement variance, unanticipated ECHA substance restrictions beyond isocyanate hardeners, and alpine tourism demand shocks from climate variability. Forecasts reflect documented assumptions about resin price stabilization and certification backlog resolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
PE Sports Turf Market
Sports Equipment
Europe Artificial Grass Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Power Sports Aftermarket Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Portable Basketball Hoops Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Golf Club Market
Sports Equipment
Agility Ladders Market
Sports Equipment
Mouthguard Market
Sports Equipment
Trail Shoes Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Bike Saddles Market