
 Baseball Shoes Market | 2026-2036
Baseball Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Baseball Shoes Market Analysis
California SB 657 is decoupling baseball footwear sourcing from opaque supply chains, compelling brands to document labor practices across synthetic material suppliers. Nike leverages its vertically controlled Asian manufacturing network to sustain compliance visibility from raw polymer to finished cleat. Adidas competes through its speed-to-market architecture, while New Balance anchors its positioning in domestic final assembly for institutional buyers.
Baseball shoes are engineered athletic footwear incorporating molded or metal cleat configurations, midsole cushioning systems, and upper constructions of leather or synthetic composites designed to optimize traction, stability, and biomechanical performance on dirt and grass surfaces. The cleats category dominates unit volume through institutional team procurement, though turf shoes are gaining share in indoor training facilities and cold-climate markets where field access is constrained. Mesh and synthetic materials are displacing leather in youth and recreational segments due to weight reduction and moisture management advantages, while premium leather uppers retain their position in professional and collegiate channels where durability and break-in customization carry priority.
FDA oversight of footwear chemical safety, EPA guidelines on volatile organic compound emissions in adhesive manufacturing, and ISO 17075 chromium testing protocols collectively elevate compliance costs for brands serving the North American market. The Consumer Product Safety Commission's evolving guidance on youth athletic equipment further shapes product liability exposure and design documentation requirements. Stakeholders must monitor how state-level extended producer responsibility legislation in California and New York will alter end-of-life collection obligations and material recovery specifications for athletic footwear.
Market Dynamics
California SB 657 supply chain transparency mandates are decoupling baseball footwear sourcing from opaque Asian manufacturing networks, compelling brands to document labor practices across synthetic material suppliers from polymer extraction through finished cleat assembly.
Growth Catalysts
- Youth League Expansion:Amateur baseball programs across Texas and Florida sustain above-average footwear refresh cycles through year-round training schedules. Municipal park districts prioritize bulk cleat procurement for seasonal league enrollments.
- Synthetic Upper Performance:Mesh and engineered composites are displacing leather in recreational segments due to weight reduction and moisture management advantages. Polymer chemistry advances enable comparable durability at reduced unit cost.
- Indoor Training Infrastructure:Cold-climate markets and urban density constraints accelerate turf shoe adoption for indoor facility access. Facility operators specify non-marking outsoles compatible with artificial surface warranties.
Market Restraints
- Petrochemical Input Volatility:Synthetic rubber and thermoplastic polyurethane prices fluctuate with crude oil derivatives, compressing margin visibility for mid-tier manufacturers dependent on spot market sourcing.
- Concentrated Asian Manufacturing:Finished cleat production clusters in Vietnam and Indonesia create geopolitical and logistics risk exposure. Single-source dependencies amplify disruption vulnerability during port congestion events.
- ISO 17075 Compliance Burden:Chromium VI testing protocols for leather tanning processes elevate documentation costs and extend quality assurance timelines for brands maintaining premium leather product lines.
Strategic Opportunities
- Domestic Final Assembly:New Balance's institutional buyer positioning demonstrates viable demand for US-assembled product among collegiate athletic departments and military exchange systems.
- Extended Producer Responsibility:California and New York state legislation will mandate end-of-life collection and material recovery specifications, creating first-mover advantage for circular design capabilities.
- Biomechanical Customization:3D scanning and additive manufacturing convergence enables position-specific cleat plate geometries for professional and elite amateur segments.
Industry Challenges
- Polymer Chemistry Talent Scarcity:Formulation expertise for high-performance synthetic uppers concentrates among aging specialist cohorts with limited university pipeline replenishment.
- Multi-Regulatory Documentation:Simultaneous FDA chemical safety, EPA VOC emission, and CPSC youth equipment guidance compliance creates overlapping certification timelines and liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baseball Shoes Market |
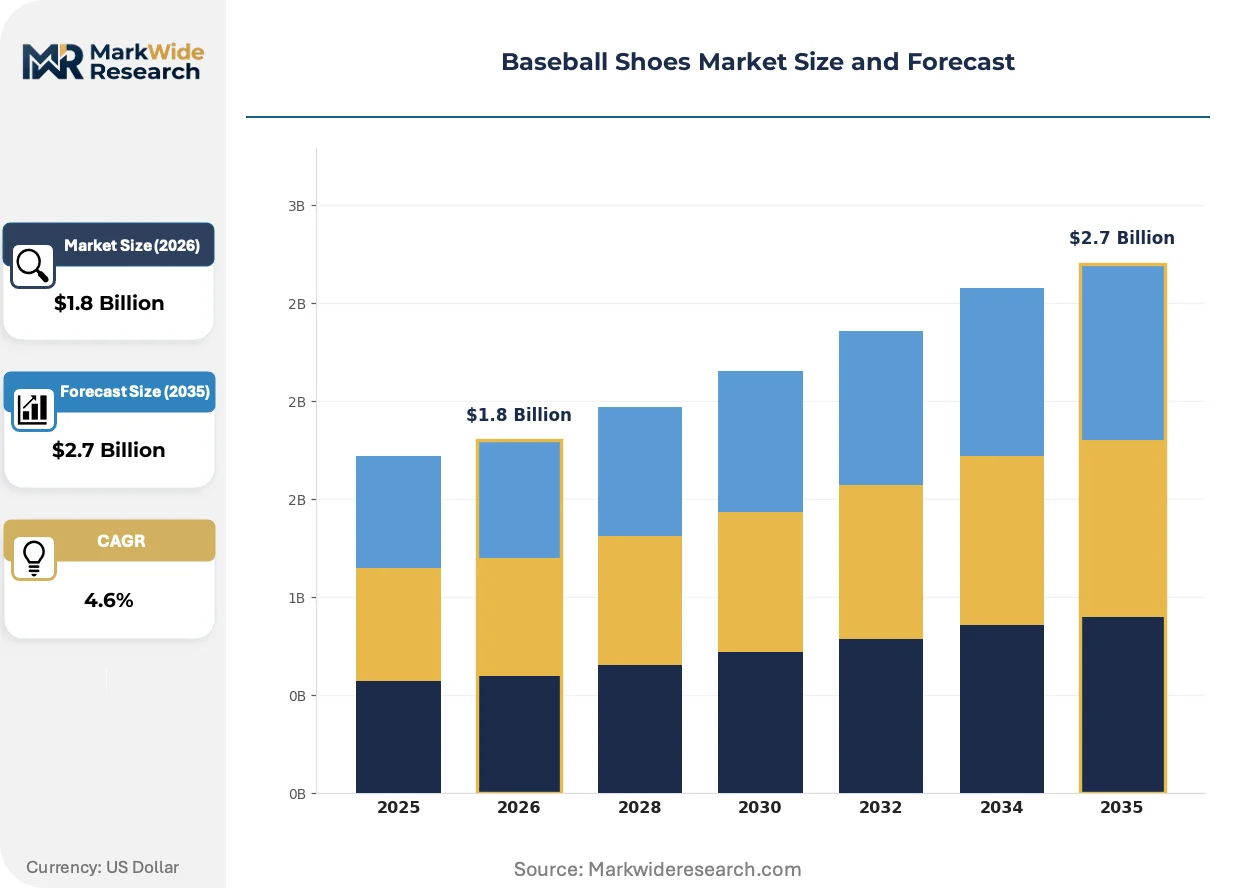
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cleats, Turf Shoes, Training Shoes, Casual Styles Material: Leather, Synthetic, Mesh, Rubber End User: Athletes, Coaches, Youth Players, Recreational Players Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Mizuno, Marucci Sports, Nike, SQAIRZ, Wilson, Adidas, Rawlings, Under Armour, New Balance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baseball Shoes Market Emerging Trajectories
Material science advances and regulatory transparency mandates are restructuring how baseball footwear is engineered, sourced, and sold across amateur and professional channels.
Engineered mesh and knit synthetic uppers are absorbing moisture management and weight reduction functions previously requiring leather construction. Youth and recreational leagues adopt these materials fastest, driven by parental preference for machine-washable durability and reduced break-in periods. The technology is absorbing cost compression pressure while maintaining performance parity with traditional materials.
REACH chemical substance restrictions and California's SB 657 supply chain disclosure requirements are forcing reformulation of adhesives and synthetic polymers across European and North American distribution channels. Brands must now map tier-three supplier labor practices and chemical inputs for regulatory filing. Professional and collegiate channels face the steepest compliance documentation burdens due to institutional procurement audit requirements.
Direct-to-team bulk procurement platforms are consolidating purchasing authority among athletic directors and equipment managers, bypassing traditional retail intermediaries. Regional sporting goods distributors lose share to specialized team dealers offering customization and volume pricing. Texas and Florida high school athletic associations exhibit the most concentrated adoption of centralized buying cooperatives for standardized cleat specifications.
Baseball Shoes Market Segmentation
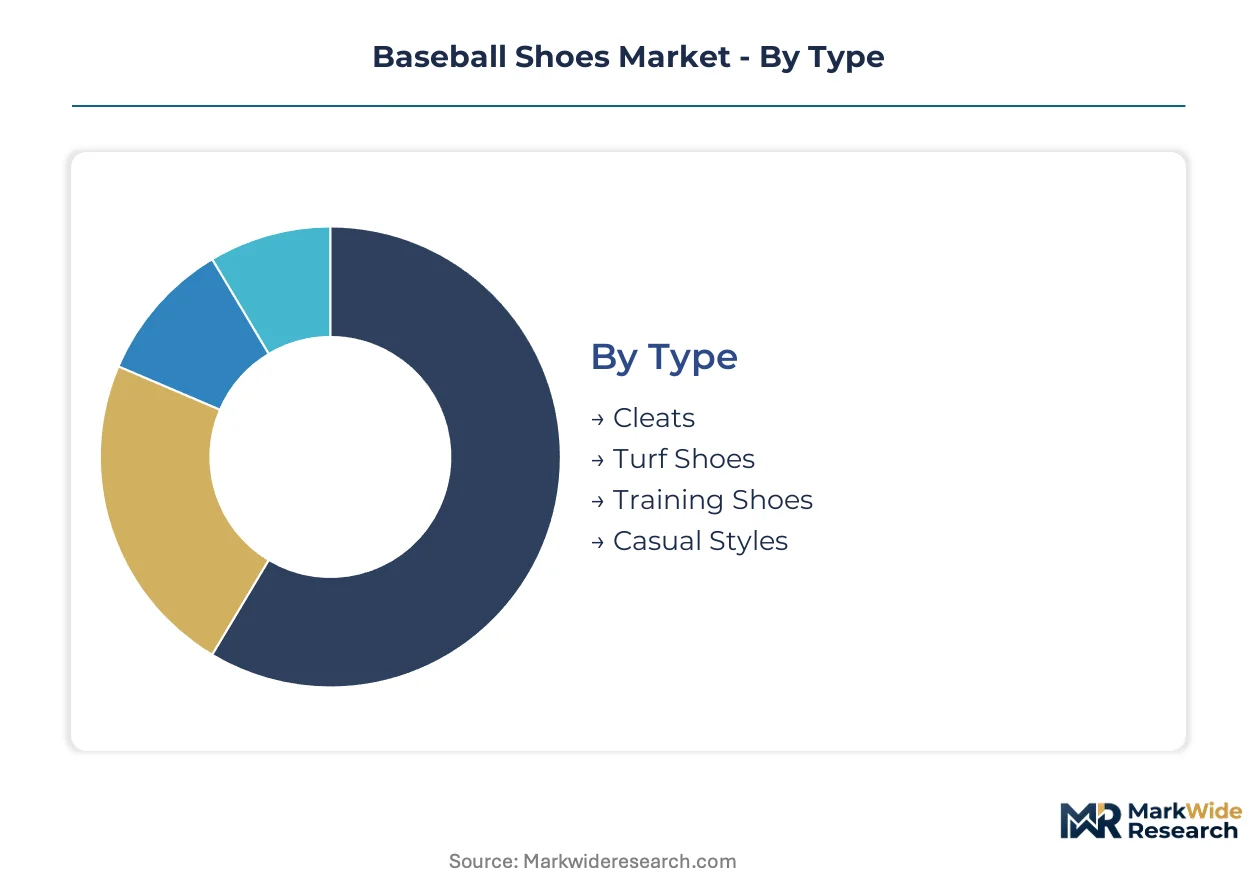
Baseball footwear segmentation reflects divergent performance requirements across competitive tiers, material science trade-offs between durability and weight, and procurement patterns that separate institutional buyers from individual consumers. Understanding these divisions enables targeted positioning against distinct technical specifications and purchasing behaviors.
Type:
Cleat configurations anchor competitive play while alternative designs serve training and lifestyle applications with varying integration depth into athletic performance systems.
- Cleats:Molded and metal spike configurations dominate competitive play across dirt and natural grass surfaces. Texas and Florida high school athletic associations specify cleat types through centralized procurement cooperatives for seasonal league compliance. Institutional team purchasing concentrates demand in this segment through bulk refresh cycles tied to academic calendars.
- Turf Shoes:Rubber-studded outsoles optimize traction on artificial surfaces and indoor training facilities. Cold-climate markets in the northern United States accelerate adoption where field access is seasonally constrained. Facility operators mandate non-marking compounds to preserve artificial turf warranty coverage.
- Training Shoes:Flat-soled designs support batting practice and conditioning work without cleat-induced surface damage. These serve embedded roles within comprehensive equipment arsenals rather than standalone competitive use.
- Casual Styles:Lifestyle-oriented silhouettes leverage baseball aesthetics for everyday wear. Fashion-focused distribution channels move these through retail rather than team procurement pathways.
Cleats lead volumes today; turf shoes are gaining share fastest.
Material:
Upper construction choices balance break-in customization against maintenance convenience across player maturity levels and competitive intensities.
- Synthetic:Engineered polymers and polyurethane composites deliver moisture management and machine-washable durability. Youth leagues in California and Texas adopt these materials fastest due to parental preference for reduced break-in periods and lower replacement frequency.
- Leather:Full-grain and split-leather uppers retain priority in collegiate and professional channels where durability and personalized fit carry premium value. ISO 17075 chromium testing protocols elevate compliance documentation for tanned leather sourcing.
- Mesh:Knit and woven textile constructions maximize breathability for recreational and training applications. Weight reduction benefits appeal to developing players in amateur programs.
- Rubber:Outsole compounds and protective overlays provide abrasion resistance and surface traction. Formulation expertise concentrates among specialized polymer suppliers serving Vietnamese and Indonesian manufacturing clusters.
Synthetic materials dominate unit shipments; mesh constructions show steepest expansion trajectory.
End User:
User categories separate performance-driven competitive requirements from developmental and instructional footwear needs with distinct replacement cadences.
- Youth Players:Growing feet and seasonal league structures drive annual replacement cycles across municipal park districts. Parental purchasing prioritizes cost efficiency and rapid availability over customization depth.
- Athletes:Collegiate and professional competitors demand position-specific plate geometries and biomechanical optimization. Equipment managers coordinate direct-to-team procurement bypassing retail intermediaries.
- Coaches:Instructional staff require durable footwear for extended field hours with less intensive lateral movement. Bulk purchasing authority often consolidates through athletic director oversight.
- Recreational Players:Adult amateur leagues and casual participants prioritize versatility across multiple sports and casual use. Price sensitivity shapes brand switching behavior in this segment.
Youth players anchor volume concentration; athletes command premium pricing tiers.
Price Tier:
Pricing stratification aligns material quality, manufacturing location, and brand positioning against distinct procurement authority structures.
- Mid-Range:Synthetic-leather hybrids and domestic assembly options capture institutional buyers balancing performance specifications with budget constraints. Collegiate athletic departments in Texas and Florida standardize on this tier for team-wide distribution.
- Premium:Full-grain leather uppers and advanced cushioning systems target competitive players seeking durability and customization. Extended product lifecycles justify higher initial outlay for serious amateur athletes.
- Budget:Basic synthetic constructions serve entry-level youth participation and seasonal recreational use. Mass retail channels and online marketplaces concentrate distribution for price-sensitive purchasers.
- Luxury:Limited editions and heritage-inspired designs command collector premiums through scarcity positioning. Direct-to-consumer releases bypass traditional sporting goods distribution.
Mid-range pricing holds largest revenue share; premium tier climbs fastest among competitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baseball footwear manufacturing traces its modern origins to Massachusetts leather tanneries and rubber sole fabricators that supplied early 20th-century American professional leagues. The industry's geographic footprint now spans multiple continents as synthetic materials and specialized cleat engineering have globalized production networks.
United States
Texas and Florida sustain the highest per-capita replacement rates through year-round youth league schedules and collegiate athletic procurement. California's SB 657 supply chain transparency mandates compel brands to document labor practices across tier-three synthetic material suppliers. Boston anchors domestic final assembly operations for institutional buyers seeking US-manufactured product lines.
Vietnam
Ho Chi Minh City and surrounding industrial provinces host concentrated cleat manufacturing for export to North American markets. Factory clusters specialize in thermoplastic polyurethane molding and rubber outsole vulcanization for major athletic brands. The country's Ministry of Industry and Trade oversees compliance with ISO 17075 chromium testing protocols for any leather components in premium product lines.
Indonesia
Java-based manufacturing facilities produce synthetic upper components and cleat plate assemblies for global distribution. Batam and Jakarta industrial zones attract footwear investment through specialized polymer chemistry expertise. The national standards body implements REACH-aligned chemical restrictions for adhesives and synthetic polymers entering European distribution channels.
China
Guangdong Province manufacturing clusters supply engineered mesh textiles and knit synthetic constructions for youth and recreational segments. Shenzhen polymer laboratories develop moisture-management fabrics that displace leather in cost-sensitive product tiers. The State Administration for Market Regulation enforces GB standards for footwear chemical safety in domestic and export production.
Japan
Kansai region industrial centers maintain precision metal cleat forging and advanced cushioning system production for professional-grade equipment. Osaka-based suppliers serve Nippon Professional Baseball and high school federation procurement with position-specific biomechanical designs. METI guidelines on manufacturing quality assurance shape documentation requirements for synthetic material traceability.
Baseball Shoes Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material innovation and supply chain transparency dimensions. The vendor base organizes into three tiers: vertically integrated multinationals with captive Asian manufacturing, domestic-assembly specialists serving institutional procurement, and private-label suppliers competing on price for entry-level youth segments. Dominant competitive moves include strategic partnerships with polymer chemistry laboratories and geographic expansion into cold-climate turf shoe markets.
Among US-based athletic equipment conglomerates, Nike and New Balance occupy distinct positioning vectors. Nike exemplifies the vertically integrated multinational archetype through controlled Asian manufacturing networks that sustain compliance visibility from raw polymer extraction. New Balance anchors the domestic-assembly specialist tier with Massachusetts-based final operations targeting collegiate athletic departments and military exchange systems. Adidas, organized as a European GmbH structure, represents the speed-to-market architecture competing through rapid product cycle turnover.
| Leading Market Players |
|---|
| Mizuno |
| Marucci Sports |
| Nike |
| SQAIRZ |
| Wilson |
| Adidas |
| Rawlings |
| Under Armour |
| New Balance |
| Others |
Supply Flow & Price Mechanics
Specialized polymer chemists in Ho Chi Minh City and Guangdong Province command wage premiums that compress margin spreads between premium leather and synthetic upper tiers, forcing brands to absorb labor-cost differentials through tiered product architecture rather than geographic arbitrage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates baseball footwear, with ISO 17075 certification status and domestic final assembly location serving as primary price differentiation drivers. Pricing pressure stems from petrochemical input volatility in thermoplastic polyurethane feedstocks, squeezing mid-tier manufacturers most severely. Youth league parents exhibit highest price sensitivity, while collegiate equipment managers demonstrate lowest sensitivity due to institutional budget fungibility.
Supply Chain Analysis
Dual-sourcing requirements from institutional buyers in Texas and Florida compel brands to qualify redundant suppliers across Vietnam, Indonesia, and China for synthetic uppers and rubber outsoles. Raw material dependencies center on crude oil derivatives for TPU molding, Malaysian rubber for outsole vulcanization, and chromium-tanned leather from tanneries subject to ISO 17075 protocols. Tariff exposure on Vietnamese footwear imports creates structural risk concentration. Distribution runs through direct-to-team platforms and specialized sporting goods dealers serving municipal park districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Baseball footwear has entered a late-cycle quality phase where collegiate and professional procurement standards are hardening around supply chain transparency documentation, rewarding brands with tier-three supplier visibility.
For Market Incumbents: Hedge against synthetic material cost volatility through backward integration into polymer formulation partnerships or captive TPU molding capacity in Vietnam. Defend institutional buyer relationships by accelerating SB 657 compliance documentation ahead of California's audit deadlines, as procurement officers increasingly disqualify opaque supply chains. For New Entrants and Emerging Players: Begin with cold-climate turf shoe specialization for indoor training facilities in northern US markets, where facility operators mandate non-marking outsoles and warranty-compatible construction. Penetrate through direct-to-facility sales bypassing established team dealer networks, leveraging customization speed as the primary go-to-market wedge. For Investors and Strategic Acquirers: Athletic equipment conglomerates with captive Asian manufacturing are the most active acquirer in this space, seeking polymer chemistry capabilities and regional distribution infrastructure. Long-term viability favors targets with demonstrated circular design competencies ahead of extended producer responsibility mandates. Watch California and New York legislative implementation timelines as the critical inflection signal for material recovery obligation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Supply Chain Transparency Certification | SB 657 compliance documentation unlocks institutional procurement channels in California and Texas. |
| Circular Design Capability Investment | End-of-life collection infrastructure positions brands ahead of New York extended producer responsibility mandates. |
| Biomechanical Customization Platform | 3D scanning integration enables position-specific cleat geometries for professional and elite amateur segments. |
| Domestic Final Assembly Expansion | Massachusetts-based production captures military exchange and collegiate athletic department preference for US-manufactured product. |
| Synthetic Upper Material Science Partnership | Engineered mesh development with Shenzhen polymer laboratories accelerates leather displacement in youth segments. |
Methodological Framework
Direct dialogue with equipment managers at collegiate athletic departments, procurement officers for municipal park districts, polymer chemists at Vietnamese manufacturing facilities, and regulatory compliance leads at athletic footwear brands grounded the qualitative foundation. Secondary validation drew from CPSC youth equipment guidance documents, EPA VOC emission filings, customs records for footwear imports, and ISO 17075 testing protocol disclosures. Bottom-up demand modeling from youth league enrollment data and top-down value estimation from institutional procurement databases were triangulated against production capacity assessments.
Top-down macroeconomic indicators and bottom-up segment-specific demand drivers converged across the analysis window through a structured forecasting framework. Modeled dimensions included cleat configuration type, upper material composition, end-user competitive tier, and price positioning band. CAGRs were derived from regression analysis against historical replacement cycle data and projected league expansion rates, with petrochemical price indices and regulatory implementation timelines serving as primary industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced trade policy shifts, abrupt changes in youth sports participation rates, and breakthrough material science displacing existing synthetic formulations. Deviation in California SB 657 enforcement intensity or New York extended producer responsibility implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Badminton Equipment Market
Sports Equipment
US Fencing Market
Sports Equipment
Surfing Boards Market
Sports Equipment
Global Skateboard Market
Sports Equipment
Kiteboarding Equipment Market
Sports Equipment
Cycling Helmet Market
Sports Equipment
Global Darts Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
Motocross Gears Market
Sports Equipment
Ladderball Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Mixed Martial Arts Equipment Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
North America Sporting Goods Market