
 Gymnastic Bars Market | 2026-2036
Gymnastic Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Gymnastic Bars Market Analytics
FIG apparatus certification is rotating as the decisive gate for competition-grade bar manufacturers seeking Olympic and World Championship eligibility. Spieth America leverages its European manufacturing heritage to sustain premium positioning in FIG-certified equipment. Tumbl Trak anchors North American distribution through specialized dealer networks serving competitive clubs and professional schools. Nimble Sports differentiates by occupying the junior and recreational tier with folding bars designed for home users and entry-level gyms.
Gymnastic bars are rigid horizontal apparatuses, typically constructed from laminated fiberglass cores sheathed in hardwood or synthetic grips, engineered to withstand dynamic loads from swings, releases, and regrasp maneuvers in training and competitive environments. Competition bars command the highest margin pools due to FIG certification requirements and limited qualified supplier bases, while folding bars represent the fastest-expanding category as home gymnastics participation surges post-pandemic. Aluminum and composite materials are displacing traditional steel in mid-tier training bars, offering weight reduction and corrosion resistance for high-volume recreational gyms.
FIG technical committees, the U.S. Consumer Product Safety Commission, and ASTM International F24 amusement ride and device standards collectively shape bar design, load testing protocols, and market access requirements across major gymnastics economies. ASTM F2374 specifically addresses structural stability and impact resistance for gymnastic equipment installed in public and institutional settings. Stakeholders must monitor evolving FIG apparatus specifications and regional safety mandates to align R&D pipelines with certification cycles that determine tournament eligibility and institutional procurement authorization.
Market Dynamics
FIG apparatus certification requirements are concentrating supplier eligibility for Olympic-caliber equipment, compressing the vendor base while elevating technical barriers for competition-grade bar manufacturers.
Growth Catalysts
- Youth Enrollment Surge:Competitive clubs across the United States are expanding equipment procurement as structured gymnastics programs absorb record post-pandemic participation rates.
- ASTM F2374 Mandates:The U.S. Consumer Product Safety Commission's structural stability standards are institutionalizing safety-driven replacement cycles in public and educational facilities.
- Fiberglass-Core Engineering:Laminated composite construction is displacing traditional steel in mid-tier training bars, reducing weight while maintaining dynamic load tolerance.
Market Restraints
- Certification Cost Concentration:FIG apparatus testing and approval cycles impose fixed-cost burdens that exclude smaller manufacturers from tournament-eligible supply chains.
- Hardwood Supply Volatility:Premium grip material sourcing faces pressure from sustainable forestry constraints and export restrictions in traditional supplier nations.
- Aluminum Price Fluctuation:Mid-tier bar production remains exposed to London Metal Exchange aluminum pricing volatility, compressing margin predictability.
Strategic Opportunities
- Home Gymnasium Expansion:Folding bar designs targeting residential users in suburban United States markets capture unmet demand from recreational gymnasts.
- Composite Material Convergence:Carbon-fiber hybrid cores combined with synthetic grip surfaces enable premium performance at reduced transport costs.
- Elite Facility Upgrades:NCAA Division I programs and Olympic training centers are accelerating replacement cycles for FIG-certified apparatus ahead of championship cycles.
Industry Challenges
- Certification Timeline Compression:FIG technical committee review cycles for apparatus modifications lag behind material innovation cadences, delaying product launches.
- Specialized Installation Labor:Competition-grade bar anchoring and calibration require certified technicians, constraining deployment velocity for new facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gymnastic Bars Market |
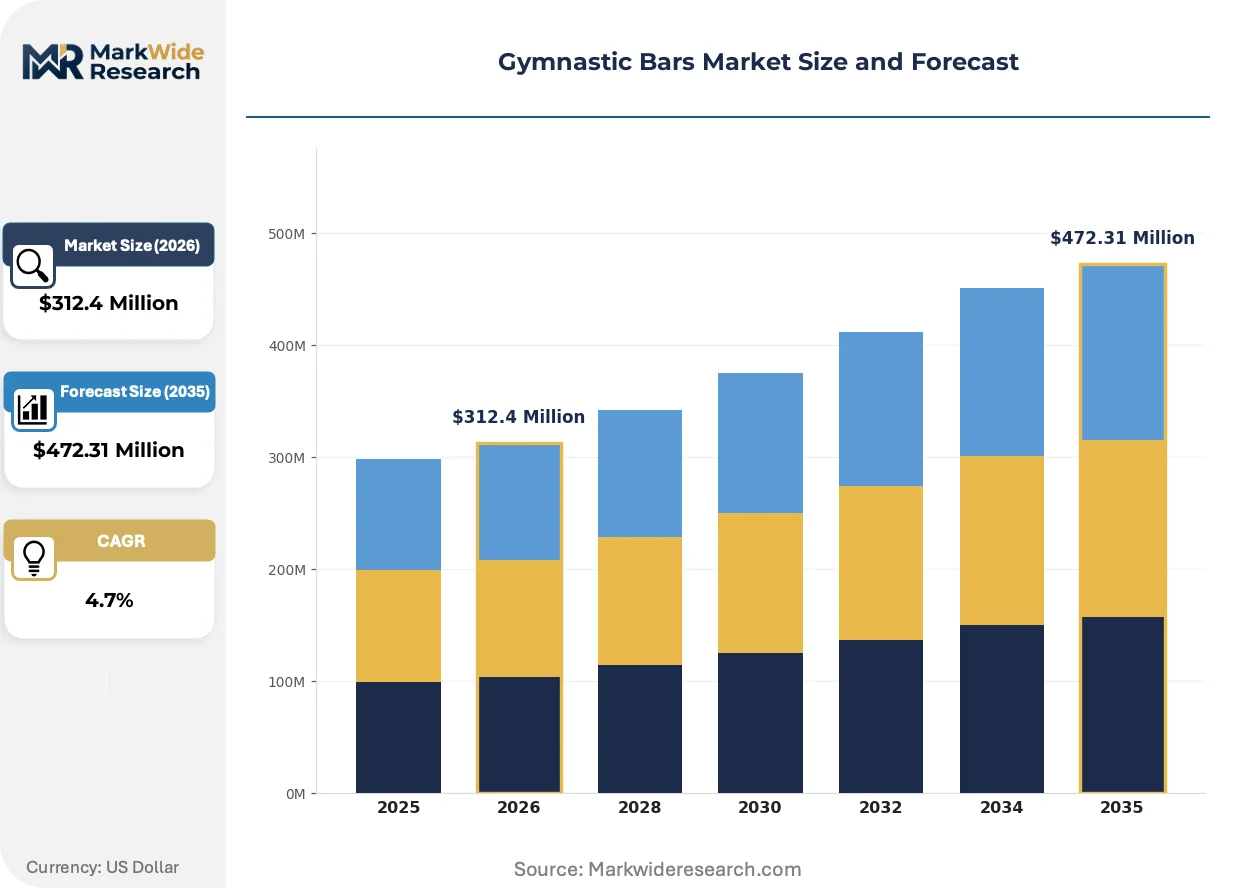
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Bars, Training Bars, Competition Bars, Junior Bars End User: Recreational Gyms, Professional Schools, Competitive Clubs, Home Users Material: Wood, Steel, Aluminum, Composite Weight Capacity: 100 lbs, 150 lbs, 200 lbs, 250 lbs |
| Companies Covered | AirTumble, Nimble Sports, Tumbl Trak, We Sell Mats, Gym Plus, Safly, Spieth America, Milliard, Z Athletic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gymnastic Bars Market Evolving Landscape
Material science advances and certification-driven procurement standards are restructuring competitive positioning across equipment tiers, with synthetic surfaces and modular architectures gaining institutional traction.
Carbon-fiber reinforced polymer cores are displacing laminated fiberglass in premium competition bars, delivering superior energy return and fatigue resistance. Elite training facilities in Colorado Springs and Huntsville are piloting these platforms ahead of national team selection camps. The shift is compressing replacement intervals for traditional hardwood-sheathed apparatus.
ASTM International F24 amusement ride standards are extending into gymnastic equipment liability frameworks, mandating third-party structural testing for institutional installations. Manufacturers serving school districts and municipal recreation centers are reconfiguring quality assurance protocols. The standard's impact concentrates in Texas and California, where public liability thresholds are highest.
Direct-to-club equipment financing is fragmenting traditional dealer-network relationships, with competitive clubs securing lease structures for FIG-certified apparatus. Specialized distributors in the Midwest and Southeast are unbundling installation and maintenance services to preserve margin. This pattern is most pronounced among NCAA-affiliated programs with capital budget constraints.
Gymnastic Bars Market Segmentation
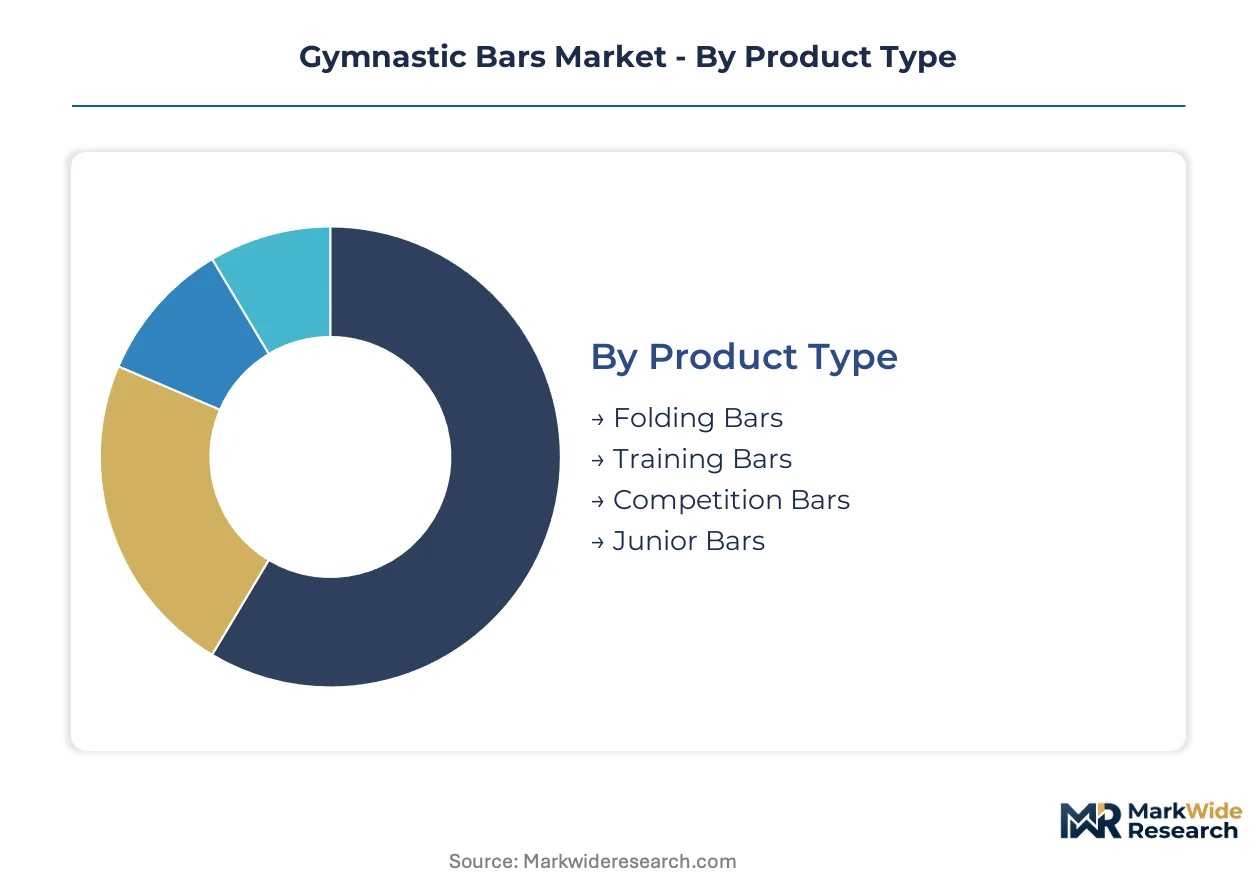
Segmentation in gymnastic bars reveals distinct procurement patterns across certification tiers, with FIG compliance requirements fragmenting supplier eligibility while recreational demand reshapes material specifications. Understanding these divides enables manufacturers to align R&D investments with replacement cycles and emerging participation channels.
Product Type:
Substitution pressure from home fitness equipment and multi-purpose training rigs threatens entry-level categories most acutely, while FIG-certified apparatus maintains structural insulation through regulatory lock-in.
- Competition Bars:Laminated fiberglass cores sheathed in hardwood or synthetic grips, engineered to FIG apparatus specifications for dynamic load tolerance during releases and regrasp maneuvers. Demand concentrates in NCAA Division I programs and Olympic training centers across the United States, driven by mandatory replacement cycles ahead of championship qualification periods.
- Folding Bars:Collapsible steel or aluminum frames with adjustable height mechanisms, designed for residential storage constraints and rapid deployment. Suburban United States markets exhibit the steepest demand acceleration as post-pandemic home gymnastics participation institutionalizes beyond temporary trends.
- Training Bars:Fixed-height institutional apparatus serving skill progression between recreational entry and competitive preparation, typically constructed from aluminum or composite materials to balance durability with transportability for mobile coaching programs.
- Junior Bars:Reduced-scale apparatus with lower mounting heights and narrower grip diameters, targeting developmental gymnastics programs for athletes aged 5-12 in municipal recreation centers and private academies.
Competition bars anchor the volume base while folding bars gain share at the steepest rate.
End User:
Cost tier stratification separates institutional procurement governed by ASTM mandates from discretionary residential purchases sensitive to price-positioning and spatial constraints.
- Competitive Clubs:Elite training facilities requiring FIG-certified apparatus for athlete qualification pathways, subject to capital budget cycles tied to enrollment growth and equipment depreciation schedules. Texas and California clubs drive premium replacement demand due to liability threshold concentrations.
- Home Users:Residential purchasers prioritizing collapsible designs and sub-200 lb weight capacities for basement or garage installations, with procurement decisions influenced by parental gymnastics backgrounds and social media equipment visibility.
- Professional Schools:Collegiate and preparatory academies balancing competitive program aspirations with institutional procurement protocols, often leasing FIG-certified apparatus through specialized distributor financing arrangements.
- Recreational Gyms:High-volume facilities serving casual participants and birthday party programming, favoring aluminum construction for corrosion resistance in humid climates and lower per-unit capital commitment.
Recreational gyms generate the highest unit velocity while competitive clubs extract the steepest per-unit margins.
Material:
Application-specific performance requirements determine material selection, with competitive environments demanding energy return characteristics unavailable in basic formulations.
- Composite:Carbon-fiber reinforced polymer cores displacing traditional fiberglass in premium competition bars, delivering superior fatigue resistance and reduced replacement intervals for elite training facilities in Colorado Springs and Huntsville.
- Aluminum:Mid-tier training and recreational bars leveraging corrosion resistance and weight reduction for high-volume institutional deployment, though London Metal Exchange pricing volatility compresses margin predictability for manufacturers.
- Wood:Traditional hardwood sheathing for grip surfaces facing sustainable forestry constraints and export restrictions from traditional supplier nations, elevating sourcing costs for FIG-certified apparatus.
- Steel:Entry-level folding and junior bar construction, increasingly displaced by aluminum in weight-sensitive applications but retained for maximum load capacity requirements in budget-constrained institutional procurement.
Composite materials command the steepest expansion trajectory while aluminum retains the broadest cross-tier penetration.
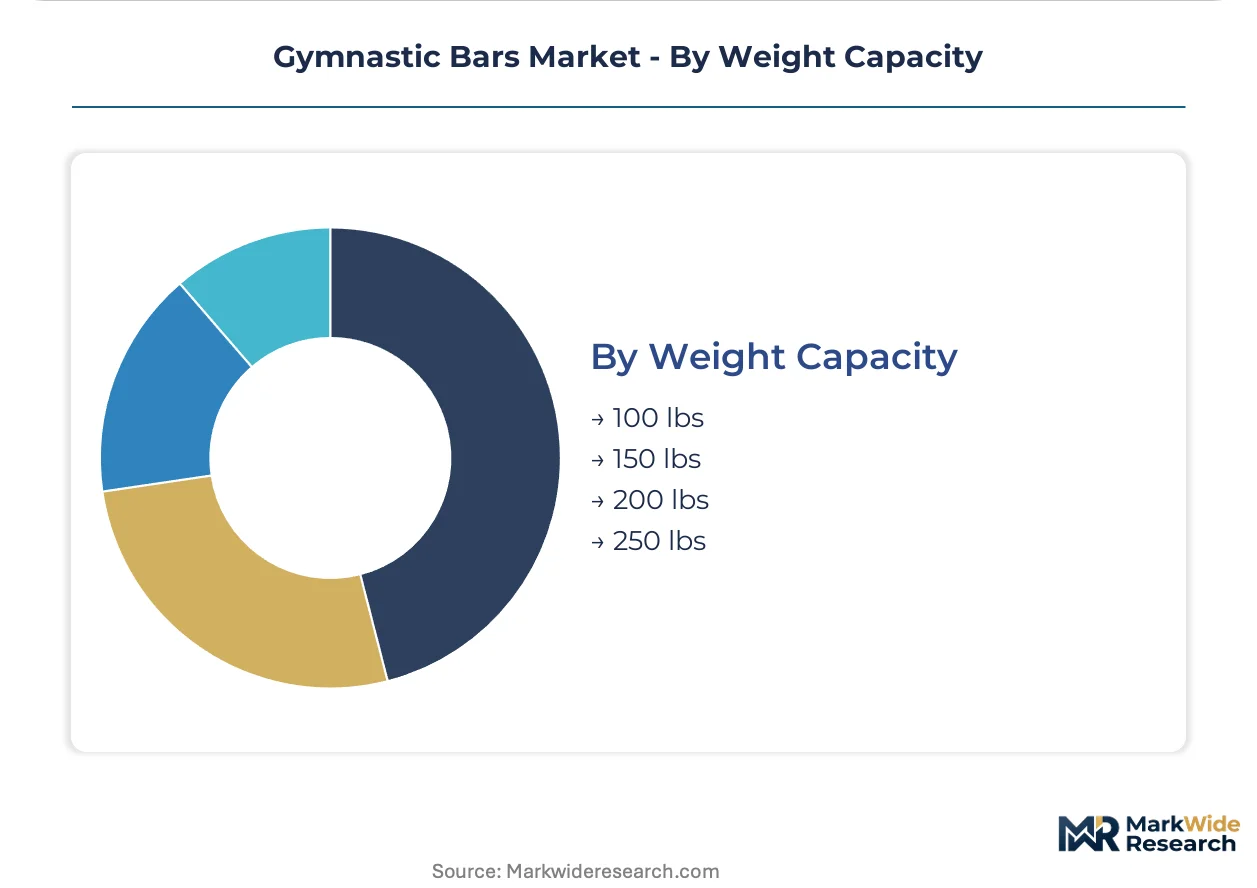
Weight Capacity:
Customer type alignment separates developmental specifications from performance-grade requirements, with liability considerations elevating minimum thresholds for commercial installations.
- 250 lbs:Maximum-load competition and elite training specifications accommodating adult male gymnasts and dynamic release maneuvers, mandatory for FIG apparatus certification and NCAA program compliance.
- 100 lbs:Entry-level junior and recreational specifications serving pre-adolescent participants in home and municipal settings, with ASTM F2374 structural stability standards governing minimum safety margins.
- 150 lbs:Intermediate training specifications bridging developmental and competitive preparation, prevalent in private academies with mixed-age programming.
- 200 lbs:Advanced recreational and competitive youth specifications capturing adolescent female gymnasts and serious home training environments.
250 lb capacity anchors institutional procurement volume while 100 lb specifications expand most quickly in residential channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elite training facilities and competitive clubs concentrate equipment procurement in the United States, Germany, China, Japan, and Australia, with each market shaped by distinct certification regimes and participation demographics.
United States
NCAA Division I programs and Olympic training centers in Colorado Springs drive FIG-certified apparatus replacement cycles ahead of championship qualification periods. ASTM F2374 structural stability standards govern institutional installations in Texas and California, where liability thresholds elevate safety-driven procurement. The Southeast region absorbs folding bar demand from suburban home gymnastics participation.
Germany
European manufacturing heritage sustains premium positioning for FIG apparatus suppliers serving competitive clubs across Bavaria and North Rhine-Westphalia. CE marking requirements and the EU's machinery directive shape equipment import protocols for training facilities. Stuttgart and Munich anchor elite gymnastics infrastructure with concentrated national team preparation centers.
China
GB standards and MIIT industrial policy guide domestic equipment manufacturing for recreational gym chains expanding in the Yangtze River Delta. Provincial sports bureaus in Guangdong and Shandong fund municipal gymnastics infrastructure development. The Pearl River Delta concentrates export-oriented fabrication for mid-tier training bars.
Japan
JIS standards and METI industrial guidance structure equipment procurement for school-based gymnastics programs in Kanto and Kansai regions. The Tokyo metropolitan area maintains elite training infrastructure for national team selection. Osaka prefecture hosts specialized distributors serving competitive club networks.
Australia
Gymnastics Australia membership growth drives equipment procurement in New South Wales and Victoria, with Sydney and Melbourne anchoring competitive club density. State-level sporting facility grants from the Australian Sports Commission fund apparatus upgrades in municipal recreation centers. Queensland's Gold Coast region supports emerging elite training infrastructure.
Gymnastic Bars Market Competitive Landscape
Player mix skews toward specialized equipment fabricators with FIG certification capabilities and mass-market recreational suppliers serving home users. The vendor base separates into three tiers: premium competition-grade manufacturers, mid-tier institutional suppliers, and entry-level recreational specialists. Strategic differentiation concentrates on certification maintenance, material innovation, and distribution channel control. Competitive moves center on direct-to-club financing arrangements and composite material R&D partnerships.
Among North American specialists, Tumbl Trak and Nimble Sports occupy distinct positioning archetypes. Tumbl Trak anchors distributor-network relationships serving competitive clubs and professional schools with institutional-grade apparatus. Nimble Sports exemplifies the recreational-tier specialist, capturing suburban home market demand through collapsible designs. Spieth America represents the European-heritage premium manufacturer, leveraging FIG certification continuity for Olympic-eligible equipment positioning.
| Leading Market Players |
|---|
| AirTumble |
| Nimble Sports |
| Tumbl Trak |
| We Sell Mats |
| Gym Plus |
| Safly |
| Spieth America |
| Milliard |
| Z Athletic |
| Others |
Value Network & Pricing Analysis
Capacity utilization at European FIG-certified manufacturing facilities anchors premium price floors, compressing mid-tier competitors while elevating procurement costs for U.S. competitive clubs seeking Olympic-eligible apparatus. This scale concentration reinforces supplier oligopoly dynamics across certification tiers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum indexation govern mid-tier training bar procurement, insulating manufacturers from commodity volatility while passing base metal risk to institutional buyers. Pricing stratifies across FIG-certified competition bars, ASTM-compliant institutional apparatus, and entry-level folding equipment, with certification grade commanding the steepest premium. Cost compression in aluminum-dependent tiers is intensifying because recreational gym chains negotiate volume aggregation. Home users exhibit the highest price sensitivity, while NCAA Division I programs demonstrate inelastic demand for FIG apparatus.
Supply Chain Analysis
Inventory cycles for laminated fiberglass cores extend lead times to 14-16 weeks during championship qualification periods, constraining rapid deployment for competitive clubs. Manufacturing concentrates in Germany, China, and the United States, with the Pearl River Delta anchoring export-oriented fabrication and Bavaria sustaining premium competition-grade production. Supply chains draw from hardwood suppliers in Southeast Asia, aluminum smelters in China, and carbon-fiber precursors from Japan. Single-source vulnerability in FIG-certified component certification creates bottleneck risk. Distribution runs through specialized dealer networks serving competitive clubs and direct-to-consumer channels for residential folding bars.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gymnastic bars market is recovering from pandemic-induced enrollment disruptions, with youth gymnastics participation cyclically rebounding through structured program expansion in suburban United States markets.
For Market Incumbents: Fortify FIG certification continuity through accelerated R&D investment in carbon-fiber hybrid cores ahead of technical committee specification updates. Deepen backward integration into laminated fiberglass production to offset hardwood supply volatility from Southeast Asian export restrictions. Channel control through exclusive distributor arrangements in Texas and California preserves margin against direct-to-club financing fragmentation. For New Entrants and Emerging Players: Lead with collapsible aluminum designs targeting residential home gymnasium demand in the Southeast United States, where post-pandemic participation institutionalization outpaces incumbent supply responsiveness. Municipal recreation centers in Australia and Canada present underpenetrated institutional channels with lower certification barriers than Olympic-eligible tiers. A digital-native go-to-market strategy leveraging parental social media equipment visibility bypasses traditional dealer network establishment costs. For Investors and Strategic Acquirers: FIG-certified niche specialists with established technical committee relationships represent the most defensible acquisition archetype within the equipment fabrication landscape. Long-term viability hinges on sustained youth enrollment trajectories and replacement cycle compression at elite training facilities. Monitor FIG apparatus specification revision timelines as the critical inflection signal for material innovation winners.| Strategic Initiative | Industry Significance |
|---|---|
| FIG Certification Investment | Technical committee engagement secures Olympic-eligible apparatus positioning for NCAA programs. |
| Composite Material R&D Partnership | Carbon-fiber hybrid core development reduces replacement intervals at Colorado Springs training centers. |
| Direct-to-Club Financing Launch | Unbundled lease structures capture capital-constrained competitive clubs in the Midwest. |
| Synthetic Grip Surface Development | Hardwood substitution addresses sustainable forestry constraints in Southeast Asian supply basins. |
| Residential Channel Expansion | Suburban United States folding bar penetration captures post-pandemic home gymnastics institutionalization. |
Research Methodology
A standing panel of competitive club equipment managers, FIG technical committee liaisons, gymnastics academy owners, and specialized distributor principals provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with these stakeholders alongside customs records, ASTM International certification databases, and gymnastics federation procurement disclosures. Bottom-up club-level equipment spend estimates triangulated against top-down manufacturer revenue assessments across product tiers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including certification tier, material composition, end-user category, and regional regulatory cluster. CAGRs derived from replacement cycle analysis, enrollment trajectory assumptions, and equipment depreciation schedules. Industry-specific inputs incorporated FIG apparatus specification revision cadences and ASTM F2374 adoption timelines.
The analysis sits within stated boundaries; outcomes outside sustained youth participation rates or FIG certification continuity would require recalibration. Forecasts reflect documented assumptions regarding championship cycle-driven replacement demand and material substitution economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Pickleball Paddle Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Golf Ball Market
Sports Equipment
Concussion Helmets Market
Sports Equipment
Asia-Pacific Bicycle Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
Bowling Lane Panels Market
Sports Equipment
PE Sports Turf Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Sports Devices Market
Sports Equipment
Global Darts Market
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
Street Skateboards Accessories Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Winter Sports Equipment Market