
 Recreational Rowing Boats Market | 2026-2036
Recreational Rowing Boats Market Size, Share, and Industry Trends Forecast 2026-2036
Recreational Rowing Boats Market Analysis
Fragmentation among rental companies and water-sports tourism operators is recalibrating procurement patterns across the recreational rowing boats value chain. Empacher leverages its carbon-composite expertise to dominate elite-performance segments, while FILIPPI LIDO SRL anchors Mediterranean supply through specialized coastal skiff production. Durham Boat Company sustains North American presence with traditional wood-strip construction methods that appeal to heritage-focused buyers.
Recreational rowing boats encompass manually propelled watercraft designed for non-competitive leisure, fitness, and coastal exploration, typically spanning 3.5 to 8.5 meters in hull length and constructed through resin-infusion or hand-layup composite processes to achieve displacement-to-weight ratios below 35 kg per meter. Fiberglass hulls occupy the volume tier due to cost-efficient mold replication and repair accessibility, while carbon-fiber variants command premium positioning among performance-oriented individual consumers. Skiff configurations lead European coastal markets where open-water stability requirements shape design priorities, and kayak derivatives capture fastest expansion in rental company fleets seeking stackable storage and modular seating arrangements.
ISO 12217 small-craft stability standards govern hull certification requirements across European Union member states, while the US Coast Guard enforces flotation and labeling rules under 33 CFR 183 that constrain material selection and manufacturing documentation. REACH chemical regulations limit certain resin formulations in European production, compelling manufacturers to reformulate gelcoat and adhesive systems. Stakeholders must monitor evolving sustainability mandates and hull-recycling directives that will reshape material specifications and end-of-life obligations without grandfathering existing fleet inventories.
Market Dynamics
Carbon-fiber resin-infusion techniques are compressing hull production cycles while ISO 12217 stability mandates force design recalibration across European manufacturing clusters. This dual pressure is restructuring procurement relationships between coastal boathouses and composite suppliers.
Growth Catalysts
- REACH-compliant resin reformulation:ECHA-mandated gelcoat substitutions are accelerating bio-epoxy adoption in German and Italian hull production, creating first-mover advantages for reformulated supply chains.
- Community boathouse fleet renewal:Municipal recreation departments across Germany and Austria are replacing aging fiberglass inventories with multi-seat training shells, concentrating demand for 6-8 meter hull configurations.
- Resin-infusion automation:Vacuum-assisted transfer molding is reducing void rates in carbon-fiber laminates, enabling smaller yards to achieve Empacher-grade structural consistency without hand-layup labor depth.
Market Restraints
- Carbon fiber feedstock concentration:Toray and Hexcel dominate aerospace-grade precursor supply, exposing hull fabricators to allocation risk when aviation demand surges.
- REACH chemical documentation burden:ECHA substance-of-very-high-concern listings require reformulation tracking across adhesive and gelcoat supply tiers, extending new product qualification timelines.
- Coastal skiff substitution by rigid inflatables:PVC-hull tenders from Zodiac and Brig are capturing day-rental operators seeking lower capital commitment and reduced dry-dock maintenance.
Strategic Opportunities
- Modular seating kayak derivatives:Stackable polyethylene shells are penetrating French and Spanish rental fleets, displacing traditional fixed-seat designs through containerized logistics efficiency.
- EU Green Deal hull-recycling mandates:Anticipated end-of-life producer responsibility frameworks will reward manufacturers establishing thermoplastic composite take-back programs before regulatory deadlines.
- Digital hull-scanning integration:Laser-based damage assessment tools are converging with mobile repair networks, enabling insurance-backed fleet management contracts for university programs.
Industry Challenges
- Composite technician apprenticeship gaps:German and Austrian vocational pipelines are failing to replace retiring laminators familiar with cold-molded wood-core construction.
- ISO 12217 Category C certification timelines:Stability testing for open-water skiff variants requires tank facilities in Southampton or Delft, creating bottlenecks for Mediterranean builders lacking in-house naval architecture capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recreational Rowing Boats Market |
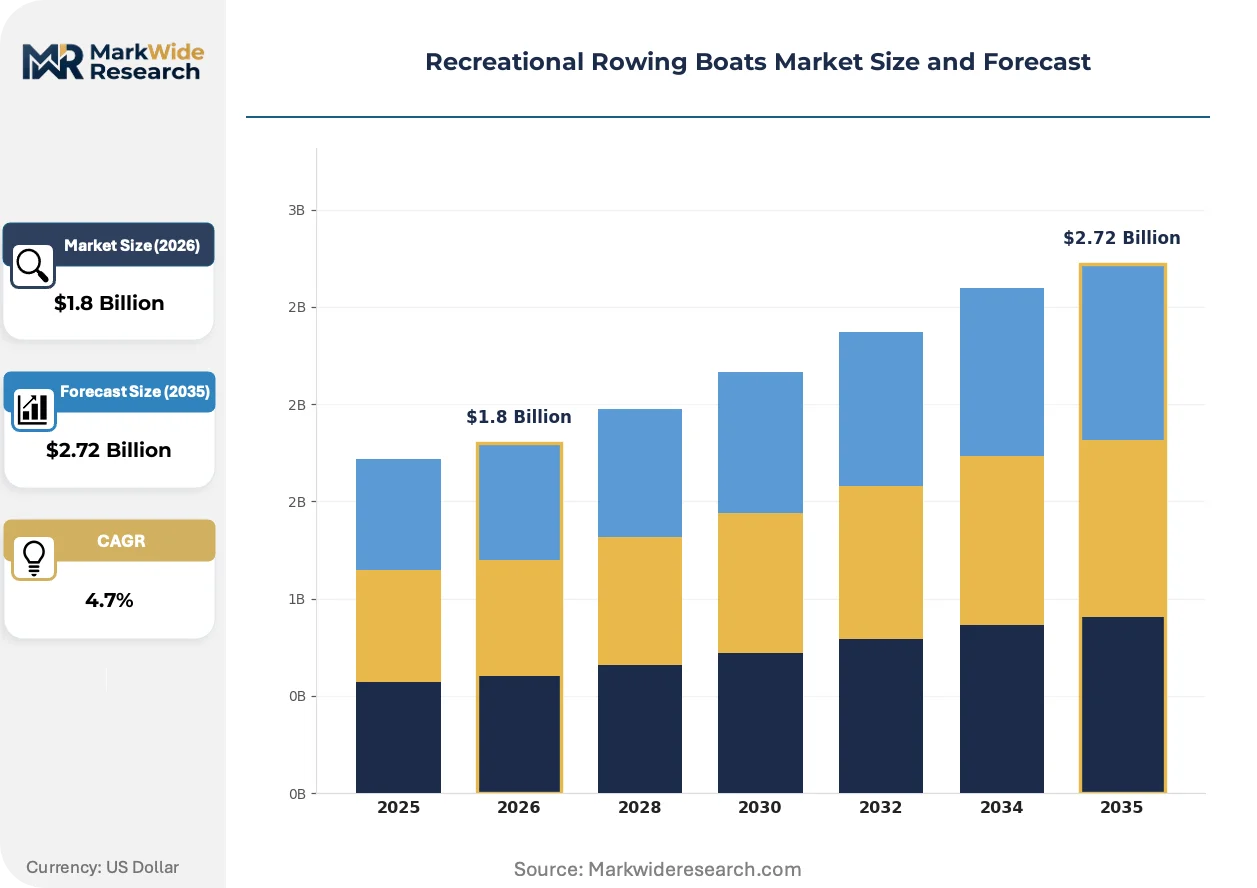
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boat Type: Kayak, Skiff, Dinghy, Canoe Material: Fiberglass, Aluminum, Wood, Plastic End User: Individual Consumers, Rental Companies, Educational Institutions, Clubs Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Trade Shows |
| Companies Covered | Empacher, FILIPPI LIDO SRL, Durham Boat Company, Whitehall Rowing & Sail, ECHO ROWING, Baumgarten Bootsbau, Leo Coastal, Vega Réalisations Composites, Kiwi International Rowing Skiffs Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recreational Rowing Boats Market Emerging Trajectories
Material substitution and regulatory stringency are converging to reshape hull construction economics, while downstream distribution channels fragment between direct-to-club sales and rental-fleet aggregators.
Prepreg carbon-fiber systems with automated fiber placement are electrifying elite-performance segment production. German university programs and national federation training centers are adopting these hulls for their stiffness-to-weight ratios. The technology is electrifying competitive procurement by compressing replacement cycles from ten-year intervals to five-year fleet turnover.
REACH Annex XVII restrictions on bisphenol-A in marine coatings are compelling gelcoat reformulation across EU production. Italian and Spanish manufacturers are shifting to vinylester barrier coats to maintain osmosis warranty terms. Coastal skiff builders serving Mediterranean charter operators face the steepest compliance cost escalation.
Boathouse procurement committees are consolidating vendor relationships around full-service fleet management agreements. Direct manufacturer relationships are displacing traditional marine distributor networks for orders exceeding twenty hulls. French municipal recreation authorities and Austrian rowing federations have pioneered this contractual structure.
Recreational Rowing Boats Market Segmentation
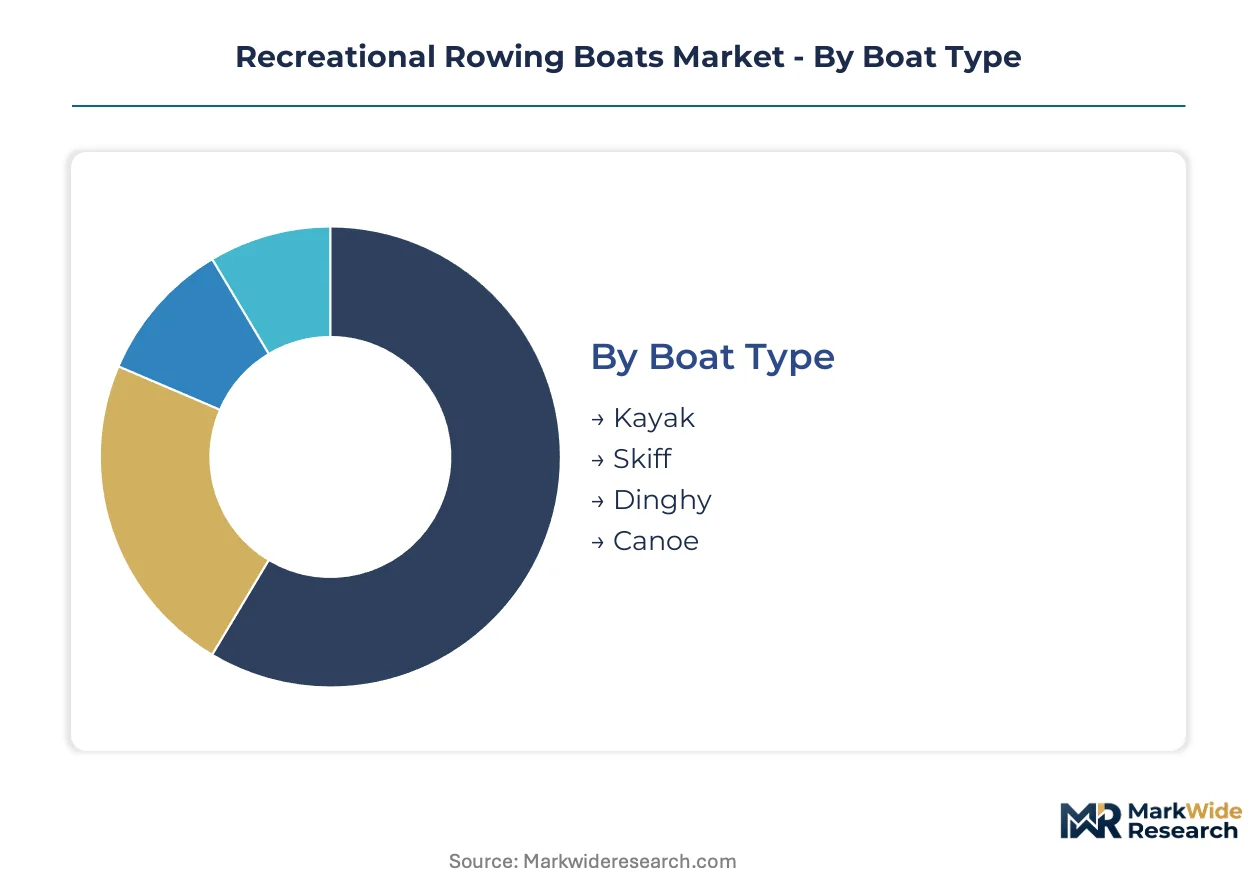
Recreational rowing boats fragment across four intersecting dimensions that reshape procurement economics. Boat type and material specifications determine hull certification pathways under ISO 12217, while end-user concentration in German and Austrian municipal programs redirects distribution channel investments.
Boat Type:
Supply concentration in coastal manufacturing clusters favors hull configurations with established certification infrastructure and repair networks.
- Skiff:Open-water designs with 4-8 meter hull lengths dominate Mediterranean charter fleets. Italian and Spanish coastal operators prioritize stability-certified variants for day-rental deployment, driving demand toward ISO 12217 Category C compliance.
- Kayak:Stackable polyethylene derivatives are penetrating French rental fleets through containerized logistics efficiency. Modular seating configurations allow single-hull inventory to serve solo and tandem users interchangeably.
- Dinghy:Compact tenders under 4 meters serve harbor-access programs and yacht clubs. German municipal recreation authorities specify these for youth introductory curricula.
- Canoe:Traditional open-cockpit designs retain heritage-focused demand in North American markets. Durham Boat Company sustains production through cold-molded wood-core construction methods.
Skiff configurations absorb the bulk of installed capacity; kayak derivatives are expanding most quickly.
Material:
Cost tier stratification separates premium performance procurement from volume fleet replacement cycles.
- Fiberglass:Hand-layup and resin-infusion processes enable cost-efficient mold replication. German community boathouses specify these hulls for training fleet renewal due to repair accessibility and gelcoat warranty terms.
- Carbon Fiber:Prepreg systems with automated fiber placement deliver stiffness-to-weight ratios below 35 kg per meter. University programs and national federation training centers concentrate procurement here.
- Aluminum:Welded hulls serve commercial rental operators seeking impact resistance and minimal dry-dock maintenance. Austrian lake districts specify these for heavy-use municipal fleets.
- Wood:Cold-molded and strip-plank construction retains niche demand among heritage preservation buyers. Craft production sustains limited output through specialized vocational programs.
- Plastic:Rotomolded polyethylene enables stackable storage and containerized shipping for rental aggregators. French and Spanish operators are displacing fixed-seat fiberglass inventory with these hulls.
Fiberglass retains the largest installed base; carbon fiber commands the steepest expansion trajectory.
End User:
Volume concentration among institutional buyers is compressing replacement cycles and consolidating vendor relationships.
- Rental Companies:Fleet aggregators in France and Spain prioritize stackable kayak derivatives and standardized maintenance protocols. Containerized logistics and modular seating reduce per-unit storage costs.
- Educational Institutions:German university rowing programs and Austrian technical colleges drive demand for multi-seat training shells. Direct manufacturer relationships are displacing traditional marine distributor networks for orders exceeding twenty hulls.
- Individual Consumers:Performance-oriented buyers concentrate in carbon-fiber segments, while leisure purchasers favor fiberglass cost efficiency. Heritage-focused segments sustain wood-hull demand.
- Clubs:Community boathouses across Germany and Austria are replacing aging inventories with REACH-compliant resin systems. Municipal procurement committees consolidate around full-service fleet management agreements.
Rental companies absorb the bulk of volume procurement; educational institutions are climbing the fastest.
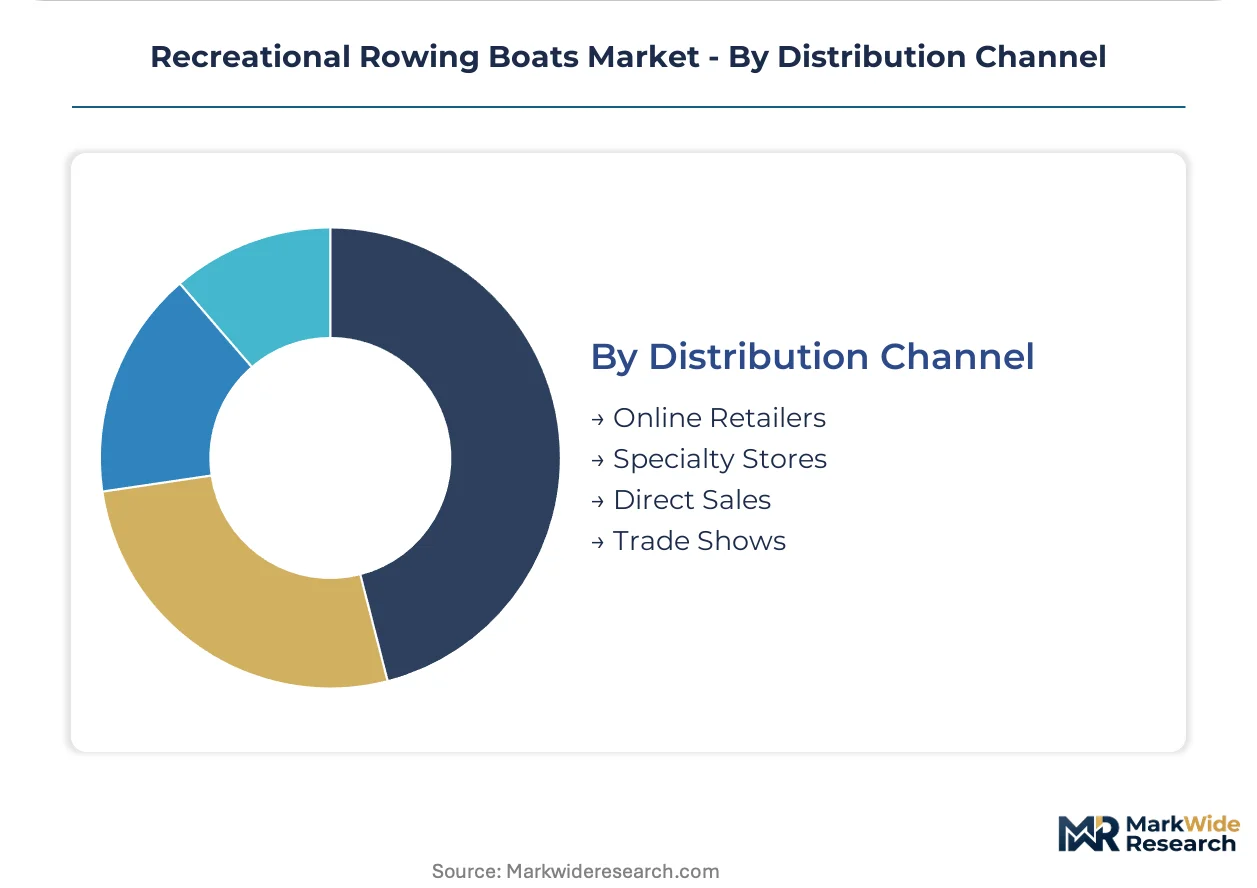
Distribution Channel:
Margin structure and customer acquisition cost differentiate channel investments across end-user segments.
- Direct Sales:Manufacturer relationships dominate institutional procurement above twenty-hull thresholds. French municipal recreation authorities pioneered full-service fleet management contracts through this channel.
- Specialty Stores:Regional marine retailers serve individual consumers requiring hands-on hull inspection. German and Italian coastal markets sustain these networks through service bundling.
- Online Retailers:Digital platforms capture accessory and small-craft sales with standardized shipping logistics. Kayak derivatives penetrate here due to modular packaging.
- Trade Shows:European regatta circuits and municipal procurement fairs concentrate annual order placement. Italian and Spanish manufacturers anchor Mediterranean visibility through these events.
Direct sales channel captures institutional volume; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university rowing programs and Austrian municipal boathouses concentrate fleet procurement demand, while Mediterranean charter operators and French rental aggregators reshape coastal distribution patterns.
Germany
Community boathouse fleet renewal drives multi-seat training shell procurement across Bavaria and Baden-Württemberg. ECHA REACH compliance mandates bio-epoxy resin reformulation in hull production. Empacher anchors manufacturing in the Stuttgart region with carbon-composite expertise serving national federation training centers.
France
Rental fleet aggregators prioritize stackable kayak derivatives for containerized logistics efficiency. The EU Green Deal anticipates hull-recycling producer responsibility frameworks. Mediterranean charter operators in Provence-Alpes-Côte d'Azur specify ISO 12217 Category C stability certification for open-water skiff deployment.
Italy
Coastal skiff production concentrates in Adriatic manufacturing clusters serving day-rental operators. REACH Annex XVII bisphenol-A restrictions compel vinylester gelcoat reformulation. FILIPPI LIDO SRL anchors supply from specialized yards in Veneto with heritage coastal craft expertise.
Austria
Lake district municipalities specify aluminum-hulled training fleets for heavy-use durability. National technical colleges drive demand for standardized multi-seat shells. Vienna and Upper Austria procurement committees consolidate around full-service fleet management agreements with direct manufacturer relationships.
United States
Heritage-focused buyers sustain demand for wood-strip construction methods in traditional rowing communities. The US Coast Guard enforces 33 CFR 183 flotation and labeling rules constraining material documentation. Durham Boat Company sustains North American presence through cold-molded wood-core craft production.
Recreational Rowing Boats Market Vendor Landscape
German producers anchor the performance tier; Italian specialists hold Mediterranean coastal positioning. The vendor base stratifies across three tiers: carbon-fiber elite-performance fabricators, fiberglass volume manufacturers, and heritage wood-craft specialists. Two dominant competitive moves are reshaping positioning: direct-to-institution fleet management contracting and REACH-compliant resin system reformulation.
Within the carbon-composite elite tier, Empacher and FILIPPI LIDO SRL represent contrasting geographic anchoring strategies. Empacher exemplifies German precision-engineering positioning with Stuttgart-region concentration, while FILIPPI LIDO SRL occupies Italian coastal craft specialization. Durham Boat Company anchors the heritage wood-construction archetype with North American presence.
| Leading Market Players |
|---|
| Empacher |
| FILIPPI LIDO SRL |
| Durham Boat Company |
| Whitehall Rowing & Sail |
| ECHO ROWING |
| Baumgarten Bootsbau |
| Leo Coastal |
| Vega Réalisations Composites |
| Kiwi International Rowing Skiffs Ltd |
| Others |
Supply Flow & Price Mechanics
Captive carbon-fiber precursor supply from Toray and Hexcel anchors both hull fabrication economics and manufacturer pricing power across European recreational rowing boat production. This upstream concentration forces hull fabricators into long-term offtake commitments that lock in material cost structures while ISO 12217 certification investments create tiered margin differentiation between elite-performance and volume fleet tiers.
Pricing Analysis
Volume procurement by German municipal boathouses compresses per-unit margins while carbon-fiber elite segments sustain premium positioning through stiffness-to-weight certification. Price differentiation hinges on ISO 12217 stability tier and REACH-compliant resin system documentation. Cost compression in fiberglass training hulls is intensifying because rental fleet aggregators consolidate orders around standardized maintenance protocols. Municipal recreation departments exhibit highest price sensitivity; national federation training centers show lowest.
Supply Chain Analysis
Direct-to-club channels handle institutional fleet demand above twenty-hull thresholds while specialty marine retailers serve individual inspection requirements. Manufacturing concentrates in Germany, Italy, and Austria. Hull fabrication draws from aerospace-grade carbon fiber, bio-epoxy resin systems, and vinylester gelcoat formulations. Single-source vulnerability runs through Toray-Hexcel precursor allocation when aviation demand surges. Distribution runs through full-service fleet management contracts pioneered by French municipal authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resin-infusion automation is displacing hand-layup legacy across recreational rowing boat manufacturing, compressing production cycles and recalibrating labor-skill requirements throughout European hull fabrication.
For Market Incumbents: Acquire composite technician training capacity to address German and Austrian vocational pipeline gaps. Secure REACH-compliant resin formulation IP ahead of ECHA substance-of-very-high-concern listings. Defensive consolidation around automated fiber placement technology counters emerging entrants with vacuum-assisted transfer molding capabilities.
For New Entrants and Emerging Players: French rental fleet aggregators seeking stackable kayak derivatives represent the most penetrable buyer archetype. Target containerized logistics efficiency as the go-to-market wedge against fixed-seat fiberglass incumbents. Modular seating configurations and thermoplastic composite take-back programs open white-space positioning ahead of EU Green Deal hull-recycling mandates.
For Investors and Strategic Acquirers: Exit pathways concentrate in fleet management contract aggregators with direct municipal relationships. Long-term viability favors manufacturers with backward integration into bio-epoxy resin systems and in-house ISO 12217 certification capacity. Watch ECHA substance-of-very-high-concern listing velocity as the inflection signal for reformulation cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Resin-Infusion Automation Investment | Vacuum-assisted transfer molding reduces void rates in carbon-fiber laminates for Empacher-grade consistency. |
| REACH-Compliant Resin Reformulation | Bio-epoxy adoption in German hull production creates first-mover supply chain advantages under ECHA mandates. |
| Fleet Management Contract Expansion | Full-service agreements with French municipal authorities displace traditional marine distributor networks. |
| Modular Seating Kayak Development | Stackable polyethylene shells penetrate Spanish rental fleets through containerized logistics efficiency. |
| Thermoplastic Composite Take-Back Program | Producer responsibility frameworks ahead of EU Green Deal deadlines reward end-of-life hull recycling infrastructure. |
Methodological Framework
Trade publications, customs databases, and ECHA regulatory filings formed the secondary backbone of this analysis. Primary interviews with hull fabrication plant managers, municipal procurement committee chairs, composite supplier sales directors, and university rowing program fleet managers combined with secondary validation across ISO 12217 certification records and REACH Annex XVII substance listings. Bottom-up hull shipment tallies and top-down recreational marine equipment expenditure estimates were triangulated to anchor market sizing.
Bottom-up modeling of hull configurations by material tier and end-user concentration was cross-checked against top-down European recreational boating expenditure patterns across the projection horizon. Segmentation dimensions included boat type, material specification, end-user category, and distribution channel. CAGRs were derived from fleet replacement cycle compression and municipal procurement committee consolidation trends. Forecast inputs incorporated resin-infusion automation adoption curves and ECHA substance listing timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aviation carbon fiber allocation surges and EU hull-recycling mandate implementation timing. Forecasts reflect documented assumptions regarding municipal budget continuity and REACH compliance cost pass-through. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Kneeboard Market
Sports Equipment
US Fencing Market
Sports Equipment
Bowling Lane Panels Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
North America Sporting Goods Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Europe Archery Equipment Market
Sports Equipment
France Artificial Turf Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Golf Club Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Waist Support Belt Market