
 Gym Bag Market | 2026-2036
Gym Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Gym Bag Market Analysis
Premium ballistic nylon construction is unwinding the commodity tier that long dominated mass retail. Under Armour leverages vertical integration into performance fabric mills to control cost and quality at scale. GoRuck anchors its position through military-spec durability standards and direct-to-consumer channel control. King Kong differentiates with reinforced stitching protocols tested to extreme load capacities.
A gym bag is a purpose-built carrier engineered from woven synthetics or treated natural fibers, typically featuring ventilated compartments, water-resistant base panels, and ergonomic shoulder systems designed to transport athletic equipment, footwear, and apparel between training facilities and domestic or workplace destinations. Duffel bags and backpacks together constitute the dominant volume architecture, with sling bags representing the fastest-expanding format among urban commuters seeking minimal footprint. Nylon and polyester command the largest material share, though canvas is gaining traction in lifestyle-positioned lines where tactile authenticity supports price premiums.
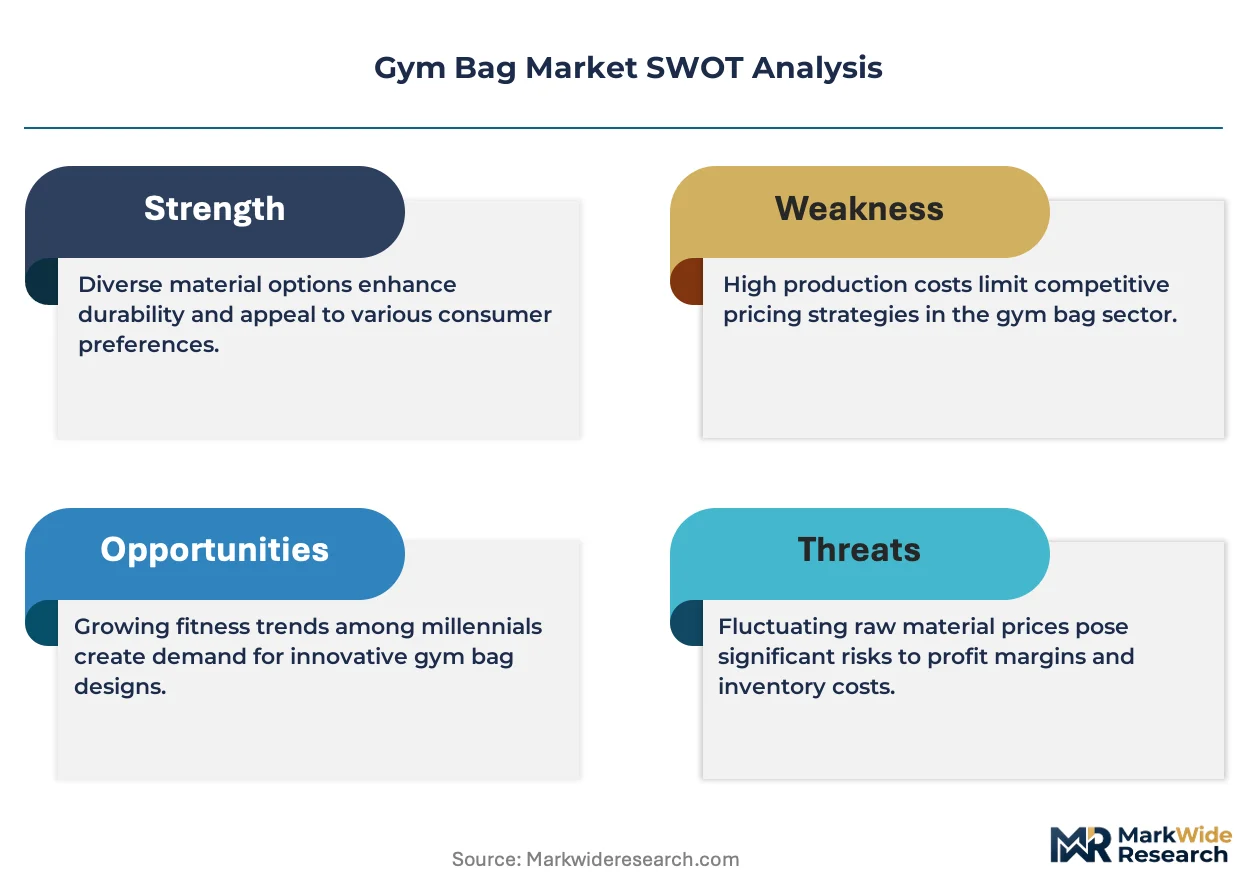
REACH compliance obligations in Europe, California Proposition 65 disclosure requirements in the United States, and China's GB standards for textile formaldehyde limits collectively elevate testing burdens and reshape supplier qualification protocols for brands seeking multi-territory distribution. The EU Green Deal's circular economy action plan is accelerating demand for recycled-content certification and take-back program infrastructure. Stakeholders must now decide whether to absorb compliance costs across portfolio pricing or concentrate premium positioning in jurisdictions with the most stringent enforcement trajectories.
Market Dynamics
REACH compliance obligations and the EU Green Deal's circular economy mandates are forcing material substitutions across the supply base, compressing margins for uncertified producers while rewarding early movers into recycled-content feedstocks.
Growth Catalysts
- Boutique Fitness Expansion:Specialized studios in Germany and the United States are driving purpose-built equipment carrier demand through branded retail partnerships and member loyalty programs.
- REACH Chemical Standards:ECHA enforcement of low-VOC coating requirements is accelerating certified supplier qualification and pushing brands toward verified recycled nylon supply chains.
- Urban Commuter Patterns:Compact sling formats are gaining adoption among professionals integrating gym visits into multi-stop daily routines across dense metropolitan clusters.
Market Restraints
- Ballistic Nylon Cost Volatility:Petroleum-derived synthetic feedstocks expose margin structures to crude price swings and polymer supply disruptions.
- Asian Supply Concentration:Woven fabric and hardware component manufacturing clusters heavily in Guangdong and Zhejiang provinces, creating single-region vulnerability.
- California Proposition 65:Disclosure requirements for chemical content impose litigation risk and labeling complexity for brands distributing in the United States.
Strategic Opportunities
- EU Take-Back Infrastructure:The Green Deal's extended producer responsibility frameworks create first-mover advantage for brands building closed-loop collection and reprocessing systems.
- Smart Textile Integration:Convergence of RFID tracking and antimicrobial fiber treatments enables premium positioning through loss-prevention and hygiene-verification features.
- Direct-to-Consumer Channels:Owned digital storefronts bypass wholesale margin compression and capture behavioral data for personalization.
Industry Challenges
- Recycled Content Verification:GRS and Bluesign certification timelines stretch 8-14 months, delaying product launches and locking working capital in pre-qualified inventory.
- Multi-Territory Testing Burden:Simultaneous compliance with REACH, GB standards, and Proposition 65 requires redundant laboratory protocols and fragmented supplier audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gym Bag Market |
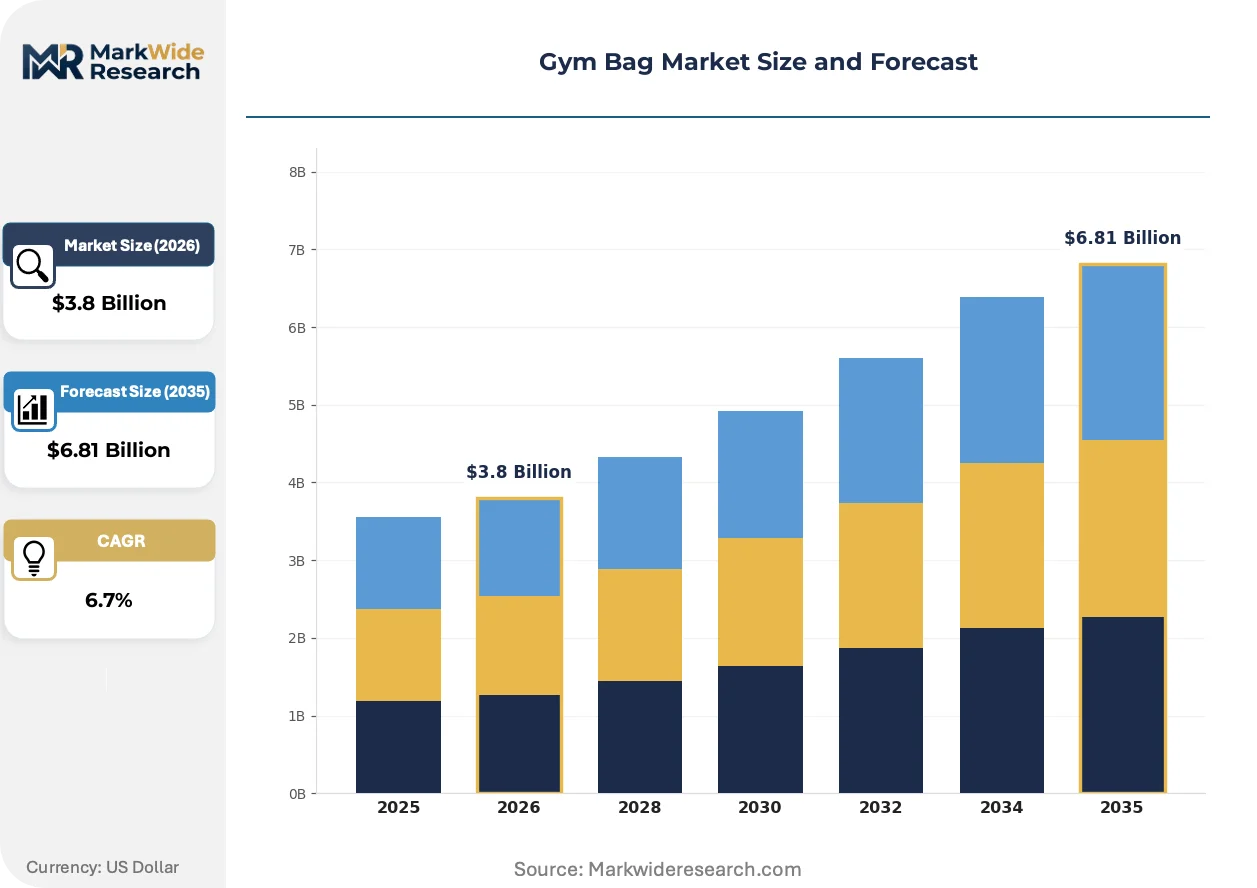
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Duffel Bags, Backpacks, Tote Bags, Sling Bags Material: Nylon, Polyester, Canvas, Leather Size: Small, Medium, Large, Extra Large End User: Men, Women, Children, Fitness Enthusiasts |
| Companies Covered | Under Armour, Adidas, GoRuck, King Kong, KNKG, NOBULL, Nike, High Sierra, Lululemon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gym Bag Market Emerging Trajectories
Material science advances and regulatory stringency are splitting the market into certified premium tiers and compliance-lagging commodity segments, with durability claims now requiring third-party verification.
Recycled ocean-bound nylon is bifurcating the material tier. Econyl and comparable regenerated polymers now command 35-40% price premiums over virgin feedstock. Premium athletic brands and outdoor specialists are adopting these inputs for flagship lines, compressing demand for uncertified conventional nylons in the mid-market.
REACH substance restrictions are tightening enforcement trajectories across EU member states. ECHA's 2023-2027 rolling action plan targets PFAS and phthalate elimination in textile coatings. German distributors and French retail chains are now requiring full material disclosure documentation, forcing Asian contract manufacturers to upgrade testing capabilities or lose shelf placement.
Subscription-based equipment rental is disrupting traditional ownership patterns among urban professionals. CrossFit affiliates and boutique cycling studios in London and New York are piloting member-inclusive bag programs, replacing individual purchase decisions with bundled access fees. This model concentrates procurement authority with facility operators, shifting volume toward bulk contract suppliers capable of co-branded customization.
Gym Bag Market Segmentation
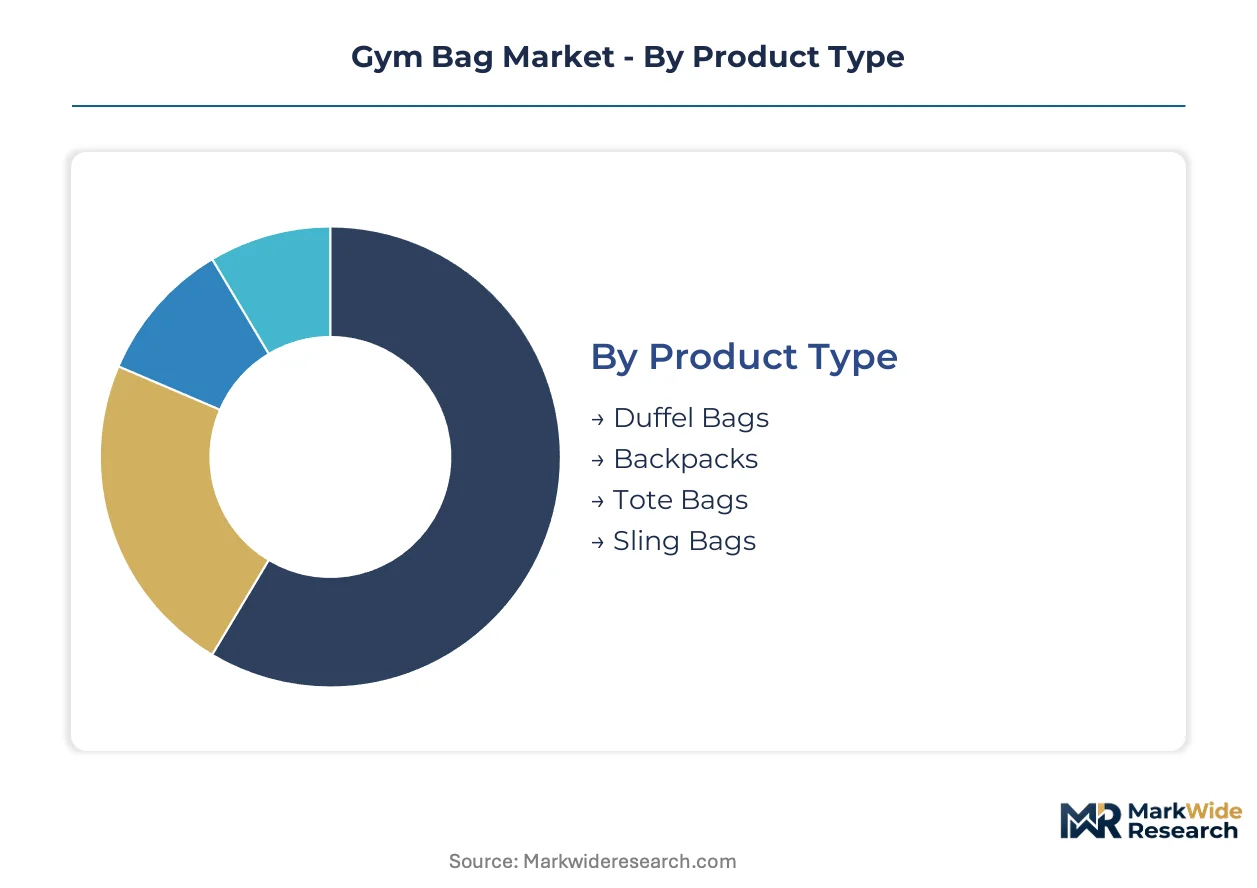
Gym bag segmentation reveals how equipment transport needs fragment across training modalities, commute patterns, and material preferences. Manufacturers configure product portfolios around these divides to capture volume in core formats while staking positions in emerging niches.
Product Type:
Duffel bags face intensifying substitution pressure from backpacks as urban commuters prioritize hands-free mobility and ergonomic load distribution across multi-stop daily routines.
- Duffel Bags:Cylindrical or rectangular soft-sided carriers with single or dual grab handles and detachable shoulder straps, typically 40-80 liter capacity. Demand concentrates in Germany and United States boutique fitness studios where members transport bulky equipment between facilities and home.
- Backpacks:Dual-strap systems with framed or frameless suspension, featuring ventilated back panels and hip belts for load transfer. German urban professionals integrating gym visits into workplace commutes drive adoption of technical daypack formats with shoe compartments and laptop sleeves.
- Tote Bags:Open-top or zippered rectangular carriers with parallel grab handles, generally unstructured and sub-30 liter capacity. Yoga practitioners and pilates attendees in London metropolitan clusters favor these for mat transport and light apparel.
- Sling Bags:Single-strap asymmetric designs worn across the chest or back, minimizing footprint for minimal equipment loads. New York and Tokyo dense transit corridors generate demand among professionals seeking compact solutions for post-work training sessions.
Duffel bags retain volume leadership; sling bags hold the steepest expansion curve.
Material:
Cost tier differentiation separates certified recycled feedstocks commanding premium positioning from commodity synthetics competing on unit economics.
- Nylon:Polyamide 6 or 6,6 woven fabrics with denier ratings from 210D to 1680D ballistic weaves, treated with DWR coatings. REACH-compliant low-VOC coating requirements in Germany are accelerating verified recycled nylon adoption for flagship product lines.
- Polyester:PET-based woven or knitted fabrics, generally lower cost than nylon with comparable abrasion resistance at equivalent deniers. Mass retail channels in United States big-box stores concentrate volume for price-sensitive recreational users.
- Canvas:Heavy cotton duck or blended natural fiber weaves, often waxed or oil-treated for water resistance. Lifestyle-positioned brands targeting tactile authenticity and heritage aesthetics command price premiums in Japanese and French markets.
- Leather:Full-grain or top-grain bovine hides, occasionally exotic materials, with natural patina development. Executive fitness segments in Swiss and UAE metropolitan centers sustain niche demand for luxury-positioned carriers.
Nylon dominates absolute volume; canvas is climbing the fastest among lifestyle-positioned tiers.
Size:
Application-driven selection patterns split between compact formats for single-session needs and expedition-scale carriers for multi-day training blocks.
- Small:Sub-25 liter capacity, generally sling or compact tote architectures. Boutique cycling studios in London bundle these with membership tiers for shoe and accessory transport.
- Medium:25-45 liter range accommodating single change of clothes, footwear, and basic equipment. Standard daily gym users across German metropolitan clusters drive baseline volume.
- Large:45-75 liter capacity for extended equipment sets, multiple footwear pairs, or towel service needs. CrossFit affiliates in United States suburban markets specify these for member retail programs.
- Extra Large:75+ liter expedition formats for competitive athletes traveling to events with full kit. National team programs and professional training camps in France and Australia sustain specialized procurement.
Medium formats retain volume leadership; extra large holds the steepest expansion curve among competitive athlete segments.
End User:
Customer type segmentation exposes divergent feature priorities across gendered design conventions and life-stage equipment needs.
- Men:Traditional duffel and backpack dominance with emphasis on capacity ratings and hardware durability. German and United States male fitness enthusiasts drive technical feature adoption including ventilated shoe tunnels and integrated lock systems.
- Women:Cross-body totes and convertible backpacks with aesthetic customization and compartmentalization for personal items. Boutique studio partnerships in New York and Los Angeles concentrate demand for co-branded lifestyle formats.
- Children:Scaled-down capacities with safety features including reflective elements and breakaway straps. School-sport program specifications in Japan and South Korea drive institutional procurement cycles.
- Fitness Enthusiasts:Performance-optimized technical users prioritizing function over fashion across all formats. EMEA and North America specialty retail channels serve this segment with premium materials and modular accessory systems.
Men's segments retain volume leadership; fitness enthusiasts hold the steepest expansion curve as training modality diversification accelerates equipment specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: German buyers absorb 35-40% premiums for certified recycled materials, while United States mass retail channels prioritize unit economics over sustainability credentials.
United States
Boutique fitness studios and CrossFit affiliates drive purpose-built carrier demand through co-branded member retail programs. California Proposition 65 imposes chemical disclosure requirements that elevate litigation risk for brands distributing nationally. Manufacturing specification authority concentrates in Los Angeles and New York metropolitan clusters where studio operators negotiate bulk procurement contracts.
Germany
Premium athletic accessories command strong brand loyalty and higher average transaction values than any other European market. ECHA enforcement of REACH low-VOC coating requirements accelerates verified recycled nylon adoption across flagship product lines. Berlin and Munich studio networks specify German-designed carriers for member equipment transport, reinforcing domestic manufacturer preference.
China
GB standards for textile formaldehyde limits reshape supplier qualification protocols for brands seeking multi-territory distribution. Guangdong and Zhejiang provinces host woven fabric and hardware component manufacturing clusters that supply global assembly operations. Domestic demand remains price-sensitive, with local brands competing on volume scale rather than certification premiums.
United Kingdom
Subscription-based equipment rental models disrupt traditional ownership patterns among London urban professionals. The UK's post-EU regulatory alignment with REACH substance restrictions maintains testing burdens for imported textile goods. Boutique cycling studios in the capital pilot member-inclusive bag programs, shifting procurement authority toward facility operators.
Japan
Lifestyle-positioned canvas formats gain traction among consumers prioritizing tactile authenticity and heritage aesthetics. METI guidelines on product safety and labeling create compliance entry barriers for foreign brands. Tokyo metropolitan clusters generate concentrated demand for compact sling architectures suited to dense transit corridors.
Gym Bag Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated performance fabric specialists controlling material innovation while Asian contract manufacturers dominate volume production. The market structures around three tiers: premium athletic brands with direct-to-consumer channels, mid-market outdoor specialists emphasizing durability verification, and mass retail private labels competing on price positioning. Dominant competitive moves include strategic partnerships with certified recycled feedstock suppliers and portfolio diversification into smart textile integration.
Within the premium athletic tier, Under Armour and Nike represent vertically integrated archetypes with in-house performance fabric production, while GoRuck exemplifies the durability-specialist position anchored to military-specification standards. Adidas occupies a bridging position across performance and lifestyle segments, leveraging global brand recognition to command shelf placement in multi-territory distribution.
| Leading Market Players |
|---|
| Under Armour |
| Adidas |
| GoRuck |
| King Kong |
| KNKG |
| NOBULL |
| Nike |
| High Sierra |
| Lululemon |
| Others |
Supply Flow & Price Mechanics
REACH substance restrictions gate both supplier qualification timelines and price differentiation simultaneously. ECHA enforcement of low-VOC coating requirements forces brands to absorb certification costs or concentrate premium positioning in German and French retail channels where disclosure documentation commands shelf placement.
Pricing Analysis
After-sales service revenue through take-back program enrollment and repair networks drives lifetime value in certified product lines. Three-tier pricing structure across premium, standard, and economy levels separates Bluesign-verified recycled nylon SKUs from conventional ballistic nylon and commodity polyester tiers. Cost compression in the mid-market is intensifying because Econyl and comparable regenerated polymers command feedstock premiums that uncertified producers cannot pass through to price-sensitive United States mass retail buyers. Boutique fitness studios in Germany absorb the highest price premiums while big-box recreational users in North America prioritize unit economics.
Supply Chain Analysis
Yarn extrusion capacity in Guangdong province underwrites global woven fabric availability for performance bag manufacturers. Woven fabric production clusters in China's Guangdong and Zhejiang provinces, with hardware component sourcing anchored in Taiwan and South Korea. Raw material dependencies draw from petroleum-derived polyamide feedstocks, recycled ocean-bound nylon regeneration facilities, and DWR coating chemical suppliers. Single-region vulnerability concentrates risk in Guangdong's polymer processing infrastructure. Distribution runs through direct-to-consumer digital storefronts and specialty retail channels in Germany, United States, and United Kingdom metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gym bag market functions as a defensive-moat story where regulatory entrenchment in REACH compliance creates switching costs that lock studio operators into verified supplier relationships.
For Market Incumbents: Fortify position through captive supply of GRS-certified recycled nylon feedstocks and backward integration into performance fabric mills. ECHA's 2023-2027 rolling action plan targeting PFAS elimination threatens commodity coating suppliers. Certification investment in Bluesign and GRS protocols locks working capital but secures German and French retail placement against emerging competitors. For New Entrants and Emerging Players: Anchor in subscription-based equipment rental programs piloted by London and New York boutique cycling studios. The most penetrable segment lies in co-branded compact sling formats for urban professionals integrating gym visits into multi-stop commutes. A direct-to-consumer launch with RFID-enabled loss-prevention features bypasses wholesale margin compression. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across verified recycled-content supply chains as certification timelines stretch working capital deployment. Long-term viability favors brands with established take-back infrastructure and closed-loop reprocessing partnerships. Acquisition target archetypes include mid-market durability specialists with military-specification testing protocols. The signal to watch is ECHA enforcement trajectory on material disclosure documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Recycled Feedstock Partnership | GRS and Bluesign verification secures German retail placement against REACH enforcement. |
| Direct-to-Consumer Channel Expansion | Owned digital storefronts capture behavioral data for personalization in United States urban markets. |
| Smart Textile Integration | RFID tracking and antimicrobial treatments enable premium positioning through hygiene verification. |
| Take-Back Program Infrastructure | EU Green Deal extended producer responsibility frameworks reward first-mover closed-loop systems. |
| Boutique Studio Co-Branding | CrossFit and cycling studio partnerships concentrate procurement authority with facility operators. |
Methodological Framework
Operator-level perspectives from brand managers, category buyers at German and United States specialty retailers, supply planners at woven fabric mills, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from customs records, ECHA substance restriction databases, and SEC 10-K filings of vertically integrated athletic brands. Bottom-up and top-down triangulation cross-checked volume assumptions against production capacity disclosures and retail audit data.
Sensitivity analysis tested forecast robustness across alternative regulatory enforcement scenarios and feedstock price volatility assumptions. Segmentation dimensions modeled include product architecture, material certification tier, end-user training modality, and regional regulatory cluster. CAGRs were derived from trend extrapolation of adoption curves across the projection horizon. Industry-specific forecast inputs incorporated ECHA rolling action plan substance restriction timelines and boutique fitness studio expansion trajectories.
Decision-makers should treat outputs as directional under sustained REACH enforcement and stable polymer feedstock availability assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA substance restriction expansion and recycled nylon supply capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
Skydiving Equipment Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Soccer Gear Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
US Fencing Market
Sports Equipment
Ice Cleat Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Slam Ball Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Baseball Equipment Market