
 Golf Gloves Market | 2026-2036
Golf Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Gloves Market Intelligence
A shift from single-source manufacturing to a diversified, multi-source supplier model is pivoting how brands manage production costs and supply chain resilience. Acushnet Holdings Corp., through its Titleist and FootJoy brands, leverages its scale to control premium material sourcing. TaylorMade Golf Company differentiates with technology-infused designs aimed at performance optimization. Nike sustains its market position through extensive global distribution and cross-promotional marketing with its other sports apparel.
A golf glove is a piece of technical apparel designed to enhance a player's grip on the club, reduce friction, and absorb moisture. Construction often involves thin, high-quality cabretta leather or advanced synthetic materials engineered for specific tackiness and breathability. The leather material segment commands the premium end of the market, especially within performance gloves. Synthetic and microfiber materials are expanding rapidly in the training and rain gloves categories due to superior durability and all-weather functionality.
Product safety and material claims fall under the purview of consumer protection bodies like the US Federal Trade Commission (FTC) regarding advertising. In Europe, chemical usage in textiles and leathers is governed by the REACH regulation, impacting material choices for manufacturers. The critical strategic decision for brands revolves around managing the material mix to meet performance expectations across different price points.
Market Dynamics
The primary structural force is the tension between the performance attributes of premium natural leathers and the cost-efficiency and all-weather durability of advanced synthetic materials. This dynamic shapes product segmentation, sourcing strategies, and brand positioning across the market.
Growth Catalysts
- Rising Participation:Increased golf engagement, especially among amateur and youth demographics in developed markets like the United States and Japan, directly expands the consumer base for all glove types.
- Material Science Advances:Innovations in breathable, moisture-wicking synthetic fabrics and hybrid leather-synthetic constructions enhance comfort and performance, attracting new buyers and encouraging upgrades.
- Golf Tourism Expansion:The growth of golf tourism in destinations with favorable climates creates consistent, year-round demand for gloves, particularly all-weather and UV-protective models.
Market Restraints
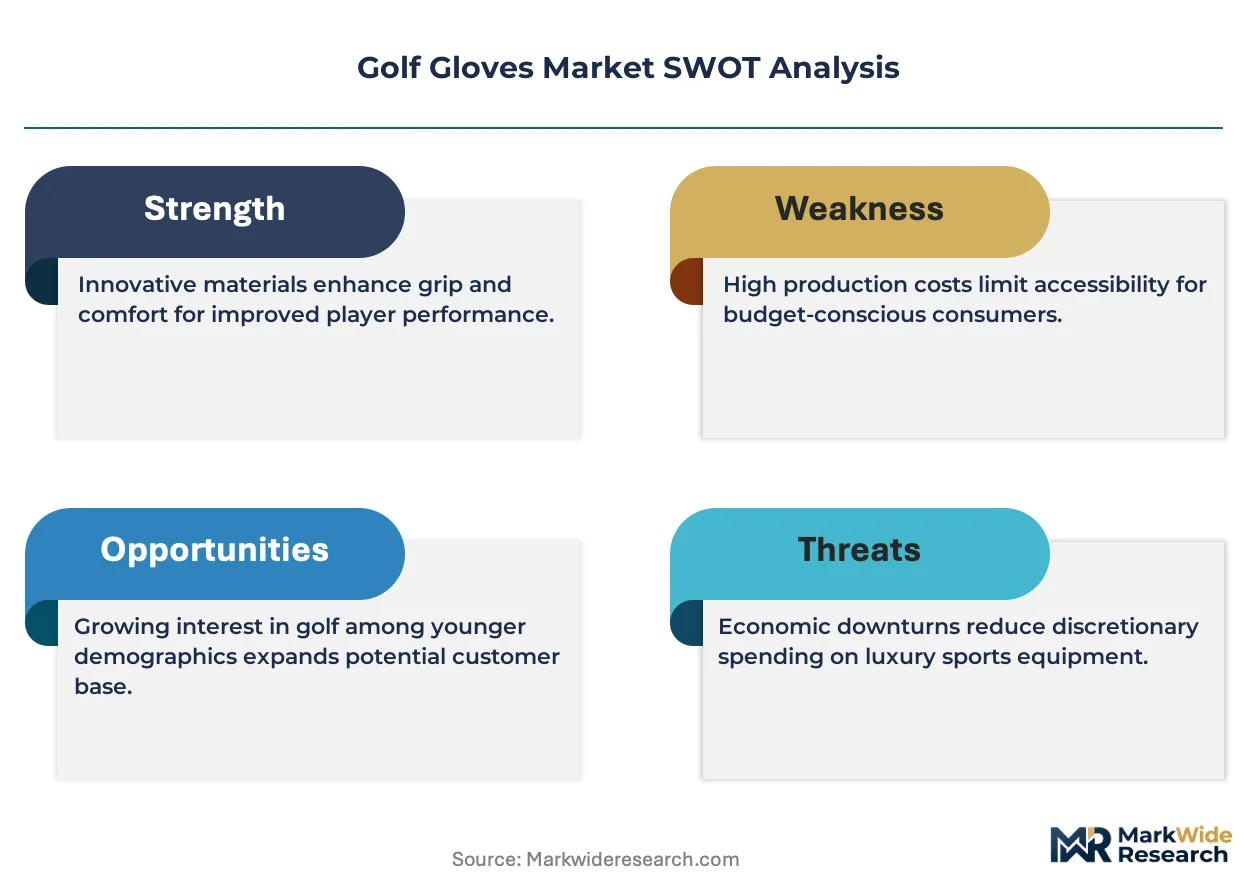
- Cabretta Leather Volatility:The price and supply of high-grade cabretta leather, a key premium input, are subject to significant fluctuations, impacting gross margins for performance gloves.
- Substitution Risk:Some players opt for no-glove techniques or lower-cost, non-specialized sports gloves, limiting market penetration at the entry-level and in casual play segments.
- Regulatory Compliance Costs:Adherence to chemical regulations like the EU's REACH for leather tanning and textile dyeing adds complexity and cost to manufacturing processes for global brands.
Strategic Opportunities
- Emerging Golf Economies:Untapped demand in developing golf regions, particularly across Southeast Asia and the Middle East, presents significant geographic expansion potential for established and new brands.
- Smart Glove Development:Integrating micro-sensors for swing path and grip pressure analysis creates a new high-margin category aimed at the tech-savvy player and the professional coaching market.
- Simulator-Specific Designs:The expansion of indoor golf creates an opportunity for gloves designed specifically for simulator use, focusing on durability and consistent grip without weather-resistance features.
Industry Challenges
- Supply Chain Consistency:Managing quality and material consistency across a diversified, multi-source supplier base, especially for natural leathers sourced from various regions, poses a significant operational hurdle.
- Counterfeit Product Mitigation:The prevalence of counterfeit premium gloves, particularly in online marketplaces, erodes brand value and requires constant monitoring and legal enforcement actions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Gloves Market |
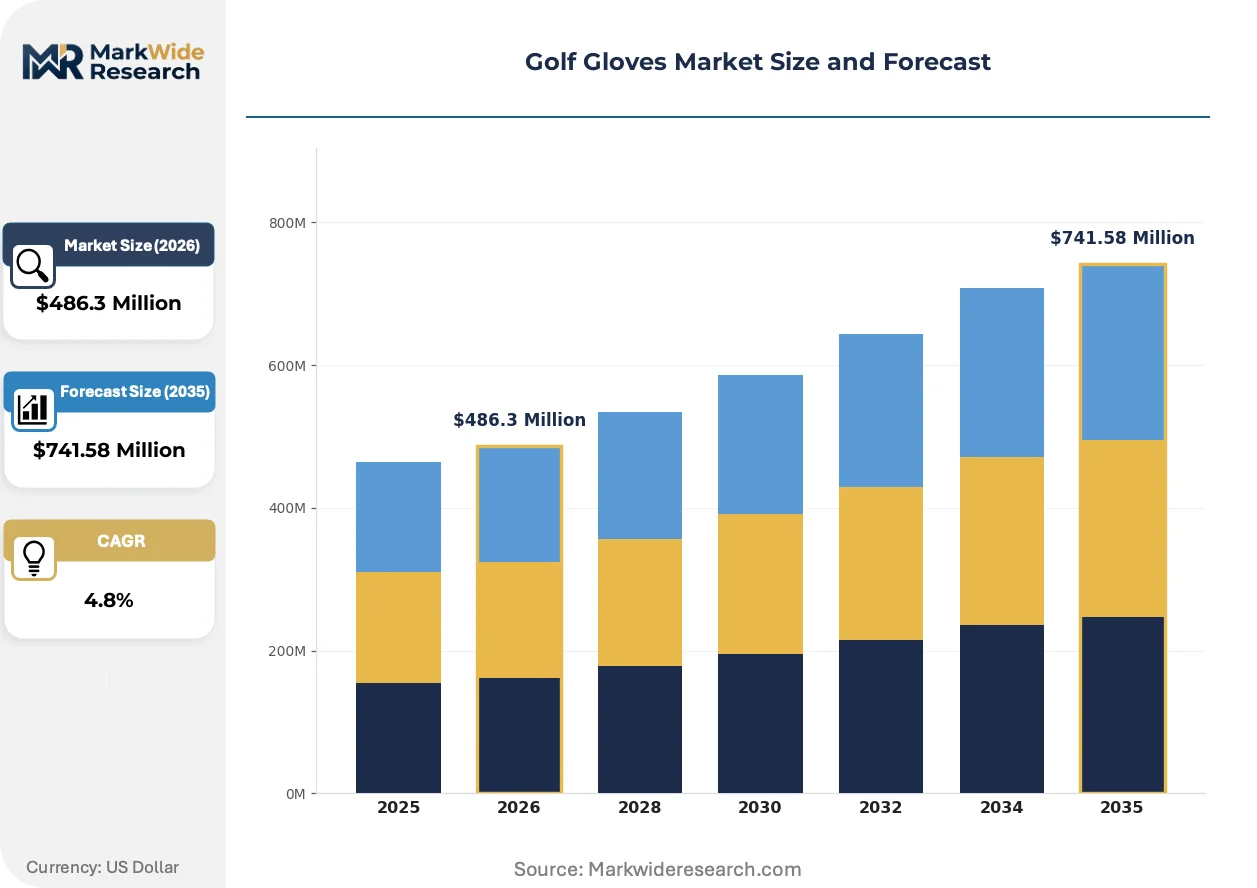
| Market Size in 2026 | $486.3 Million |
| Market Size in 2035 | $741.58 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Winter Gloves, Training Gloves, Performance Gloves, Rain Gloves Material: Leather, Synthetic, Cotton, Microfiber Size: Small, Medium, Large, Extra Large Gender: Men, Women, Unisex, Youth |
| Companies Covered | FootJoy, Callaway Golf Company, Acushnet Holdings Corp., Titleist, Nike, TaylorMade Golf Company, Srixon, Under Armour, Zero Friction, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Gloves Market Strategic Shifts & Innovations
Material science advancements are converging with data analytics to redefine what a golf glove can offer beyond basic grip. This shift moves the product from a simple accessory to a performance enhancement tool, influencing design, manufacturing, and marketing strategies across the industry.
Sensor-infused fabrics embed microelectronics to capture data on grip pressure, club position, and swing tempo. Performance-oriented amateurs and professional instructors are the primary adopters of this technology. This integration of live feedback is electrifying the golf instruction market by providing quantifiable data for player development and club fitting.
Europe's REACH regulation imposes strict controls on chemicals used in textile and leather production, including certain dyes and tanning agents. This forces manufacturers to re-evaluate their material suppliers and production processes to ensure market access. The performance leather segment is most affected, requiring investment in compliant and sustainable tanning methods to serve this key region.
A pronounced shift toward direct-to-consumer (DTC) purchasing models is disrupting established retail channels. This trend allows digital-native brands to bypass traditional pro shops and large sporting goods retailers, often offering subscription services and customized fittings online. This is most visible in North America, where e-commerce penetration in sporting goods is highest among consumers.
Golf Gloves Market Segmentation
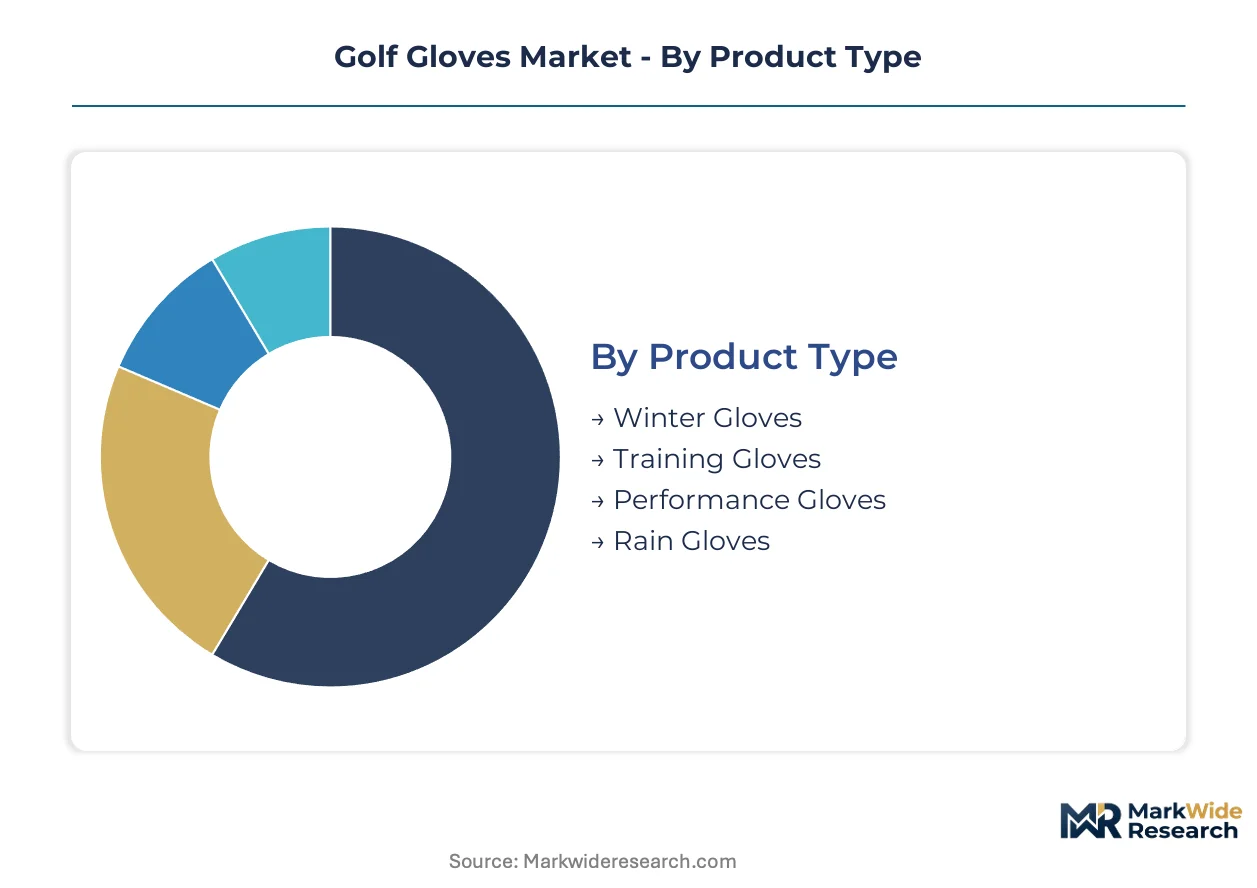
Market segmentation for golf gloves is essential for manufacturers to tailor product development, pricing strategies, and distribution channels. This granular view allows brands to address the specific demands of diverse player demographics and performance needs across various golfing conditions. Understanding these segments drives targeted innovation and market penetration.
Product Type:
The product type segmentation highlights how compliance with material claims and performance standards influences market access and consumer trust, particularly for specialized gloves.
- Performance Gloves:These gloves are engineered for optimal grip, feel, and moisture management, often incorporating advanced materials like premium cabretta leather or high-tech synthetics. Demand concentrates among professional and serious amateur players in competitive environments, where product claims are scrutinized by bodies like the US Federal Trade Commission.
- Training Gloves:Designed for durability and often integrating features for swing analysis or grip pressure feedback, these gloves prioritize longevity over extreme tactile sensitivity. Demand is strong among amateur golfers and in golf academies, driven by the desire for skill improvement and the integration of smart technology.
- Winter Gloves:Constructed with insulating materials to provide warmth and maintain grip in cold weather conditions.
- Rain Gloves:Specifically designed with water-resistant or hydrophobic materials to enhance grip in wet playing conditions.
Performance Gloves sits at the top of the volume ranking, with Training Gloves climbing the fastest.
Material:
Material segmentation reveals a critical tension between cost efficiency, performance attributes, and regulatory compliance, shaping the pricing tiers across the market.
- Leather:Typically made from cabretta leather, offering superior feel, softness, and natural breathability, often requiring specific tanning processes. Demand is concentrated in the premium segment and among players prioritizing traditional feel, though subject to EU REACH chemical regulations.
- Synthetic:Constructed from advanced synthetic fabrics, providing enhanced durability, all-weather performance, and consistent grip, often at a lower cost point. Demand is expanding rapidly in the training and recreational segments, where cost-effectiveness and versatility are prized.
- Cotton:Offers basic grip and comfort, primarily used in entry-level or casual-use gloves.
- Microfiber:Known for moisture-wicking properties and a soft texture, often blended with other materials for enhanced performance.
Leather materials command a significant share, while synthetic alternatives are rapidly gaining traction.
Size:
Segmentation by size reflects the diverse anthropometric requirements of golfers, influencing manufacturing precision and inventory management for global distribution.
- Medium:Represents a broad segment of the golfing population, designed to fit average adult hand sizes for comfort and consistent club control. Demand is widespread across all player levels, making it a high-volume category for manufacturers.
- Large:Caters to golfers with larger hand dimensions, providing extended coverage and ensuring a secure fit without restricting movement. Demand is consistent in established golf markets like the United States and the United Kingdom, where a significant portion of the male golfing population requires this size.
- Small:Tailored for players with smaller hands, including many women and some youth golfers.
- Extra Large:Designed for the largest hand sizes, offering maximum coverage and a specialized fit for specific player needs.
Accurate sizing is critical for player performance, influencing inventory management and brand loyalty.
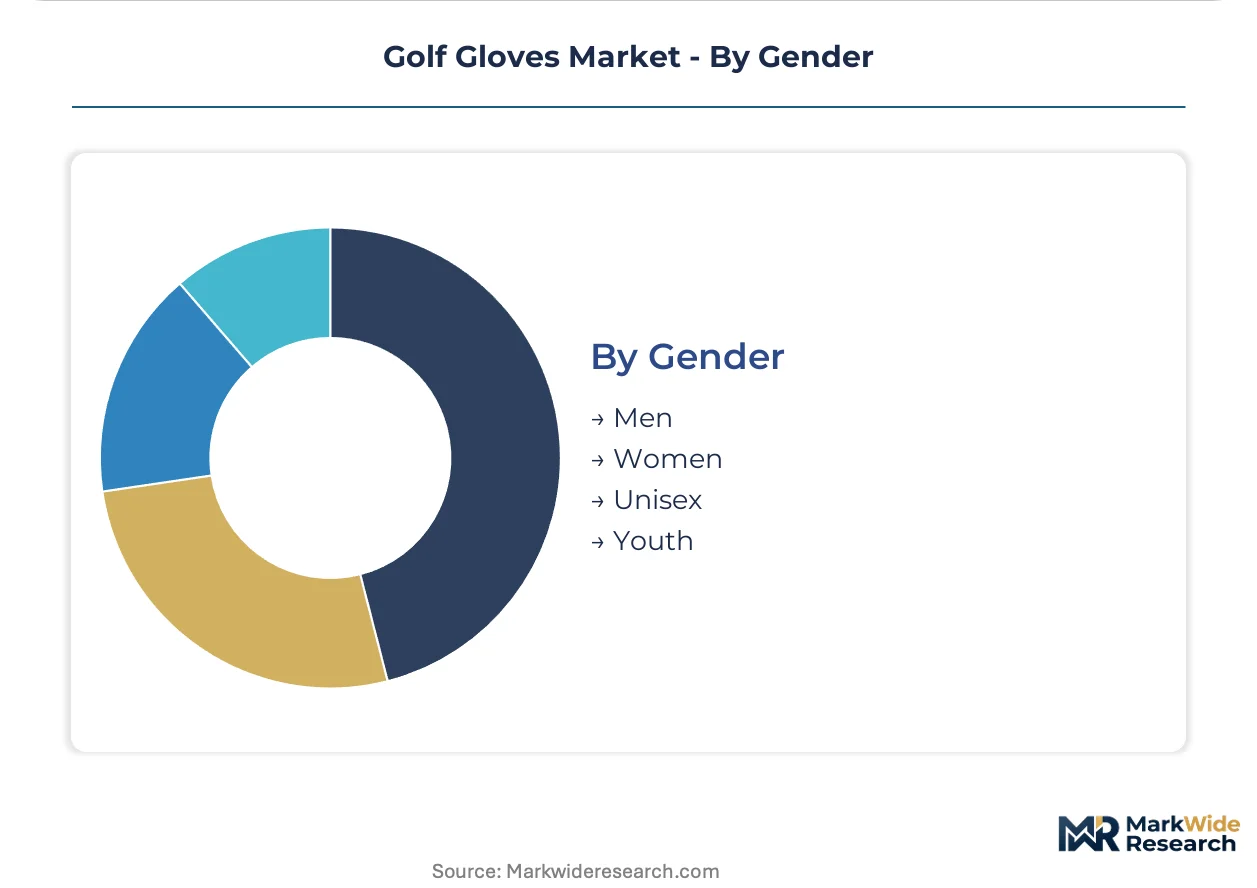
Gender:
Gender segmentation highlights distinct design considerations and marketing approaches tailored to the specific anatomical and aesthetic preferences of different player groups.
- Men:This segment traditionally represents the largest consumer base, with product designs emphasizing durability, performance, and a range of classic to modern aesthetics. Demand is robust across all golf-playing regions, driven by established participation rates.
- Women:Products in this segment often feature a more tailored fit, lighter materials, and a wider array of color and style options. Demand is growing in regions with increasing female golf participation, such as the United States and Japan, reflecting a shift towards more inclusive product offerings.
- Unisex:Designed to offer a universal fit and neutral aesthetic, appealing to a broad audience without specific gender targeting.
- Youth:Caters to younger players with smaller sizes and often more durable, entry-level designs suitable for learning and growth.
The expanding female and youth participation rates are driving product diversification and targeted marketing efforts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The established golf markets in the United States and Japan drive significant demand for golf gloves, supported by high participation rates and a strong culture of professional and amateur play. Expanding golf tourism in favorable climates also contributes to consistent, year-round product consumption. Material science advances continue to improve product performance, attracting new buyers across various regions.
United States
Demand in the United States stems from a large base of professional and amateur golfers, alongside a robust golf tourism industry. The US Federal Trade Commission (FTC) scrutinizes material claims and advertising for golf apparel, ensuring consumer trust in product performance. Major golf equipment manufacturers and specialized glove brands concentrate their distribution networks around golf courses and sporting goods retailers in Florida, California, and Arizona.
Japan
Japan exhibits strong demand for high-performance golf gloves, driven by a dedicated amateur golf population and a focus on precision equipment. The Ministry of Economy, Trade and Industry (METI) oversees product safety standards and manufacturing quality for sports goods. Tokyo, Osaka, and other metropolitan areas serve as key hubs for golf retail and product innovation, particularly for premium leather and advanced synthetic gloves.
United Kingdom
Golf participation in the United Kingdom, both recreational and competitive, sustains consistent demand for gloves across various weather conditions. European Union regulations, such as REACH, impact material choices for leather and textile components, even post-Brexit, due to supply chain integration. Scotland, the birthplace of golf, along with golf-dense regions like the Southeast of England, remains a significant market for golf apparel sales.
Germany
Germany's growing golf engagement, particularly among younger demographics, fuels demand for durable and technologically advanced golf gloves. Adherence to EU REACH regulations is critical for manufacturers supplying the German market, influencing the sourcing of compliant materials. Industrial clusters in Bavaria and North Rhine-Westphalia house distributors and retailers catering to the country's expanding golf community.
China
China represents an emerging golf economy with increasing participation rates, creating new demand for both entry-level and performance golf gloves. The State Administration for Market Regulation (SAMR) enforces product quality and safety standards for imported and domestically produced sports equipment. Major cities like Shanghai, Beijing, and Shenzhen are developing golf facilities and retail infrastructure, attracting new brands and consumers.
Golf Gloves Market Key Industry Players
Global majors compete with regional champions across product innovation and distribution reach, creating a tiered market structure. The competitive landscape includes established sports apparel giants, specialized golf equipment manufacturers, and smaller, agile innovators. Companies primarily focus on portfolio diversification and strategic partnerships to expand their market footprint.
Within the specialized golf equipment segment, FootJoy exemplifies a brand with a strong heritage in golf apparel, particularly gloves. TaylorMade Golf Company represents a competitor focused on performance optimization through technology-infused designs. Nike, a global sports apparel leader, leverages its extensive distribution network and cross-promotional marketing to maintain its market position within the golf accessories category.
| Leading Market Players |
|---|
| FootJoy |
| Callaway Golf Company |
| Acushnet Holdings Corp. |
| Titleist |
| Nike |
| TaylorMade Golf Company |
| Srixon |
| Under Armour |
| Zero Friction |
| Others |
Cost & Logistics Intelligence
Cabretta leather futures volatility directly cascades through the golf glove supply chain, influencing premium product pricing and driving manufacturers to diversify material sourcing for cost stability across different tiers. This commodity price sensitivity shapes both material mix and final consumer price points.
Pricing Analysis
Input cost fluctuations, particularly in high-grade cabretta leather, directly pass through to performance glove pricing for consumers. Pricing stratifies across premium, standard, and economy tiers, reflecting material quality and brand premium. Cost compression in the synthetic segment intensifies due to increased manufacturing efficiencies and market competition. Amateur golfers and training glove buyers exhibit higher price sensitivity, while professional players prioritize performance regardless of cost.
Supply Chain Analysis
Single-source vulnerability sits with raw material suppliers of high-grade cabretta leather from specific global regions, impacting premium glove production. The supply chain draws heavily from Asian manufacturing hubs for synthetic fabrics and specialized components. Commodity price volatility for natural leathers represents a significant structural risk for manufacturers. Distribution runs through established pro shops, large sporting goods retailers, and a rapidly expanding direct-to-consumer model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The golf gloves market functions as a regulatory compounder, with the EU's REACH regulation driving material innovation and sustainability in sourcing. This regulatory pressure fosters product differentiation and market access for compliant manufacturers.
For Market Incumbents: Cement market leadership by diversifying material sourcing beyond traditional cabretta leather, mitigating volatility and synthetic substitution threats. Invest heavily in hybrid material R&D to combine natural feel with synthetic durability. Strengthen direct-to-consumer channels to control brand narrative and customer relationships. Acushnet Holdings Corp. and TaylorMade Golf Company can leverage scale for advanced material procurement and smart glove integration.
For New Entrants and Emerging Players: Online sporting goods retailers offer new entrants a direct pathway to consumers, bypassing traditional pro shop barriers. Target the simulator-specific glove market with durable, consistent-grip designs tailored for indoor play. Focus on the youth and training segments in emerging golf economies like Southeast Asia with tech-integrated products. Develop subscription models for training gloves featuring embedded sensors for performance analytics.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized technology firms integrating micro-sensors into golf gloves for performance analytics. The market demonstrates long-term viability driven by sustained golf participation and material science advances. Identify acquisition targets among agile innovators in smart glove development and simulator-specific designs. Monitor smart glove adoption metrics and patent filings as key inflection indicators for future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch Smart Glove Line | Captures high-margin tech-savvy player segment with integrated swing analytics. |
| Expand Direct-to-Consumer Channels | Enhances brand control and customer engagement, reducing reliance on traditional retail. |
| Invest in REACH-Compliant Tanning | Secures market access in Europe and appeals to sustainability-conscious consumers. |
| Acquire Material Science Innovator | Accelerates development of hybrid fabrics for superior performance and durability. |
| Develop Simulator-Specific Gloves | Addresses demand from growing indoor golf market with specialized, durable products. |
Research Approach
Direct dialogue with golf equipment manufacturers, material suppliers, pro shop managers, and professional golf coaches grounded primary research. This qualitative data was validated against extensive secondary sources like industry reports, company filings, and trade association publications. The methodology integrated bottom-up and top-down data triangulation for comprehensive market understanding. Regulatory body guidelines from the US FTC and EU REACH further shaped the analysis.
Volume and value projections were generated through a robust statistical modeling framework, integrating historical market performance across the analysis window. Segmentation dimensions modeled included product type, material, gender, size, and regional adoption patterns. Compound annual growth rates derived from historical data and projected golf engagement trends. Key forecast inputs included golf participation and material science advancements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to economic downturns and material supply disruptions. All projections reflect a specific set of assumptions regarding market evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Rowing Machine Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Sports Mouthguard Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Sports Protective Equipment Market
Sports Equipment
Turbo Trainer Market
Sports Equipment
Concussion Helmets Market
Sports Equipment
Baseball Equipment Market
Sports Equipment
Crampon Market
Sports Equipment
Dance Equipment Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Global Spikeball Equipment Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Mixed Martial Arts Equipment Market
Sports Equipment
Sports Equipment Market