
 Figure Skating Equipment Market | 2026-2036
Figure Skating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Figure Skating Equipment Market Intelligence
Aftermarket blade sharpening and mounting services is rewriting profit allocation across the value chain. Jackson Ultima Skates leverages its Canadian manufacturing base to dominate North American distribution of heat-moldable boot systems. EDEA srl anchors its premium positioning through Italian craftsmanship and sponsorship ties to Olympic medalists. GRAF SKATES AG competes on blade metallurgy, sustaining loyalty among European competitive circles.
Figure skating equipment encompasses boots, blades, protective gear, and performance apparel engineered to ISO 10993 biocompatibility standards for prolonged skin contact during athletic exertion. Boot construction employs multi-layer leather or synthetic fiber laminates with reinforced counters and thermoformable foams to transmit edge control forces while absorbing jump impact loads. Among product type segments, blades command the highest replacement frequency and aftermarket attachment revenue. By end user, competitive athletes drive premium pricing while recreational skaters constitute volume demand. Material innovation in fiber-reinforced boot shells is displacing traditional leather in mid-tier price bands.
ISO 10993 biocompatibility testing and CE marking under the EU Personal Protective Equipment Regulation constrain market entry for uncertified suppliers. The US Consumer Product Safety Commission monitors blade retention failures, while Health Canada enforces phthalate limits in plastic components of youth-sized protective gear. Stakeholders must monitor evolving federation equipment rules and material substitution timelines to align R&D pipelines with regulatory and competitive demand shifts.
Market Dynamics
Heat-moldable thermoplastic boot shells are compressing traditional leather craftsmanship timelines while federation certification protocols force simultaneous biocompatibility compliance upgrades across manufacturing footprints.
Growth Catalysts
- South Korean Podium Success:Sustained Olympic and World Championship medals in figure skating have concentrated retail demand and training infrastructure investment in Seoul and Gangwon Province.
- ISO 10993 Biocompatibility Standards:Mandatory prolonged skin-contact testing for boot linings and protective gear components has professionalized supply chains and eliminated low-grade imports from European and North American distribution channels.
- Fiber-Reinforced Shell Molding:Automated thermoforming of carbon-fiber and glass-fiber laminates reduces custom boot production cycles from weeks to days for competitive athlete segments.
Market Restraints
- CE Marking Compliance Burden:EU Personal Protective Equipment Regulation certification costs and third-party testing timelines create six-to-nine month entry barriers for uncertified Asian manufacturers.
- Titanium and Stainless Steel Price Volatility:Blade metallurgy input costs fluctuate with aerospace and medical device sector demand, compressing margin predictability for forged blade specialists.
- Artisan Production Concentration:Premium hand-lasted boot manufacturing remains clustered in Northern Italian and Southern German craft regions, creating geographic supply vulnerability.
Strategic Opportunities
- Underpenetrated Chinese Recreational Base:Indoor ice rink construction in Chengdu, Shenzhen, and Chongqing outpaces equipment distribution infrastructure, creating first-mover channel establishment potential.
- Subscription Sharpening Services:Blade maintenance apps coordinating mobile technician dispatch are replacing pro-shop dependency among suburban recreational skaters in Canada and the United States.
- Health Canada Phthalate Limits:Youth protective gear mandates ahead of US Consumer Product Safety Commission timelines position compliant manufacturers for anticipatory North American market positioning.
Industry Challenges
- Master Last-Maker Succession:European craft traditions depend on aging artisan workforces with limited formal apprenticeship pipeline replacement in Veneto and Baden-Württemberg production zones.
- Dual Certification Timeline Compression:Simultaneous ISO 10993 biocompatibility and federation equipment rule compliance requires parallel testing tracks that strain mid-tier manufacturer R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Figure Skating Equipment Market |
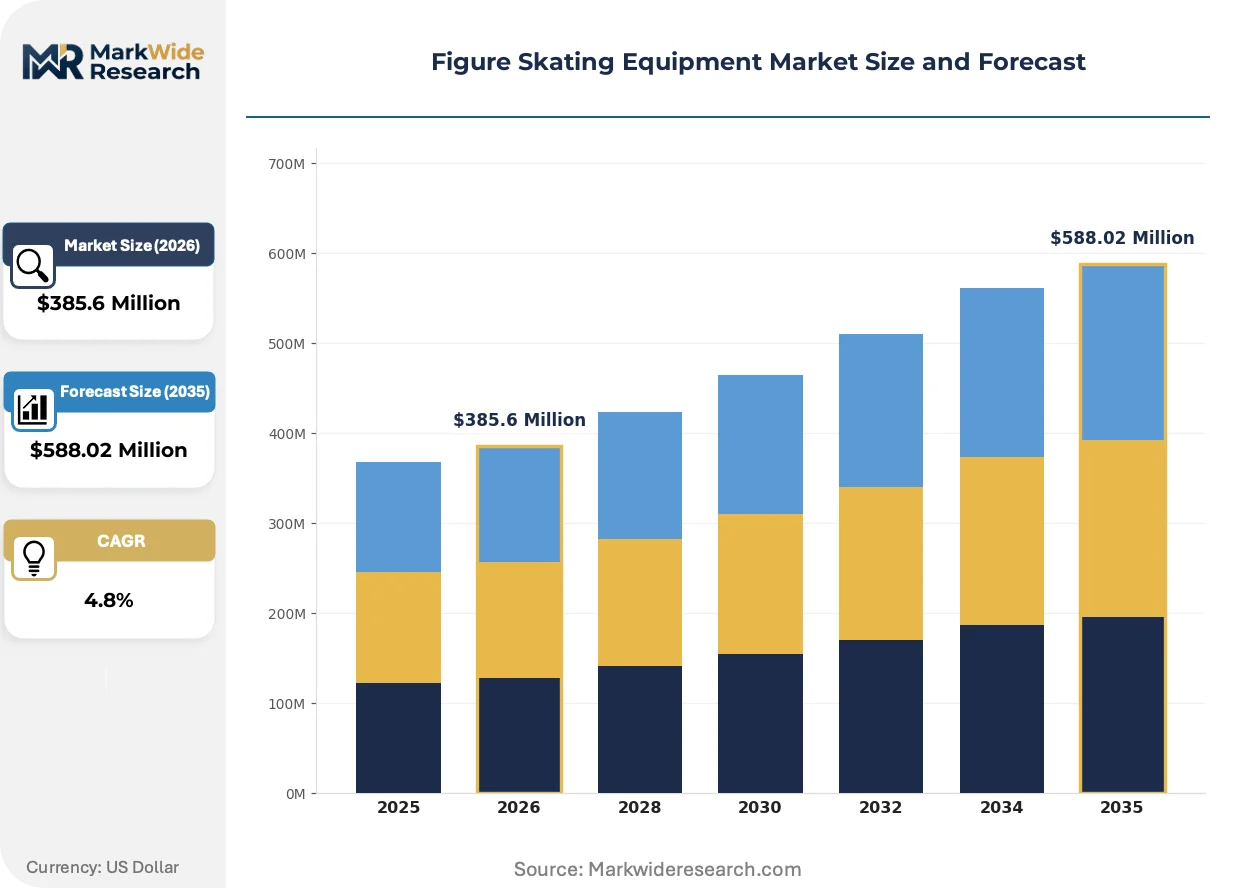
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skates, Blades, Protective Gear, Apparel End User: Recreational Skaters, Competitive Athletes, Coaches, Clubs Material: Leather, Fiber, Plastic, Steel Feature: Adjustable Fit, Lightweight Design, Enhanced Grip, Shock Absorption |
| Companies Covered | Jackson Ultima Skates, Riedell Shoes Inc, EDEA srl, GRAF SKATES AG, HD Sports Ltd, SP-Teri, Paramount Sk8s Inc, Roces srl, American Athletic Shoe Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Figure Skating Equipment Market Strategic Shifts & Innovations
Digital foot-scanning and automated last-generation systems are collapsing the traditional bespoke boot fitting timeline while fragmenting competitive advantage away from heritage craftsmanship toward precision manufacturing scale.
Carbon-fiber reinforced thermoplastic boot shells with programmable stiffness gradients are rendering obsolete multi-layer leather construction for competitive jump training applications. National team equipment managers in South Korea and Japan have adopted these systems for podium-contending athletes. The technology is compressing replacement cycle economics and shifting value capture toward mold-design software licensors.
EU Medical Device Regulation reclassification of certain high-performance protective gear components is forcing blade-retention hardware and ankle stabilization systems toward notified-body oversight previously reserved for clinical orthotics. Italian and German manufacturers with existing medical-device quality systems are absorbing compliance costs more efficiently than pure sporting-goods suppliers. The regulation is accelerating consolidation around dual-use manufacturing certifications in Alpine production zones.
Aftermarket blade mounting and sharpening services are unbundling from pro-shop retail, with independent mobile technicians capturing recreational skater relationships through direct-to-consumer booking platforms. Canadian and US suburban markets show the fastest platform adoption, displacing traditional rink-affiliated service monopolies. This channel fragmentation is reallocating lifetime customer value from boot manufacturers toward service-network operators.
Figure Skating Equipment Market Segmentation
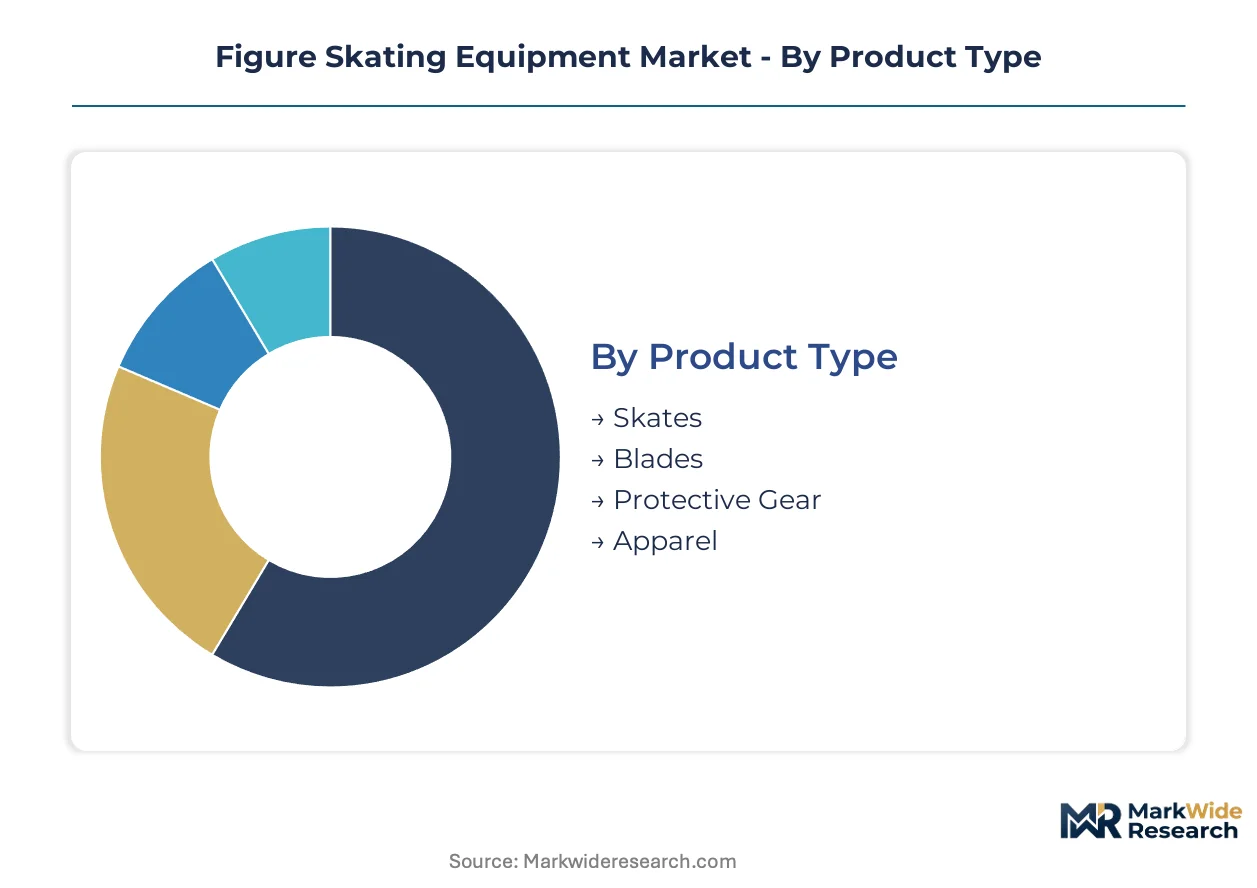
Segmentation in figure skating equipment reveals how technical specifications, certification requirements, and end-use intensity fragment purchasing behavior across price tiers and replacement cycles. Understanding these divisions exposes where margin concentrates versus where volume scales.
Product Type:
Use-case intensity spans casual rink visits to Olympic training regimens, with equipment durability and customization depth scaling accordingly.
- Skates:Multi-layer boot construction employing leather laminates or thermoformable synthetics transmits edge control forces while absorbing jump impact loads. Heat-moldable shell systems from Canadian and Italian manufacturers dominate competitive athlete procurement in South Korea and Japan, where federation certification protocols mandate precise fit tolerances.
- Blades:Forged steel or titanium alloys with precision-ground hollows determine edge bite and glide characteristics. Replacement frequency runs highest among competitive jump training programs in Seoul and Gangwon Province, generating recurring aftermarket revenue for sharpening and mounting services.
- Protective Gear:Helmets, padded shorts, and wrist guards engineered to ISO 10993 biocompatibility standards for prolonged skin contact.
- Apparel:Performance costumes and training wear subject to federation dress code regulations and thermal management requirements.
Established volume favors recreational skates; emerging adoption favors heat-moldable competitive boot systems.
End User:
Customer type determines price sensitivity, replacement cadence, and susceptibility to federation equipment rule changes.
- Recreational Skaters:Weekend rink visitors and adult learners purchasing entry-level leather boots through mass retail channels. Volume concentration in Canadian and US suburban markets drives economies of scale for standardized sizing, though mobile sharpening apps are displacing traditional pro-shop loyalty.
- Competitive Athletes:Podium-contending skaters requiring custom-lasted boots with programmable stiffness gradients. South Korean national team equipment managers have accelerated procurement of carbon-fiber reinforced thermoplastic shells, compressing production cycles from weeks to days.
- Coaches:Professional instructors with institutional purchasing influence over club inventory decisions.
- Clubs:Rink-affiliated training facilities managing fleet equipment for lesson programs and test sessions.
Recreational skaters anchor unit volume; competitive athletes command premium pricing and technology adoption leadership.
Material:
Raw material selection trades heritage craftsmanship against automated manufacturing scalability and regulatory compliance burden.
- Leather:Traditional multi-layer hide construction with hand-lasted shaping and reinforced counters. Artisan production remains clustered in Northern Italian and Southern German craft regions, creating geographic supply vulnerability as aging master last-makers lack formal apprenticeship pipeline replacement.
- Fiber:Carbon-fiber and glass-fiber reinforced thermoplastic laminates enabling automated thermoforming. Fiber-reinforced shell molding is displacing leather in mid-tier price bands, with programmable stiffness gradients rendering multi-layer construction obsolete for jump training applications.
- Plastic:Injection-molded components for youth protective gear and recreational boot hardware.
- Steel:Blade metallurgy inputs subject to aerospace and medical device sector demand volatility.
Leather sustains premium positioning; fiber composites gain share fastest in competitive segments.
Feature:
Performance attributes differentiate offerings across certification tiers and price bands while responding to injury prevention priorities.
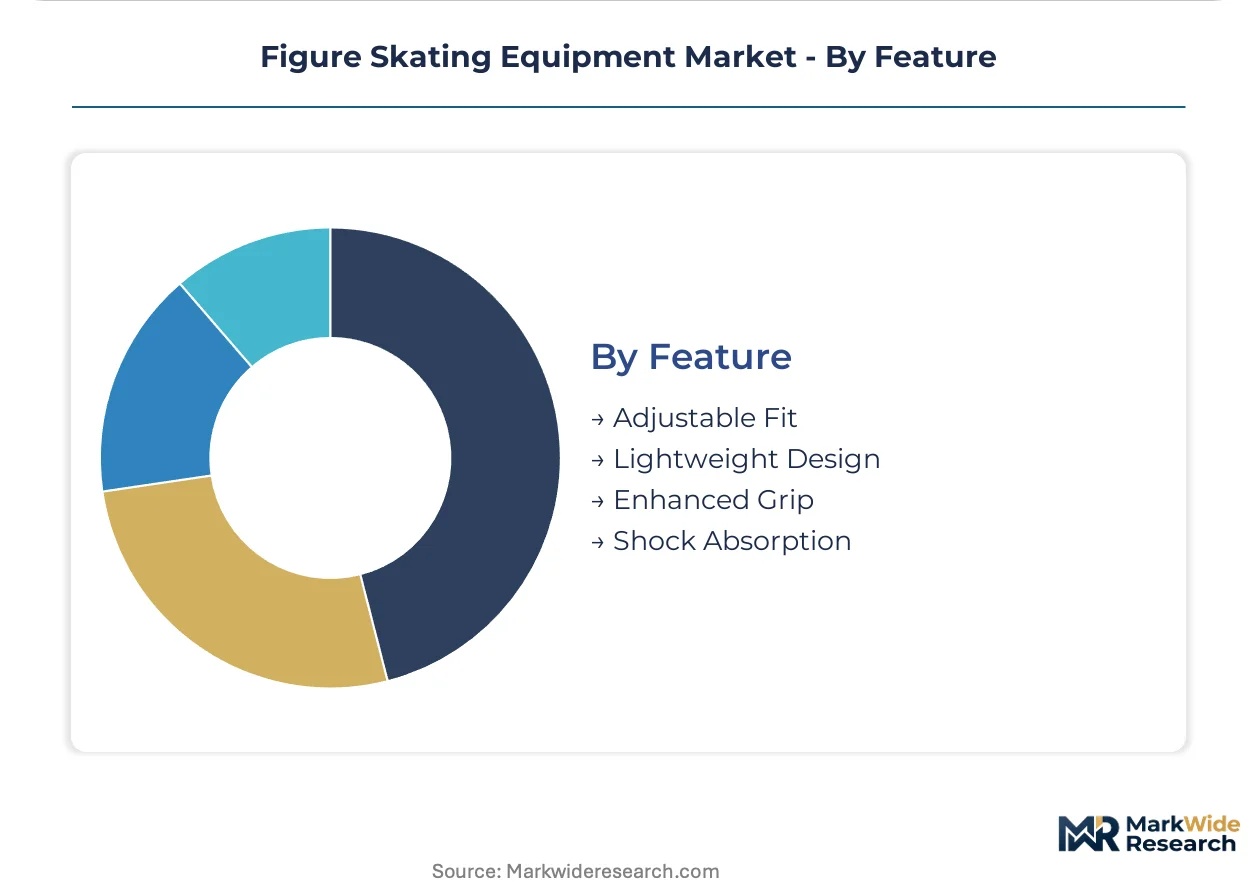
- Adjustable Fit:Heat-activated molding systems and modular sizing components accommodating growth spurts in youth segments. Health Canada phthalate limits in plastic components of youth-sized protective gear have accelerated compliant manufacturer positioning ahead of US Consumer Product Safety Commission timelines.
- Lightweight Design:Carbon-fiber shell construction reducing rotational inertia for jump rotation efficiency. National team equipment managers in Japan prioritize gram reduction for senior international competitors.
- Enhanced Grip:Blade hollow geometry and specialized coatings for ice surface conditions.
- Shock Absorption:Thermoformable foam liners and reinforced heel counters mitigating landing impact forces.
Adjustable fit dominates youth procurement; lightweight design commands priority in elite competitive specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational buyers in Canada and the United States show high price elasticity, while competitive athletes in South Korea and Japan absorb substantial premiums for certified heat-moldable systems. Demand intensity clusters where federation investment and podium success concentrate procurement authority.
United States
Suburban rink construction in Texas and Florida drives entry-level volume, though mobile sharpening apps erode traditional pro-shop loyalty. The US Consumer Product Safety Commission monitors blade retention failures, forcing design documentation upgrades. Chicago and Minneapolis-St. Paul retain dense competitive club infrastructure sustaining custom boot demand.
Canada
Jackson Ultima's domestic manufacturing base secures preferential distribution for thermoformable systems across Ontario and Quebec recreational networks. Health Canada enforces phthalate limits in youth protective gear ahead of US timelines, accelerating compliant supplier positioning. Calgary and Edmonton cluster elite training facilities with institutional procurement influence.
South Korea
Olympic podium success concentrates retail demand and national team equipment budgets in Seoul and Gangwon Province. The Korea Fair Trade Commission scrutinizes exclusive distribution arrangements between foreign manufacturers and domestic retailers. Busan-Ulsan corridor hosts expanding indoor ice infrastructure with underserved equipment distribution.
Italy
Artisan boot production in Veneto sustains premium positioning through hand-lasted craftsmanship and Olympic medalist sponsorship ties. CE marking under the EU Personal Protective Equipment Regulation constrains uncertified import competition. Montebelluna district clusters heritage manufacturers facing master last-maker succession risks.
Japan
National team equipment managers prioritize gram-reduction specifications for senior international competitors, compressing replacement cycle economics. METI standards for sports equipment safety testing add parallel certification requirements for imported systems. Nagoya and Sapporo training centers drive specification adoption for carbon-fiber reinforced shells.
Figure Skating Equipment Market Key Industry Players
Capability concentration sits with heritage craft manufacturers possessing dual medical-device quality systems; scale advantage sits with automated thermoforming specialists serving recreational volume. The vendor base organizes around three strategic archetypes: Italian and German artisan houses defending premium positioning through federation sponsorships; Canadian and Asian fabricators exploiting thermoplastic molding scale; and blade metallurgy specialists capturing aftermarket service revenue. Consolidation pressure favors manufacturers with existing notified-body relationships under tightening EU Medical Device Regulation reclassification.
Within the heritage craft tier, EDEA srl and GRAF SKATES AG exemplify positioning anchored in Alpine manufacturing traditions and dual-use certification advantages. Jackson Ultima Skates occupies the scale-driven vector through North American thermoformable production. These three entities represent divergent responses to ISO 10993 biocompatibility and federation rule compliance compression.
| Leading Market Players |
|---|
| Jackson Ultima Skates |
| Riedell Shoes Inc |
| EDEA srl |
| GRAF SKATES AG |
| HD Sports Ltd |
| SP-Teri |
| Paramount Sk8s Inc |
| Roces srl |
| American Athletic Shoe Co |
| Others |
Cost & Logistics Intelligence
Montebelluna's artisan boot production clusters concentrate premium manufacturing capacity in a narrow Alpine corridor, amplifying pricing power for hand-lasted heritage manufacturers while compressing margin flexibility for mid-tier competitors dependent on Italian subcontracting networks. This geographic concentration of master last-makers tightens supply elasticity, forcing downstream brands to absorb certification cost escalations or cede positioning to automated thermoforming specialists.
Pricing Analysis
Aftermarket blade sharpening and mounting services command the dominant share of lifetime customer value, with recurring service revenue often exceeding initial equipment purchase value for competitive athletes. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and customization depth, with ISO 10993-compliant systems carrying substantial premiums. Pricing pressure stems from titanium and stainless steel input volatility driven by aerospace sector demand swings. Recreational skaters in Canadian and US suburban markets exhibit highest price elasticity, while South Korean national team procurement absorbs premium positioning without volume sensitivity.
Supply Chain Analysis
Extended payment terms from Italian and German heritage manufacturers to Veneto and Baden-Württemberg craft subcontractors stabilize artisan production through seasonal demand fluctuations. Supply concentration centers on Italy, Canada, and South Korea for finished systems, with blade metallurgy drawing from German and Japanese steel specialists. Raw material dependencies include carbon-fiber prepregs, titanium forgings, and thermoplastic resins. Single-source vulnerability concentrates around aging master last-makers in Alpine zones without formal apprenticeship pipelines. Distribution runs through rink-affiliated pro shops, direct-to-consumer platforms, and national federation procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery driven by South Korean podium success concentrating training infrastructure investment and equipment procurement authority. Federation certification protocol tightening reinforces premium tier durability against commoditization pressures.
For Market Incumbents: Entrench federation sponsorship relationships and dual medical-device quality systems as defensive moats against carbon-fiber thermoforming disruptors. Deepen backward integration into mold-design software licensing to capture value migrating from boot fabrication to precision manufacturing scale. Prioritize CE marking and ISO 10993 compliance investment ahead of EU Medical Device Regulation reclassification timelines to absorb consolidation pressure more efficiently than pure sporting-goods competitors. For New Entrants and Emerging Players: Establish a beachhead in China's underpenetrated recreational base where indoor rink construction in Chengdu, Shenzhen, and Chongqing outpaces equipment distribution infrastructure. Target subscription-based blade maintenance apps coordinating mobile technician dispatch, displacing traditional pro-shop monopolies in Canadian and US suburban markets. Pursue anticipatory Health Canada phthalate compliance positioning ahead of US Consumer Product Safety Commission timelines to capture first-mover advantage in youth protective gear segments. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because tightening biocompatibility and federation equipment rules favor incumbents with existing notified-body relationships and dual-use manufacturing footprints. Acquisition targets should display medical-device quality systems overlaying sporting-goods production. Watch for master last-maker succession failures in Veneto and Baden-Württemberg as inflection indicators for accelerated thermoforming adoption and heritage brand distress.| Strategic Initiative | Industry Significance |
|---|---|
| Federation Certification Investment | ISO 10993 compliance and CE marking under EU PPE Regulation lock out uncertified Asian competitors from premium distribution channels. |
| Carbon-Fiber Thermoforming Scale-Up | Automated shell production in Canadian and South Korean facilities compresses custom boot delivery from weeks to days for competitive athletes. |
| Mobile Sharpening Platform Launch | Direct-to-consumer blade maintenance apps fragment recreational skater relationships away from rink-affiliated pro-shop monopolies. |
| Dual Medical-Device Certification | EU MDR reclassification of protective gear components favors Italian and German manufacturers with existing orthotics quality systems. |
| Chinese Distribution Channel Establishment | First-mover equipment distribution in Chengdu and Chongqing captures indoor rink construction outpacing supply infrastructure. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with national team equipment managers, federation certification officers, rink operations directors, and heritage manufacturer production heads. Secondary validation drew from ISO 10993 testing documentation, EU notified-body certification registers, federation equipment rule amendments, and trade flow data for carbon-fiber and titanium inputs. Bottom-up segment sizing across product type, end user, material, and feature dimensions was triangulated against top-down market value reconstruction.
Calibration against historical replacement cycle patterns and federation procurement budget disclosures anchored volume projections across the analysis window. Segmentation modeling spanned competitive versus recreational intensity, leather versus fiber material substitution timelines, and regional certification adoption clusters. CAGRs were derived from slope analysis of equipment penetration against ice rink infrastructure development curves, with blade aftermarket revenue and thermoformable boot adoption rates as primary forecast inputs.
Sensitivities concentrate around federation rule amendment timing, master last-maker succession disruptions, and raw material price volatility from competing industrial demand. Forecasts reflect documented assumptions on certification compliance trajectories and regional infrastructure investment commitments. Macroeconomic contraction affecting discretionary recreational spending, regulatory acceleration beyond modeled timelines, or breakthrough manufacturing automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Wakeboarding Equipment Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Water Polo Suits Market
Sports Equipment
Global Golf Rangefinders Market
Sports Equipment
Mouthguard Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Pitching Machine Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
Inflatable Sleds Market
Sports Equipment
Triathlon Bikes Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Badminton Equipment and Products Market
Sports Equipment
Global Sports Bicycle Market