
 Backboard Market | 2026-2036
Backboard Market Size, Share, and Industry Trends Forecast 2026-2036
Backboard Market Analytics
Paramedic training capacity is collapsing across North American emergency medical services, forcing fire departments and hospital systems to extend equipment replacement cycles while demanding more durable backboard platforms. Ferno leverages its vertical integration in aluminum frame production to sustain price stability for municipal buyers. Laerdal Medical anchors the professional training segment with simulation-compatible backboard designs. Zhangjiagang Xiehe Medical competes on manufacturing scale, occupying the export channel for fiberglass-reinforced models across Southeast Asian markets.
A backboard is a rigid rectangular panel, typically measuring 72 inches horizontally by 42 inches vertically, engineered from tempered glass, acrylic, polycarbonate, or composite substrates to withstand repeated ball impact while maintaining optical clarity and dimensional stability for competitive basketball play. The product type dimension shows polycarbonate variants capturing institutional preference due to shatter resistance and lighter handling weights, while fiberglass formulations retain dominance in outdoor municipal installations where weathering tolerance determines procurement outcomes. Among installation types, portable systems with adjustable height mechanisms are displacing fixed permanent mounts in school districts seeking multi-sport gymnasium flexibility.
The National Federation of State High School Associations sets dimensional and performance standards that directly shape manufacturer design specifications for products entering the scholastic procurement channel. China's GB standards for sports equipment safety and the EU's REACH chemical compliance framework both impose material composition constraints that filter market access for polycarbonate and acrylic suppliers. Stakeholders must monitor how municipal budget cycles synchronize with building code refreshes to anticipate replacement demand windows.
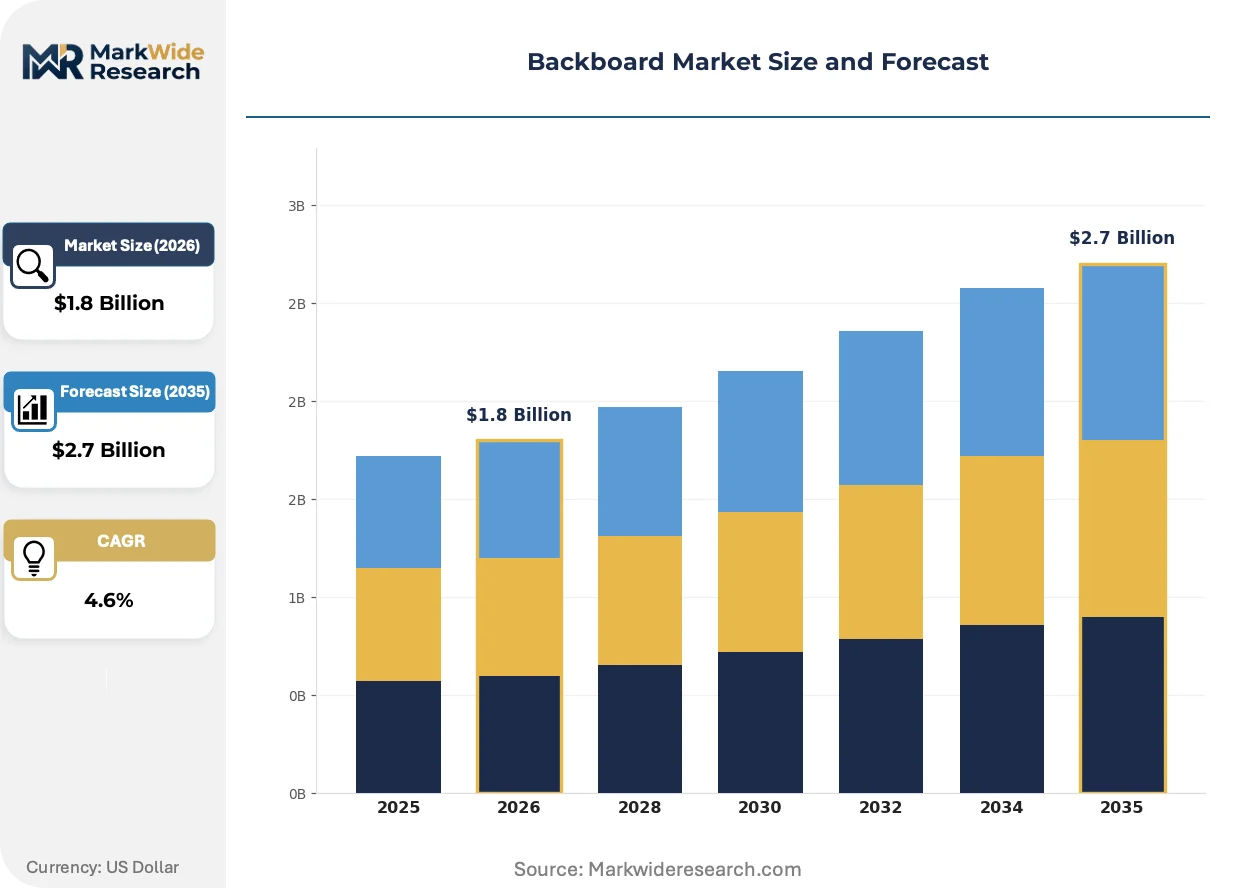
Market Dynamics
School districts across the United States are accelerating gymnasium equipment replacement cycles as federal infrastructure funding reaches municipal procurement channels. This capital injection is compressing replacement timelines from ten-year cycles toward five-year refresh rates.
Growth Catalysts
- EU Green Deal material mandates:Recycled polycarbonate formulations now qualify for preferential procurement scoring in European municipal tenders. Manufacturers reformulating around post-consumer resin streams gain channel access.
- China's tier-one city infrastructure budgets:Municipal sports bureaus in Beijing, Shanghai, and Shenzhen expanded dedicated funding lines for competitive basketball facilities. Public-private partnership models are unlocking venue construction at scale.
- Multi-sport gymnasium flexibility requirements:Adjustable-height portable systems enable rapid reconfiguration between volleyball, basketball, and indoor soccer. School districts prioritize capital equipment serving multiple athletic programs.
Market Restraints
- Aluminum frame input volatility:Primary aluminum pricing swings tied to energy costs in Chinese smelting regions transmit directly to backboard frame manufacturing economics.
- Fiberglass resin supply concentration:Epoxy and polyester resin production clusters in South Korea and Taiwan create geographic chokepoints for outdoor municipal backboard supply chains.
- Tempered glass weight limitations:Structural load requirements for ceiling-suspended installations restrict glass backboard deployment in older gymnasium facilities lacking reinforced support infrastructure.
Strategic Opportunities
- India's underpenetrated scholastic sports infrastructure:The country's K-12 physical education mandate expansion creates first-mover positioning for polycarbonate backboard suppliers establishing local assembly partnerships.
- Simulation-integrated training platforms:Sensor-embedded backboards enabling shot-tracking analytics are converging with athletic performance software ecosystems. Hospital systems and professional training centers represent high-margin adoption segments.
- Direct municipal procurement portals:State-level cooperative purchasing agreements in Texas, California, and Florida are consolidating district-level demand into volume tenders bypassing traditional distribution layers.
Industry Challenges
- GB standards compliance timeline compression:China's sports equipment safety certification process requires extended testing protocols for polycarbonate impact resistance. Foreign manufacturers face six-to-nine month approval windows disrupting market entry sequencing.
- Legacy gymnasium structural assessment complexity:Pre-1980 school facilities require engineered load studies before ceiling-mounted system installation. District capital planning teams lack in-house structural engineering capacity.
- REACH chemical documentation burden:European acrylic and polycarbonate suppliers must maintain substance volume tracking across complex additive packages. Smaller compounders struggle with regulatory data management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backboard Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood, Acrylic, Polycarbonate, Fiberglass End User: Schools, Sports Clubs, Gyms, Residential Installation Type: Permanent, Portable, Adjustable, Fixed Usage Context: Indoor, Outdoor, Competitions, Training |
| Companies Covered | Spinal Innovations, Ferno, Laerdal Medical, Ambu, Medtronic, Smiths Medical, Bound Tree Medical, Zhangjiagang Xiehe Medical, Beijing Etertop Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backboard Market Evolving Landscape
Material science advances and procurement digitization are restructuring competitive positioning across institutional and municipal buyer segments. Three converging developments warrant strategic monitoring.
Smart backboard systems integrating pressure-sensitive shot-tracking sensors and wireless connectivity are displacing passive equipment in professional training environments. NCAA Division I programs and NBA development facilities are standardizing these platforms for player analytics integration. The technology is compressing replacement demand into shorter performance-upgrade cycles.
REACH chemical compliance frameworks are forcing reformulation of polycarbonate additive packages across European supply chains. Manufacturers substituting legacy flame retardants and UV stabilizers face requalification testing for optical clarity and impact resistance. Institutional buyers in Germany and France now require full material disclosure documentation as standard tender elements.
Cooperative purchasing consortiums aggregating demand from multiple school districts are consolidating specification authority at state and regional levels. Traditional equipment distributors serving individual districts face margin compression as volume tenders bypass intermediate stocking layers. Texas and Florida procurement cooperatives represent the most advanced manifestations of this channel restructuring.
Backboard Market Segmentation
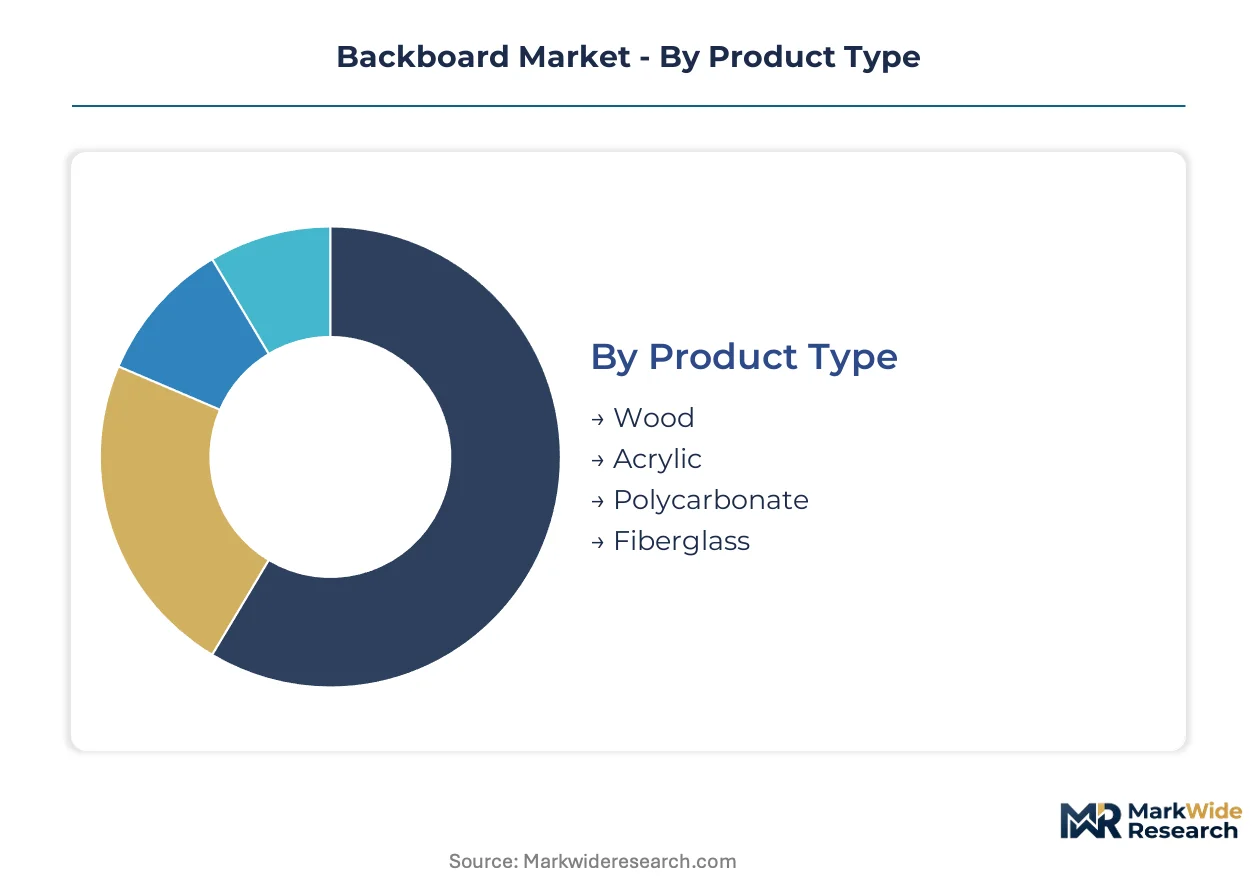
Backboard procurement flows through distinct channel configurations depending on material composition and installation complexity. Understanding these segment-channel pairings reveals where margin pools concentrate and which specifications drive volume tenders versus premium direct sales.
Product Type:
Channel mix splits sharply between institutional specification sales and municipal tender channels, with material durability ratings determining which procurement pathway manufacturers prioritize.
- Polycarbonate:Engineered from thermoplastic polymer sheets offering superior shatter resistance and lighter handling weights than glass alternatives. School districts in the United States concentrate demand here as federal infrastructure funding compresses replacement cycles toward five-year refresh rates, with the NFHS dimensional standards directly shaping manufacturer design specifications.
- Fiberglass:Reinforced composite substrates combining epoxy or polyester resins with glass fiber matrices for weathering tolerance. Outdoor municipal installations across Southeast Asian markets favor this segment where humidity exposure and UV degradation resistance determine procurement outcomes, though resin supply concentration in South Korea and Taiwan creates geographic chokepoints.
- Acrylic:Cast or extruded thermoplastic delivering optical clarity at lower cost than polycarbonate formulations. European REACH compliance frameworks are forcing reformulation of additive packages, with full material disclosure documentation now standard in German and French tenders.
- Wood:Laminated hardwood constructions retaining niche presence in heritage gymnasium refurbishments and budget-constrained scholastic installations. India's K-12 physical education mandate expansion creates first-mover positioning for suppliers establishing local assembly partnerships.
Fiberglass dominates installed base in outdoor municipal contexts. Polycarbonate is where expansion concentrates as institutional buyers prioritize multi-sport flexibility.
End User:
Cost tier stratification separates capital equipment buyers with dedicated facilities budgets from discretionary purchasers sensitive to price-per-unit thresholds.
- Schools:Public and private K-12 institutions plus university athletic departments operating under collective procurement agreements. Texas, California, and Florida state-level cooperative purchasing agreements are consolidating district-level demand into volume tenders that bypass traditional distribution layers.
- Sports Clubs:Private membership facilities and semi-professional training centers requiring competition-grade specifications. NCAA Division I programs and NBA development facilities are standardizing sensor-embedded platforms for player analytics integration.
- Gyms:Commercial fitness operators prioritizing rapid reconfiguration between programming formats. Adjustable-height portable systems enable same-day conversion between volleyball, basketball, and indoor soccer configurations.
- Residential:Individual consumers purchasing through retail channels or direct-to-consumer portals. Price sensitivity here pushes demand toward entry-level acrylic and polycarbonate formulations with simplified mounting hardware.
Schools anchor volume procurement through cooperative agreements. Sports clubs represent the steepest expansion trajectory as performance analytics integration compresses replacement cycles.
Installation Type:
Customer type differentiation separates permanent infrastructure investors from operators requiring asset mobility across venue portfolios.
- Portable:Freestanding units with wheeled bases and telescoping height adjustment mechanisms. School districts seeking multi-sport gymnasium flexibility are displacing fixed permanent mounts with these systems.
- Adjustable:Wall-mounted or ceiling-suspended configurations with motorized or manual height modification. Hospital systems and professional training centers represent high-margin adoption segments for simulation-compatible designs.
- Permanent:Fixed-height installations anchored to structural walls or poured concrete foundations. Pre-1980 school facilities require engineered load studies before ceiling-mounted system installation, creating structural assessment complexity.
- Fixed:Non-adjustable ceiling or wall-mounted systems common in dedicated basketball facilities with single-sport programming. China's GB standards for sports equipment safety impose material composition constraints that filter market access.
Permanent installations dominate legacy facility stock. Portable configurations are gaining share fastest as capital planning teams prioritize equipment versatility.
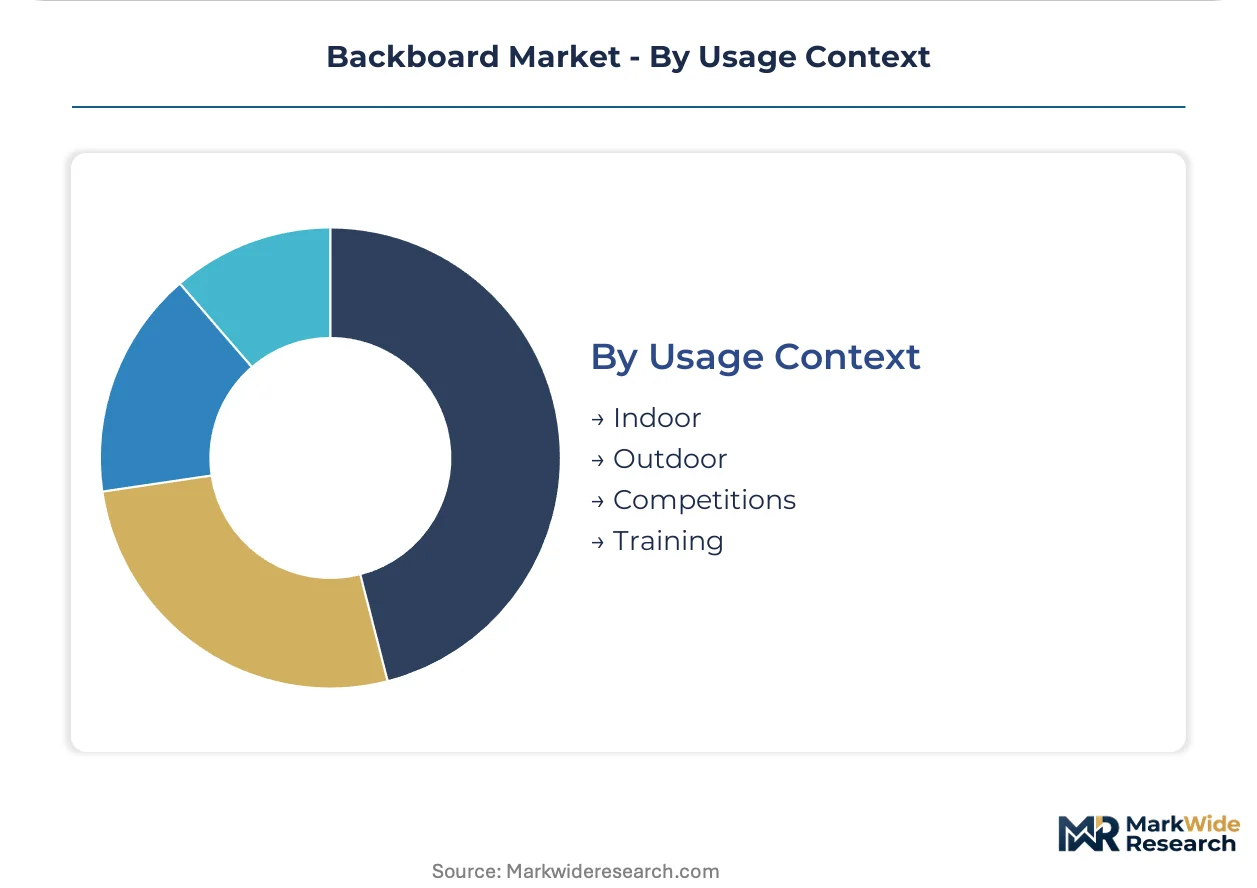
Usage Context:
Geography and margin structure intersect where climate exposure and competitive intensity shape specification requirements.
- Indoor:Climate-controlled environments prioritizing optical clarity and consistent ball rebound characteristics. China's tier-one city infrastructure budgets in Beijing, Shanghai, and Shenzhen are expanding dedicated funding lines for competitive basketball facilities.
- Outdoor:Exposed installations requiring UV stabilization, moisture resistance, and thermal expansion tolerance. EU Green Deal material mandates now qualify recycled polycarbonate formulations for preferential procurement scoring in European municipal tenders.
- Competitions:Regulation-specified dimensions and performance standards for sanctioned play. The National Federation of State High School Associations sets dimensional and performance standards that directly shape manufacturer design specifications.
- Training:Practice environments accommodating repeated high-volume use with durability prioritization over optical perfection. Paramedic training capacity constraints across North American emergency medical services are extending equipment replacement cycles while demanding more durable platforms.
Indoor contexts dominate revenue concentration. Outdoor applications are expanding most quickly as municipal sports infrastructure budgets proliferate across emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Federation of State High School Associations anchors specification authority in the United States, while China's GB standards and the EU Green Deal shape parallel compliance frameworks across their respective jurisdictions.
United States
School districts in Texas, California, and Florida are consolidating demand through state-level cooperative purchasing agreements that bypass traditional distribution layers. Federal infrastructure funding is compressing replacement cycles from ten-year intervals toward five-year refresh rates. Municipal procurement teams in these states prioritize multi-sport gymnasium flexibility when evaluating portable system specifications.
China
Municipal sports bureaus in Beijing, Shanghai, and Shenzhen have expanded dedicated funding lines for competitive basketball facilities under public-private partnership models. GB standards for sports equipment safety impose six-to-nine month certification windows for polycarbonate impact resistance testing. The Yangtze River Delta and Pearl River Delta regions concentrate manufacturing capacity for fiberglass-reinforced outdoor installations serving Southeast Asian export markets.
Germany
REACH chemical compliance frameworks are forcing reformulation of polycarbonate additive packages across European supply chains. Institutional buyers now require full material disclosure documentation as standard tender elements. The country's municipal procurement scoring systems award preferential status to recycled polycarbonate formulations aligned with EU Green Deal material mandates.
India
K-12 physical education mandate expansion is creating first-mover positioning for suppliers establishing local assembly partnerships. State governments in Maharashtra and Karnataka are channeling infrastructure budgets toward scholastic sports facility construction. The Delhi-NCR corridor represents an emerging concentration zone for budget-constrained institutional procurement favoring wood and acrylic formulations.
Japan
METI industrial standards for sports equipment safety filter market access for polycarbonate and acrylic suppliers targeting institutional channels. Prefecture-level education boards in Kanto and Kansai regions are refreshing aging gymnasium infrastructure with adjustable-height systems. Osaka-based fabricators occupy positions in the export channel for training-grade equipment across East Asian markets.
Backboard Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the current market structure. Three strategic archetypes define competitive positioning: vertically integrated aluminum processors sustaining price stability for municipal buyers, simulation-technology specialists anchoring professional training segments, and scale-driven manufacturers occupying export channels for fiberglass-reinforced models. Dominant competitive moves include backward integration into primary material production and strategic partnerships with municipal procurement cooperatives.
Among North American emergency medical equipment specialists, Ferno and Laerdal Medical exemplify divergent archetype positioning. Ferno leverages in-house aluminum frame production to maintain cost predictability for fire department and hospital system buyers facing extended replacement cycles. Laerdal Medical occupies a position within the simulation-integrated training tier, with designs compatible with athletic performance analytics platforms. Zhangjiagang Xiehe Medical represents the scale-driven export manufacturer archetype, with production configurations aligned to Southeast Asian municipal tender requirements for weathering-tolerant outdoor installations.
| Leading Market Players |
|---|
| Spinal Innovations |
| Ferno |
| Laerdal Medical |
| Ambu |
| Medtronic |
| Smiths Medical |
| Bound Tree Medical |
| Zhangjiagang Xiehe Medical |
| Beijing Etertop Technology |
| Others |
Value Network & Pricing Analysis
Scale economies in polycarbonate sheet extrusion anchor price floors across institutional procurement channels, with integrated manufacturers in the Yangtze River Delta leveraging captive resin supply to undercut fragmented assemblers dependent on spot-market polymer feedstock. This concentration dynamic compresses margins for non-integrated competitors while creating geographic price spreads between production-heavy and import-dependent regions.
Pricing Analysis
Geographic price spreads separate Chinese-manufactured polycarbonate backboards from European and North American equivalents by 15-25 percent at equivalent NFHS specification tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with sensor-embedded smart systems commanding premium positioning. Price erosion runs through standard-grade fiberglass outdoor installations as resin cost volatility transmits from South Korean and Taiwanese epoxy suppliers. School districts operating through Texas and Florida cooperative purchasing agreements exhibit lowest price sensitivity, while individual municipal buyers in fragmented Indian states face highest unit-cost exposure.
Supply Chain Analysis
China and South Korea anchor global polycarbonate resin and fiberglass matrix production respectively, with Taiwan concentrating epoxy hardener formulation for outdoor backboard weatherproofing. Raw material dependencies rest on bisphenol-A for thermoplastic substrates, aluminum billet for portable system frames, and glass fiber roving for reinforced composites. Single-source vulnerability concentrates in South Korean epoxy resin supply for Southeast Asian municipal tenders. Distribution runs through state-level cooperative purchasing consortiums in the United States, direct municipal procurement portals in China's tier-one cities, and traditional equipment distributors serving fragmented district-level demand in India and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backboard market incumbents face substitution pressure from sensor-embedded smart training platforms that compress replacement cycles and capture performance-analytics budgets previously allocated to passive equipment. Defense requires repositioning around durability specifications and certification authority that emerging electronics-integrated entrants cannot rapidly replicate.
For Market Incumbents: Consolidate specification authority through deeper NFHS and GB standards committee participation, locking in dimensional and impact-resistance benchmarks that sensor-embedded alternatives must separately qualify. Backward integration into aluminum frame production sustains price stability against primary metal volatility, while captive polycarbonate extrusion capacity insulates margin compression from resin spot-market swings. Prioritize multi-sport flexibility certification to defend against pure-play basketball analytics specialists.
For New Entrants and Emerging Players: China's GB standards fast-track for polycarbonate impact resistance offers six-to-nine month regulatory arbitrage against established European and North American competitors. Target India's underpenetrated K-12 physical education infrastructure through local assembly partnerships in Maharashtra and Karnataka, where state infrastructure budgets are channeling first-time gymnasium construction. Anchor go-to-market through direct municipal procurement portal registration, bypassing traditional distributor margin layers that concentrate in legacy scholastic channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with simulation-compatible design portfolios and established hospital system relationships, as professional training segments compress replacement demand into shorter performance-upgrade cycles. Long-term viability hinges on regulatory compliance infrastructure capable of navigating REACH reformulation mandates and China's extended certification windows. Watch GB standards timeline compression as the inflection signal—accelerated approval protocols would erode foreign incumbents' regulatory moats and reshape competitive entry economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Polycarbonate Formulation Investment | EU Green Deal procurement scoring advantages unlock preferential municipal tender access across Germany and France. |
| Sensor-Embedded Platform Development | NCAA Division I and NBA development facility standardization creates high-margin replacement cycle compression. |
| Cooperative Purchasing Consortium Partnership | Texas and Florida state-level agreements consolidate district demand into volume tenders bypassing distribution layers. |
| Local Assembly Partnership in India | Maharashtra and Karnataka state infrastructure budgets channel first-mover positioning for K-12 mandate expansion. |
| GB Standards Fast-Track Certification | Six-to-nine month approval windows in China create regulatory arbitrage against established Western competitors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC equipment manufacturer filings, and municipal procurement database records. Primary interviews engaged plant managers at polycarbonate extrusion facilities, procurement leads at U.S. school district cooperative purchasing agreements, and distribution channel partners serving Southeast Asian municipal tenders. Secondary validation drew from NFHS equipment standards documentation, China's GB sports equipment safety certifications, and EU REACH chemical compliance filings. Bottom-up demand aggregation across installation types and end-user segments triangulates against top-down market sizing from production capacity and trade flow analysis.
Segmentation dimensions modeled span product type, installation configuration, end-user category, and geographic regulatory cluster across the projection horizon. Analytical framework derives CAGRs from installed base replacement cycle compression, municipal budget expansion trajectories, and material substitution elasticity parameters. Industry-specific forecast inputs incorporate federal infrastructure funding disbursement timelines in the United States and public-private partnership construction velocity in China's tier-one cities.
Underlying assumptions cover sustained municipal budget allocation to sports infrastructure, stable polycarbonate resin supply from integrated petrochemical complexes, and gradual REACH additive package reformulation without disruptive requalification failures, with deviation risk concentrated in aluminum price volatility from Chinese smelting energy costs and extended GB certification delays for foreign manufacturers. Recalibration cycles align with material shifts in municipal procurement digitization and smart backboard technology adoption trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Volleyball Shoes Market
Sports Equipment
Global Stand Up Paddle (SUP) Boards Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Bowling Lane Panels Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
Dirt Bike Market
Sports Equipment
France Artificial Turf Market
Sports Equipment
Dance Equipment Market
Sports Equipment
Archery Equipment Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Gym Bag Market
Sports Equipment
Sports Devices Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
US Fencing Market