
 Soccer Cleats Market | 2026-2036
Soccer Cleats Market Size, Share, and Industry Trends Forecast 2026-2036
Soccer Cleats Market Insights
Premium knit-upper specifications is reorganizing the competitive hierarchy in soccer cleats. Nike leverages its Flyknit manufacturing scale to control costs at the high-performance tier. Adidas anchors its position through Primeknit integration across club and national team supply contracts. Puma differentiates via evoKNIT specialization in lightweight speed-position boots.
Soccer cleats are performance footwear engineered with stud configurations optimized for traction across natural and synthetic pitch surfaces, typically incorporating thermoplastic polyurethane outsoles and engineered mesh or knitted synthetic uppers designed to balance ball control, weight reduction, and ankle stability during multidirectional athletic movement. Firm Ground cleats dominate volume due to universal pitch compatibility across seasonal conditions, while Artificial Ground variants represent the fastest-expanding category as municipal and club investments in third-generation turf accelerate. Synthetic materials now command the largest material share by volume, though Knit constructions capture disproportionate margin pools through technical differentiation and athlete endorsement premiums.
ISO standards for footwear safety and performance benchmarking shape baseline product requirements, while national sporting federations and league operators impose additional equipment compliance protocols that filter market access. The US Consumer Product Safety Commission monitors youth cleat safety, and EU REACH chemical restrictions constrain adhesive and dye formulations used in European distribution. Stakeholders must track evolving turf surface standards and corresponding stud-pattern regulations as hybrid pitch installations multiply across competitive venues.
Market Dynamics
Knit-upper manufacturing scale is compressing legacy leather supply chains as thermoplastic polyurethane outsole integration demands tighter material coordination across tier-one suppliers.
Growth Catalysts
- EU REACH chemical restrictions:REACH compliance mandates on adhesive formulations are accelerating bio-based synthetic adoption among European distributors seeking regulatory pre-clearance advantages.
- Third-generation turf municipal investments:Municipal pitch installations across Brazil and Germany are expanding Artificial Ground cleat replacement cycles beyond traditional seasonal patterns.
- Academy pipeline density:Brazil's favela-to-pro development systems sustain multi-tier demand concentration unmatched by club-dependent markets.
Market Restraints
- Petrochemical input volatility:Thermoplastic polyurethane resin prices fluctuate with crude derivatives, compressing margin predictability for synthetic-dominant product lines.
- Stud-pattern standardization gaps:Hybrid pitch proliferation without unified traction protocols forces redundant SKU proliferation across regional variants.
- ISO 20344 testing bottlenecks:Footwear safety certification queues at accredited laboratories extend commercialization timelines for new constructions.
Strategic Opportunities
- Bio-based synthetic convergence:Material innovators combining algae-derived polymers with knit structures can capture premium positioning ahead of leather displacement completion.
- Direct-to-academy distribution:Bypassing retail intermediaries to supply Brazilian and German youth development systems reduces price-tier leakage.
- US Consumer Product Safety Commission youth mandates:Emerging CPSC traction-testing protocols for under-14 cleats create first-mover certification advantages.
Industry Challenges
- Knit technician scarcity:Flyknit-equivalent manufacturing expertise concentrates at a handful of Asian contract manufacturers, constraining capacity expansion.
- Multi-surface stud compliance:Engineering teams must reconcile Firm Ground universal compatibility against Artificial Ground specialization without SKU explosion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soccer Cleats Market |
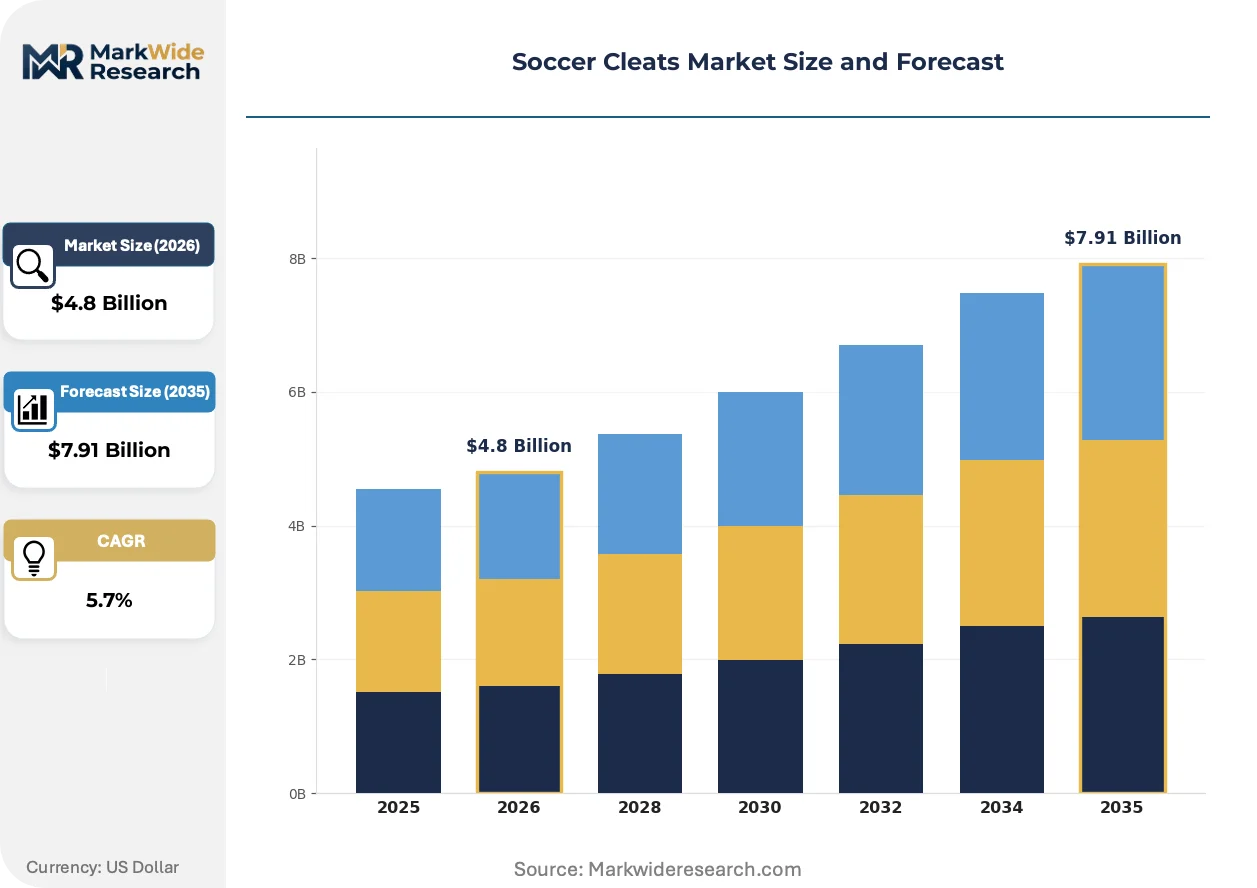
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firm Ground, Soft Ground, Artificial Ground, Turf Material: Leather, Synthetic, Mesh, Knit End User: Children, Adults, Professionals, Amateurs Price Tier: Premium, Mid-range, Budget, Discounted |
| Companies Covered | New Balance, Sokito, Nike, Under Armour, Skechers, Adidas, Mizuno, Lotto, Puma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soccer Cleats Market Trends and Innovations
Material science convergence with biometric customization is fragmenting the traditional three-tier product architecture. Performance segmentation now follows positional biomechanics rather than price brackets alone.
Engineered mesh uppers with zonal compression mapping are decomposing the leather-to-synthetic transition timeline. Elite academies in Germany and Brazil now specify knit constructions as standard issue, compressing the remaining leather share to heritage positioning. The structural consequence is margin pool migration toward material innovators with captive polymer synthesis capabilities.
REACH chemical restrictions on azo dyes and heavy-metal adhesives are forcing reformulation investments across European distribution channels. Manufacturers serving EU markets must maintain dual supply chains: REACH-compliant for Europe, conventional for less regulated geographies. Artificial Ground variants face the steepest compliance costs due to adhesive-intensive outsole bonding requirements.
Youth league procurement committees are consolidating supplier relationships around certified safety portfolios. In the United States, club administrators now demand CPSC-aligned traction documentation before bulk purchases, displacing parent-driven retail selection. Brazil's municipal league systems exhibit the most advanced committee structures, with technical directors negotiating academy-wide contracts directly with manufacturers.
Soccer Cleats Market Segmentation
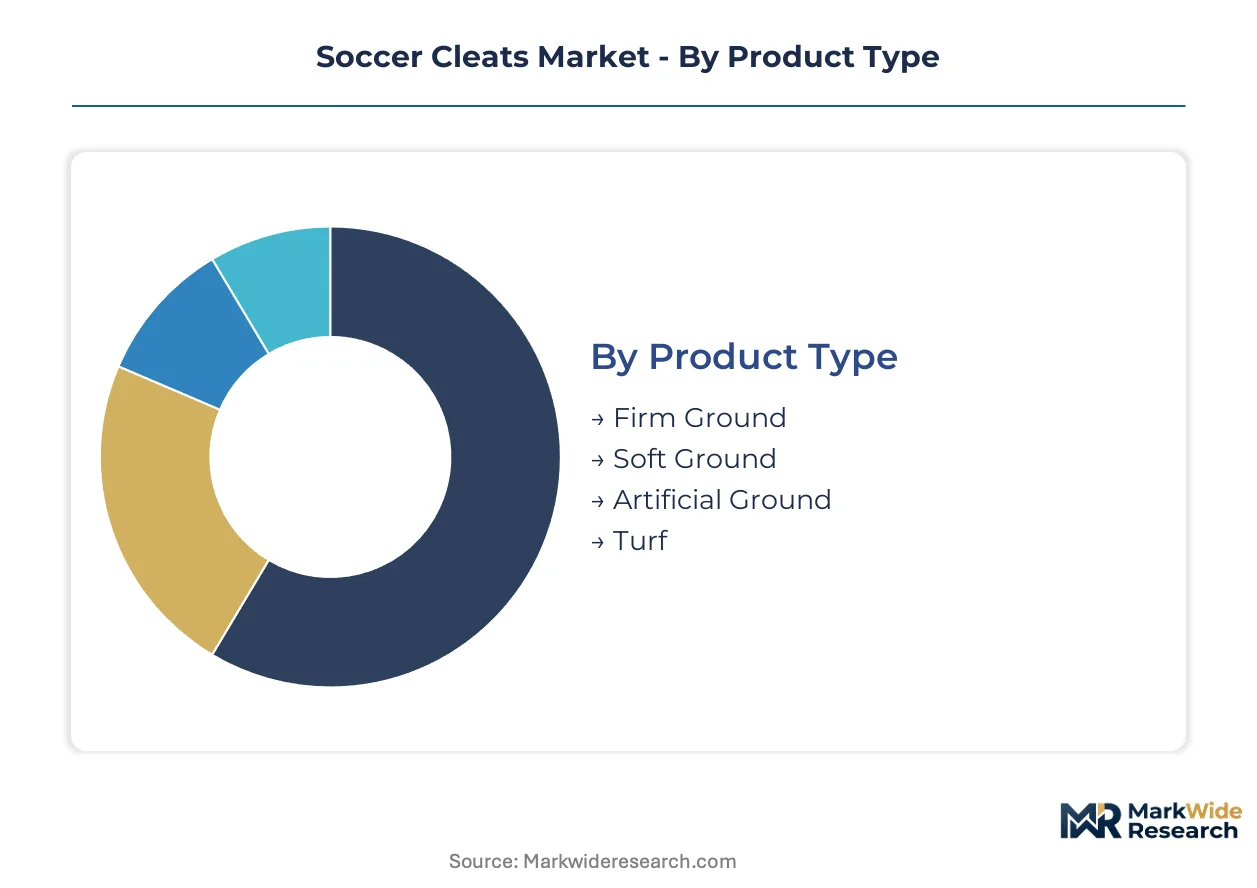
Soccer cleat segmentation tracks how pitch surface specialization, material substitution, and procurement channel evolution fragment demand. Manufacturers must align SKU architecture against these cross-cutting dimensions to avoid inventory mismatches.
Product Type:
Artificial Ground variants face the steepest substitution pressure as hybrid pitch installations blur surface definitions and compress dedicated SKU viability.
- Firm Ground:Stud configurations with conical or bladed thermoplastic polyurethane cleats engineered for natural grass traction across variable moisture conditions. Brazilian municipal leagues and German academy systems sustain replacement cycles through year-round training schedules on hybrid natural surfaces.
- Artificial Ground:Shorter, denser stud patterns with hollow conical designs distribute load across third-generation turf infill. Installations across São Paulo and Berlin municipal systems are expanding replacement frequency beyond traditional seasonal boundaries.
- Soft Ground:Replaceable metal-tipped studs for saturated natural pitches predominate in Northern European winter competition schedules.
- Turf:Rubber-studded outsoles for older generation artificial surfaces retain niche demand in US recreational leagues.
Firm Ground anchors the volume base while Artificial Ground gains share at the steepest rate.
Material:
Cost tier stratification determines margin capture, with synthetic and knit constructions commanding premium positioning against legacy leather.
- Synthetic:Thermoplastic polyurethane and bio-based polymer uppers deliver consistent performance at controlled cost points. REACH-compliant formulations from European distributors are displacing conventional petrochemical variants.
- Knit:Engineered yarn constructions with zonal compression mapping reduce weight while maintaining structural integrity. German elite academies now specify knit as standard issue, compressing leather to heritage positioning.
- Leather:Kangaroo and calfskin uppers retain professional player preference for ball touch sensitivity.
- Mesh:Engineered textile uppers with synthetic overlays occupy entry-level price tiers in Brazilian favela-to-pro pipelines.
Synthetic materials anchor the volume base while Knit climbs the fastest toward margin leadership.
End User:
Customer type fragmentation splits procurement channels between parent-driven retail, club-administered bulk purchasing, and professional endorsement contracts.
- Adults:Recreational and semi-competitive players drive replacement cycles through wear-rate patterns on artificial surfaces.
- Professionals:Athletes with federation supply contracts and personal endorsement agreements generate disproportionate margin through limited-edition releases.
- Children:CPSC-aligned safety certification requirements in US youth leagues are consolidating supplier relationships around certified portfolios.
- Amateurs:Club-affiliated recreational players in Brazilian municipal systems purchase through committee-negotiated academy contracts.
Adults anchor the volume base while Professionals concentrate margin capture.
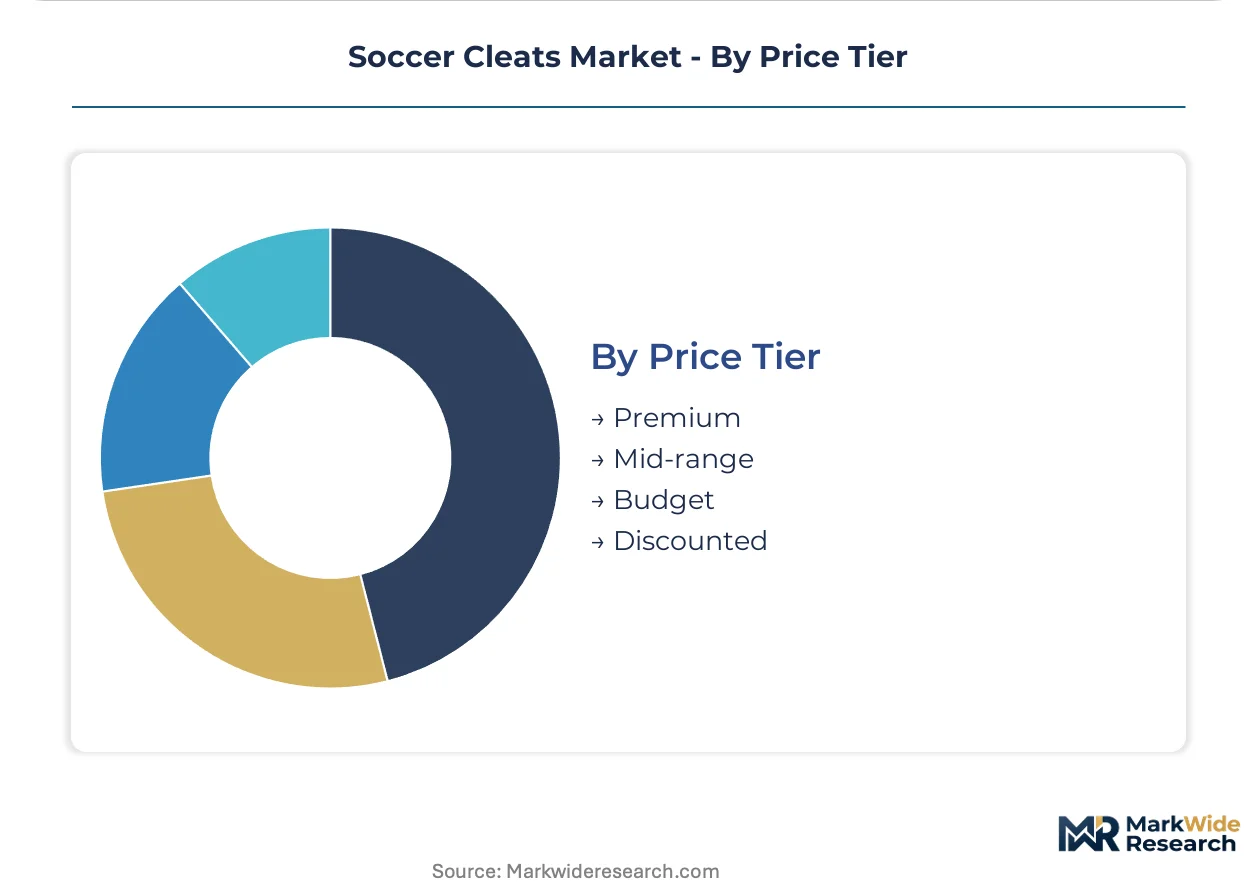
Price Tier:
Volume distribution stratifies across certification grade, performance specification, and procurement channel rather than simple quality ladders.
- Premium:Athlete-endorsed knit constructions with biometric customization and limited distribution. German Bundesliga and Brazilian Serie A supply contracts validate positioning.
- Mid-range:Synthetic-dominant specifications with club licensing and academy standard-issue status. São Paulo municipal procurement committees negotiate direct manufacturer contracts at this tier.
- Budget:Conventional synthetic constructions for recreational frequency without performance benchmarking requirements.
- Discounted:Prior-season colorways and volume clearance through secondary channels serving price-sensitive Brazilian youth segments.
Mid-range anchors the volume base while Premium expands most quickly through endorsement premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in soccer cleats track manufacturing concentration against consumption gravity. Brazil and Germany run structural deficits, importing finished products while exporting design specifications and academy procurement contracts. Asia-Pacific contract manufacturers capture the assembly value, with Vietnam and Indonesia dominating thermoplastic polyurethane outsole production.
Brazil
Favela-to-pro academy pipelines sustain replacement cycles unmatched by club-dependent markets. ANVISA monitors youth footwear safety standards for municipal league procurement. São Paulo's municipal committee structures negotiate manufacturer-direct contracts, bypassing retail intermediaries entirely.
Germany
Bundesliga supply contracts and elite academy standard-issue specifications drive premium knit adoption. REACH chemical restrictions mandate bio-based adhesive formulations across EU distribution channels. Bavaria's manufacturing clusters specialize in thermoplastic polyurethane resin synthesis for outsole integration.
United States
CPSC-aligned traction documentation requirements consolidate supplier relationships around certified youth portfolios. Club administrators now mandate safety certification before bulk purchases. California's recreational league density sustains Artificial Ground variant demand through year-round synthetic pitch utilization.
Vietnam
Contract manufacturing scale for knit-upper assembly concentrates Flyknit-equivalent production expertise. The country's ministry of industry and trade oversees footwear export quality benchmarks. Ho Chi Minh City industrial zones host thermoplastic polyurethane outsole molding facilities serving European and North American brands.
United Kingdom
Premier League endorsement premiums validate limited-edition release positioning. The Health and Safety Executive monitors workplace standards in footwear distribution warehouses. Greater Manchester's sporting goods logistics hubs coordinate pan-European inventory allocation for synthetic and knit constructions.
Soccer Cleats Market Competitive Landscape
Concentration sits with diversified sporting goods conglomerates controlling manufacturing scale and athlete endorsement networks. Three to four entities capture the majority of professional supply contracts and academy procurement relationships. Strategic archetypes include: knit-technology specialists leveraging proprietary yarn engineering, bio-based material innovators with captive polymer synthesis, and heritage leather houses repositioning toward premium nostalgia positioning. Competitive moves center on direct-to-academy distribution bypasses and REACH-compliant formulation pre-certification.
Within the conglomerate tier, Nike and Adidas anchor opposite ends of the supply contract spectrum, with Puma occupying a specialist position in speed-position boot architectures. New Balance represents the challenger archetype, while Under Armour exemplifies the cross-sport entrant attempting soccer-specific credibility. Mizuno and Lotto sit within heritage-positioning segments, and Skechers occupies the value-tier expansion vector. Sokito anchors the sustainability-native challenger archetype with bio-based synthetic specialization.
| Leading Market Players |
|---|
| New Balance |
| Sokito |
| Nike |
| Under Armour |
| Skechers |
| Adidas |
| Mizuno |
| Lotto |
| Puma |
| Others |
Pricing and Supply Chain Analysis
Knit-upper displacement of leather constructions simultaneously concentrates thermoplastic polyurethane outsole sourcing in Vietnam and Indonesia while compressing margin pools at heritage pricing tiers. REACH-compliant bio-based adhesive formulations add certification-driven cost premiums that manufacturers absorb or pass through depending on academy contract leverage.
Pricing Analysis
Professional club procurement committees anchor three-tier pricing structure across premium, standard, and economy levels, with athlete endorsement premiums separating limited-edition knit releases from academy standard-issue synthetics. Price differentiation hinges on ISO 20344 certification grade and biometric customization depth. Cost compression in mid-range synthetic tiers is intensifying because petrochemical input volatility feeds directly into contract renegotiation cycles. Brazilian favela-to-pro pipeline buyers exhibit highest price sensitivity; Bundesliga supply contract holders show lowest.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for thermoplastic polyurethane resin shipments bound for Bavarian outsole molding facilities. Manufacturing gravity centers on Vietnam, Indonesia, and China, with knit-upper assembly expertise concentrating in Ho Chi Minh City industrial zones. Raw material dependencies span crude-derived TPU resins, algae-based polymer feedstocks, and REACH-compliant adhesive formulations. Single-source vulnerability sits with Flyknit-equivalent technician scarcity at Asian contract manufacturers. Distribution runs through Brazilian municipal procurement committees, German academy direct contracts, and US club administrator bulk purchasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soccer cleats constitute a regulatory-entrenchment defensive moat where ISO traction-testing certification and REACH chemical compliance create multi-year supplier lock-in with academy and municipal procurement systems.
For Market Incumbents: Shield market position by deepening captive polymer synthesis capabilities in Bavaria to offset petrochemical volatility exposure. Secure multi-year academy supply contracts in São Paulo and Berlin before bio-based synthetic challengers achieve REACH pre-certification scale. Prioritize ISO 20344 testing queue relationships to compress new construction commercialization timelines against emerging knit-technology specialists. For New Entrants and Emerging Players: Differentiate on bio-based synthetic convergence with algae-derived polymer formulations ahead of leather displacement completion. Target US youth league CPSC certification white space where incumbent portfolios lag emerging traction-testing mandates. Pursue direct-to-academy distribution bypasses in Brazilian municipal systems to circumvent retail intermediary margin capture. For Investors and Strategic Acquirers: The market sits at a material-substitution acceleration phase that favors bio-based innovators with captive synthesis capabilities over heritage leather repositioning plays. Long-term viability across the next decade hinges on regulatory compliance infrastructure rather than brand nostalgia alone. Monitor EU REACH expansion scope and CPSC youth mandate rollout velocity as inflection indicators for premium tier margin migration timing.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Pre-Certification | European distributors gain regulatory pre-clearance advantages ahead of chemical restriction expansions. |
| Direct-to-Academy Distribution Bypass | São Paulo municipal committees negotiate manufacturer-direct contracts eliminating retail margin leakage. |
| Knit-Upper Manufacturing Scale Expansion | Vietnamese contract manufacturers capture Flyknit-equivalent technician expertise concentration. |
| Bio-Based Synthetic Polymer Integration | Algae-derived formulations displace petrochemical inputs amid REACH adhesive reformulation mandates. |
| CPSC Youth Certification First-Mover Investment | US club administrators consolidate supplier relationships around certified safety portfolios. |
Research Methodology
Cross-validation between primary interviews with footwear procurement directors, academy technical directors, and contract manufacturing operations heads and secondary validation through customs trade data, Bundesliga supply contract disclosures, and ANVISA youth safety filings anchors the qualitative findings. Bottom-up segmentation triangulation against top-down macroeconomic indicators ensures demand-side and supply-side consistency across the analysis window.
Sensitivity analysis around petrochemical input volatility scenarios and REACH compliance cost trajectories informs the analytical framework throughout the forecast period. Segmentation dimensions span pitch surface specialization, material construction tier, end-user procurement channel, and regional regulatory cluster. CAGRs derive from replacement cycle frequency modeling across Brazilian academy systems and German municipal leagues, with biometric customization adoption curves and third-generation turf installation rates as soccer-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained academy pipeline density and REACH chemical restriction enforcement assumptions; material deviation in either would warrant model refresh. Forecasts reflect base-case assumptions around knit-upper manufacturing scale expansion and CPSC youth mandate implementation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Shuttlecock Market
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Pitching Machine Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
High-End Bicycle Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Kneeboard Market
Sports Equipment
Global Basketball Shoes Market
Sports Equipment
Global Kinesio Tape Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Table Tennis Equipment Market