
 Shooting Ranges Market | 2026-2036
Shooting Ranges Market Size, Share, and Industry Trends Forecast 2026-2036
Shooting Ranges Market Analysis
A capital-intensity divergence between legacy steel-target manufacturers and digital simulation providers is bifurcating competitive dynamics across the sector. Cubic Corporation leverages its defense electronics heritage to dominate integrated live-virtual-constructive training architectures. Saab AB anchors its position through sustained R&D investment in ballistics modeling and tactical scenario software. Theissen Training Systems GmbH competes on precision-engineered steel target systems and automated range control hardware for European military customers.
Shooting ranges encompass controlled environments designed for firearms proficiency development, incorporating ballistic containment systems, air filtration infrastructure, and acoustic mitigation to specified decibel thresholds. These facilities serve military qualification protocols, law enforcement certification programs, and civilian marksmanship training with strict adherence to projectile containment and lead exposure limits. Indoor ranges command premium infrastructure investment due to HVAC and backstop requirements, while virtual ranges are capturing fastest-growing demand as ammunition costs pressure training budgets. Tactical ranges concentrate margin pools through specialized scenario replication for special operations and SWAT units.
The US Environmental Protection Agency enforces lead abatement standards that compel indoor range operators to retrofit ventilation and bullet-trap systems, directly shaping capital allocation patterns. The Occupational Safety and Health Administration mandates exposure thresholds that drive demand for automated target retrieval and separated shooter-instructor positioning. National Rifle Association range certification programs influence insurance underwriting and municipal zoning decisions for new construction. Stakeholders must monitor evolving state-level preemption statutes governing local range zoning, as these determine greenfield development feasibility in high-growth metropolitan corridors.

Market Dynamics
The US Environmental Protection Agency's lead abatement mandates are forcing indoor range operators into capital-intensive ventilation and bullet-trap retrofits, redirecting investment flows toward compliant infrastructure while compressing margins for legacy facilities.
Growth Catalysts
- Live-fire training mandates:NATO procurement agencies are expanding qualification infrastructure across member states. Military end-users drive sustained demand for ballistic containment systems and automated target control.
- OSHA exposure thresholds:The Occupational Safety and Health Administration mandates stricter airborne lead limits. Range operators install automated retrieval systems and separated shooter-instructor positioning to achieve compliance.
- Texas-Florida-Arizona corridor:Civilian construction permits have risen sharply in these states. Municipal zoning boards in high-growth metropolitan areas are approving greenfield range developments.
Market Restraints
- Lead remediation cost structure:HVAC and backstop upgrades for indoor facilities require substantial capital outlay. Small operators face liquidity constraints when retrofitting aging infrastructure.
- Steel target supply concentration:Precision-engineered reactive target systems depend on specialized European foundries. Geopolitical friction threatens just-in-time delivery for range construction timelines.
- Ammunition cost volatility:Raw material price swings for brass and propellant compress training budgets. Law enforcement agencies are curtailing live-fire hours in favor of simulation alternatives.
Strategic Opportunities
- Virtual range convergence:Digital ballistics modeling and tactical scenario software are merging with live-fire infrastructure. Integrated live-virtual-constructive architectures capture fastest-growing demand segments.
- Special operations scenario replication:SWAT units and tactical teams seek specialized urban combat simulations. Premium margin pools concentrate in facilities offering force-on-force training environments.
- NRA certification tailwinds:National Rifle Association range standards influence insurance underwriting and municipal bonding. Certified facilities gain preferential zoning treatment in contested jurisdictions.
Industry Challenges
- Ballistics engineering talent scarcity:Specialized expertise in projectile containment and acoustic mitigation is concentrated among retiring defense-sector professionals. Range developers compete for limited qualified consultants.
- Legacy system integration friction:Automated range control hardware must interface with decades-old mechanical target carriers. Retrofit projects face extended commissioning timelines and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shooting Ranges Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Indoor Ranges, Outdoor Ranges, Virtual Ranges, Tactical Ranges End User: Law Enforcement, Military, Recreational Shooters, Competitors Service Type: Membership Services, Training Courses, Equipment Rental, Events Technology: Electronic Targets, Ballistic Simulation, Safety Systems, Surveillance |
| Companies Covered | Cubic Corporation, Action Target Inc., Polytronic International AG, Saab AB, Range Systems Inc., Laser Shot Inc., Theissen Training Systems GmbH, InVeris Training Solutions, Zen Technologies Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shooting Ranges Market Emerging Trajectories
Digital simulation technologies are fragmenting traditional training economics, compressing the boundary between physical and virtual proficiency development while forcing infrastructure providers to reposition around hybrid delivery models.
Advanced ballistics modeling software is decomposing the traditional live-fire monopoly on qualification protocols. Military procurement agencies in Germany and the United Kingdom are piloting blended training regimens that reduce ammunition consumption by half. This technology is decomposing capital allocation patterns across the sector as operators defer steel-target investments in favor of software licenses.
The US Environmental Protection Agency is tightening enforcement of its National Ambient Air Quality Standards for lead particulates. Indoor range operators face mandatory ventilation audits and bullet-trap replacement schedules. European facilities under REACH regulations are experiencing parallel compliance pressure, with French and German operators accelerating filtration upgrades ahead of inspection deadlines.
Law enforcement agencies are unbundling after-sales service from initial range construction contracts. Municipal buyers in Texas and Florida now separate maintenance agreements from capital procurement, creating recurring revenue pressure for infrastructure providers. This shift is most visible among mid-sized police departments seeking operational flexibility without long-term vendor lock-in.
Shooting Ranges Market Segmentation
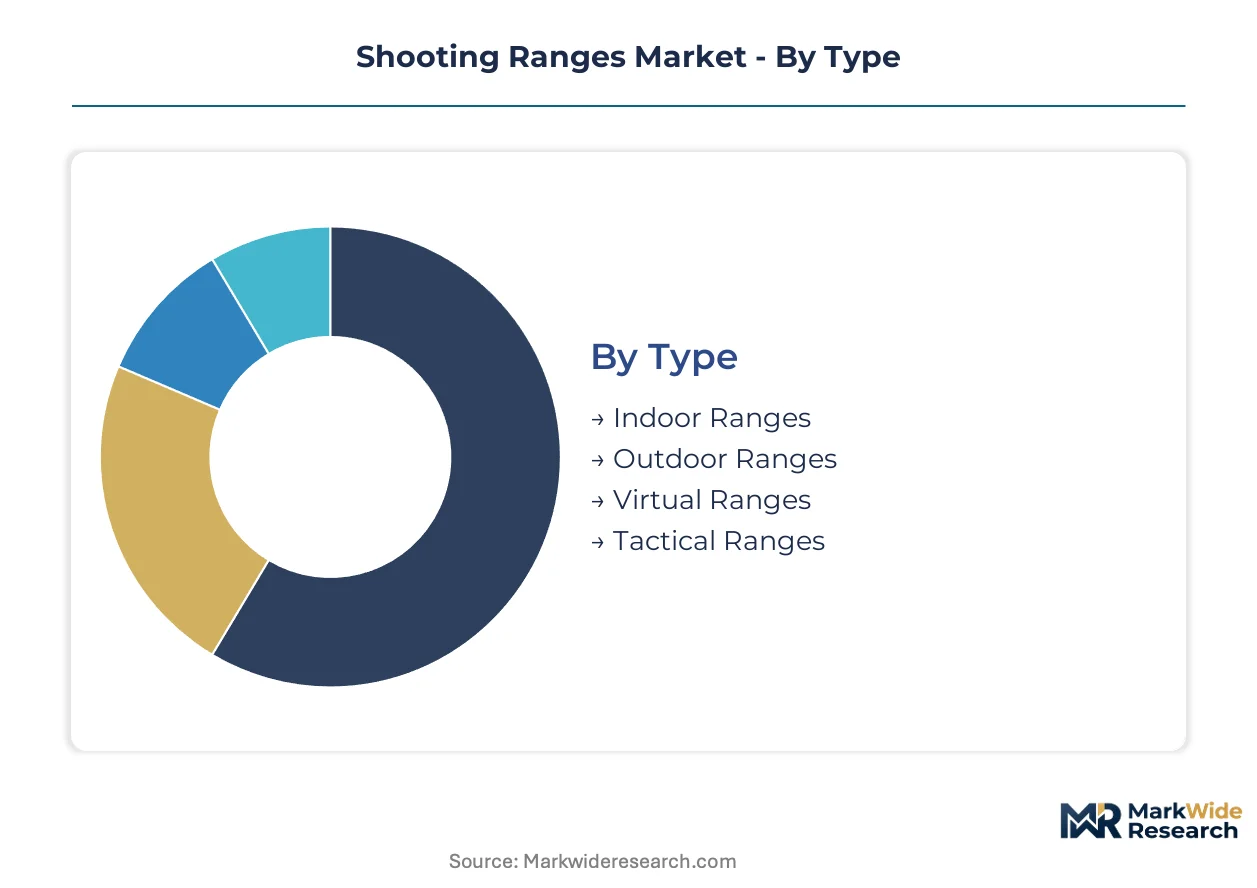
Segmentation reveals how capital allocation patterns diverge across facility types and customer bases. Range operators configure infrastructure investments differently when serving military procurement agencies versus recreational shooters, while technology choices determine recurring revenue potential and regulatory compliance burdens.
Type:
Margin pools concentrate in facilities that balance high throughput with premium pricing power through specialized scenario offerings.
- Indoor Ranges:These facilities incorporate HVAC filtration systems, steel bullet-trap backstops, and acoustic mitigation to EPA-specified lead particulate thresholds. Demand concentrates in Texas, Florida, and Arizona where municipal zoning boards have approved sharp permit increases for metropolitan greenfield developments. Operators face capital-intensive retrofit cycles driven by OSHA exposure mandates.
- Virtual Ranges:Digital ballistics modeling and tactical scenario software reduce ammunition consumption while expanding training throughput. Military procurement agencies in Germany and the United Kingdom are piloting blended regimens that compress live-fire requirements, positioning this segment for steepest expansion trajectory as budget pressures mount.
- Outdoor Ranges:Open-air facilities minimize ventilation infrastructure but require expansive land parcels and noise abatement buffers.
- Tactical Ranges:Urban combat simulations and force-on-force environments command premium pricing from SWAT units and special operations.
The dominant share belongs to Indoor Ranges, while Virtual Ranges is closing the gap fastest.
End User:
Customer type determines contract structure, with military and law enforcement buyers favoring multi-year procurement agreements while recreational users drive membership economics.
- Military:NATO procurement agencies sustain demand for ballistic containment systems and automated target control through qualification infrastructure expansion. Live-fire training mandates lock in predictable capital cycles across member states.
- Law Enforcement:Municipal buyers in Texas and Florida increasingly unbundle maintenance agreements from initial construction contracts. Ammunition cost volatility is curtailing live-fire hours in favor of simulation alternatives.
- Recreational Shooters:Individual marksmanship enthusiasts generate recurring revenue through membership models and lane rentals.
- Competitors:Precision shooting athletes require specialized distance configurations and electronic scoring systems.
Military end-users anchor volume commitments, though Law Enforcement is shifting procurement patterns most dramatically.
Service Type:
Revenue mix varies by operational model, with training and events capturing disproportionate margin against fixed-cost infrastructure.
- Training Courses:Structured certification programs for concealed carry, tactical response, and competition preparation command per-session premiums. NRA certification standards influence insurance underwriting and municipal bonding for course-offering facilities.
- Membership Services:Recurring lane access and priority booking generate predictable cash flows that amortize fixed infrastructure investments.
- Equipment Rental:Firearm and protective gear provision lowers barriers for novice participants.
- Events:Corporate team-building and private functions monetize off-peak capacity.
Training Courses extract highest per-visit yield, while Membership Services provides revenue stability.
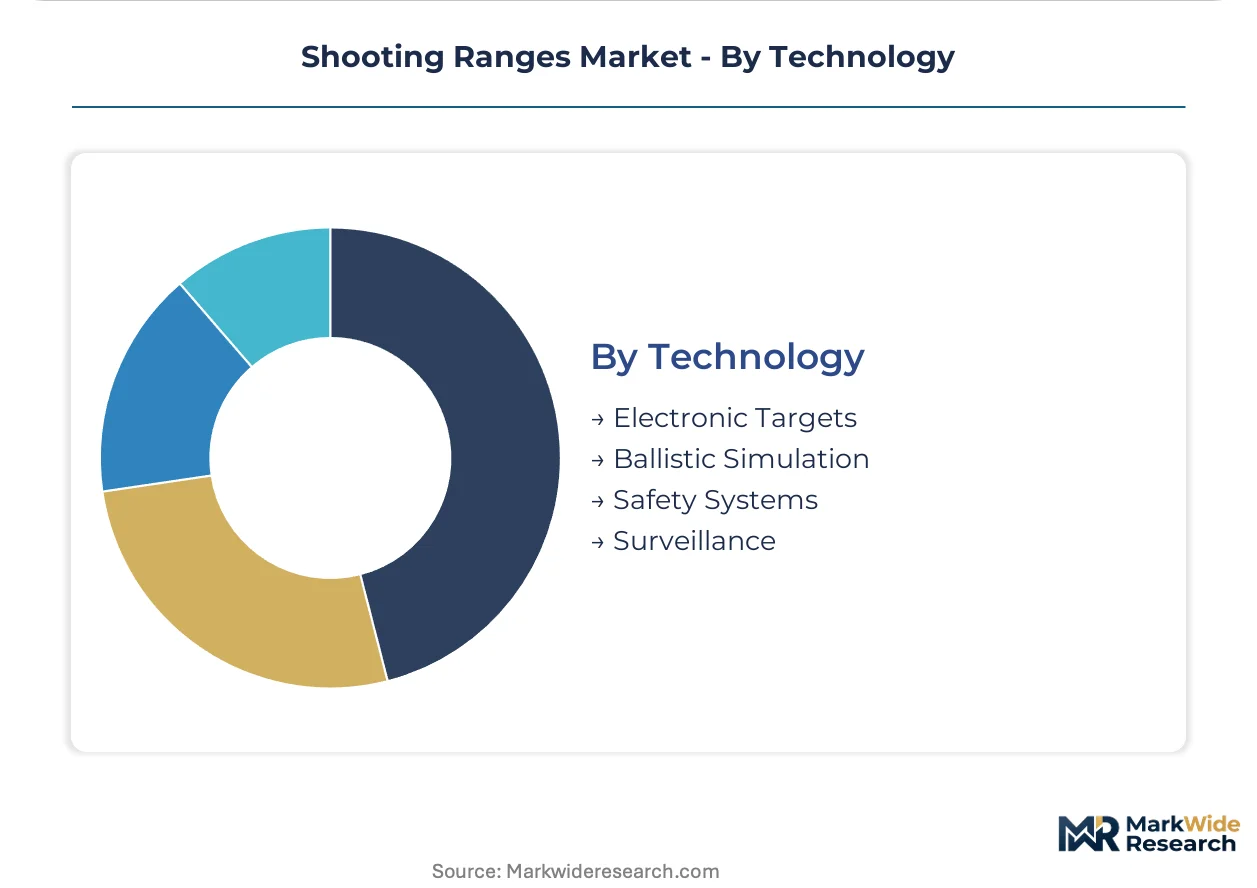
Technology:
Technology selection shapes both compliance posture and competitive differentiation against simulation alternatives.
- Electronic Targets:Automated retrieval systems with instant shot grouping display reduce range officer staffing needs. OSHA exposure thresholds are accelerating separated shooter-instructor positioning investments.
- Safety Systems:Ventilation controls, ballistic baffles, and lead collection infrastructure dominate capital budgets for indoor facilities. EPA enforcement of National Ambient Air Quality Standards is tightening audit schedules and replacement timelines.
- Ballistic Simulation:Software-based marksmanship training compresses ammunition expenditure while expanding scenario complexity.
- Surveillance:Range monitoring and access control systems satisfy liability underwriting requirements.
Safety Systems absorbs the largest capital share, with Electronic Targets expanding most quickly as labor costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Western European military procurement corridors while cost-competitive capacity clusters across the American Southwest. This asymmetry shapes investment allocation and technology sourcing patterns across national markets.
United States
Texas, Florida, and Arizona municipal zoning boards have approved sharp permit increases for metropolitan greenfield range developments. The Environmental Protection Agency enforces lead abatement standards that compel indoor operators into ventilation and bullet-trap retrofits. OSHA exposure thresholds drive demand for automated retrieval systems in high-growth metropolitan corridors.
Germany
Bundeswehr procurement agencies sustain demand for precision-engineered steel target systems and automated range control hardware. REACH regulations accelerate filtration upgrades ahead of inspection deadlines for indoor facilities. Bavaria and North Rhine-Westphalia host concentrated defense electronics heritage supporting integrated training architectures.
United Kingdom
Ministry of Defence pilot programs are reducing ammunition consumption through blended live-virtual-constructive regimens. National Ambient Air Quality Standards enforcement tightens audit schedules for legacy indoor infrastructure. Scotland and Northern England concentrate outdoor range developments minimizing ventilation capital requirements.
France
ANSM oversight parallels EPA pressure on lead particulate containment for indoor facilities. Special operations units seek premium urban combat simulation environments commanding margin premiums. Provence-Alpes-Côte d'Azur and Île-de-France anchor tactical scenario replication demand from GIGN and RAID units.
Sweden
Saab AB anchors sustained R&D investment in ballistics modeling software serving NATO qualification protocols. Swedish military procurement drives integrated live-virtual-constructive training architecture adoption. Stockholm and Gothenburg corridors concentrate defense electronics talent supporting simulation technology development.
Shooting Ranges Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Defense electronics heritage companies dominate integrated architecture development while precision engineering specialists capture steel-target and automated control hardware segments. Three archetypes define competitive positioning: integrated system architects, precision hardware fabricators, and digital simulation pure-plays. M&A activity concentrates on software capabilities while capacity expansion targets the Texas-Florida-Arizona corridor.
Among defense electronics heritage companies, Cubic Corporation exemplifies integrated live-virtual-constructive architecture development. Saab AB occupies a position within ballistics modeling and tactical scenario software specialization. Theissen Training Systems GmbH represents precision-engineered steel target and automated range control hardware fabrication for European military customers.
| Leading Market Players |
|---|
| Cubic Corporation |
| Action Target Inc. |
| Polytronic International AG |
| Saab AB |
| Range Systems Inc. |
| Laser Shot Inc. |
| Theissen Training Systems GmbH |
| InVeris Training Solutions |
| Zen Technologies Limited |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between NATO procurement agencies and European steel-target manufacturers lock in supply access while providing price visibility across volatile raw material cycles. These agreements insulate military end-users from spot-market brass and propellant fluctuations while compressing margins for non-contracted civilian operators facing spot ammunition purchases.
Pricing Analysis
Configured-to-order pricing for specialized tactical ranges commands substantial premiums over standardized indoor lane configurations. Three-tier pricing structure across premium, standard, and economy levels separates force-on-force simulation facilities from basic membership clubs and municipal training centers. Price differentiation rests on OSHA compliance certification tier and after-sales service bundling. Pricing pressure stems from ammunition cost volatility curtailing law enforcement live-fire budgets. Municipal buyers exhibit highest price sensitivity, while special operations units demonstrate lowest elasticity for scenario replication capabilities.
Supply Chain Analysis
Germany and Sweden anchor precision-engineered steel target fabrication and automated range control hardware production for European defense customers. China and South Korea supply electronic target components and HVAC filtration systems that indoor facilities require for EPA compliance. Raw material dependencies encompass specialized steel alloys, lead particulate filtration media, and ballistics-grade rubber for bullet-trap systems. Single-source vulnerability concentrates in European foundries supplying reactive target systems to NATO members. Distribution runs through direct military procurement channels and regional construction contractors serving civilian greenfield developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live-virtual-constructive training architectures are redefining platform economics as digital ballistics software achieves interoperability with legacy steel-target infrastructure. This ecosystem shift rewards operators who bridge physical and virtual proficiency development.
For Market Incumbents: Shield core military relationships by accelerating integrated live-virtual-constructive architecture development before pure-play simulation vendors achieve NATO qualification protocol penetration. Deepen backward integration into ballistics modeling software to capture recurring licensing revenue displacing steel-target replacement cycles. For New Entrants and Emerging Players: Lead with subscription-based virtual range deployments targeting mid-sized law enforcement agencies unbundling maintenance from capital procurement in Texas and Florida. The penetrable white-space sits in automated target retrieval systems for aging indoor facilities facing OSHA retrofit mandates. A direct-to-municipal-buyer SaaS model bypasses incumbent construction-contractor channels. For Investors and Strategic Acquirers: Digital simulation pure-plays with established military pilot program relationships represent the highest-conviction acquisition archetype for long-term viability across the next decade. Ballistics software capabilities that reduce ammunition consumption by half are displacing capital-intensive steel infrastructure. The signal to watch is Bundeswehr and Ministry of Defence procurement shifting from hardware-centric to software-weighted training budgets.| Strategic Initiative | Industry Significance |
|---|---|
| Live-Virtual-Constructive Integration | Merges Cubic Corporation defense electronics with Saab AB ballistics modeling for NATO qualification protocols. |
| EPA Compliance Retrofit Services | Captures recurring revenue from indoor range operators facing mandatory ventilation and bullet-trap upgrades. |
| Special Operations Scenario Licensing | Monetizes urban combat simulation IP through per-use fees from SWAT units and tactical teams. |
| Texas-Florida-Arizona Corridor Expansion | Positions construction capacity where municipal zoning boards have approved sharp permit increases. |
| Automated Target Retrieval Development | Addresses OSHA exposure thresholds through separated shooter-instructor positioning systems. |
Methodological Framework
Cross-validation between regulatory filing analysis and construction permit databases anchors the qualitative findings on greenfield development feasibility. Primary interviews with range operators, military procurement officers, HVAC engineering consultants, and municipal zoning administrators combined with secondary validation against EPA enforcement records, OSHA compliance databases, and NATO procurement disclosures. Bottom-up facility counts across Texas, Florida, Arizona, Germany, and the United Kingdom triangulate against top-down military training budget allocations.
Sensitivity analysis across ammunition price volatility scenarios and regulatory enforcement intensity levels shapes the analytical framework over the projection horizon. Segmentation dimensions encompass facility type, end-user category, service model, and technology tier alongside regional regulatory cluster. CAGRs derive from facility construction permit trajectories, military procurement cycle timing, and software adoption curves. Industry-specific forecast inputs include lead particulate remediation cost curves and blended training regimen pilot program expansion rates.
The analysis sits within stated boundaries; outcomes outside sustained NATO military spending or accelerated EPA enforcement timelines would require recalibration. Forecasts reflect assumptions regarding ammunition cost stabilization and REACH regulation parallel pressure in European markets. Recalibration cycles align with material shifts in defense procurement priorities and indoor range retrofit completion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
Hunting Equipment and Accessories Market
Sports Equipment
Riding Gear Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Motocross Gears Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Global Darts Market
Sports Equipment
Golf Club Grips Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Surfboard Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Sports Fishing Equipment Market