
 Sports Protective Equipment Market | 2026-2036
Sports Protective Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Protective Equipment Market Intelligence
The push for circular economy principles, particularly within the framework of the EU Green Deal, is repositioning material sourcing for sports protective equipment. This shift encourages the use of recycled polymers and bio-based foams. Nike Inc. leverages its extensive global supply chain and brand recognition to introduce sustainable materials in its product lines. Adidas AG competes by focusing its R&D on high-performance recycled plastics. Under Armour Inc. differentiates through its focus on integrated sensor technology within protective gear for performance analytics.
Sports protective equipment encompasses devices engineered to mitigate injury from impacts, falls, and collisions common in athletic activities. These products often feature a hard polycarbonate outer shell for puncture resistance and an inner layer of energy-absorbing material like expanded polypropylene (EPP) foam. Helmets and eyewear represent high-margin segments driven by safety regulations and technological advancements. Pads and guards, essential for sports such as football and hockey, constitute a major volume driver, with demand tied to participation rates among amateur players and sports academies.
Product design and market access are governed by a complex web of safety standards. In the United States, organizations like the Consumer Product Safety Commission (CPSC) and NOCSAE set forth stringent testing protocols for helmets. In Europe, CE marking is mandatory, certifying that products meet health and safety requirements. Manufacturers must navigate these varied regional standards to compete effectively. The central challenge for producers is integrating smart technologies without pricing equipment out of reach for recreational users.
Market Dynamics
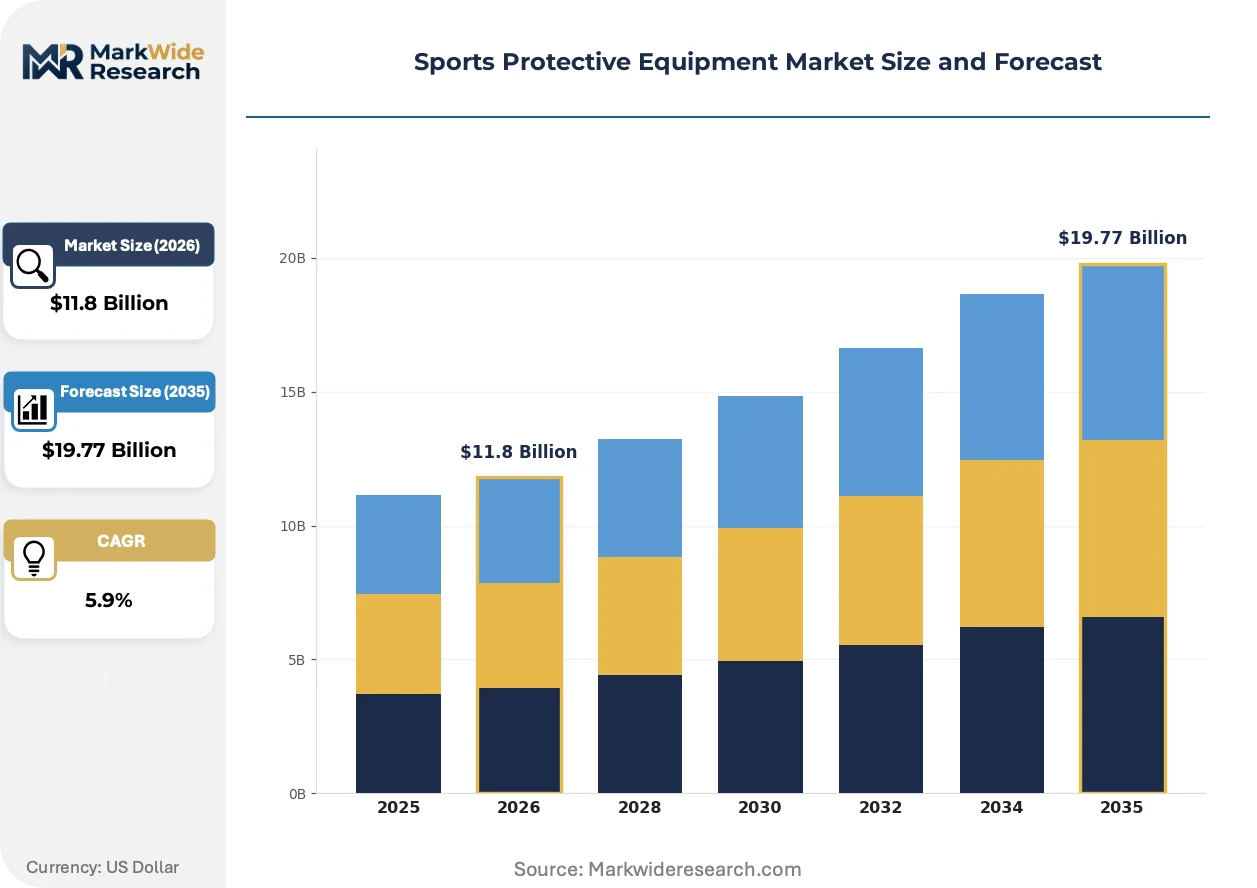
The central dynamic in the sports protective equipment market is the intersection of advanced material science and fragmented regulatory landscapes. The development of materials like multi-layer EVA foams and carbon fiber composites is pushing performance boundaries, yet manufacturers must navigate disparate safety certification protocols from bodies like NOCSAE in the United States and CE marking requirements in Europe.
Growth Catalysts
- Youth Sports Safety Mandates:Heightened awareness of concussion risks is leading to stricter equipment rules in school and youth leagues, particularly in North America and Western Europe, driving volume sales for certified helmets and pads.
- Sustainable Material Innovation:The EU Green Deal framework encourages the adoption of recycled polymers and bio-based foams, creating a demand pull for equipment with a lower environmental footprint and aligning with corporate sustainability goals.
- Organized Sports Expansion:Increasing disposable incomes and government-led health initiatives in countries like India and Brazil are fueling participation in organized sports, expanding the consumer base for essential protective gear.
Market Restraints
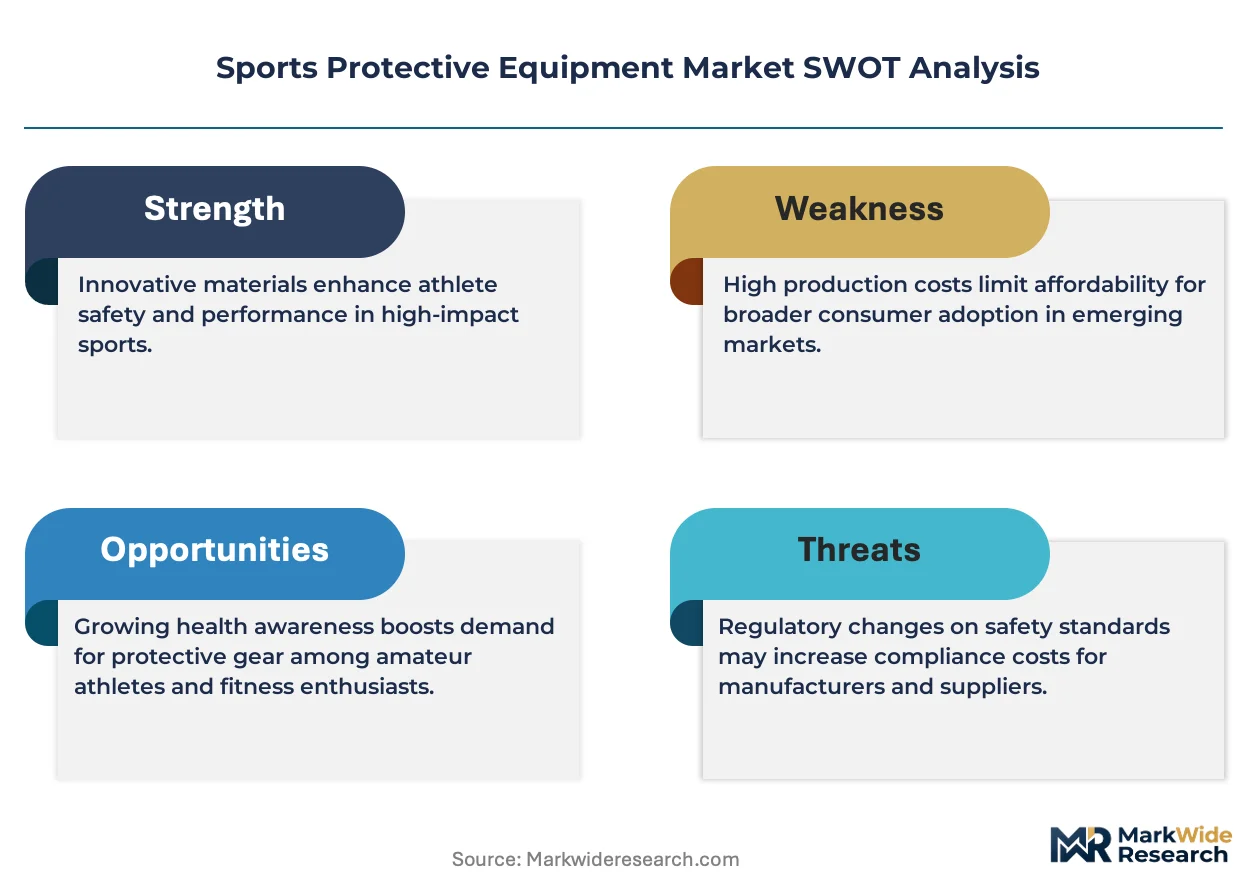
- High Input Costs:The price volatility and high cost of performance materials such as carbon fiber and expanded polypropylene (EPP) foam constrain affordability, particularly for amateur athletes and teams in developing economies.
- Regulatory Compliance Burden:Navigating the divergent and frequently updated testing protocols of standards bodies like the CPSC in the US and corresponding CE directives in Europe creates significant cost and time-to-market barriers.
- Weight and Comfort Trade-offs:The integration of multiple protective layers or smart sensors can increase equipment weight and reduce ventilation, creating a technical challenge to balance enhanced safety with athlete comfort and performance.
Strategic Opportunities
- Emerging Sports Categories:The rise of non-traditional sports like electric scooter racing and competitive drone piloting presents a white-space opportunity for designing and marketing novel, specialized protective equipment.
- Smart Material Integration:Combining sensor technology with advanced textiles and foams offers a path to creating intelligent gear that not only protects but also provides real-time biometric and performance data for athletes and coaches.
- Geographic Underpenetration:Markets in Southeast Asia and Eastern Europe, where organized sports infrastructure is still developing, offer significant growth potential for manufacturers that establish early distribution networks and brand presence.
Industry Challenges
- Recycled Material Validation:A primary operational challenge is sourcing a consistent supply of post-consumer recycled polymers that meet the stringent impact-resistance and durability standards required for protective applications.
- Certification Bottlenecks:The lengthy and expensive process of achieving and maintaining certifications from bodies like NOCSAE can delay product launches and limit the ability of smaller innovators to enter the market.
- Cost-Effective Smart Integration:Manufacturers face difficulty incorporating sensor technology into mass-produced equipment without elevating the final price point beyond the reach of the large recreational and amateur sports segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Protective Equipment Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.77 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Pads, Guards, Mouthguards, Eyewear Material: Polycarbonate, EVA Foam, Kevlar, Neoprene, Carbon Fiber Application: Football, Cricket, Hockey, Cycling, Martial Arts End User: Professional Athletes, Amateur Players, Sports Academies, Recreational Users |
| Companies Covered | Nike Inc., Adidas AG, Amer Sports, Puma SE, Under Armour Inc., Bauer Hockey, MIZUNO Corporation, Franklin Sports Inc., ASICS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Protective Equipment Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of material science and data analytics. This creates a new generation of intelligent protective gear that offers both superior impact absorption and actionable performance insights for athletes. The focus is on making equipment safer, smarter, and more sustainable.
Advanced composite materials, including multi-layer expanded polypropylene (EPP) foams, provide superior multi-impact energy dissipation. Professional and collegiate sports leagues are driving the adoption of these next-generation materials in helmets and body padding. This technology is absorbing market share from traditional single-density foam systems, setting a new safety benchmark for high-contact sports equipment.
European Union regulations, particularly the Corporate Sustainability Reporting Directive (CSRD), are forcing greater transparency in supply chains. The directive compels manufacturers to disclose detailed data on the environmental lifecycle of their products, from raw material sourcing to end-of-life recyclability. The helmet and protective apparel segments are most affected, prompting R&D investment in verifiable bio-based foams and recycled polymers to meet new compliance thresholds.
A distinct behavioral shift from one-time bulk purchasing to demand for customized and personalized gear is evident. This trend disrupts the traditional off-the-shelf retail model, creating an opening for direct-to-consumer (DTC) channels that utilize 3D scanning and bespoke manufacturing. This movement toward personalization is most pronounced in high-expenditure sports like ice hockey and American football within the North American market.
Sports Protective Equipment Market Segmentation
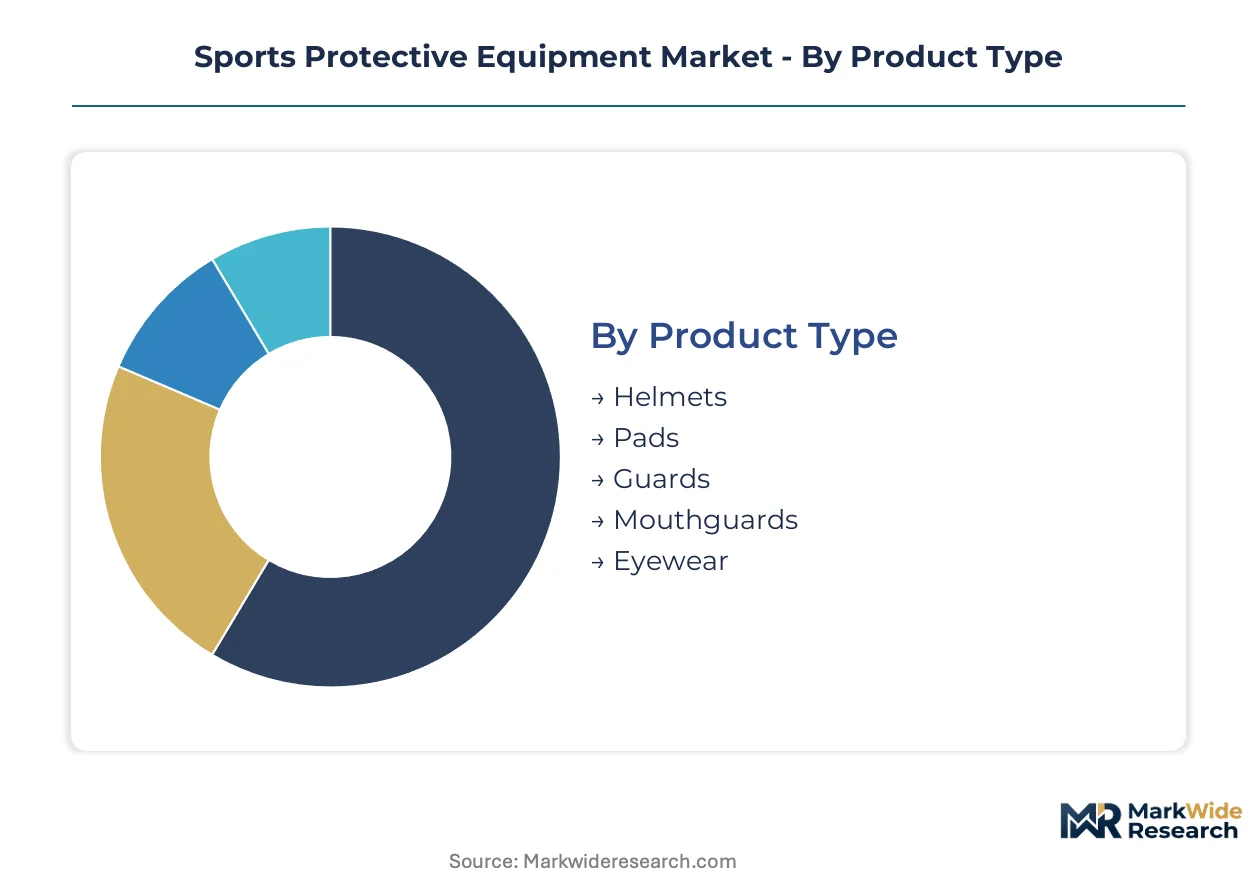
Market segmentation provides a critical framework for understanding the diverse needs and regulatory pressures within the sports protective equipment industry. This granular analysis reveals how product design, material innovation, and distribution strategies must adapt to specific sport requirements and end-user demands, influencing market growth.
Product Type:
The varying regulatory burden across product types significantly influences development costs and market access, with certain equipment categories demanding rigorous testing protocols.
- Helmets:These feature a hard polycarbonate outer shell and an inner layer of energy-absorbing expanded polypropylene (EPP) foam, designed to mitigate head injuries. Demand concentrates in high-contact sports like American football, driven by stringent NOCSAE standards in the United States.
- Pads:Composed of multi-layer EVA foams and advanced textiles, pads provide crucial impact absorption and body protection for various athletic activities. These products see high demand from amateur player participation and sports academies, particularly in sports like football and hockey.
- Guards:This category includes specialized protectors for specific body parts, often incorporating lightweight, flexible materials for targeted impact resistance.
- Mouthguards:Essential for dental protection, mouthguards are widely used in contact sports to prevent oral injuries during collisions.
- Eyewear:Designed to shield eyes from impacts, debris, or UV radiation, protective eyewear is increasingly adopted in racket sports and cycling.
Pads sits at the top of the volume ranking, with Eyewear climbing the fastest.
Material:
Material selection dictates both the performance characteristics and the final cost tier of protective equipment, impacting accessibility for various user segments.
- Polycarbonate:This durable thermoplastic forms the hard outer shells of many helmets and protective gear, offering excellent puncture and impact resistance. Its usage is widespread in products requiring CPSC and CE marking compliance for structural integrity.
- EVA Foam:Expanded ethylene-vinyl acetate foam provides critical energy absorption and cushioning, often used in multi-layer configurations for pads and internal helmet liners. Demand for EVA foam is high in equipment balancing protection with comfort and flexibility.
- Kevlar:Known for its high strength-to-weight ratio, Kevlar is integrated into equipment requiring enhanced cut and abrasion resistance without significant added bulk.
- Neoprene:This synthetic rubber offers flexibility, thermal insulation, and compression, making it suitable for joint supports and comfortable padding.
- Carbon Fiber:A lightweight and extremely stiff composite material, carbon fiber is primarily used in premium, high-performance equipment where weight reduction and structural rigidity are paramount.
Polycarbonate remains foundational for outer shells, while advanced composites like Carbon Fiber are gaining traction in high-performance applications.
Application:
The volume of protective equipment sales directly correlates with participation rates in specific sports, particularly those with high collision risks.
- Football:This application demands comprehensive protective gear, including helmets and pads, designed to meet stringent NOCSAE standards for high-impact collisions. Demand is concentrated in North America, driven by organized leagues and youth sports mandates.
- Cricket:Protective equipment for cricket includes specialized helmets, pads, and guards tailored to protect against fast-moving balls and impacts. Widespread amateur and professional play in countries like India, the UK, and Australia fuels this segment.
- Hockey:Both ice and field hockey require extensive protective equipment, including helmets, shoulder pads, shin guards, and gloves, due to the high-speed nature of the sport.
- Cycling:This category encompasses helmets and various pads for knees and elbows, catering to both recreational riders and competitive cyclists.
- Martial Arts:Specific headgear, gloves, and body protectors are essential for training and competition in various martial arts disciplines, focusing on impact dissipation.
High-contact sports like Football command significant equipment investment, whereas niche applications like Martial Arts offer specialized product opportunities.
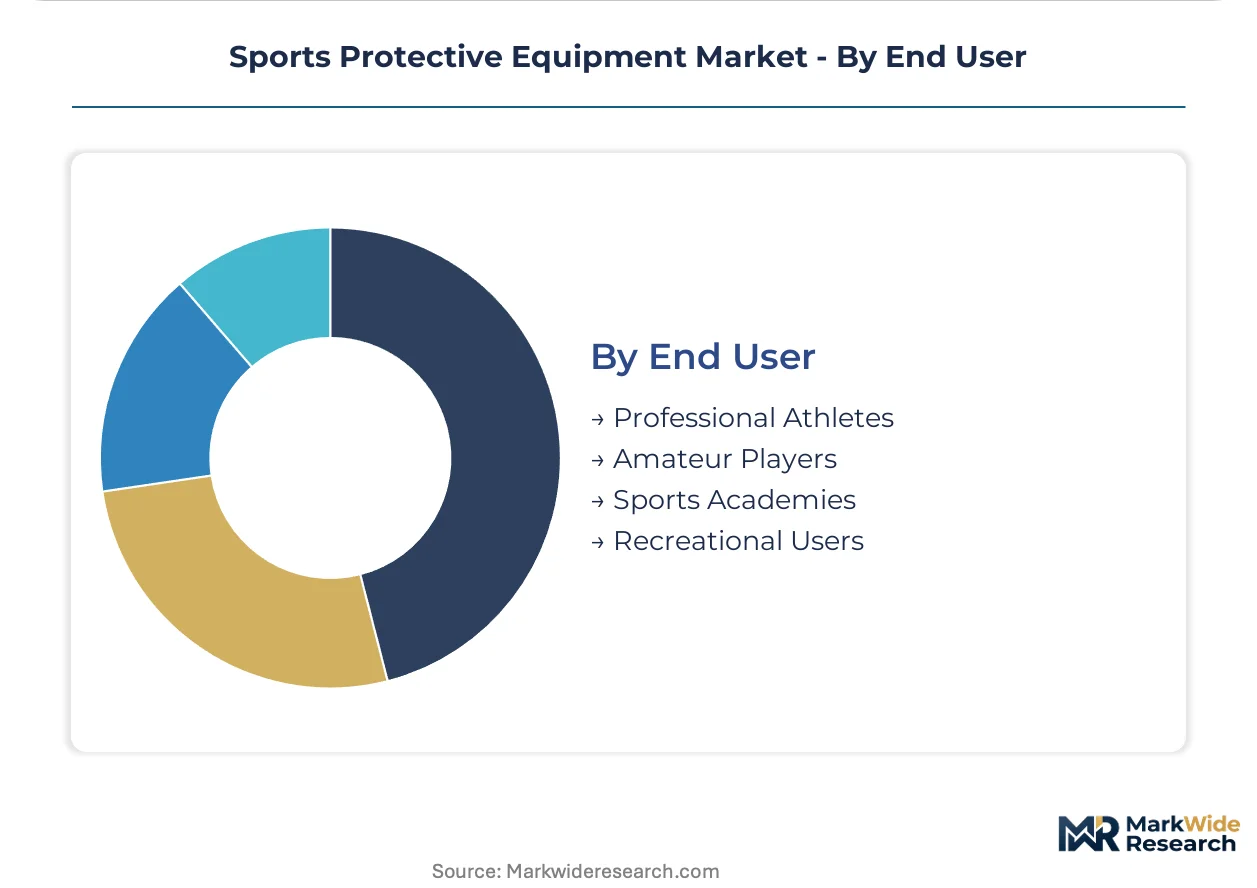
End User:
Different end-user segments exhibit distinct purchasing behaviors and product requirements, ranging from basic safety to elite performance enhancement.
- Professional Athletes:This segment demands custom-fit equipment featuring advanced materials and often integrated sensor technology for performance analytics. Demand is driven by performance optimization, professional sponsorships, and strict league regulations.
- Amateur Players:Amateur players seek durable, comfortable, and affordable protective gear that balances safety with cost-effectiveness for regular participation. High participation rates in organized sports across various age groups drive this volume segment.
- Sports Academies:These institutions prioritize bulk purchasing of durable and multi-user suitable equipment for training and development programs.
- Recreational Users:Individuals in this segment typically look for basic protection, ease of use, and lower price points for casual sporting activities.
The growing base of Amateur Players represents a major volume segment, while Professional Athletes drive innovation in high-performance gear.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The sports protective equipment market found its initial scale in the United States, driven by early organized sports leagues and a strong emphasis on athlete safety. This foundational demand, coupled with material science, has propelled market growth across diverse geographies. Regional regulatory frameworks and participation rates influence product development.
United States
Stringent youth sports safety mandates and high participation rates in American football drive demand for certified helmets and pads. NOCSAE standards dictate rigorous testing protocols for head protection. Collegiate sports programs in regions like the Midwest foster innovation in impact-absorbing materials and integrated sensor technologies.
Germany
European Union directives, including the EU Green Deal and CE marking, shape product design towards sustainable materials and verifiable safety compliance. Bio-based foams and recycled polymers gain traction due to corporate sustainability goals. The Bavarian region, with its strong engineering base, concentrates R&D efforts in advanced composite materials.
India
Increasing disposable incomes and government-led health initiatives fuel participation in organized sports, creating demand for essential protective gear. The Bureau of Indian Standards (BIS) ensures product quality and safety for consumers. Bengaluru, as a technology and manufacturing hub, sees localized production and distribution networks.
Brazil
Government programs promoting physical activity expand the consumer base for protective equipment, particularly in football and martial arts. INMETRO certification guarantees product safety and performance for domestic sales. The São Paulo metropolitan area serves as a primary hub for sports equipment manufacturing and distribution.
Japan
A cultural emphasis on precision engineering and high-performance sports, such as cycling and martial arts, drives demand for advanced protective solutions. Japanese Industrial Standards (JIS) specify quality benchmarks for sports safety equipment. The Tokyo region acts as a center for innovation in lightweight composites and smart sensor integration.
Sports Protective Equipment Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the sports protective equipment market, creating a tiered competitive structure. The market exhibits both consolidation among established brands and fragmentation among specialized innovators. Strategic archetypes include large-scale manufacturers with extensive global supply chains and niche players focusing on advanced materials or integrated smart technology. Dominant competitive moves involve strategic partnerships for technology integration and geographic expansion into emerging markets.
Scale-driven global apparel and footwear brands, including Nike Inc., Adidas AG, and Under Armour Inc., anchor the premium segment of the market. These companies leverage their established brand recognition and extensive distribution networks to introduce sustainable materials and integrate performance analytics into their product lines. They represent the archetype of vertically integrated players with significant in-house R&D capabilities, driving innovation in both material science and smart technology applications for elite athletes.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Amer Sports |
| Puma SE |
| Under Armour Inc. |
| Bauer Hockey |
| MIZUNO Corporation |
| Franklin Sports Inc. |
| ASICS Corporation |
| Others |
Cost & Logistics Intelligence
European Union regulations, including the Corporate Sustainability Reporting Directive (CSRD), gate both qualified supply and premium-tier pricing access for protective equipment manufacturers. This directive compels greater transparency in material sourcing and production processes, influencing the cost structure for compliant products.
Pricing Analysis
Pricing stratifies across premium, standard, and economy tiers, reflecting differing material compositions and certification levels. Quality grade, particularly adherence to NOCSAE standards for helmets and CE marking for all equipment, drives significant price differentiation. Brand premium also allows established manufacturers like Nike Inc. to command higher prices. Cost compression in the amateur and recreational segments intensifies due to the high input costs of performance materials such as carbon fiber and expanded polypropylene (EPP) foam. Recreational users and amateur players exhibit the highest price sensitivity, while professional athletes and collegiate leagues prioritize performance over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical components are becoming more prevalent, particularly for advanced materials where supply chain resilience is paramount. The supply chain draws from manufacturing hubs in China for general components and specialized material production in countries like Germany for advanced composites. Raw material dependencies include polycarbonate for outer shells, EPP foam for impact absorption, and carbon fiber for lightweight rigidity. Commodity price volatility for these performance materials presents a structural risk to cost stability. Distribution predominantly runs through traditional retail channels, specialized sports equipment stores, and increasingly, direct-to-consumer (DTC) platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sports protective equipment market presents a late-cycle quality story, driven by a pronounced demand-shift toward superior impact absorption and integrated smart technologies.
For Market Incumbents: Anchor market leadership by accelerating advanced material R&D, focusing on verifiable bio-based foams and recycled polymers to meet evolving sustainability mandates. Strengthen distribution networks in geographically underpenetrated markets like Southeast Asia to capture developing sports infrastructure. This mitigates threats from certification bottlenecks and high input costs.
For New Entrants and Emerging Players: Online direct-to-consumer platforms offer a viable go-to-market angle for specialized product offerings. Target niche sports categories such as electric scooter racing or competitive drone piloting, where white-space opportunities for novel equipment design exist. Focus on personalized gear, leveraging 3D scanning and bespoke manufacturing for high-expenditure sports within the North American market.
For Investors and Strategic Acquirers: Roll-up economics work for specialized material innovators because the market values proprietary technology and strong intellectual property in protective applications. Long-term viability rests on sustained demand for athlete safety and performance enhancement in organized sports. A key signal to watch is the adoption rate of integrated sensor technology in professional and collegiate leagues, indicating market readiness for intelligent gear.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material R&D | Developing next-generation bio-based foams and recycled polymers ensures compliance with sustainability directives. |
| Geographic Expansion | Establishing early distribution networks in Southeast Asia captures growth from developing sports infrastructure. |
| Smart Technology Integration | Embedding real-time biometric sensors into protective gear offers performance data and enhances athlete safety. |
| Customization Platform Development | Implementing 3D scanning and bespoke manufacturing enables personalized protective equipment solutions. |
| Certification Standard Leadership | Driving new safety testing protocols for emerging sports categories like drone piloting sets market benchmarks. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a comprehensive market understanding. Primary data involved discussions with product development engineers, regulatory compliance officers, sports league officials, and procurement managers at sports academies. Secondary data sources included Consumer Product Safety Commission (CPSC) reports, NOCSAE standards, CE marking directives, company annual reports, and relevant industry journals, all triangulated with bottom-up and top-down analyses.
The forecast window was anchored to historical reference periods, establishing a baseline for future projections across the projection horizon. Our analytical framework modeled segmentation dimensions including product type, material, application, end-user, and regional regulatory frameworks. Compound annual growth rates (CAGRs) were derived from historical trends and projected market drivers, with sports participation rates and material science advancements serving as critical industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to macroeconomic conditions, evolving regulatory landscapes, and technological breakthroughs. Deviation in material innovation or regulatory enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Ice Cleat Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Gymnastic Hoops Market
Sports Equipment
Running Gear Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
North America Stand-Up Paddleboard Market
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Tetherball Market
Sports Equipment
Global Kinesio Tape Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market